
 Endovascular Therapy Devices Market | 2026-2036
Endovascular Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Endovascular Therapy Devices Market Foresight
Aftermarket service revenue is narrowing as original equipment manufacturers bundle multi-year maintenance contracts with initial device sales. Medtronic leverages its integrated cath lab ecosystem to lock in hospital purchasing committees across North American and European accounts. Boston Scientific Corporation sustains R&D intensity in drug-eluting coronary platforms, while Terumo Corporation anchors its position in guidewire and microcatheter specialization across Japanese and Southeast Asian markets.
Endovascular therapy devices are minimally invasive instruments delivered through vascular access to treat arterial and venous pathologies, typically fabricated from nitinol, cobalt-chromium, or polymer substrates and deployed under fluoroscopic or intravascular ultrasound guidance. Their primary purpose is to restore luminal patency or exclude aneurysmal segments without open surgical exposure. Stent platforms command the deepest margin pools due to long-term implant monitoring and repeat intervention economics, while balloon dilatation devices face commoditization pressure from regional manufacturers. Robotic-assisted surgery represents the fastest-growing technology dimension as hospitals seek to standardize procedural outcomes and reduce operator radiation exposure.
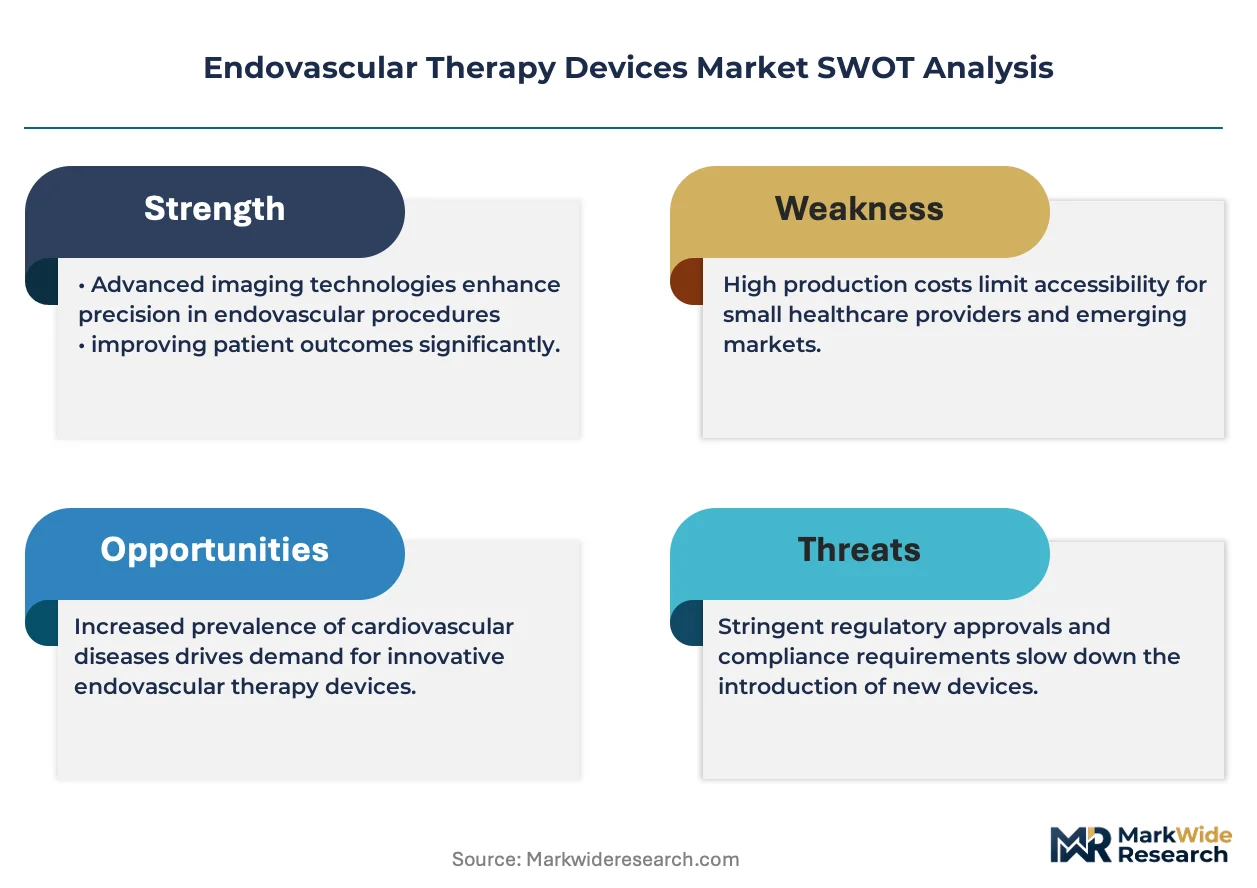
FDA premarket notification and PMA pathways govern US commercialization, while the EU MDR and CE marking requirements impose extended clinical follow-up obligations on stent and graft manufacturers. Japan's PMDA maintains distinct pharmacovigilance reporting standards that shape post-market surveillance investment for multinational suppliers. Stakeholders must monitor reimbursement threshold negotiations between hospital systems and public payers, as these determinations directly influence cath lab capital allocation and procedure scheduling priorities.
Market Dynamics
Hospital consolidation is compressing cath lab procurement cycles as integrated delivery networks negotiate multi-year platform contracts with original equipment manufacturers, shifting purchasing authority from individual physicians to centralized value analysis committees.
Growth Catalysts
- EU MDR clinical follow-up mandates:Extended surveillance obligations for stent graft manufacturers are accelerating investment in post-market data infrastructure, creating competitive moats for established suppliers with robust pharmacovigilance systems.
- Robotic-assisted surgical platforms:Health systems in the United States and Germany are deploying capital for radiation-reducing automation, standardizing procedural outcomes across operator experience levels.
- Aging demographics in Japan:PMDA reimbursement clarity for endovascular aortic repair is expanding procedure volumes among patients over 75 who are ineligible for open surgery.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy fabrication depends on a limited supplier base in the United States and Germany, exposing stent manufacturers to input price volatility and allocation constraints.
- FDA PMA pathway timelines:Novel stent graft submissions require extensive clinical evidence packages that extend development cycles and compress effective patent life before generic competition.
- Drug-eluting balloon commoditization:Regional manufacturers in Southeast Asia are displacing premium-priced devices with functionally equivalent bare-metal alternatives, eroding margin pools in coronary interventions.
Strategic Opportunities
- Underpenetrated venous disease segments:Deep vein thrombosis and chronic venous insufficiency procedures remain below 15% penetration in India and Brazil, offering expansion paths beyond saturated arterial markets.
- AI-enabled procedural planning:Machine learning algorithms for vessel sizing and stent selection are converging with robotic platforms to reduce fluoroscopy time and contrast agent volumes.
- Japan's regenerative medicine framework:PMDA accelerated approval pathways for tissue-engineered vascular grafts create regulatory tailwinds for bioresorbable scaffold development.
Industry Challenges
- Interventionalist training bottlenecks:Complex endovascular procedures require 200+ supervised cases for credentialing, constraining procedure volume growth in markets with limited fellowship programs.
- Legacy PACS integration:Robotic platforms must interface with hospital-specific imaging archives, creating deployment friction and customization costs that delay cath lab commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endovascular Therapy Devices Market |
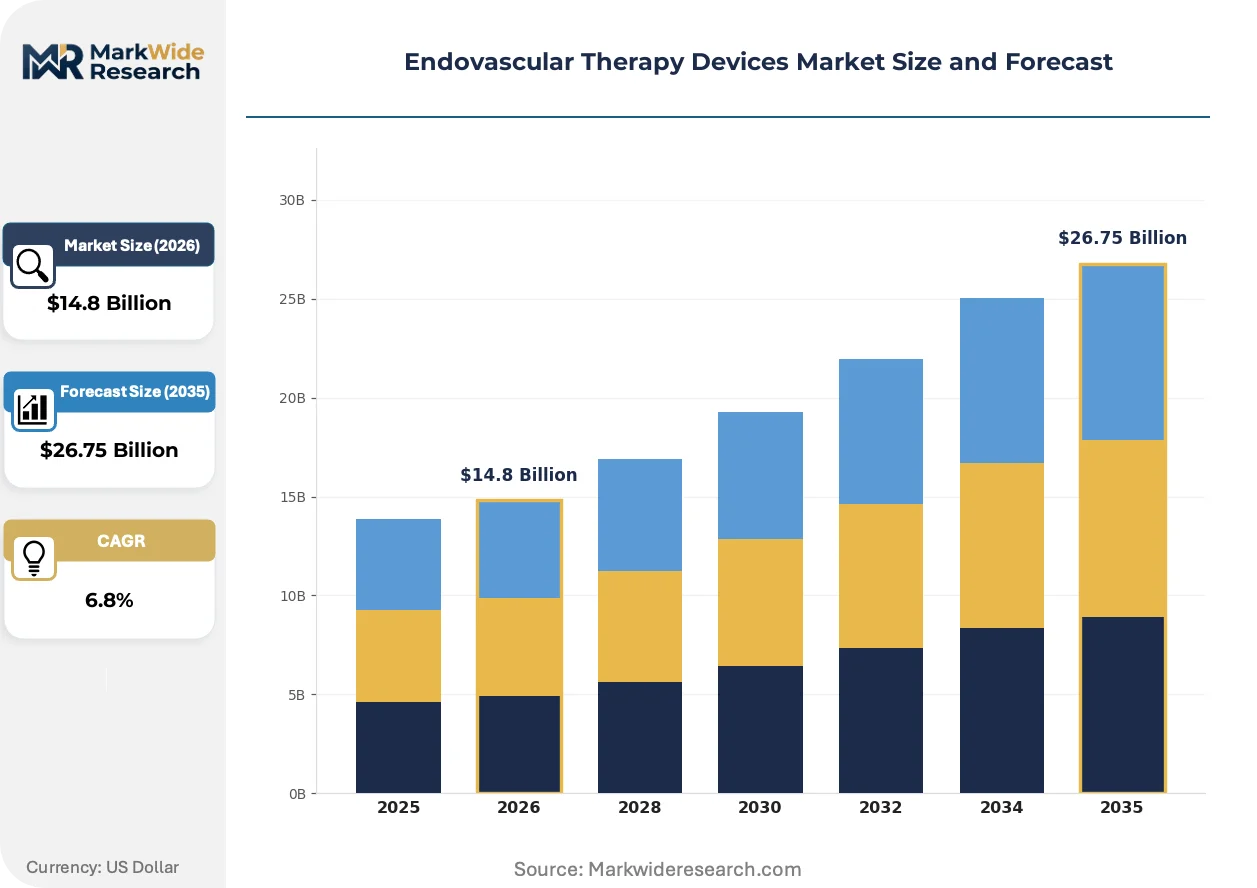
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.75 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Guidewires, Balloon Dilatation Devices Application: Aneurysm Repair, Peripheral Artery Disease, Coronary Artery Disease, Endovenous Laser Therapy End User: Hospitals, Outpatient Facilities, Specialty Clinics, Surgical Centers Technology: Robotic-Assisted Surgery, Imaging Techniques, Drug-Eluting Devices, Minimal-Invasion Techniques |
| Companies Covered | Medtronic, Boston Scientific Corporation, Cardinal Health, Getinge, Terumo Corporation, Penumbra, Lifetech Scientific, Endospan, InspireMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endovascular Therapy Devices Market Shifts & Advancements
Digital integration across the procedural workflow is compressing decision timelines and enabling real-time outcome tracking that reshapes how hospitals evaluate technology investments.
Intravascular ultrasound with integrated artificial intelligence is digitizing vessel assessment by automating lumen border detection and plaque characterization. Academic medical centers in Germany and the United States are deploying these systems for left main coronary interventions where angiographic ambiguity drives adverse events. The technology is digitizing the pre-stenting assessment phase, reducing procedural time and contrast volumes while generating structured data for registry submissions.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for Class III implantable devices by 12-18 months. Notified body capacity constraints in Germany and the Netherlands are creating bottlenecks that favor manufacturers with established quality management systems. Stent graft suppliers are responding by front-loading clinical evidence generation and diversifying notified body relationships across multiple EU member states.
Hospital value analysis committees are consolidating vendor relationships through multi-year enterprise agreements that bundle capital equipment, disposables, and service. Integrated delivery networks in the United States are displacing transactional purchasing with total cost-of-ownership frameworks that penalize device fragmentation. This concentration is most visible in cardiovascular service line management at systems spanning 10+ hospitals, where standardization mandates override individual physician preferences.
Endovascular Therapy Devices Market Segmentation
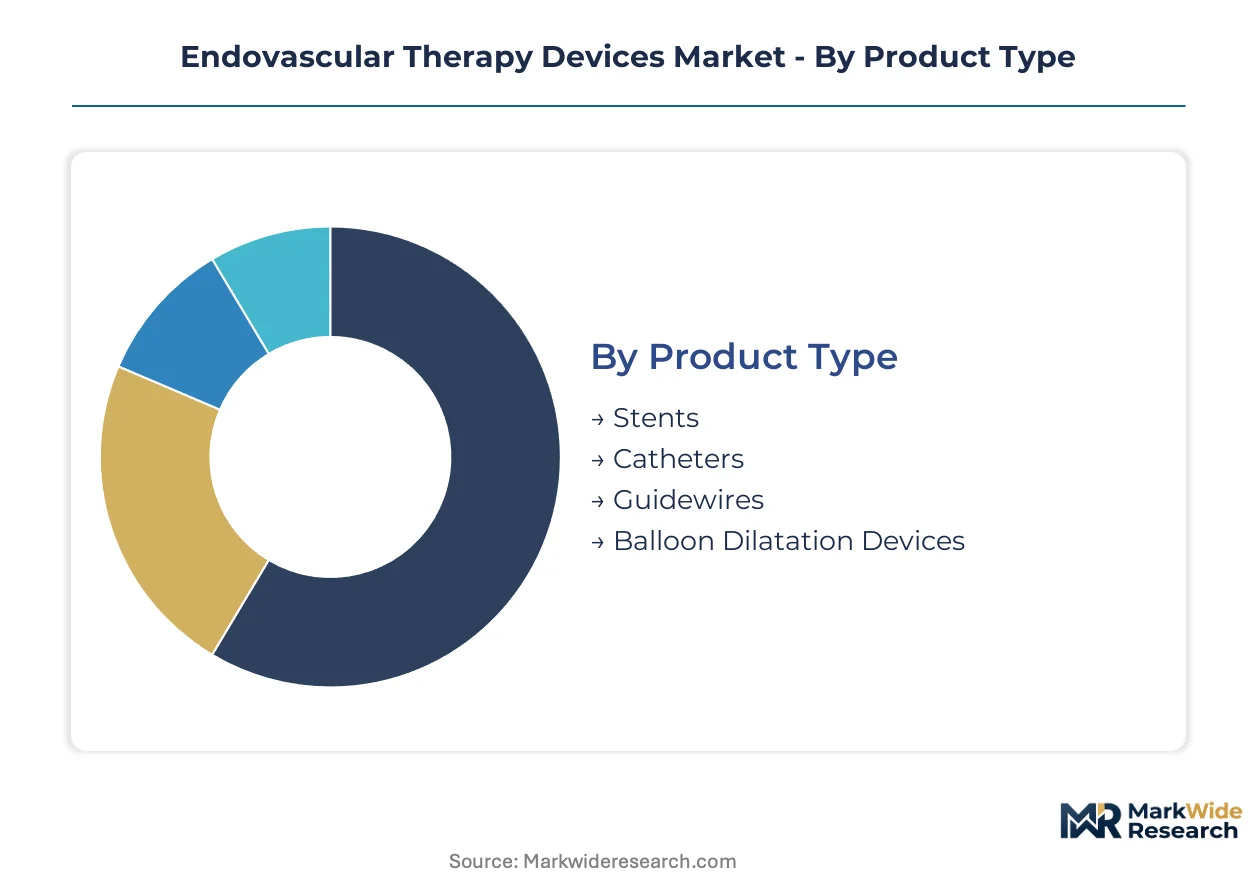
Segmentation in the endovascular therapy devices market reveals how procurement authority, clinical workflow integration, and reimbursement pathways concentrate value across distinct product and customer categories. Hospitals negotiate enterprise contracts that bundle capital equipment with disposables, while outpatient migration and robotic automation reshape where margins accrue.
Product Type:
After-sales service intensity varies sharply across implantable versus disposable categories, with stent platforms demanding long-term surveillance infrastructure and balloon devices requiring minimal technical support.
- Stents:Self-expanding nitinol or balloon-expandable cobalt-chromium scaffolds restore luminal patency in coronary, peripheral, and neurovascular territories. Demand concentrates in the United States and Germany where reimbursement for drug-eluting platforms supports premium pricing, though EU MDR clinical follow-up mandates extend surveillance obligations. By volume, stents lead. By growth pace, robotic-compatible delivery systems are ahead.
- Catheters:Diagnostic and interventional catheters deliver therapeutic agents, embolic materials, or energy sources to target lesions. Japanese and Southeast Asian health systems favor hydrophilic-coated designs for tortuous anatomy, with Terumo Corporation anchoring regional supply relationships.
- Guidewires:Stainless steel or nitinol core wires with hydrophilic or polytetrafluoroethylene coatings enable lesion crossing and device delivery.
- Balloon Dilatation Devices:Semi-compliant and non-compliant balloons predilate lesions or post-dilate stents. Regional manufacturers in Southeast Asia displace premium brands with bare-metal alternatives, eroding margin pools in standard coronary interventions.
Procurement committees weight total cost-of-ownership differently across these categories, favoring bundled contracts for high-service stent platforms while treating balloons as commoditized consumables.
Application:
Clinical indication shapes regulatory pathway complexity and reimbursement certainty, with aortic interventions commanding dedicated DRG codes and venous procedures fighting for coverage recognition.
- Aneurysm Repair:Endovascular stent grafts exclude thoracic and abdominal aortic aneurysms through femoral access. FDA PMA pathways and extended EU MDR timelines favor established suppliers with robust clinical evidence packages.
- Peripheral Artery Disease:Lower extremity revascularization employs drug-coated balloons and self-expanding nitinol stents to treat femoropopliteal and infrapopliteal disease. German and Japanese centers lead adoption of drug-eluting technologies despite mixed pivotal trial outcomes.
- Coronary Artery Disease:Percutaneous coronary intervention remains the highest-volume application, though procedure growth slows in saturated United States and Western European markets.
- Endovenous Laser Therapy:Thermal ablation treats superficial venous reflux and varicose veins. Outpatient facilities in the United States favor 1470nm wavelength systems for reduced bruising and faster recovery.
Aneurysm repair commands the highest average selling prices per procedure, while endovenous laser therapy expands most quickly as ambulatory surgery centers capture lower-acuity venous cases.
End User:
Site-of-care economics determine capital intensity and disposable throughput, with integrated delivery networks consolidating purchasing across hospital networks while outpatient migration fragments volume.
- Hospitals:Academic medical centers and community hospitals house cath labs with fixed angiography systems and robotic platforms. United States health systems negotiate multi-year enterprise agreements that bundle equipment, disposables, and service.
- Outpatient Facilities:Ambulatory surgery centers perform diagnostic catheterization and uncomplicated interventions under Medicare ASC payment rates. Migration accelerates in the United States where site-neutral payment policies create arbitrage opportunities.
- Specialty Clinics:Vein treatment centers and vascular access clinics handle chronic venous insufficiency and dialysis circuit maintenance.
- Surgical Centers:Multi-specialty facilities combine endovascular capabilities with open surgical backup for complicated cases.
Hospitals retain the deepest case mix complexity and capital investment, though outpatient facilities gain share fastest as payers push site-of-care optimization.
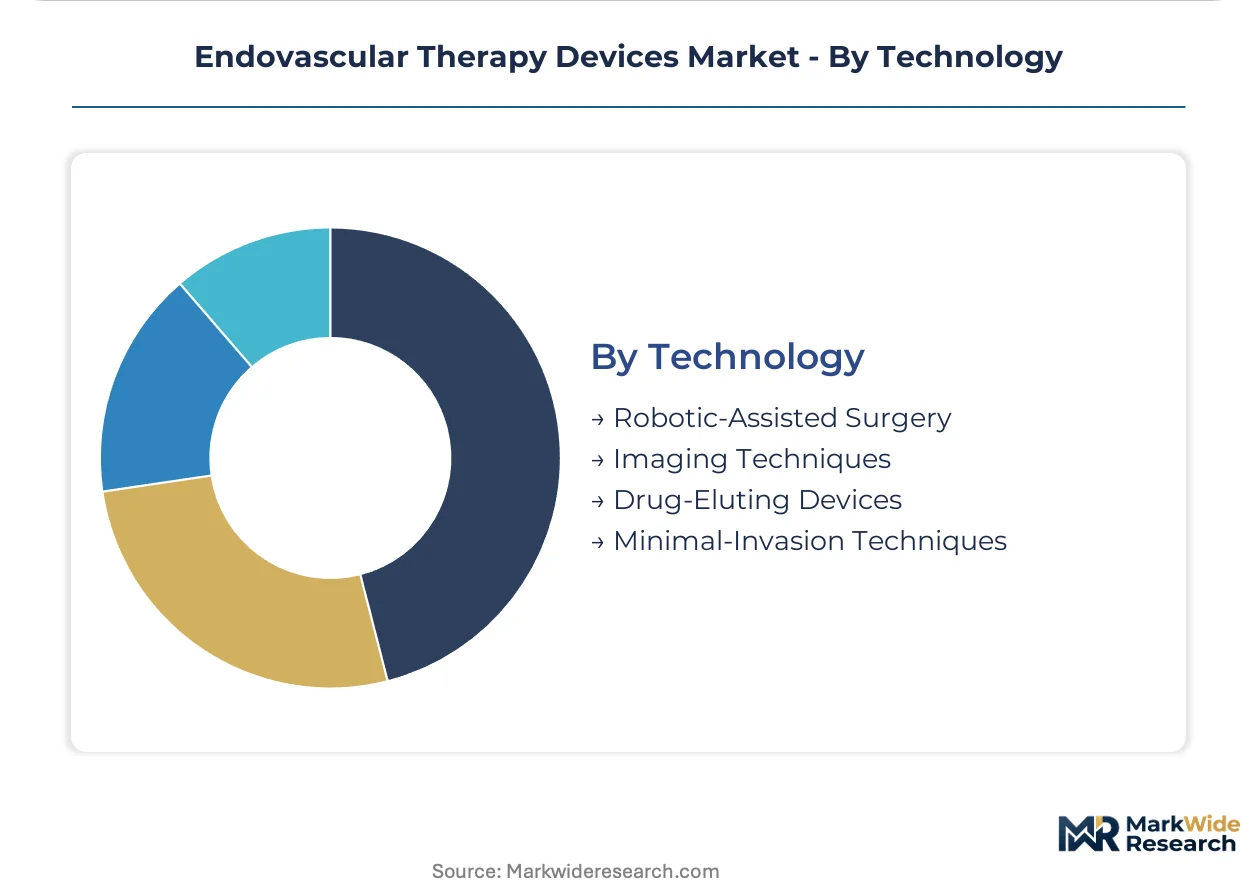
Technology:
Technology tier determines development timeline length and competitive moat durability, with robotic platforms requiring years of regulatory validation and software iteration.
- Robotic-Assisted Surgery:Magnetically steerable catheter systems and mechanical master-slave platforms reduce operator radiation exposure and standardize procedural outcomes. German and United States health systems deploy capital despite uncertain reimbursement.
- Imaging Techniques:Intravascular ultrasound and optical coherence tomography digitize vessel assessment. German centers deploy AI-integrated IVUS for left main interventions where angiographic ambiguity drives adverse events.
- Drug-Eluting Devices:Paclitaxel and sirolimus coatings suppress neointimal hyperplasia in coronary and peripheral applications. Safety signal debates have tempered United States utilization while European adoption continues.
- Minimal-Invasion Techniques:Transradial access and ultrasound-guided vascular closure reduce access site complications and accelerate ambulation.
Imaging techniques penetrate deepest by installed base, yet robotic-assisted surgery climbs the fastest as hospitals seek differentiation and radiation safety compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States health systems absorb premium pricing for robotic platforms while Indian hospitals prioritize cost-engineered bare-metal alternatives. German procurement committees balance clinical evidence requirements against total cost-of-ownership frameworks.
United States
Integrated delivery networks consolidate cath lab purchasing across 10-plus hospital systems, shifting authority from individual physicians to centralized value analysis committees. FDA PMA pathways for novel stent grafts extend development timelines and compress effective patent life. Academic medical centers in Boston and Cleveland deploy capital for robotic-assisted platforms despite uncertain reimbursement codes.
Germany
University hospitals in Munich and Heidelberg lead adoption of AI-integrated intravascular ultrasound for left main coronary interventions. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines by 12-18 months for Class III implantable devices. Notified body capacity constraints in Berlin and Hamburg create bottlenecks favoring manufacturers with established quality management systems.
Japan
PMDA reimbursement clarity for endovascular aortic repair expands procedure volumes among patients over 75 ineligible for open surgery. METI funding for regenerative medicine accelerates development of tissue-engineered vascular grafts under accelerated approval pathways. Tokyo and Osaka medical centers anchor regional demand for hydrophilic-coated catheter designs optimized for tortuous anatomy.
China
NMPA priority review pathways for innovative medical devices shorten registration timelines for domestic manufacturers versus multinational entrants. Provincial procurement consortia in Jiangsu and Guangdong drive price compression for drug-eluting stents through volume-based tendering. Shanghai-based research hospitals pilot robotic catheter systems for radiation exposure reduction.
India
Central government price capping on coronary stents forces manufacturers to absorb margin compression or exit the market. CDSCO streamlined registration for Class C and D devices reduces entry barriers for regional bare-metal balloon manufacturers. Hyderabad and Bangalore emerge as clusters for cost-engineered guidewire production serving Southeast Asian export markets.
Endovascular Therapy Devices Market Competitive Landscape
Integrated cath lab ecosystem providers and specialized component fabricators split the market into distinct competitive spheres. Hospital procurement consolidation favors vendors with multi-year enterprise agreements bundling capital equipment, disposables, and service. Three archetypes dominate: diversified medtech conglomerates with integrated surgical platforms, regional specialists in guidewire and microcatheter technologies, and emerging challengers in cost-engineered bare-metal devices. Competitive moves center on strategic partnerships with health systems and backward integration into nitinol supply chains.
Among diversified medtech conglomerates, Medtronic and Boston Scientific Corporation exemplify the integrated platform archetype. Terumo Corporation anchors the specialized component tier with regional strength in Japanese and Southeast Asian markets. These three entities represent contrasting strategic positions: scale-driven ecosystem lock-in versus focused technical specialization versus geographic niche dominance.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Cardinal Health |
| Getinge |
| Terumo Corporation |
| Penumbra |
| Lifetech Scientific |
| Endospan |
| InspireMD |
| Others |
Supply & Pricing Matrix
Transpacific freight corridors from Shanghai to Los Angeles and Hamburg to Singapore shape landed cost structures for nitinol feedstock and finished stent platforms, concentrating pricing power with German and United States alloy suppliers while forcing Asian manufacturers to absorb logistics premiums or cede margin.
Pricing Analysis
After-sales service contracts spanning multi-year preventive maintenance and software updates generate the dominant lifetime value pools for robotic-assisted surgical platforms. Pricing stratifies across premium drug-eluting stent tiers with embedded surveillance infrastructure, mid-tier bare-metal alternatives, and economy bare balloons from regional Southeast Asian manufacturers. Cost compression in standard coronary balloon segments is intensifying because Indian price caps and Chinese volume-based tendering force margin absorption. Ambulatory surgery centers exhibit the sharpest price sensitivity, while academic medical centers in Germany and the United States prioritize total cost-of-ownership frameworks over unit economics.
Supply Chain Analysis
Nitinol shape-memory alloy feedstock draws from captive melting operations in the United States and Germany, with secondary processing concentrated in Japan for medical-grade wire drawing. Critical dependencies include cobalt-chromium tubing for balloon-expandable platforms, polymer substrates for catheter shafts, and hydrophilic coating chemistries. Single-source vulnerability pervades the nitinol supplier base, where two dominant metallurgical houses control medical-grade specification production. Distribution runs through direct hospital contracting for capital equipment and GPO-aggregated disposables procurement for high-volume consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endovascular therapy devices fragment across arterial, venous, and neurovascular niches as site-of-care migration creates distinct procurement ecosystems for hospitals versus outpatient facilities.
For Market Incumbents: Build pharmacovigilance data moats through EU MDR-mandated post-market surveillance infrastructure that smaller competitors cannot replicate. Consolidate notified body relationships across Berlin, Hamburg, and Amsterdam to preempt conformity assessment bottlenecks. Acquire robotic platform software capabilities to defend against radiation-safety compliance mandates displacing conventional angiography systems. For New Entrants and Emerging Players: Brazilian deep vein thrombosis penetration below fifteen percent offers white-space expansion beyond saturated coronary markets. Target cost-engineered bare-metal balloon production for Southeast Asian export corridors where Indian and Chinese procurement consortia prioritize unit economics over brand premiums. Pursue CDSCO streamlined registration pathways for Class C devices to establish manufacturing beachheads in Hyderabad and Bangalore. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming cardiovascular divisions lacking cath lab ecosystem integration. Long-term viability hinges on robotic-assisted surgery adoption curves and reimbursement code development for AI-enabled procedural planning. Watch FDA PMA approval velocity for novel thoracic stent grafts as an inflection signal for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance opens German and Dutch hospital procurement to Class III implantables. |
| Hospital System Partnership | Multi-year enterprise agreements with United States integrated delivery networks lock in disposable throughput. |
| Software Companion Development | AI-integrated IVUS algorithms reduce fluoroscopy time for left main interventions at Heidelberg and Munich centers. |
| Backward Integration into Nitinol | Captive alloy supply insulates against United States and German supplier price volatility. |
| Reimbursement Strategy | PMDA clarity for endovascular aortic repair expands Japanese volumes among patients over seventy-five. |
Research Methodology
Operator-level perspectives from interventional cardiologists, cath lab directors, hospital value analysis committee members, and GPO contracts managers anchored the qualitative base. These primary insights combined with secondary validation from FDA PMA filings, EU MDR notified body transparency databases, PMDA reimbursement bulletins, and CMS Medicare procedure volume data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Scenario-bracketing framed projections across the analysis window by modeling procedure volume elasticity to reimbursement thresholds, technology adoption S-curves for robotic platforms, and site-of-care migration patterns. Segmentation dimensions included product type, clinical application, end-user facility tier, and technology intensity. CAGRs derived from fitted growth curves applied to base-year market sizing, with cross-checks against capital expenditure cycles for cath lab equipment and regulatory approval pipeline velocities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers leveraging NMPA priority review pathways would shift outcomes through accelerated price competition. Quarterly review of FDA PMA submission backlogs, EU MDR notified body capacity utilization, and PMDA reimbursement schedule updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Lower Limb Arterial Stents Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Cardiac Mapping Systems Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market