
 Germany Cardiovascular Devices Market | 2026-2036
Germany Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Cardiovascular Devices Market Foresight
The capability gap between capital-intensive imaging system manufacturers and commoditized stent producers is unwinding as reimbursement shifts toward outcome-based hospital payments. Edwards Lifesciences anchors its position through deep specialization in transcatheter heart valve technologies. Medtronic PLC leverages integrated electrophysiology platforms to sustain pricing power across arrhythmia treatment workflows. Siemens Healthineers dominates diagnostic imaging supply to cardiac catheterization laboratories throughout Bavaria and Baden-Württemberg.
Germany cardiovascular devices encompass implantable and interventional instruments engineered from cobalt-chromium alloys, nitinol, and biocompatible polymers, typically requiring Class III CE marking under EU Medical Device Regulation for permanent blood contact applications. These devices restore hemodynamic function through mechanical support, electrical rhythm management, or vascular patency maintenance. Stent and catheter segments face margin compression from tender-based hospital procurement, while cardiac monitor and imaging system categories retain stronger pricing through software-integrated service contracts. Biodegradable device technology represents an emerging structural priority as clinicians seek to reduce long-term implant burden in younger coronary artery disease patients.
BfArM coordinates post-market surveillance alongside notified bodies conducting EU MDR conformity assessments, extending clinical evidence requirements for legacy device approvals. Germany's national hospital reimbursement framework through the Institute for the Hospital Remuneration System shapes adoption velocity for innovative cardiovascular interventions. Stakeholders must monitor emerging DiGA pathways for digital cardiovascular monitoring applications and evolving G-BA benefit assessments for transcatheter procedures.
Market Dynamics
The convergence of EU MDR clinical evidence requirements with Germany's DiGA reimbursement pathway is restructuring competitive positioning around software-integrated cardiovascular platforms rather than standalone hardware.
Growth Catalysts
- EU MDR Class III pathway acceleration:BfArM-coordinated conformity assessments are compressing approval timelines for cobalt-chromium implantables with robust clinical dossiers.
- Cardiac surgery center expansion:University hospital clusters in North Rhine-Westphalia are scaling catheterization laboratory procurement through consolidated tender frameworks.
- Nitinol-based transcatheter platforms:Shape-memory alloy engineering enables minimally invasive valve replacement procedures in aging patient populations.
Market Restraints
- Platinum-iridium electrode cost volatility:Precious metal input pricing swings compress margins for pacemaker and ICD manufacturers.
- Notified body capacity concentration:EU MDR technical documentation review queues extend market access timelines for novel bioresorbable stent entrants.
- Biodegradable polymer degradation uncertainty:Long-term scaffold integrity data gaps limit coronary intervention adoption in younger demographics.
Strategic Opportunities
- Digital therapeutics integration:DiGA reimbursement pathways enable remote cardiac monitoring applications to capture ambulatory care budgets.
- Baden-Württemberg manufacturing densification:Precision engineering clusters around Stuttgart offer captive nitinol processing capabilities.
- AI-augmented electrophysiology mapping:Machine learning algorithm integration with catheter ablation systems creates outcome-based pricing leverage.
Industry Challenges
- Electrophysiologist training pipeline constraints:Complex ablation procedure skill scarcity limits throughput expansion in tertiary centers.
- Legacy imaging system interoperability:PACS integration complexity with new catheterization laboratory equipment extends installation cycles.
- EU MDR post-market surveillance documentation:Periodic safety update report requirements strain regulatory affairs bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Cardiovascular Devices Market |
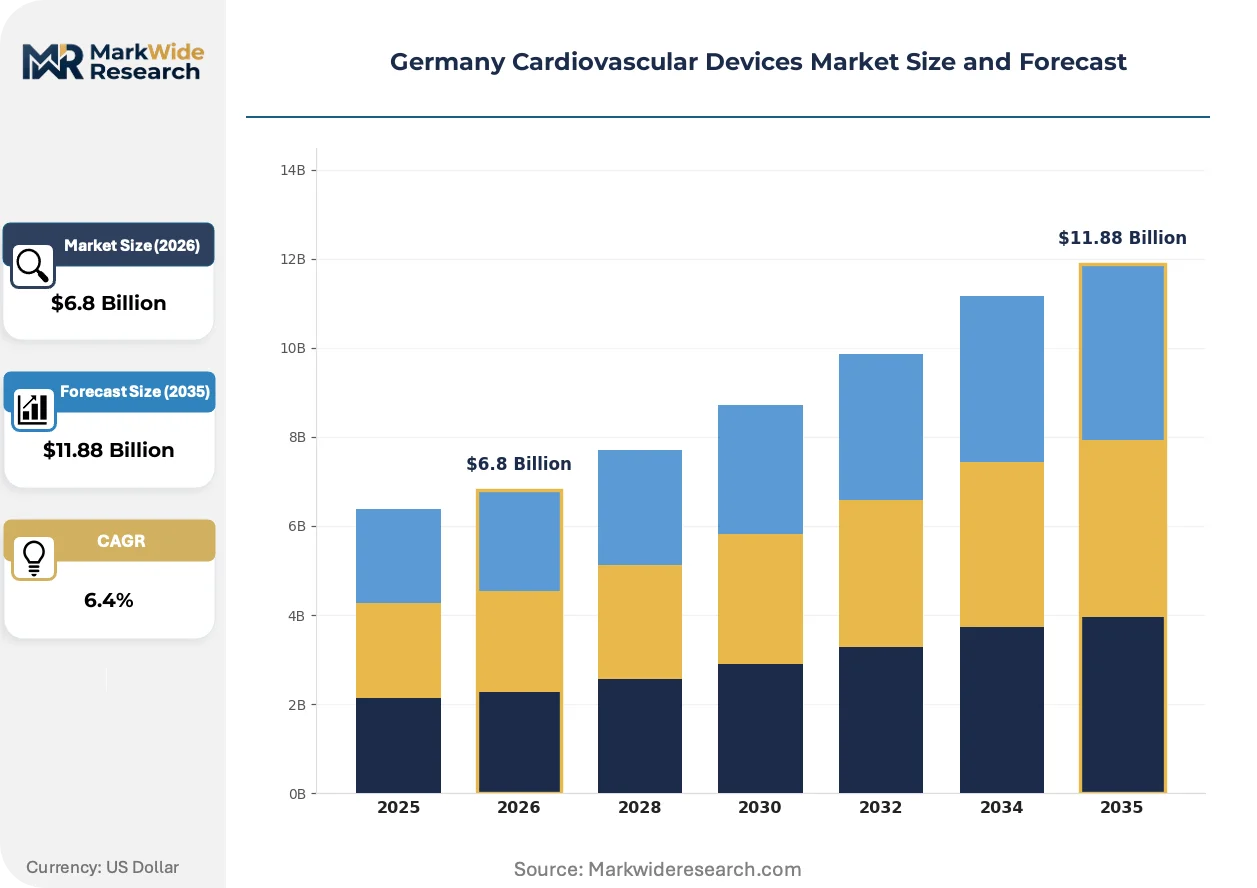
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Heart Valves, Cardiac Monitors Application: Arrhythmia Treatment, Coronary Artery Disease, Heart Failure, Valvular Disease, Peripheral Vascular Disease End User: Cardiac Surgery Centers, Diagnostic Laboratories, Specialty Clinics, Rehabilitation Centers, Research Institutes Technology: Balloon Angioplasty, Electrotherapy, Imaging Systems, Biodegradable Devices, Wireless Monitoring |
| Companies Covered | Edwards Lifesciences, B. Braun Melsungen, Medtronic PLC, Johnson & Johnson, Cardinal Health Inc, Abbott Laboratories, BIOTRONIK, Siemens Healthineers, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Cardiovascular Devices Market Shifts & Advancements
Bioresorbable scaffold engineering and AI-integrated diagnostic platforms are restructuring how hemodynamic interventions are delivered, reimbursed, and monitored across German hospital networks.
Bioresorbable polymer coronary scaffolds degrade within 24-36 months after restoring vessel patency. Interventional cardiologists at Charité Berlin and Heidelberg University Hospital are piloting these platforms in patients under 60. Metallic drug-eluting stent dominance is supplanting as payers prioritize implant-free long-term outcomes.
EU MDR Article 61 clinical evaluation requirements now mandate systematic literature reviews for legacy device renewals. BfArM coordinates with notified bodies to enforce equivalence thresholds for predicate device claims. High-risk implantable manufacturers face compressed timelines to generate prospective registry data.
Hospital procurement consortia in Bavaria and North Rhine-Westphalia are unbundling imaging hardware from software service contracts. Cardiac catheterization laboratory directors now negotiate predictive maintenance and AI analytics separately from capital equipment. This pattern concentrates vendor selection power within centralized purchasing committees.
Germany Cardiovascular Devices Market Segmentation
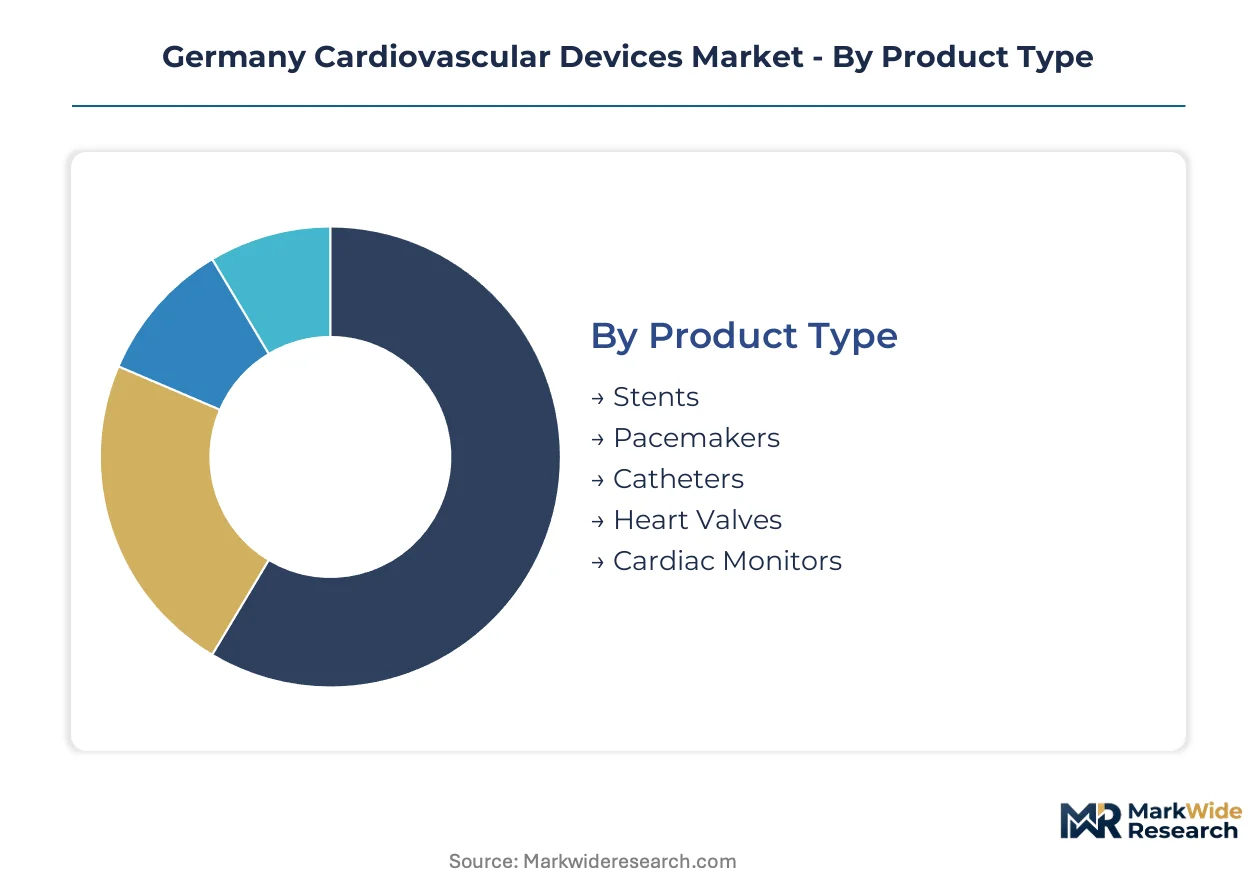
Cardiovascular device procurement in Germany channels through distinct pathways shaped by reimbursement tier, procedure complexity, and hospital procurement consortium leverage. Segment performance diverges sharply between capital-intensive imaging platforms and commoditized implantables facing tender-based margin compression.
Product Type:
Distribution runs through three distinct channels: university hospital tenders for premium implantables, outpatient procurement frameworks for diagnostic equipment, and G-BA reimbursement pathways for chronic therapy devices.
- Stents:Cobalt-chromium and nitinol platforms with drug-eluting polymer coatings restore coronary patency. Demand concentrates in North Rhine-Westphalia catheterization laboratories where procedure volumes exceed national averages by substantial margins, though tender-based procurement compresses manufacturer margins.
- Pacemakers:Platinum-iridium electrode systems with lithium-iodine batteries manage bradyarrhythmia through transvenous implantation. Charité Berlin and Heidelberg University Hospital drive adoption of MRI-conditional devices, with reimbursement tied to G-BA benefit assessments for dual-chamber systems.
- Catheters:Diagnostic and interventional catheters navigate vascular anatomy for angiography and ablation procedures.
- Heart Valves:Mechanical and biological prostheses replace diseased native valves through surgical or transcatheter approaches.
- Cardiac Monitors:Implantable loop recorders and external telemetry systems capture arrhythmia episodes for diagnostic confirmation.
Stents dominate installed base volume. Cardiac monitors represent where expansion concentrates fastest as ambulatory reimbursement frameworks mature.
Application:
Cost tier stratification separates acute intervention reimbursement from chronic disease management budgets within Germany's DRG hospital payment system.
- Arrhythmia Treatment:Catheter ablation and device-based rhythm management address atrial fibrillation and ventricular tachycardia. Bavarian electrophysiology centers report throughput constraints from specialist training pipeline limitations, creating waitlist backlogs for complex procedures.
- Coronary Artery Disease:Percutaneous coronary intervention with stent deployment restores myocardial perfusion. Baden-Württemberg interventional cardiology programs prioritize bioresorbable scaffold evaluation in younger patient cohorts seeking implant-free long-term outcomes.
- Heart Failure:Cardiac resynchronization therapy and mechanical circulatory support address systolic dysfunction progression.
- Valvular Disease:Surgical and transcatheter valve replacement corrects stenosis and regurgitation lesions.
- Peripheral Vascular Disease:Endovascular revascularization targets lower extremity ischemia through femoropopliteal intervention.
Coronary artery disease commands the largest procedure volume. Arrhythmia treatment is climbing the fastest as aging demographics expand the atrial fibrillation patient pool.
End User:
Customer type determines contract structure, with consolidated tenders from hospital networks contrasting individual clinic procurement for specialized diagnostic services.
- Cardiac Surgery Centers:Tertiary hospitals perform open-heart procedures and complex hybrid interventions. University hospital clusters in North Rhine-Westphalia leverage procurement scale through centralized purchasing committees, unbundling imaging hardware from software service contracts.
- Diagnostic Laboratories:Independent and hospital-affiliated labs process cardiac biomarkers and functional tests. Bavarian laboratory networks are consolidating under regional health authority frameworks, standardizing analyzer platforms and reagent supply agreements.
- Specialty Clinics:Ambulatory cardiology practices deliver diagnostic workup and stable patient management.
- Rehabilitation Centers:Post-acute facilities provide cardiac recovery programs and secondary prevention.
- Research Institutes:Academic centers conduct clinical trials and device evaluation studies.
Cardiac surgery centers anchor capital equipment demand. Specialty clinics represent where DiGA reimbursement pathways are unlocking digital monitoring expansion.
Technology:
Supply concentration varies by technology maturity, with established imaging platforms consolidating vendor relationships while biodegradable device manufacturing remains geographically dispersed.
- Balloon Angioplasty:Percutaneous transluminal angioplasty with compliant and non-compliant balloons predilates lesions before stent deployment. Stuttgart-area precision engineering clusters supply nitinol processing capabilities for advanced balloon catheter platforms.
- Electrotherapy:Pacemaker, ICD, and CRT systems deliver electrical rhythm management through transvenous leads. BfArM-coordinated EU MDR conformity assessments are compressing approval timelines for next-generation devices with robust clinical dossiers.
- Imaging Systems:Angiography, intravascular ultrasound, and optical coherence tomography guide intervention precision.
- Biodegradable Devices:Polymer scaffolds degrade after temporary vascular support function.
- Wireless Monitoring:Bluetooth and cellular-connected devices transmit ambulatory cardiac data.
Electrotherapy systems dominate implantable device revenue. Wireless monitoring is gaining share fastest as DiGA pathways integrate remote patient management into standard care workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across German states, with Bavarian university hospitals exhibiting lowest price sensitivity for integrated imaging platforms while North Rhine-Westphalia tender frameworks drive aggressive commoditization of stent and catheter segments.
Bavaria
Electrophysiology throughput constraints at Munich and Erlangen tertiary centers create procedure waitlists extending 8-12 weeks. BfArM coordinates EU MDR conformity assessments for next-generation cardiac rhythm devices through notified bodies headquartered in the state. Siemens Healthineers anchors diagnostic imaging supply to catheterization laboratories across Munich, Nuremberg, and Regensburg hospital networks.
North Rhine-Westphalia
University hospital clusters in Cologne, Düsseldorf, and Essen consolidate procurement through centralized purchasing committees unbundling hardware from service contracts. The Institute for the Hospital Remuneration System shapes adoption velocity for innovative interventions through DRG classification updates. Aachen and Dortmund manufacturing zones supply precision nitinol processing for transcatheter valve platforms.
Baden-Württemberg
Stuttgart-area precision engineering clusters offer captive shape-memory alloy capabilities reducing lead times for advanced catheter platforms. G-BA benefit assessments for transcatheter procedures determine reimbursement thresholds across Mannheim and Heidelberg interventional cardiology programs. Freiburg University Hospital pilots bioresorbable scaffold evaluation in younger coronary artery disease cohorts seeking implant-free outcomes.
Berlin-Brandenburg
Charité Berlin drives MRI-conditional pacemaker adoption through dual-chamber system evaluations tied to statutory health insurance reimbursement. DiGA reimbursement pathways for digital cardiovascular monitoring applications unlock ambulatory care budget capture across Brandenburg specialty clinic networks. The BfArM headquarters coordinates post-market surveillance documentation requirements for legacy device renewals.
Lower Saxony
Hanover and Göttingen cardiac surgery centers scale hybrid operating room procurement for complex structural heart interventions. Regional hospital procurement consortia standardize analyzer platforms for cardiac biomarker processing across laboratory networks. Wolfsburg and Braunschweig precision manufacturing zones supply cobalt-chromium alloy components for coronary stent platforms.
Germany Cardiovascular Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated electrophysiology and imaging platform specialists commanding premium pricing while commoditized stent and catheter manufacturers face tender-based margin compression. The vendor base stratifies across three tiers: multinational conglomerates with diversified cardiovascular portfolios, mid-scale specialists concentrated in single therapeutic areas, and regional contract manufacturers supplying precision alloy components. Dominant competitive moves include backward integration into nitinol processing capabilities and strategic partnerships securing DiGA pathway access for remote monitoring applications.
Among diversified multinational participants, Edwards Lifesciences, Medtronic PLC, and Siemens Healthineers occupy positions exemplifying distinct strategic archetypes. Edwards Lifesciences represents deep specialization in transcatheter structural heart interventions. Medtronic PLC exemplifies integrated electrophysiology and cardiac rhythm management platform breadth. Siemens Healthineers anchors diagnostic imaging supply relationships with catheterization laboratory networks across German hospital systems.
| Leading Market Players |
|---|
| Edwards Lifesciences |
| B. Braun Melsungen |
| Medtronic PLC |
| Johnson & Johnson |
| Cardinal Health Inc |
| Abbott Laboratories |
| BIOTRONIK |
| Siemens Healthineers |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Long-term service contracts with predictive maintenance clauses lock in catheterization laboratory access while stabilizing revenue visibility for imaging system vendors across Bavarian and North Rhine-Westphalia hospital networks. These bundled arrangements concentrate pricing power with manufacturers holding proprietary software analytics, while commoditized implantable producers face tender-based compression.
Pricing Analysis
After-sales service revenue tiers including predictive maintenance contracts and AI analytics subscriptions drive lifetime value for diagnostic imaging platforms. Three-tier pricing structure across premium, standard, and economy levels separates vendors with proprietary software ecosystems from hardware-only suppliers. Cost compression in stent and catheter segments is intensifying because hospital procurement consortia unbundle device specifications from service bundles. Academic medical centers exhibit lowest price sensitivity for integrated electrophysiology platforms, while regional hospitals drive aggressive commoditization of bare-metal stent categories.
Supply Chain Analysis
Strategic stockpiling of platinum-iridium electrodes and cobalt-chromium alloy feedstock mitigates precious metal price volatility for rhythm device manufacturers. Nitinol shape-memory alloy supply concentrates in Germany, United States, and Japan, with Stuttgart-area precision engineering clusters offering captive processing capabilities. Raw material dependencies include cobalt-chromium alloys, nitinol wire, and biocompatible polymer coatings for drug-eluting platforms. Single-source vulnerability in notified body technical documentation review creates regulatory access bottlenecks for novel bioresorbable entrants. Distribution runs through university hospital tender frameworks for premium implantables and GPO contracts for diagnostic equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers must defend against substitution from bioresorbable scaffold platforms that promise implant-free long-term outcomes in younger coronary artery disease cohorts.
For Market Incumbents: Secure backward integration into nitinol processing capabilities to reduce lead times for transcatheter valve platforms. Deepen software-analytics bundling with imaging hardware to create switching costs against emerging AI-augmented competitors. Bioresorbable scaffold substitution threatens metallic drug-eluting stent franchises in under-60 patient segments. For New Entrants and Emerging Players: Lead with DiGA-compliant remote cardiac monitoring applications targeting Brandenburg specialty clinic networks where ambulatory reimbursement pathways are maturing fastest. White-space concentrates in wireless monitoring for post-ablation arrhythmia surveillance and AI-integrated electrophysiology mapping systems. Partner with university hospital pilot programs to generate registry data for EU MDR equivalence claims. For Investors and Strategic Acquirers: Mid-scale electrophysiology specialists with proprietary catheter ablation platforms represent compelling acquisition targets as procedure volume constraints create consolidation pressure. Long-term viability hinges on navigating EU MDR clinical evidence requirements and securing G-BA reimbursement for transcatheter interventions. Watch electrophysiologist training pipeline expansion rates as inflection indicator for throughput-constrained Bavarian centers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Pathway Acceleration | BfArM-coordinated conformity assessments compress timelines for cobalt-chromium implantables with robust clinical dossiers. |
| DiGA Reimbursement Strategy | Digital therapeutics integration captures ambulatory care budgets across Brandenburg specialty clinic networks. |
| Hospital System Partnership | University hospital clusters in North Rhine-Westphalia consolidate procurement through centralized purchasing committees. |
| Software Companion Development | AI-augmented electrophysiology mapping creates outcome-based pricing leverage against hardware-only competitors. |
| Backward Integration Initiative | Captive nitinol processing capabilities in Stuttgart-area clusters reduce lead times for transcatheter platforms. |
Research Methodology
A standing panel of interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from BfArM device registrations, G-BA benefit assessment documents, hospital procurement databases, and EU MDR notified body technical documentation. Bottom-up demand modeling across stent, pacemaker, catheter, and imaging system categories was triangulated with top-down market sizing from statutory health insurance reimbursement data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology maturity tier alongside regional procurement consortium leverage. CAGRs were derived from procedure volume trajectories, reimbursement framework evolution, and technology substitution elasticity. Industry-specific forecast inputs incorporated EU MDR approval timelines and DiGA pathway maturation rates.
Forecasts assume regulatory continuity in EU MDR and G-BA frameworks; material policy shifts would require re-modeling. Revision becomes warranted when notified body capacity constraints or bioresorbable scaffold long-term data thresholds cross critical adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
North America Vascular Graft Market