
 Arteriotomy Closure Devices Market | 2026-2036
Arteriotomy Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Arteriotomy Closure Devices Market Analysis
Asset-light leasing models for cath lab equipment is narrowing the capital barrier for mid-size hospitals entering the vascular closure space. Abbott Laboratories leverages its integrated vascular portfolio to sustain catheter lab loyalty across multiple procedure types. Terumo Corporation anchors its position through specialized hemostasis technology that dominates Japanese interventional suites. Medtronic competes by extending its structural heart reach into peripheral vascular workflows.
Arteriotomy closure devices mechanically or biologically seal femoral or radial arterial punctures following catheterization, typically incorporating collagen plugs, suture-mediated systems, or nitinol clip mechanisms designed to achieve hemostasis within minutes. These instruments serve the essential commercial purpose of reducing time-to-ambulation, minimizing access-site complications, and enabling same-day discharge in diagnostic and interventional cardiology. Mechanical devices occupy the largest revenue pool given established reimbursement and broad physician familiarity, while biodegradable systems represent the fastest-expanding segment as hospitals prioritize bioabsorbable implants that eliminate permanent foreign body retention. Deployment through ambulatory surgical centers is accelerating as outpatient-based labs capture share from traditional hospital settings.
The FDA's 510(k) clearance framework governs Class II vascular closure system submissions in the United States, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for European market access. Japan's PMDA maintains distinct pharmacovigilance reporting standards that influence post-market surveillance obligations for hemostasis device manufacturers. Stakeholders must monitor evolving reimbursement thresholds for same-day discharge protocols and the shifting site-of-service economics between hospitals and freestanding cardiac clinics.
Market Dynamics
Hospital cath labs are consolidating purchasing power around integrated vascular platforms that bundle closure devices with diagnostic catheters, forcing standalone closure manufacturers to defend reimbursement slots through outcome guarantees rather than device pricing alone.
Growth Catalysts
- FDA 510(k) pathway acceleration:The streamlined premarket notification process for Class II vascular closure systems compresses time-to-market for iterative device improvements, encouraging incremental innovation in suture-mediated and clip-based mechanisms.
- Radial access adoption:Transradial catheterization protocols are expanding procedure volumes in interventional cardiology suites, creating parallel demand for specialized radial closure devices optimized for smaller arterial diameters.
- Same-day discharge mandates:Medicare reimbursement incentives for outpatient cardiac procedures are pulling closure device selection toward technologies that demonstrably reduce time-to-hemostasis below 15 minutes.
Market Restraints
- Collagen plug material concentration:Bovine-derived collagen supply chains concentrate in specific agricultural processing regions, exposing manufacturers to input volatility from livestock disease outbreaks and export restrictions.
- Japan PMDA pharmacovigilance burden:Post-market surveillance requirements for hemostasis devices impose ongoing clinical data collection obligations that elevate compliance costs for market participants.
- Manual compression substitution:Low-cost manual compression remains the default closure method in price-sensitive healthcare systems, particularly where labor costs suppress the economic case for device-mediated closure.
Strategic Opportunities
- India CDSCO emerging pathway:The country's medical device regulatory framework is formalizing quality standards for vascular closure products, creating first-mover advantage for manufacturers establishing local clinical evidence.
- Bioresorbable polymer convergence:Combining polylactic acid scaffolds with active hemostatic agents addresses the foreign body retention concern that limits long-term outcomes in permanent implant systems.
- Ambulatory surgical center channel expansion:Freestanding cardiac catheterization labs are capturing procedural volume from hospital-based suites, requiring device portfolios optimized for lower-acuity settings with reduced support staff.
Industry Challenges
- Interventional cardiology fellowship pipeline:Training program capacity constraints limit the supply of physicians proficient in both femoral and radial access techniques, creating regional bottlenecks in procedure throughput.
- EU MDR technical documentation burden:The Medical Device Regulation's clinical evidence requirements for Class IIa vascular closure systems extend certification timelines and elevate documentation costs for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arteriotomy Closure Devices Market |
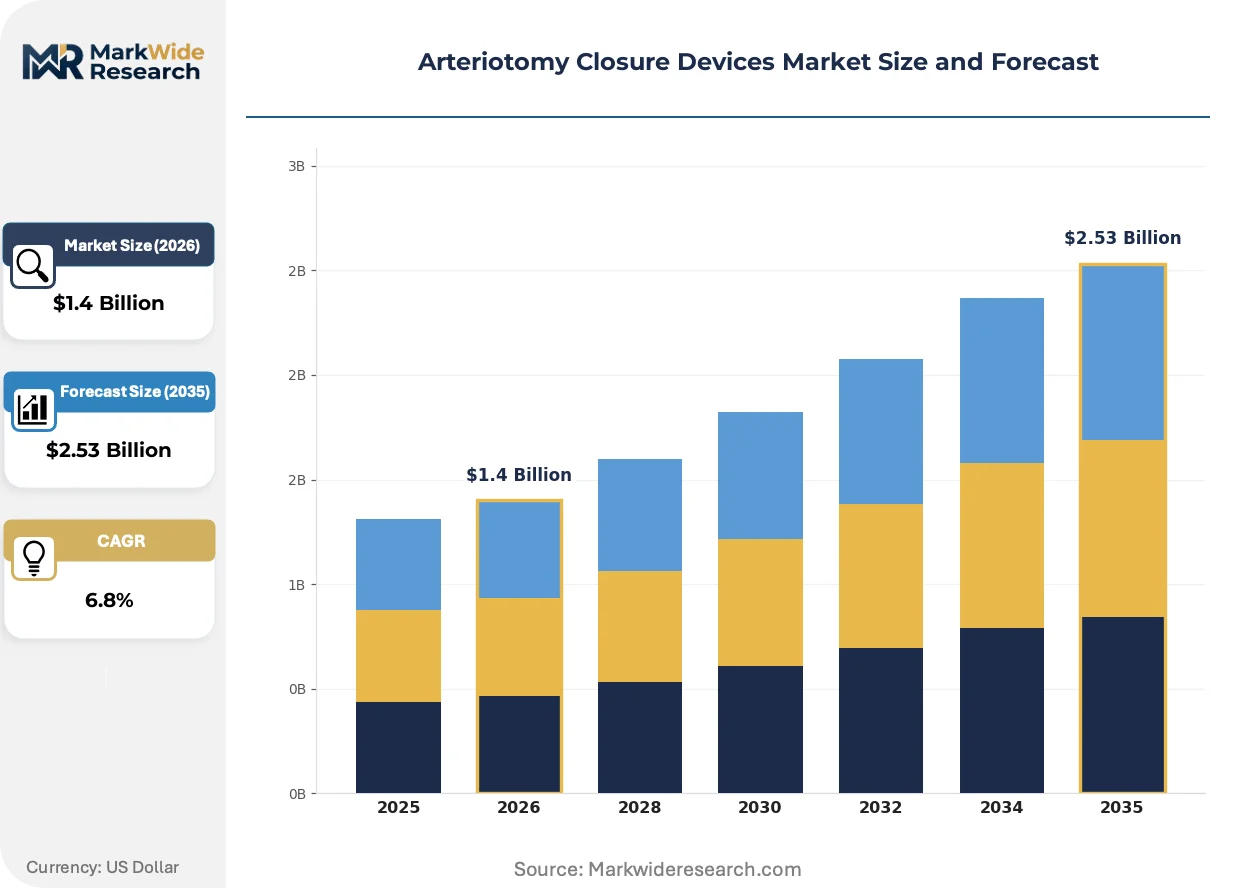
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Devices, Biodegradable Devices, Sutures, Sealants End User: Hospitals, Ambulatory Surgical Centers, Cardiac Clinics, Urgent Care Facilities Deployment: In-Hospital, Outpatient, Mobile Clinics, Home Healthcare Application: Cardiology, Radiology, Vascular Surgery, Interventional Procedures |
| Companies Covered | Abbott Laboratories, Terumo Corporation, Medtronic, Cardinal Health, Teleflex Incorporated, Haemonetics Corporation, Merit Medical Systems, Boston Scientific Corporation, Cardiva Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arteriotomy Closure Devices Market Emerging Trajectories
Active closure mechanisms are converging with bioresorbable materials to eliminate permanent implants, while regulatory frameworks on three continents simultaneously tighten post-market surveillance and streamline premarket pathways.
Suture-mediated vascular closure systems are hybridizing with bioabsorbable anchor components that dissolve within 90 days, eliminating the chronic inflammation risks associated with permanent nitinol clips. Academic medical centers in Germany and the United States are piloting these hybrid platforms in high-volume transcatheter aortic valve replacement programs. The structural consequence is compression of the pure mechanical device segment as hospitals prioritize implant-free healing trajectories.
The European Union's Medical Device Regulation imposes stricter clinical evidence requirements for vascular closure systems seeking CE marking, mandating post-market clinical follow-up studies that extend regulatory timelines by 12-18 months. Manufacturers are responding by front-loading clinical trials in Germany and France to generate the robust safety datasets required for MDR compliance. Small and mid-cap device developers without existing European revenue streams face disproportionate capital requirements to satisfy these evidentiary thresholds.
Hospital procurement committees are consolidating vascular closure purchasing into multi-year enterprise agreements that bundle closure devices with diagnostic catheters and guidewires from preferred suppliers. Independent cath labs and mid-size hospital systems are ceding negotiating leverage to integrated device vendors that can span the full procedure workflow. This concentration is most visible in the United States, where health system mergers have reduced the number of independent purchasing entities by roughly half over the past decade.
Arteriotomy Closure Devices Market Segmentation
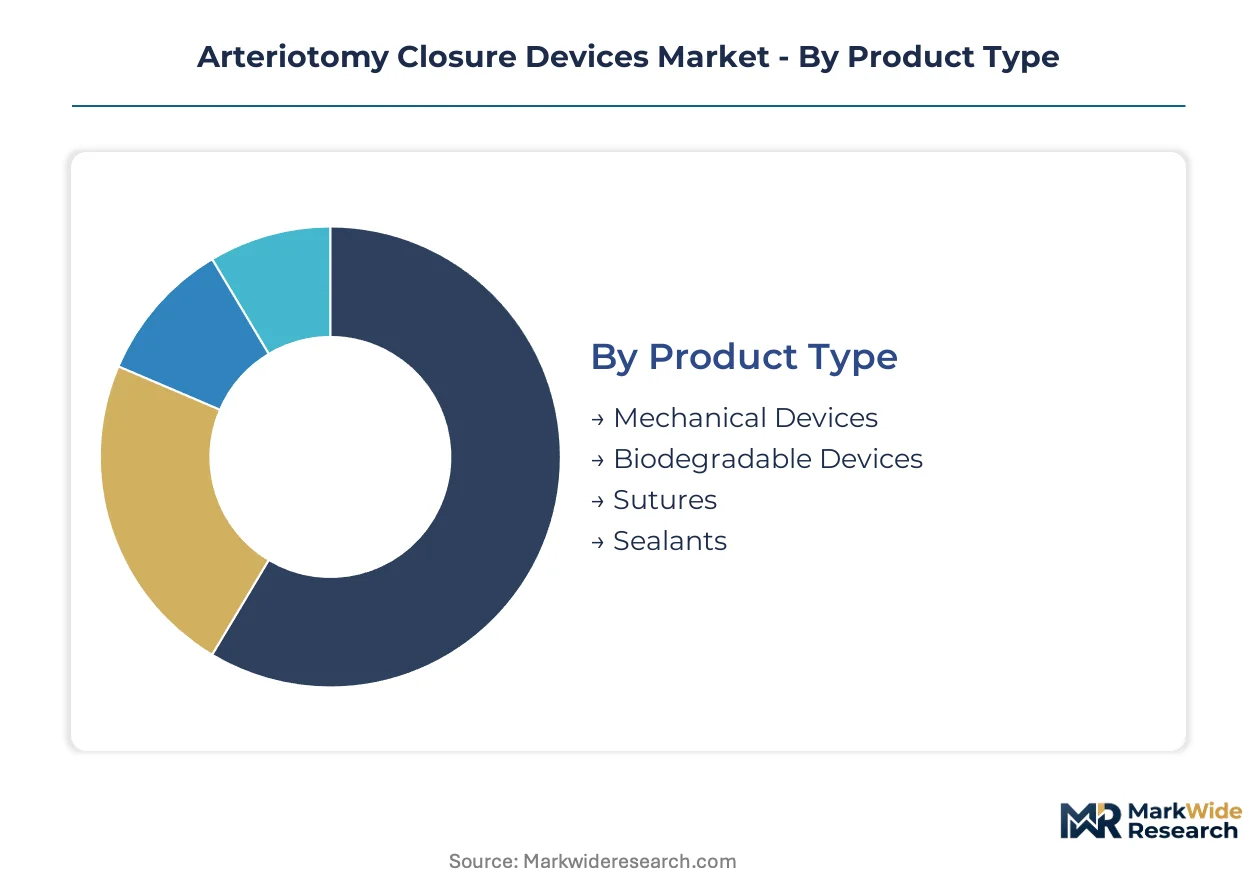
Arteriotomy closure devices serve distinct clinical workflows that demand differentiated mechanical specifications, reimbursement coding, and deployment protocols. Segment-level purchasing patterns reveal where manufacturers must align product portfolios with site-of-service economics and procedural volume concentration.
Product Type:
Mechanical closure systems dominate cath lab purchasing through established hemostasis reliability, while biodegradable alternatives are capturing preference in ambulatory settings seeking implant-free recovery pathways.
- Mechanical Devices:Nitinol clip and suture-mediated systems achieve hemostasis through permanent implant retention, with collagen plug variants relying on bovine-derived matrices. Hospital cath labs in the United States and Germany concentrate procurement around these platforms due to decades of physician training familiarity and predictable reimbursement slots. The FDA's 510(k) pathway has streamlined iterative improvements in clip deployment mechanisms, compressing product development cycles for established manufacturers.
- Biodegradable Devices:Polylactic acid scaffolds combined with active hemostatic agents dissolve within 90 days, eliminating chronic inflammation risks from permanent foreign bodies. Japanese interventional suites and European outpatient clinics are driving adoption as post-market surveillance data validates safety profiles. The EMA's MDR clinical evidence requirements are extending certification timelines for new biodegradable entrants, favoring developers with existing European revenue streams.
- Sutures:Manual and assisted suturing systems retain utility in cost-sensitive healthcare systems where device expenditure faces procurement committee scrutiny.
- Sealants:Topical hemostatic agents serve adjunctive roles in complex access sites with coagulopathic patients or anticoagulation therapy.
The dominant share belongs to Mechanical Devices, while Biodegradable Devices is closing the gap fastest.
End User:
Purchasing authority concentrates differently across facility types, with hospital systems leveraging enterprise agreements while freestanding clinics prioritize device flexibility.
- Hospitals:Integrated delivery networks bundle closure devices with diagnostic catheter purchases, extracting volume discounts that compress standalone manufacturer margins. Cath lab consolidation across United States health systems has halved independent purchasing entities over the past decade, forcing device vendors into multi-year enterprise commitments.
- Ambulatory Surgical Centers:Freestanding cardiac catheterization labs are capturing procedural volume from hospital-based suites, requiring closure portfolios optimized for reduced support staff and rapid patient turnover. Medicare reimbursement incentives for outpatient cardiac procedures are accelerating this channel shift.
- Cardiac Clinics:Specialized interventional facilities concentrate radial access procedures, creating demand for smaller-diameter closure specifications.
- Urgent Care Facilities:Peripheral vascular access management in emergency settings favors disposable, single-operator deployment systems.
Hospitals retain volume leadership through bundled purchasing power, though Ambulatory Surgical Centers is expanding most quickly as site-of-service economics shift.
Deployment:
Care setting determines staffing requirements, infection control protocols, and device storage conditions that shape product specifications.
- In-Hospital:Full-service cath labs maintain inventory breadth across mechanical and biodegradable platforms, supported by sterile processing infrastructure and 24-hour interventional coverage. German academic medical centers and United States teaching hospitals pilot hybrid bioabsorbable systems in transcatheter valve programs.
- Outpatient:Same-day discharge mandates drive selection toward technologies demonstrating sub-15-minute hemostasis, with reimbursement tied to ambulatory surgery center efficiency metrics.
- Mobile Clinics:Portable catheterization units serving rural populations require compact, temperature-stable closure device formats.
- Home Healthcare:Post-procedure compression devices and monitoring tools support early discharge protocols in integrated care pathways.
In-Hospital deployment commands procedure volume, yet Outpatient settings are gaining share fastest as cardiac care decentralizes.
Application:
Procedural complexity and access site characteristics dictate closure device selection across interventional specialties.
- Cardiology:Diagnostic catheterization and percutaneous coronary intervention generate the highest closure device consumption, with transradial adoption creating parallel demand for specialized radial closure formats. Japanese interventional cardiology suites lead radial access penetration, influencing device design specifications globally.
- Radiology:Interventional radiology procedures including transarterial chemoembolization and uterine fibroid embolization utilize closure devices in femoral access sites with larger sheath sizes.
- Vascular Surgery:Endovascular aneurysm repair and peripheral arterial interventions require robust hemostasis in anticoagulated patients.
- Interventional Procedures:Hybrid operating rooms combining surgical and catheter-based techniques demand closure compatibility with open conversion scenarios.
Cardiology holds the dominant application share, while Interventional Procedures is climbing fastest as hybrid OR investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for bovine-derived collagen concentrates device manufacturing in select markets, while export-oriented medtech clusters in Germany and Japan supply finished closure systems throughout Europe and Asia-Pacific.
United States
Hospital cath lab consolidation has halved independent purchasing entities over the past decade, concentrating procurement power in integrated delivery networks. The FDA's 510(k) pathway compresses time-to-market for iterative device improvements, accelerating suture-mediated and clip-based mechanism upgrades. Minneapolis-St. Paul anchors vascular device development, with Boston and Irvine clusters supporting specialized hemostasis technology.
Germany
Academic medical centers in Munich and Heidelberg pilot hybrid bioabsorbable closure platforms in transcatheter valve programs, validating 90-day dissolution profiles. The EMA's Medical Device Regulation mandates post-market clinical follow-up studies that extend certification timelines by 12-18 months for new entrants. Baden-Württemberg's precision manufacturing corridor supplies nitinol clip components to European device assemblers.
Japan
Transradial catheterization penetration leads globally, driving specialized radial closure device specifications adopted worldwide. The PMDA maintains distinct pharmacovigilance reporting standards that elevate post-market surveillance compliance costs for hemostasis device manufacturers. Tokyo-Osaka medical device clusters concentrate domestic production of polylactic acid scaffolds for biodegradable systems.
India
Price-sensitive healthcare systems sustain manual compression as the default closure method, suppressing device-mediated adoption outside premium urban hospitals. The CDSCO's emerging medical device regulatory framework is formalizing quality standards for vascular closure products, creating first-mover positioning for clinical evidence generators. Maharashtra's Mumbai-Pune corridor hosts contract manufacturing for collagen plug components serving export markets.
United Kingdom
NHS procurement frameworks favor outcome-guarantee contracting over device pricing alone, pressuring standalone closure manufacturers. MHRA post-Brexit regulatory alignment with EMA MDR requirements maintains CE marking relevance for UK market access. London's teaching hospitals concentrate radial access training programs that influence closure device selection criteria.
Arteriotomy Closure Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market structure consolidates around integrated vascular portfolios that bundle closure devices with diagnostic catheters, compressing margins for standalone manufacturers. Three archetypes dominate: diversified medtech conglomerates with cath lab ecosystem control, specialized hemostasis technology developers, and regional contract manufacturers supplying collagen matrices and nitinol components. Competitive moves concentrate on multi-year enterprise purchasing agreements and backward integration into bovine collagen processing.
Within the diversified medtech tier, Abbott Laboratories, Terumo Corporation, and Medtronic occupy positions spanning full procedure workflows. Abbott leverages its integrated vascular portfolio to sustain catheter lab loyalty across multiple intervention types. Terumo anchors its position through specialized hemostasis technology that dominates Japanese interventional suites. Medtronic extends its structural heart reach into peripheral vascular workflows, representing the ecosystem-expansion archetype among platform players.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Terumo Corporation |
| Medtronic |
| Cardinal Health |
| Teleflex Incorporated |
| Haemonetics Corporation |
| Merit Medical Systems |
| Boston Scientific Corporation |
| Cardiva Medical |
| Others |
Supply Flow & Price Mechanics
Undercapacity in bovine-derived collagen processing regions is tightening input availability for plug-based closure systems, forcing manufacturers to absorb cost volatility while hospital procurement committees demand outcome-guaranteed contracting. This utilization squeeze concentrates pricing power with agricultural processors upstream, compressing margins for device assemblers who cannot pass through input spikes to bundled enterprise agreements.
Pricing Analysis
Hospital purchasing committees anchor pricing stratification across premium, standard, and economy tiers based on hemostasis speed certification and after-sales clinical support bundling. Price differentiation hinges on FDA 510(k) clearance tier and volume scale commitments within multi-year enterprise contracts. Cost compression in the standard tier is intensifying because standalone closure manufacturers lack catheter bundling leverage against integrated vascular platforms. Ambulatory surgical centers exhibit highest price sensitivity due to thin reimbursement margins, while academic medical centers prioritize premium hybrid bioabsorbable systems regardless of unit cost.
Supply Chain Analysis
Extended payment terms from integrated delivery networks are squeezing working capital for component suppliers, accelerating supply-chain finance facility adoption among nitinol clip fabricators. Geographic concentration centers on the United States, Germany, and Japan for finished device assembly, with bovine collagen sourcing anchored in specific agricultural processing regions and polylactic acid scaffold production tethered to Tokyo-Osaka chemical corridors. Single-source vulnerability in collagen plug matrices exposes assemblers to livestock disease outbreak disruptions. Distribution runs through GPO-contracted channels for hospital systems and direct procurement for freestanding cardiac clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting toward ecosystem control as cath lab equipment leasing models and integrated vascular portfolios collapse standalone device margins, rewarding interoperability investments that span diagnostic catheter-to-closure workflows.
For Market Incumbents: Build switching-cost moats through backward integration into bovine collagen processing and captive supply of nitinol clip components. Defensive consolidation must address the threat from biodegradable polymer convergence by acquiring polylactic acid scaffold specialists, while channel control investments in ambulatory surgical center direct sales teams provide leverage against hospital system bundling pressure. For New Entrants and Emerging Players: Establish a beachhead in India's emerging CDSCO pathway by generating local clinical evidence ahead of formalized quality standards. The most penetrable white-space sits in radial closure devices optimized for smaller arterial diameters, where Japanese specification leadership has not yet fully transferred to cost-sensitive Asian markets. A go-to-market angle through mobile catheterization unit operators bypasses entrenched hospital GPO contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biodegradable device sub-segments as polylactic acid scaffold manufacturing scales and regulatory documentation costs amortize across product generations. Long-term viability over the next decade favors developers with existing European revenue streams capable of absorbing EMA MDR clinical evidence burdens. The acquisition target archetype is specialized hemostasis technology developers with Japanese PMDA pharmacovigilance compliance infrastructure. Watch for inflection signals in same-day discharge mandate expansion across Medicare reimbursement schedules.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification compresses time-to-market for iterative clip mechanism improvements. |
| CE Marking Pathway Investment | Front-loaded German and French clinical trials generate robust safety datasets required for EMA MDR compliance. |
| Hospital System Partnership | Multi-year enterprise agreements bundle closure devices with diagnostic catheters across consolidated cath labs. |
| Backward Integration into Collagen | Captive bovine-derived matrix supply insulates against agricultural processing region volatility. |
| Reimbursement Strategy | Outcome-guarantee contracting aligns device selection with sub-15-minute hemostasis efficiency metrics. |
Methodological Framework
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates across cath lab types triangulated with top-down manufacturer revenue segmentation.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by mechanism, end-user facility economics, deployment setting staffing requirements, and application-specific procedural complexity. CAGRs were derived from installed cath lab capacity expansion, radial access adoption curves, and ambulatory surgery center volume capture rates. Industry-specific forecast inputs included PMDA pharmacovigilance compliance cost trajectories and CDSCO regulatory pathway formalization timelines.
Sensitivities concentrate around bovine collagen supply disruptions, EMA MDR certification timeline extensions, and radial access training program capacity constraints. Forecasts reflect assumptions regarding Medicare reimbursement stability for outpatient cardiac procedures and integrated delivery network consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Blood Pressure Transducers Market
Cardiovascular Devices
Cardiac Cannulas Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market