
 Lower Limb Arterial Stents Market | 2026-2036
Lower Limb Arterial Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Lower Limb Arterial Stents Market Analytics
European nitinol wire producers is realigning supply chains toward medical-grade certification. Boston Scientific Corporation leverages captive foundry partnerships to secure superelastic alloy feedstock. Medtronic anchors its position through vertically integrated stent-graft manufacturing in Ireland and Minnesota. Abbott Laboratories differentiates via proprietary drug-elution platforms for femoropopliteal lesions.
Lower limb arterial stents are implantable tubular scaffolds manufactured from nitinol, cobalt-chromium, or stainless steel alloys, typically 5-8 mm in diameter and 20-200 mm in length, designed to restore patency in superficial femoral and popliteal arteries compromised by atherosclerotic disease. Self-expanding nitinol stents dominate chronic total occlusion cases where vessel recoil demands continuous outward radial force, while drug-eluting stents command premium positioning in restenosis-prone lesions due to paclitaxel or sirolimus coatings that modulate neointimal hyperplasia. Ambulatory surgical centers represent the fastest-growing end-user channel as same-day discharge protocols and office-based lab investments shift lower-complexity procedures away from inpatient settings.
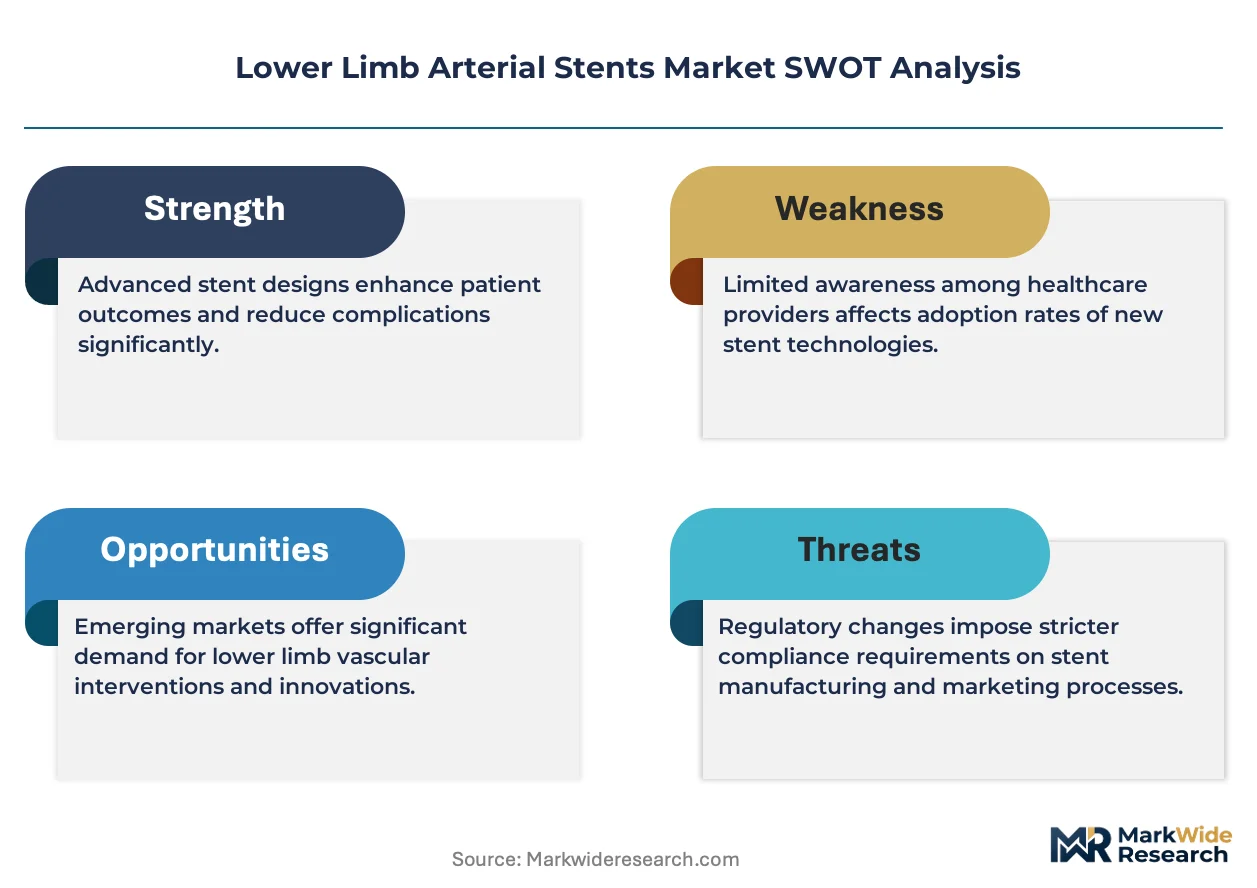
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern commercial access, with both frameworks intensifying post-market surveillance requirements for permanent implants. The EPA and ECHA regulate nickel ion leaching thresholds from nitinol substrates, forcing alloy refinement and surface passivation investments. Stakeholders must monitor evolving reimbursement thresholds for drug-eluting platforms against bare-metal alternatives as health technology assessment bodies tighten evidence requirements for premium pricing.
Market Dynamics
Hospital systems in the United States, Germany, and Japan are consolidating endovascular capacity into specialized procedure suites, concentrating purchasing power and forcing stent manufacturers to bundle training, inventory management, and outcome guarantees into supply contracts.
Growth Catalysts
- Diabetes prevalence acceleration:Rising diabetic populations in Japan and the United States generate sustained superficial femoral artery lesion volumes requiring repeat intervention.
- CE marking under EU MDR:Stricter post-market surveillance requirements for permanent implants are elevating quality barriers that favor established nitinol processors with certified foundry partnerships.
- Drug-elution platforms:Paclitaxel and sirolimus coatings that modulate neointimal hyperplasia command premium positioning in restenosis-prone lesions.
Market Restraints
- Nickel feedstock volatility:Medical-grade nitinol wire producers face ECHA-mandated traceability investments that compress alloy margins.
- Superelastic alloy concentration:European foundry capacity limits constrain rapid scaling of self-expanding stent production.
- Bare-metal substitution ceiling:Health technology assessment bodies in Germany demand incremental cost-effectiveness evidence that stalls drug-eluting platform uptake.
Strategic Opportunities
- Ambulatory surgical center expansion:Same-day discharge protocols in the United States shift lower-complexity procedures from inpatient settings.
- Surface passivation advances:Nickel ion leaching reduction technologies align with EPA thresholds and open differentiated positioning.
- Vertically integrated manufacturing:Captive stent-graft production in Ireland and Minnesota insulates against supply chain disruption.
Industry Challenges
- Interventional cardiologist training pipelines:Chronic total occlusion case complexity outpaces fellowship program expansion in Japan.
- 510(k) clearance timeline compression:FDA intensification of permanent implant documentation requirements extends time-to-revenue for new nitinol designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lower Limb Arterial Stents Market |
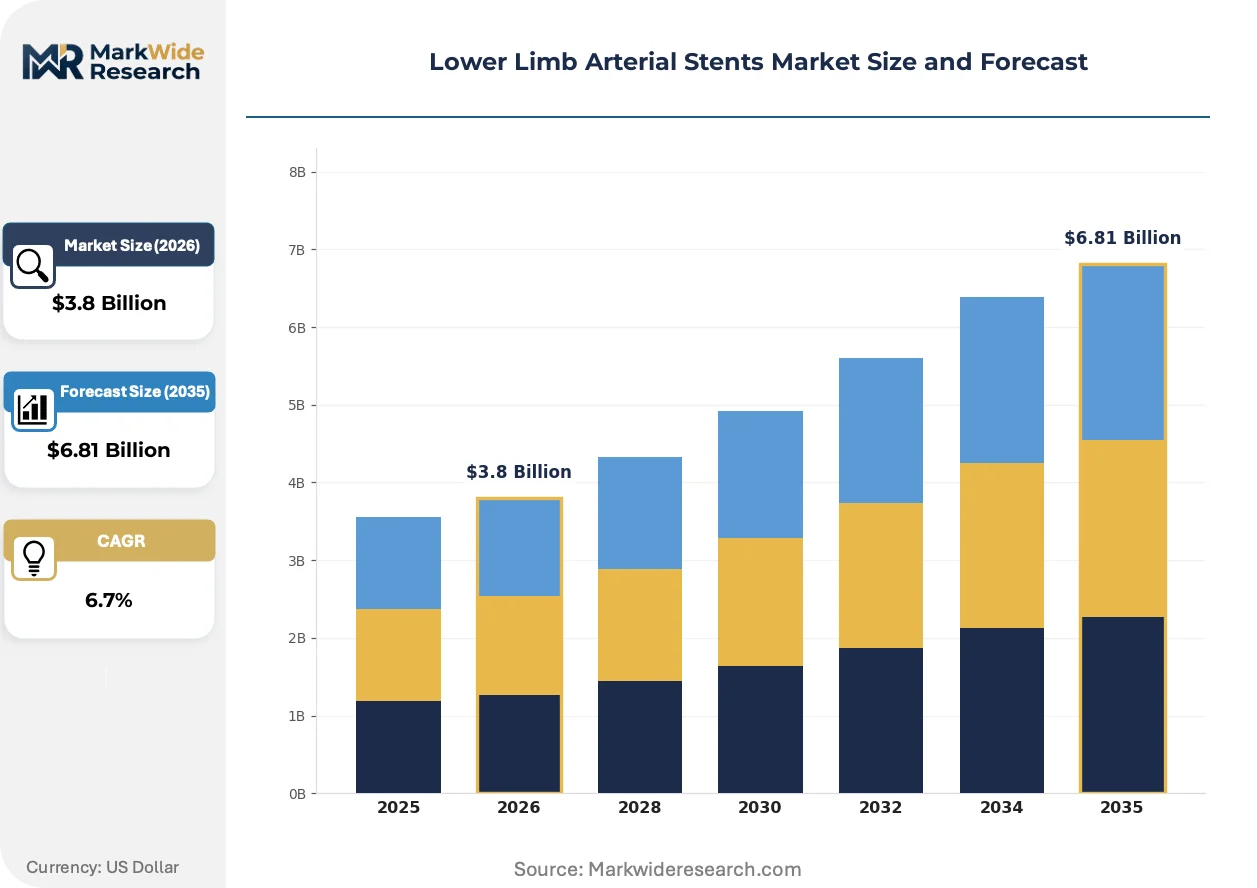
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Drug-Eluting Stents, Covered Stents End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Delivery Mode: Endovascular Delivery, Hybrid Delivery, Open Surgery, Transluminal Delivery Application: Peripheral Artery Disease, Aneurysm Repair, Vascular Reconstruction, Stenosis Treatment |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic, Terumo Corporation, B. Braun, W.L. Gore & Associates, Biotronik, Cook Medical, Biosensors International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lower Limb Arterial Stents Market Evolving Landscape
Bioresorbable scaffold development and computational modeling of vessel-wall interaction are compressing the innovation cycle, while regulatory convergence between FDA and EU MDR frameworks is harmonizing evidence requirements.
Polymer-free drug delivery systems are unifying antiproliferative efficacy with reduced inflammatory response. Ambulatory surgical centers in the United States are accelerating adoption of these platforms for femoropopliteal lesions. The technology is unifying previously separate device and pharmaceutical supply chains into single-source contracting relationships.
EU MDR post-market surveillance mandates are forcing nitinol processors to implement lot-level material genealogy systems. Manufacturers must now maintain decade-long traceability records for superelastic alloy feedstock. Small European wire producers without captive foundry partnerships face existential compliance costs.
Hospital procurement departments are consolidating stent purchasing into multi-year sole-source agreements with outcome-based performance clauses. United States health systems increasingly require manufacturers to absorb revision procedure costs for target lesion revascularization. This purchasing model compresses price differentiation between bare-metal and drug-eluting platforms.
Lower Limb Arterial Stents Market Segmentation
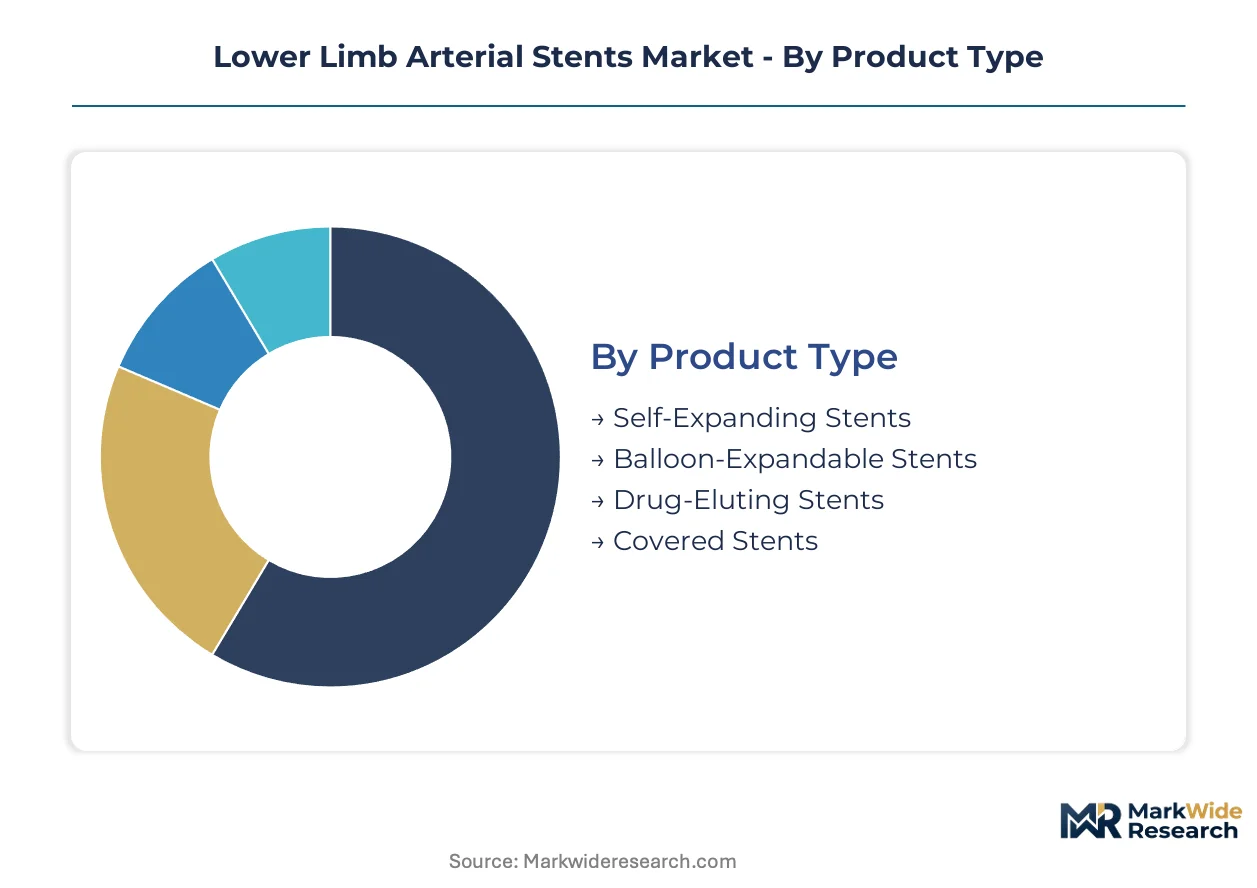
Lower limb arterial stent purchasing decisions diverge sharply across clinical settings and lesion complexity. Manufacturers must align product portfolios with distinct technical specifications, reimbursement pathways, and physician training requirements that vary by segment.
Product Type:
Self-expanding nitinol platforms command premium positioning in tortuous superficial femoral anatomy, while balloon-expandable alternatives suit calcified proximal lesions requiring precise diameter control.
- Self-Expanding Stents:Manufactured from superelastic nitinol alloys with thermal shape memory, these devices deploy at body temperature to provide continuous radial force against elastic recoil in long-segment femoropopliteal disease. Demand concentrates in United States hospital systems where chronic total occlusion volumes sustain high-volume catheterization lab utilization. FDA 510(k) documentation requirements for nitinol composition traceability extend clearance timelines but reinforce incumbent positioning.
- Drug-Eluting Stents:Polymer matrices loaded with paclitaxel or sirolimus modulate neointimal hyperplasia in restenosis-prone lesions. German health technology assessment bodies demand incremental cost-effectiveness evidence that slows uptake against bare-metal alternatives despite superior patency outcomes.
- Balloon-Expandable Stents:Cobalt-chromium or stainless steel platforms deliver precise diameter expansion for calcified ostial lesions. Japanese reimbursement thresholds favor these devices in proximal superficial femoral artery interventions.
- Covered Stents:Expanded polytetrafluoroethylene or polyester graft materials exclude aneurysm sacs from arterial pressure. United States ambulatory surgical centers deploy these for femoral artery aneurysms with same-day discharge protocols.
Volume sits with self-expanding platforms; growth tilts toward drug-eluting configurations as evidence requirements harmonize across FDA and EU MDR frameworks.
End User:
Procurement authority and technical capability determine device selection, with hospital systems consolidating purchasing power while ambulatory settings prioritize simplified inventory and rapid turnover.
- Hospitals:Comprehensive endovascular suites with hybrid operating room infrastructure manage complex multilevel disease and complication rescue. United States health systems bundle stent procurement with outcome guarantees and revision procedure cost absorption.
- Ambulatory Surgical Centers:Office-based lab investments and same-day discharge protocols concentrate demand for lower-complexity femoropopliteal interventions. These facilities are expanding most quickly as Medicare reimbursement shifts favor outpatient settings.
- Specialty Clinics:Vascular surgery and interventional radiology practices with catheterization capabilities perform diagnostic and therapeutic procedures outside hospital ownership.
- Research Institutions:Academic medical centers generate clinical evidence for novel drug-elution platforms and bioresorbable scaffolds through investigator-initiated trials.
Revenue concentrates in hospital procurement; volume expansion favors ambulatory surgical centers as site-of-service migration accelerates.
Delivery Mode:
Lesion accessibility and operator training determine delivery approach, with endovascular techniques displacing open surgical reconstruction in anatomically suitable cases.
- Endovascular Delivery:Transfemoral or transpopliteal catheter-based deployment dominates superficial femoral and popliteal artery interventions. Japan's interventional cardiologist training pipelines struggle to match chronic total occlusion case complexity growth.
- Hybrid Delivery:Combined surgical exposure and endovascular techniques address tandem lesions or inadequate landing zones. These procedures concentrate in United States academic medical centers with vascular surgery residency programs.
- Open Surgery:Bypass grafting with autologous vein or synthetic conduit persists for extensive calcification or failed endovascular reconstruction.
- Transluminal Delivery:Subintimal recanalization techniques with re-entry devices navigate chronic total occlusions when intraluminal wire passage fails.
Procedure volume clusters in endovascular delivery; hybrid techniques gain share in complex anatomical reconstructions.
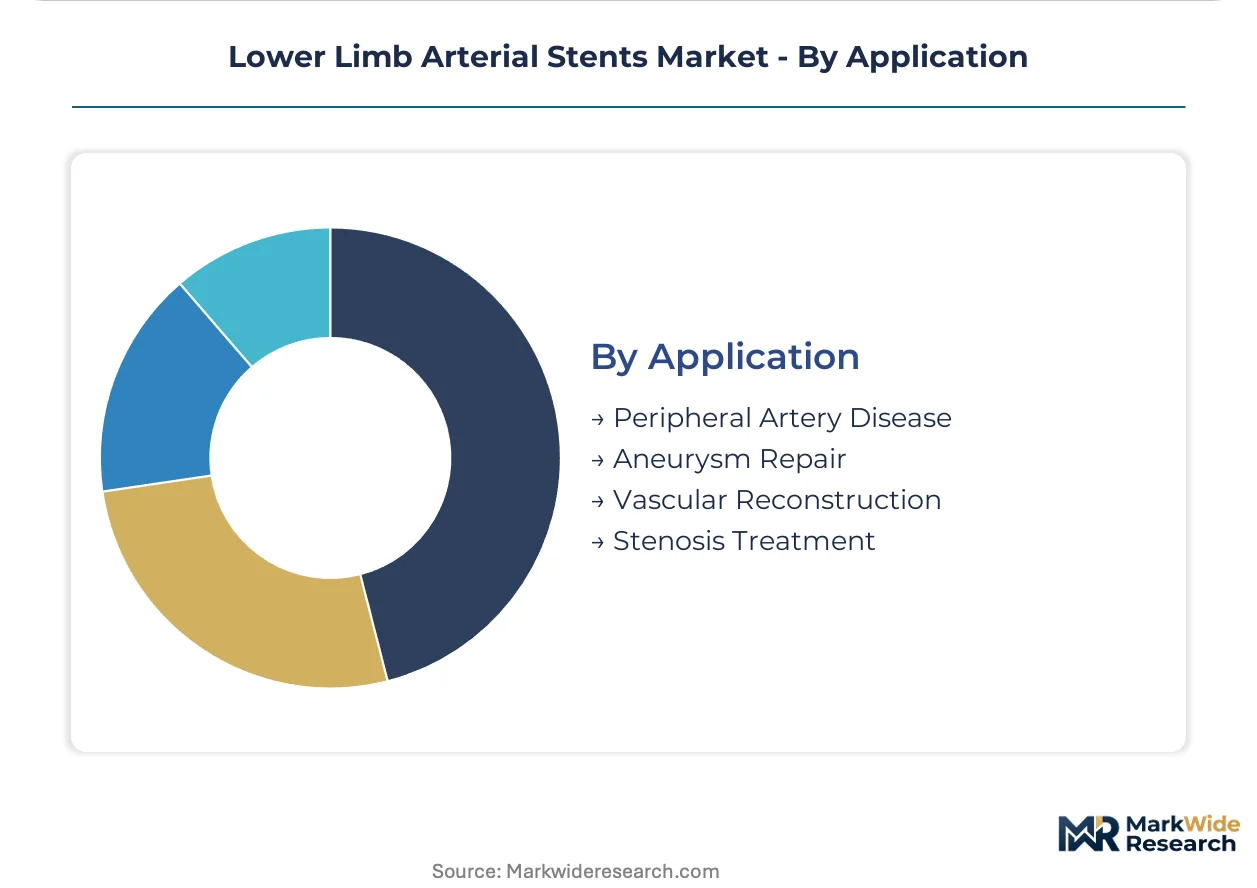
Application:
Underlying pathology dictates stent specification, with atherosclerotic disease generating repeat intervention volumes that sustain aftermarket revenue.
- Peripheral Artery Disease:Atherosclerotic superficial femoral artery stenosis and occlusion represent the dominant indication, with diabetes prevalence in Japan and the United States driving sustained lesion volumes requiring repeat intervention.
- Aneurysm Repair:Popliteal artery aneurysms and pseudoaneurysms require exclusion with covered stent-grafts to prevent thromboembolic complications.
- Vascular Reconstruction:Traumatic injury or iatrogenic dissection demands stent placement to restore luminal integrity and prevent limb loss.
- Stenosis Treatment:Recurrent stenosis after prior endovascular or surgical intervention targets drug-eluting platforms for extended patency.
Peripheral artery disease anchors installed base; aneurysm repair applications climb fastest as covered stent technology improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European nitinol foundries in Ireland and Germany anchor superelastic alloy supply chains for self-expanding stent manufacturing. Hospital procurement consolidation in the United States and Japan concentrates demand in specialized endovascular suites.
United States
Diabetes prevalence and aging demographics sustain superficial femoral artery intervention volumes across hospital systems. FDA 510(k) clearance timelines for permanent nitinol implants have extended under intensified documentation requirements. Minneapolis and Boston metropolitan areas host vertically integrated stent-graft manufacturing facilities serving domestic demand.
Germany
Health technology assessment bodies demand incremental cost-effectiveness evidence that slows drug-eluting platform uptake against bare-metal alternatives. EU MDR post-market surveillance mandates enforce lot-level material genealogy for nitinol processors. Baden-Württemberg industrial clusters concentrate precision wire drawing and surface passivation capabilities.
Japan
Interventional cardiologist training pipelines struggle to match chronic total occlusion case complexity growth. PMDA regulatory frameworks align with FDA evidence requirements for drug-eluting stent approvals. Tokyo and Osaka academic medical centers generate clinical evidence through investigator-initiated trials.
Ireland
Captive stent-graft manufacturing facilities leverage EU regulatory access and English-language commercial infrastructure. ECHA-mandated nickel traceability investments compress margins for medical-grade alloy processors. Galway and Dublin regions concentrate contract manufacturing for multinational device firms.
Lower Limb Arterial Stents Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioresorbable scaffold development and polymer-free drug delivery platforms. The vendor base stratifies across three tiers: multinational conglomerates with captive foundry partnerships, mid-scale specialists with regional regulatory approvals, and research-stage innovators targeting next-generation materials. Market consolidation proceeds through strategic partnerships between alloy processors and finished-device manufacturers, while geographic expansion into ambulatory surgical center channels accelerates.
Among United States-based conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify the vertically integrated archetype with captive supply chain control. Medtronic anchors the European manufacturing vector through Irish production facilities. Terumo Corporation represents Japanese specialist positioning with regional regulatory depth.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| B. Braun |
| W.L. Gore & Associates |
| Biotronik |
| Cook Medical |
| Biosensors International Group |
| Others |
Value Network & Pricing Analysis
ECHA-mandated nickel traceability thresholds gate qualified nitinol supply and premium-tier pricing access, forcing alloy processors to absorb compliance investments that stratify market positioning between certified foundry partnerships and marginal producers. Hospital procurement consolidation concentrates volume leverage, compressing margins for manufacturers lacking backward integration into superelastic alloy feedstock.
Pricing Analysis
Service-bundling separates manufacturers who absorb revision procedure costs from those offering unbundled device-only contracts. Three-tier pricing structure across drug-eluting, self-expanding bare-metal, and balloon-expandable configurations reflects FDA clearance tier and clinical evidence depth. Pricing pressure stems from German health technology assessment bodies demanding incremental cost-effectiveness evidence for premium platforms. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement compression, while academic medical centers with hybrid operating room infrastructure demonstrate lowest sensitivity.
Supply Chain Analysis
Precision metallurgist availability constraints in Ireland, Germany, and Minnesota shape superelastic alloy processing capacity for nitinol stent manufacturing. Medical-grade nitinol wire production draws from nickel feedstock sourced through ECHA-registered channels, with thermal shape memory processing and surface passivation coating as critical downstream steps. Single-source vulnerability concentrates in European foundry capacity for medical-grade superelastic alloys. Distribution runs through hospital system procurement departments consolidating into multi-year sole-source agreements with inventory management and outcome guarantee provisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over nitinol foundry partnerships determines margin sustainability against procurement consolidation pressure.
For Market Incumbents: Lock in exclusive superelastic alloy supply agreements with ECHA-certified European foundries before compliance investments eliminate marginal processors. Acquire surface passivation technology specialists to differentiate on nickel ion leaching performance against EPA thresholds. Bioresorbable scaffold startups threaten long-term positioning in restenosis-prone lesions. For New Entrants and Emerging Players: Polymer-free drug delivery platforms offer technology-first wedge into United States ambulatory surgical center channels where simplified inventory and rapid turnover priorities favor streamlined platforms. Target office-based lab investments in secondary metropolitan markets where hospital system purchasing consolidation remains incomplete. Pursue GPO contracting relationships that bypass direct hospital procurement committee barriers. For Investors and Strategic Acquirers: FDA 510(k) clearance timeline extension for permanent nitinol implants is the leading indicator that regulatory capacity constraints will favor established players with documented quality systems over venture-stage entrants. Five-to-ten year viability requires positioning alongside reimbursement strategy capabilities rather than pure device innovation. Acquisition target archetype: mid-scale nitinol processors with EU MDR lot-level genealogy systems already operational.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates elevate quality barriers that favor established nitinol processors with certified foundry partnerships. |
| Hospital System Partnership | Sole-source agreements with outcome-based performance clauses and revision cost absorption secure volume commitments against procurement consolidation. |
| Backward Integration into Foundry | Captive superelastic alloy supply insulates against ECHA-mandated traceability investments and European foundry capacity constraints. |
| Reimbursement Strategy | Health technology assessment body alignment in Germany and Japan determines premium platform access against bare-metal substitution. |
| Software Companion Development | Computational modeling of vessel-wall interaction accelerates design iteration and differentiates training support for chronic total occlusion cases. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification trajectories, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with vascular surgeons, interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) database filings, EUDAMED device registrations, CMS Medicare procedure volume data, and hospital procurement database extracts. Bottom-up stent unit demand modeling and top-down healthcare expenditure allocation triangulated market sizing across product type, end user, delivery mode, and application segments.
Input-output matrices mapped nitinol feedstock availability through finished-device production to end-user procurement channels, with CAGRs derived from procedure volume elasticity to diabetes prevalence and aging demographic shifts. Segmentation dimensions modeled include stent platform technology, site-of-service setting, lesion complexity tier, and geographic regulatory cluster. Forecast inputs incorporated chronic total occlusion case growth, ambulatory surgical center reimbursement migration, and drug-eluting platform evidence requirement harmonization between FDA and EU MDR frameworks.
Several conditions sit outside the modeled scope, including paclitaxel safety signal regulatory reclassification, bioresorbable scaffold clinical trial outcomes, and interventional cardiologist training pipeline expansion rates. Forecasts reflect assumptions regarding sustained diabetes prevalence acceleration and stable nickel feedstock availability. Material deviation in FDA permanent implant documentation requirements or ECHA nickel ion leaching threshold revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Intra-Aortic Balloon Pump (IABP) Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Intravascular Stents Market