
 Transcatheter Heart Valve Market | 2026-2036
Transcatheter Heart Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Heart Valve Market Analytics
The gap between premium transcatheter heart valve systems and commodity-compatible alternatives is broadening as reimbursement tiers separate high-precision delivery mechanisms from basic implantable designs. Edwards Lifesciences Corporation anchors its position through proprietary balloon-expandable platforms engineered for calcified anatomies. Medtronic leverages self-expanding nitinol frameworks to sustain dominance in transfemoral access routes. Abbott differentiates via its navigational catheter portfolio that competes across both aortic and mitral repair indications.
Transcatheter heart valves comprise bioprosthetic leaflets mounted on collapsible metal stents, typically fabricated from nitinol or cobalt-chromium alloys, delivered through minimally invasive vascular access to replace or repair native valves without open-chest surgery. The aortic valve segment leads procedural volumes due to established transcatheter aortic valve replacement protocols, while the mitral valve segment represents the fastest-growing application as repair technologies address underserved regurgitation populations. Transfemoral delivery mode occupies the dominant access channel, though transapical routes retain importance for patients with hostile femoral anatomy where vascular complications must be minimized.
FDA premarket approval pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for manufacturers seeking commercial access. The EPA and OSHA frameworks govern sterilization facility operations and cobalt-chromium powder handling standards that affect production economics. Stakeholders must monitor how evolving FDA breakthrough device criteria and EU AI Act implications for imaging-guided deployment algorithms reshape competitive entry barriers and capital allocation priorities across the development pipeline.
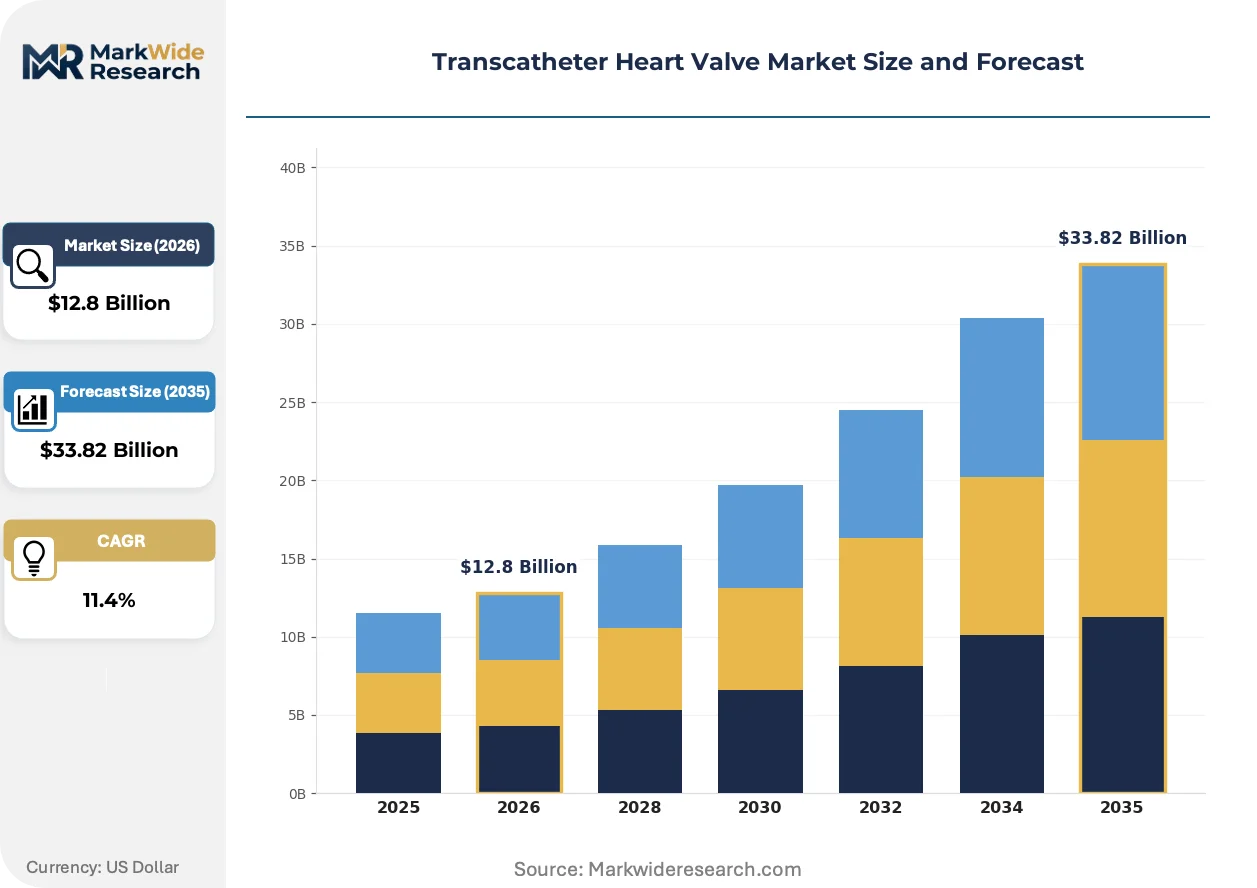
Market Dynamics
The Transcatheter Heart Valve Market is experiencing a structural inflection as balloon-expandable and self-expanding stent platforms compete for procedural dominance, with reimbursement tiers increasingly stratifying around delivery precision and anatomical compatibility rather than implant material alone.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress commercialization timelines for novel valve systems targeting underserved calcified anatomies, rewarding manufacturers who invest in predicate-busting clinical evidence packages.
- Japan's Super-Aged Society:Cardiac centers in Tokyo and Osaka report transfemoral procedure volumes climbing fastest among octogenarians previously excluded from surgical valve replacement due to frailty indices.
- Computed Tomography-Based Sizing Algorithms:Pre-procedural planning software integrated with 3D reconstruction is converging with delivery catheter engineering to reduce paravalvular leak rates and expand treatable patient populations.
Market Restraints
- Cobalt-Chromium Powder Volatility:Supply concentration in Chinese and Russian mining operations creates input cost unpredictability for stent frame manufacturers, compressing gross margins on balloon-expandable platforms.
- EU MDR Conformity Assessment Bottlenecks:Notified body capacity constraints extend CE marking timelines by 12-18 months for Class III implantable devices, freezing capital deployment and delaying revenue recognition.
- Surgical Valve Durability Benchmarks:Transcatheter bioprosthetic leaflets face structural valve deterioration skepticism among referring cardiologists in Germany, where surgical aortic valve replacement remains the comparator standard for patients under 75.
Strategic Opportunities
- Tricuspid Regurgitation Repair:The anatomical complexity of right-sided valves has delayed transcatheter solutions, creating first-mover advantage for systems navigating heterogeneous leaflet morphologies and annular dilatation patterns.
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives attract catheter assembly investments targeting price-sensitive private hospital chains in Mumbai and Delhi seeking to reduce import dependency.
- Fluoroscopy-Guided Deployment:Integration of real-time imaging with robotic catheter stabilization is converging with AI-powered anatomical landmark recognition to enable operator-agnostic procedure standardization.
Industry Challenges
- Interventional Cardiologist Training Pipelines:Procedural learning curves for transcatheter mitral repair exceed 50 supervised cases, constraining adoption velocity in community hospitals lacking structural heart fellowship programs.
- Sterilization Facility Validation:Ethylene oxide sterilization capacity shortages following EPA emissions enforcement actions force manufacturers to qualify alternative terminal sterilization methods, delaying batch releases.
- Patent Thicket Navigation:Dense intellectual property holdings around nitinol stent geometries and leaflet attachment mechanisms complicate freedom-to-operate analyses for new entrants, elevating litigation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Heart Valve Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aortic Valve, Mitral Valve, Pulmonary Valve, Tricuspid Valve Delivery Mode: Transfemoral, Transapical, Transaortic, Direct Aortic End User: Hospitals, Cardiac Centers, Outpatient Clinics, Research Institutions Application: Heart Failure, Aortic Stenosis, Mitral Regurgitation, Valve Repair |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic, Boston Scientific Corporation, Abbott, JenaValve Technology, Meril Life Sciences, Venus Medtech, Braile Biomédica, LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Heart Valve Market Evolving Landscape
Procedural economics and clinical outcomes are being recast by three intersecting forces: imaging-guided deployment precision, regulatory evidence requirements, and shifting site-of-care preferences that favor outpatient and ambulatory settings over traditional hospital admission.
Polymeric leaflet materials engineered for enhanced fatigue resistance are converging with computational fluid dynamics modeling to enable thinner, more hemodynamically efficient valve designs. Early adopting centers in Germany and the United States are evaluating these systems in feasibility trials, with particular interest in eliminating bioprosthetic calcification as a failure mode. This convergence is compressing the historical durability gap between transcatheter and surgical valve replacements, potentially expanding indicated populations to younger, lower-risk patients.
The EU AI Act's risk classification framework for medical device software is imposing new conformity obligations on imaging-guided deployment algorithms that automate annular sizing or predict paravalvular leak risk. Manufacturers must now document algorithmic transparency, training data provenance, and post-market performance monitoring for AI-integrated catheter systems. The mitral valve repair segment faces the steepest compliance burden, given the anatomical variability that complicates algorithmic generalization across patient populations.
Hospital procurement committees are consolidating vendor relationships around full-procedure bundles that encompass pre-procedural imaging, valve inventory, and complication management guarantees. This consolidation displaces the historical transactional model of device-only purchasing, favoring manufacturers with integrated service infrastructures. The shift is most visible in United States integrated delivery networks, where cath lab directors negotiate multi-year contracts tying valve pricing to aggregate procedural volume commitments and clinical outcome targets.
Transcatheter Heart Valve Market Segmentation
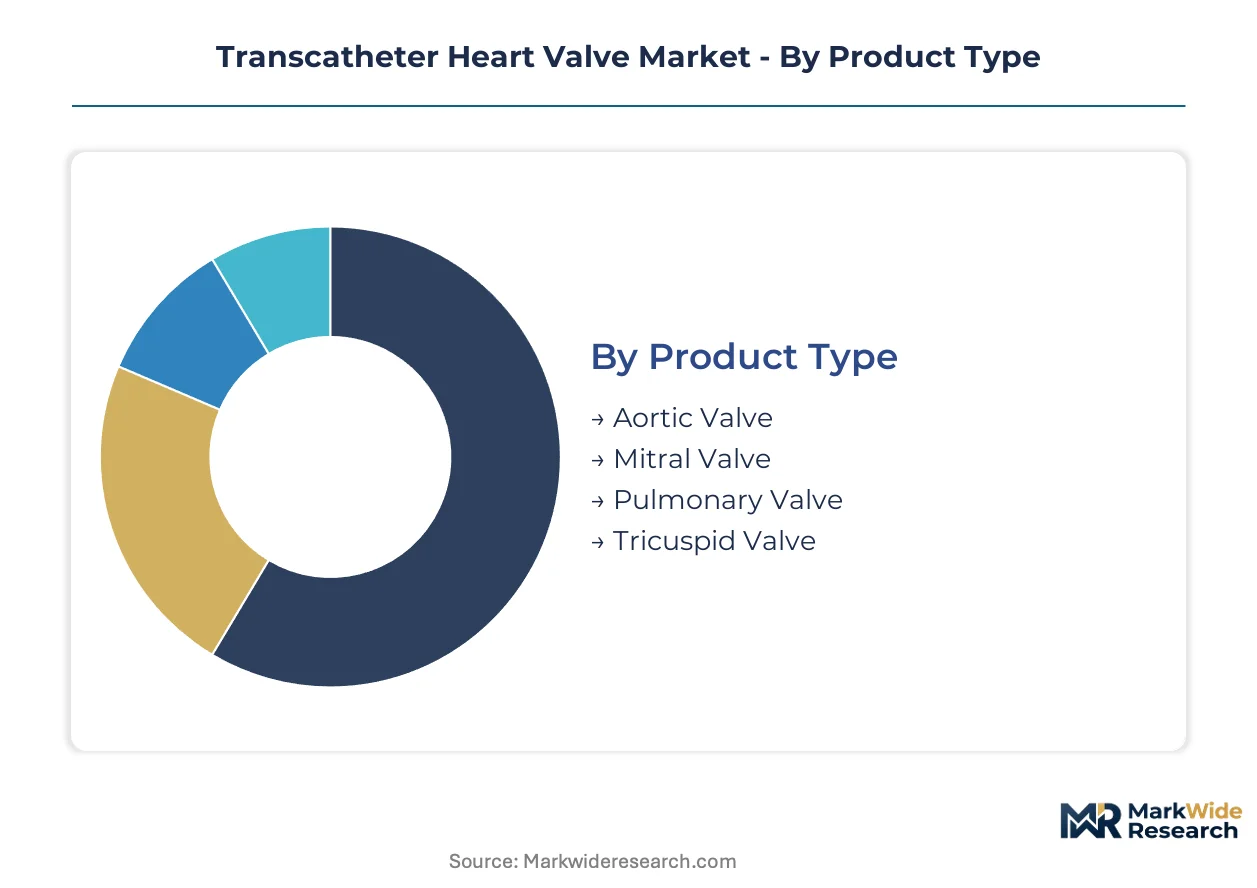
Transcatheter heart valve procurement decisions split across anatomical complexity, vascular access constraints, and site-of-care capabilities. Manufacturers must align product portfolios with these divergent clinical workflows to secure reimbursement and volume commitments.
Product Type:
Buyers in this category differentiate by anatomical challenge and regulatory pathway maturity.
- Aortic Valve:Balloon-expandable and self-expanding bioprosthetic platforms address calcified native valve leaflets. Cardiac centers in Germany and the United States concentrate demand here, driven by established transcatheter aortic valve replacement protocols and favorable reimbursement for octogenarian patients.
- Mitral Valve:Transcatheter edge-to-edge repair and replacement systems navigate complex annular geometry and heterogeneous leaflet pathology. Tokyo and Osaka cardiac centers report fastest adoption velocity as Japan's super-aged society expands treatable populations previously excluded from surgical intervention.
- Pulmonary Valve:Congenital heart disease applications dominate this segment, with specialized pediatric cardiac centers driving procurement.
- Tricuspid Valve:Anatomical complexity and device-tissue interaction challenges constrain commercial availability, creating first-mover opportunity for emerging repair platforms.
Aortic valve leads volumes today; mitral valve is gaining share fastest.
Delivery Mode:
Procurement patterns in this category track patient vascular anatomy and complication risk tolerance.
- Transfemoral:Percutaneous femoral artery access enables same-day discharge protocols. United States integrated delivery networks and German hospital procurement committees prioritize this route for its outpatient economics and reduced length-of-stay metrics.
- Transapical:Minithoracotomy through the cardiac apex bypasses hostile femoral vasculature. Retains importance in elderly patients with peripheral arterial disease where vascular complications must be minimized.
- Transaortic:Direct aortic access via ministernotomy or right anterior thoracotomy serves specific anatomical configurations.
- Direct Aortic:Alternative surgical access for patients unsuitable for transfemoral or transapical routes.
Transfemoral access dominates procedural economics; transapical routes defend niche positions in complex vascular anatomy.
End User:
Capital allocation and training infrastructure separate buyers across this category.
- Hospitals:Comprehensive cardiac surgery and interventional cardiology departments manage high-volume valve programs. United States academic medical centers anchor demand through structural heart fellowship pipelines and hybrid operating room investments.
- Cardiac Centers:Dedicated facilities concentrate procedural expertise and imaging capabilities. German cardiac centers in Munich and Hamburg drive adoption through standardized outcome registries and operator certification requirements.
- Outpatient Clinics:Ambulatory settings expand access for diagnostic workup and post-procedural monitoring.
- Research Institutions:Clinical trial sites and feasibility study centers evaluate next-generation valve platforms.
Hospital systems capture the highest absolute volumes; cardiac centers demonstrate steepest expansion in specialized geographies.
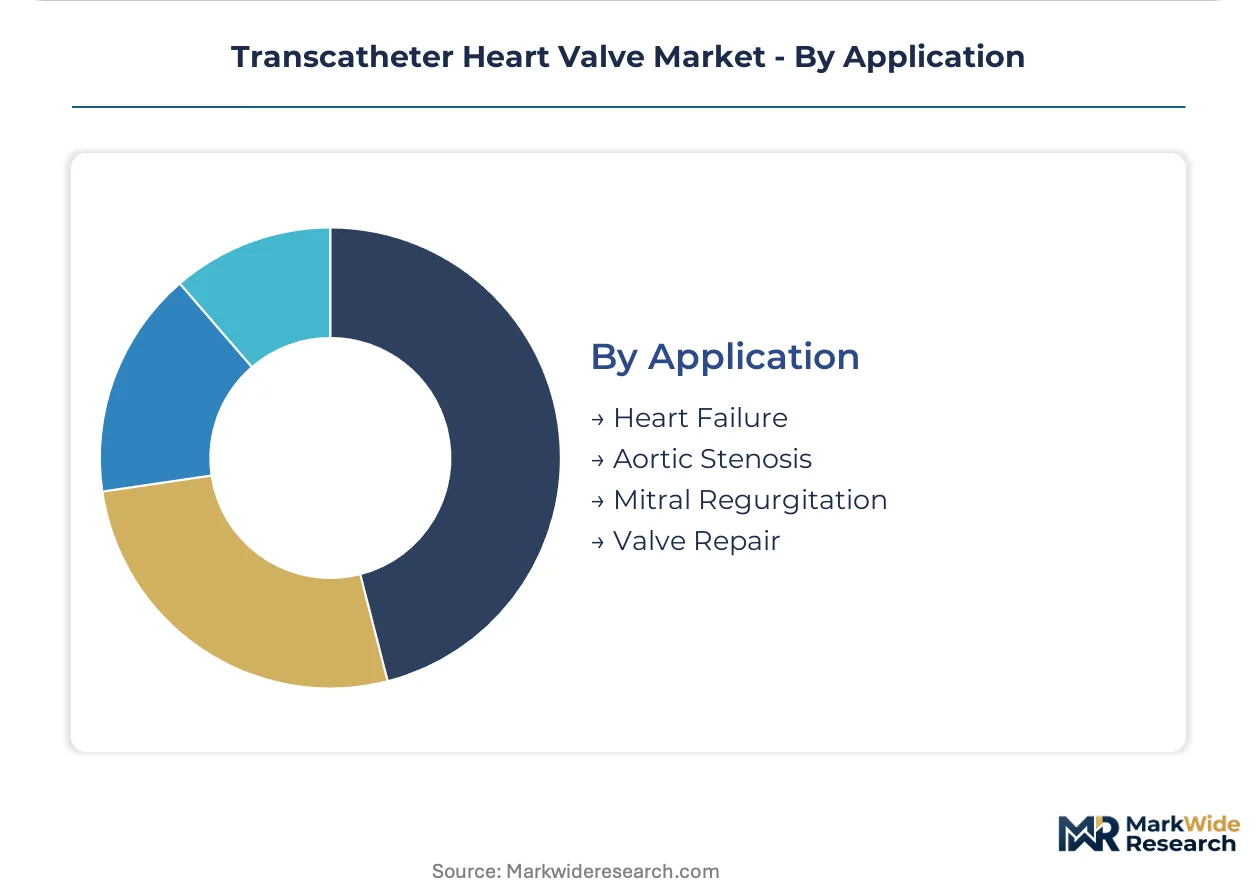
Application:
Clinical indication severity and comparator therapy availability shape procurement in this category.
- Heart Failure:Functional mitral regurgitation and secondary valve dysfunction drive demand for transcatheter repair as destination therapy.
- Aortic Stenosis:Severe native valve calcification with symptomatic obstruction represents the foundational indication. Established clinical evidence and guideline recommendations concentrate procedure volumes in United States and German healthcare systems.
- Mitral Regurgitation:Primary and secondary regurgitation patterns create heterogeneous treatment algorithms. Transcatheter edge-to-edge repair gains traction where surgical risk scores exclude conventional intervention.
- Valve Repair:Preservative techniques address annular dilatation and leaflet prolapse without complete valve replacement.
Aortic stenosis anchors current procedure volumes; mitral regurgitation applications expand most quickly as repair technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cardiac centers outpace Japanese facilities in transcatheter aortic valve replacement volumes, yet Tokyo's octogenarian patient base is expanding faster than any European metropolitan cluster.
United States
FDA breakthrough device designations compress commercialization timelines for novel valve systems targeting calcified anatomies. The agency's premarket approval pathways reward manufacturers who invest in predicate-busting clinical evidence packages. Academic medical centers in Boston and Cleveland anchor demand through structural heart fellowship pipelines and hybrid operating room investments.
Germany
Cardiac centers in Munich and Hamburg drive adoption through standardized outcome registries and operator certification requirements. EU MDR conformity assessments under notified body supervision shape product development timelines and clinical evidence requirements. Surgical aortic valve replacement remains the comparator standard for patients under 75, creating reimbursement stratification around durability benchmarks.
Japan
Tokyo and Osaka cardiac centers report transfemoral procedure volumes climbing fastest among octogenarians previously excluded from surgical valve replacement due to frailty indices. PMDA regulatory pathways align with super-aged society demographics expanding treatable populations. METI industrial policy supports domestic catheter assembly investments targeting regional hospital chains.
China
NMPA medical device registration pathways govern bioprosthetic valve approvals for aging urban populations in Shanghai and Beijing. Cobalt-chromium powder supply concentration in domestic mining operations creates input cost dynamics for stent frame manufacturers. The country's dual carbon goals influence sterilization facility energy compliance standards.
India
Domestic manufacturing incentives under the PLI scheme attract catheter assembly investments targeting price-sensitive private hospital chains in Mumbai and Delhi. CDSCO medical device regulations govern import substitution strategies for cardiac implantables. Procurement committees in metropolitan cardiac centers seek to reduce dependency on European and North American supply chains.
Transcatheter Heart Valve Market Competitive Landscape
Top-tier vendors anchor premium transcatheter platforms, while mid-cap specialists occupy navigational catheter and repair indication niches. The vendor base stratifies around delivery mechanism precision, with balloon-expandable and self-expanding stent geometries defining competitive boundaries. Three archetypes dominate: integrated cardiovascular conglomerates, structural heart pure-plays, and emerging Asia-Pacific challengers. Consolidation pressures favor M&A activity targeting complementary repair technologies and geographic expansion into underpenetrated cardiac center networks.
Within the integrated cardiovascular conglomerate tier, Edwards Lifesciences Corporation and Medtronic occupy positions exemplifying divergent stent platform philosophies, while Abbott anchors the navigational catheter and multi-valve indication strategy. These three entities represent the competitive spectrum from balloon-expandable precision engineering to self-expanding nitinol frameworks and catheter-based mitral repair diversification.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| JenaValve Technology |
| Meril Life Sciences |
| Venus Medtech |
| Braile Biomédica |
| LivaNova |
| Others |
Value Network & Pricing Analysis
Cobalt-chromium powder price volatility cascades through transcatheter heart valve manufacturing into tiered pricing structures that separate premium balloon-expandable platforms from standard self-expanding alternatives. Input cost unpredictability from mining concentration in China and Russia compresses gross margins on high-precision stent frames while rewarding manufacturers with captive nitinol supply arrangements.
Pricing Analysis
Capacity additions in domestic catheter assembly facilities across India are reshaping price floors for standard-grade transcatheter valves in Asia-Pacific private hospital chains. Three-tier pricing structure across premium, standard, and economy levels stratifies around FDA breakthrough designation status and CE marking tier under EU MDR. Pricing pressure stems from sterilization facility validation delays following EPA emissions enforcement actions. Community hospitals with limited structural heart fellowship programs exhibit highest price sensitivity; academic medical centers with hybrid operating room investments demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital procurement channels handle high-volume valve demand from United States integrated delivery networks and German cardiac center consortia. Manufacturing concentration in China, Germany, and the United States anchors nitinol stent frame and bioprosthetic leaflet production. The supply chain draws from cobalt-chromium alloys, bovine pericardial tissue, and ethylene oxide sterilization services. Single-source vulnerability in notified body capacity for EU MDR conformity assessments creates CE marking timeline risk. Distribution runs through specialized cardiovascular device distributors and direct manufacturer contracts with GPO-affiliated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transcatheter heart valve market compounds steadily as aging demographics in Japan, Germany, and the United States expand addressable patient populations beyond surgical risk thresholds.
For Market Incumbents: Deepen proprietary balloon-expandable platform investments to defend against self-expanding nitinol alternatives gaining share in transfemoral access routes. Secure captive cobalt-chromium powder supply through backward integration into mining partnerships or long-term offtake agreements with Chinese and Russian suppliers. Expand sterilization facility footprints ahead of EPA capacity constraints to ensure batch release velocity. For New Entrants and Emerging Players: Community hospital cardiac centers lacking structural heart fellowship programs represent the most penetrable buyer archetype for operator-agnostic deployment systems with integrated AI-guided imaging. Tricuspid regurgitation repair platforms navigate anatomical complexity that has delayed incumbent solutions. Pursue India's PLI scheme domestic manufacturing incentives to serve price-sensitive private hospital chains in Mumbai and Delhi with reduced import dependency. For Investors and Strategic Acquirers: Consolidation pressure builds where patent thickets around nitinol stent geometries and leaflet attachment mechanisms elevate litigation risk for standalone entrants. The market supports long-term viability for structural heart pure-plays with differentiated repair indications beyond aortic stenosis. Target acquisition profiles center on navigational catheter portfolios compatible across multiple valve indications. Monitor FDA breakthrough device designation velocity as inflection signal for competitive entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments under notified body supervision govern commercial access timelines for Class III implantable devices. |
| Hospital System Partnership | United States integrated delivery networks negotiate multi-year contracts tying valve pricing to aggregate procedural volume commitments. |
| Software Companion Development | EU AI Act risk classification frameworks impose conformity obligations on imaging-guided deployment algorithms automating annular sizing. |
| Reimbursement Strategy | German cardiac centers stratify procurement around surgical valve durability benchmarks for patients under 75 years. |
| Backward Integration | Captive cobalt-chromium powder supply mitigates input cost unpredictability from Chinese and Russian mining concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture procedural volume trends and procurement committee decision criteria. Primary discussions engaged interventional cardiologists, hospital purchasing committee members, biomedical engineers specializing in structural heart devices, and GPO contracts managers at United States integrated delivery networks. Secondary validation drew from FDA premarket approval filings, EU MDR notified body conformity assessment databases, hospital procurement registries, and CMS Medicare procedure volume data. Bottom-up manufacturer shipment analysis triangulated against top-down cardiac center capacity estimates.
Segment-weighting approaches distributed value across aortic, mitral, pulmonary, and tricuspid valve product types; transfemoral, transapical, transaortic, and direct aortic delivery modes; and hospital, cardiac center, outpatient clinic, and research institution end users. CAGRs derived from regression analysis against demographic aging curves and procedural adoption velocity across the projection horizon. Industry-specific forecast inputs incorporated PMDA regulatory pathway timelines in Japan and CDSCO medical device registration trajectories in India.
Underlying measurement precision varies by segment; aortic valve replacement volumes carry tighter precision than emerging tricuspid repair applications. Forecasts reflect assumptions around reimbursement stability, sterilization facility capacity recovery, and cobalt-chromium supply chain continuity. Regulatory pathway delays, notified body capacity constraints, or bioprosthetic leaflet durability skepticism among referring cardiologists could materially revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Aortic Aneurysm Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market