
 Endovascular Stent Market | 2026-2036
Endovascular Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Endovascular Stent Market Analytics
Ireland is reconfiguring its medtech manufacturing footprint through expanded cleanroom capacity serving European and North American distribution. Abbott Laboratories anchors its vascular device portfolio with integrated stent delivery systems manufactured at its Galway facilities. Boston Scientific Corporation competes through sustained R&D intensity across coronary and peripheral stent platforms. Medtronic plc leverages its operational scale to control supply chain costs across balloon-expandable and self-expanding product lines.
An endovascular stent is a tubular metallic or polymeric scaffold deployed via catheter to restore luminal patency in diseased blood vessels, typically manufactured from cobalt-chromium alloys or nitinol with strut thicknesses below 100 micrometers to optimize flexibility and radial strength. Its primary purpose is to prevent acute vessel closure and reduce restenosis following percutaneous intervention. Drug-eluting stents command the dominant margin pool due to sustained premium pricing tied to antiproliferative coating technologies, while self-expanding nitinol platforms lead growth in peripheral artery disease applications where vessel tortuosity demands conformability. Hospitals remain the concentrated end-user channel, though ambulatory surgical centers are capturing selective coronary cases as reimbursement shifts toward lower-acuity settings.
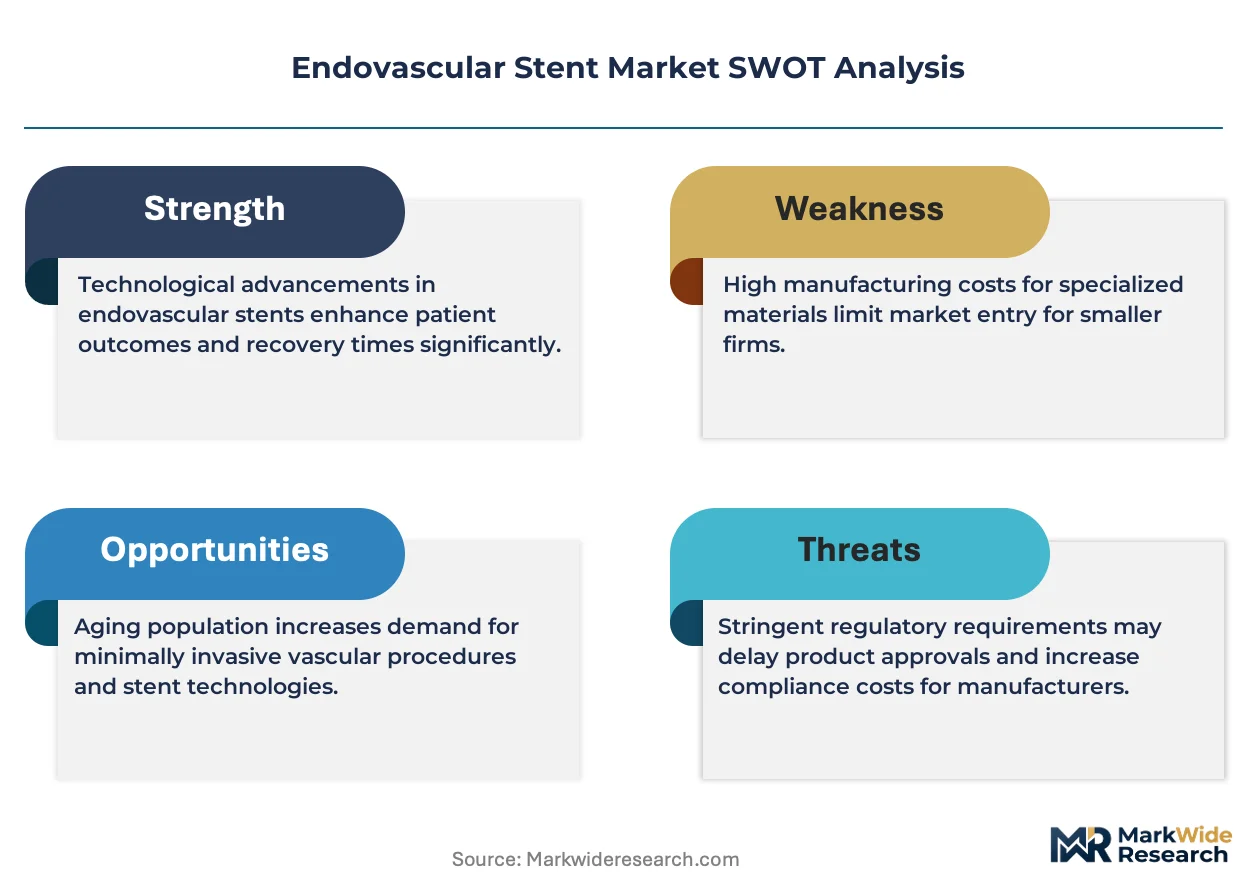
FDA premarket approval requirements and the EU Medical Device Regulation impose escalating clinical evidence and post-market surveillance burdens on manufacturers seeking commercial access. The FDA's emphasis on long-term safety data for drug-eluting platforms extends development timelines and raises capital requirements for new entrants. Stakeholders must monitor how Health Technology Assessment bodies in Germany and France calibrate reimbursement for bioresorbable scaffold alternatives against established metallic benchmarks.
Market Dynamics
Drug-eluting stent platforms face compressed development timelines as FDA demands extend into five-year follow-up protocols, forcing manufacturers to front-load clinical infrastructure before revenue recognition.
Growth Catalysts
- EU MDR transition:Stricter post-market surveillance requirements under the Medical Device Regulation are accelerating consolidation among notified bodies, favoring established manufacturers with dedicated regulatory affairs teams.
- Catheterization lab expansion:Hospital systems in the United States are building dedicated peripheral intervention suites, creating dedicated procedure volume for complex femoropopliteal cases.
- Nitinol processing advances:Laser-cut tubing with sub-80-micron strut thickness is enabling next-generation self-expanding platforms with improved deliverability through tortuous anatomy.
Market Restraints
- Cobalt-chromium alloy supply:Concentrated sourcing from specialty metallurgical suppliers in Germany creates input cost volatility for balloon-expandable coronary platforms.
- Bioresorbable scaffold failure:Technical limitations in poly-l-lactic acid degradation kinetics have stalled adoption, with ABSORB trial outcomes dampening physician confidence in non-metallic alternatives.
- Health Technology Assessment friction:France's HAS and Germany's IQWiG impose incremental evidence requirements for premium stent reimbursement, extending commercial access timelines.
Strategic Opportunities
- India's procedural gap:Coronary intervention penetration remains below 15 procedures per 100,000 population versus 80-plus in Western Europe, creating whitespace for training infrastructure investment.
- Transcatheter renal denervation:Convergence of radiofrequency ablation catheters with established femoral access workflows opens adjacent procedure volumes for integrated delivery system manufacturers.
- ASC channel development:Ambulatory surgical centers in the United States are capturing low-complexity coronary cases as site-of-service payment differentials widen against hospital outpatient departments.
Industry Challenges
- Polymer coating expertise:Scarce formulation scientists with sirolimus-analog elution profile experience command premium compensation, constraining R&D team scaling.
- PMA supplement backlog:FDA premarket approval pathway modifications for drug-eluting stent design changes average 180-day review cycles, compressing product iteration velocity.
- Legacy sterilization validation:Ethylene oxide facility closures in the United States are forcing supply chain reconfiguration for terminal sterilization of delivery system components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endovascular Stent Market |
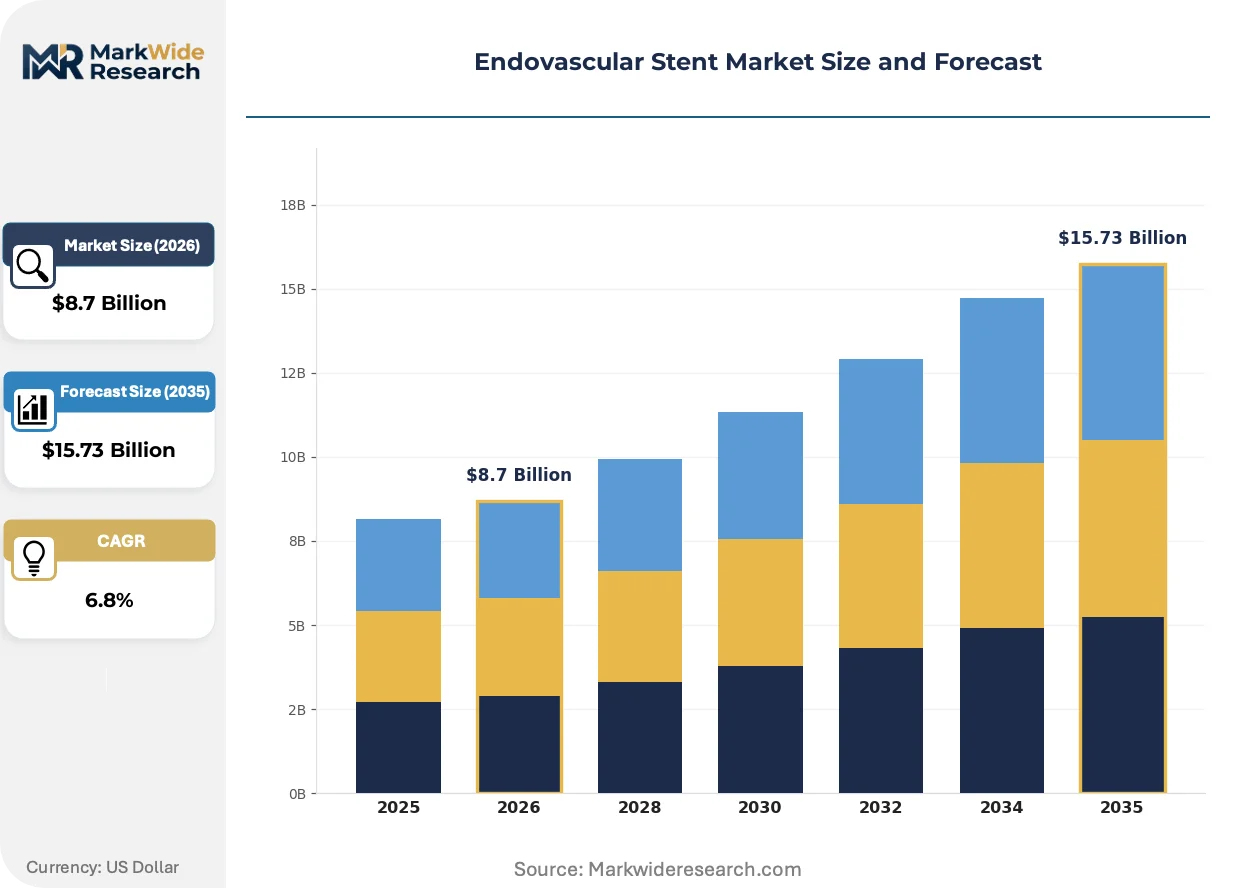
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon-Expandable, Self-Expanding, Covered, Drug-Eluting End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Material: Metal Alloy, Biodegradable Polymer, Coated Stainless Steel, Hybrid Material Application: Peripheral Artery Disease, Coronary Artery Disease, Carotid Artery Disease, Renal Artery Stenosis |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic plc, B. Braun Melsungen AG, Terumo Corporation, Biotronik SE & Co. KG, Cook Medical, W. L. Gore & Associates, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endovascular Stent Market Evolving Landscape
Endovascular stent technology is bifurcating between ultra-thin metallic platforms and bioengineered surface modifications, with manufacturing precision and coating chemistry becoming the primary vectors of differentiation.
Thin-strut cobalt-chromium architectures with biodegradable polymer coatings are hybridizing coronary intervention workflows, enabling operators to treat complex bifurcation lesions through single-stent techniques. Academic medical centers in Germany and the Netherlands are piloting these platforms in left main disease protocols. The structural consequence is compression of two-stent procedure volumes and associated inventory complexity.
REACH authorization requirements for nitinol raw material traceability are reshaping European supply chain documentation, with ECHA mandating substance-of-very-high-concern declarations for nickel alloy feedstock. Manufacturers with captive metallurgical partnerships in Ireland and Switzerland are absorbing compliance costs more efficiently than contract-dependent competitors. Peripheral stent product lines face the steepest documentation burden given higher nickel surface area exposure.
Hospital purchasing consortiums in the United States are consolidating stent procurement through single-source agreements with performance guarantees, displacing traditional multi-vendor stocking models. Integrated delivery networks in Texas and Florida are leading this consolidation, extracting volume commitments in exchange for exclusive catheterization lab access. The shift is most visible in coronary drug-eluting stent categories where product differentiation has narrowed.
Endovascular Stent Market Segmentation
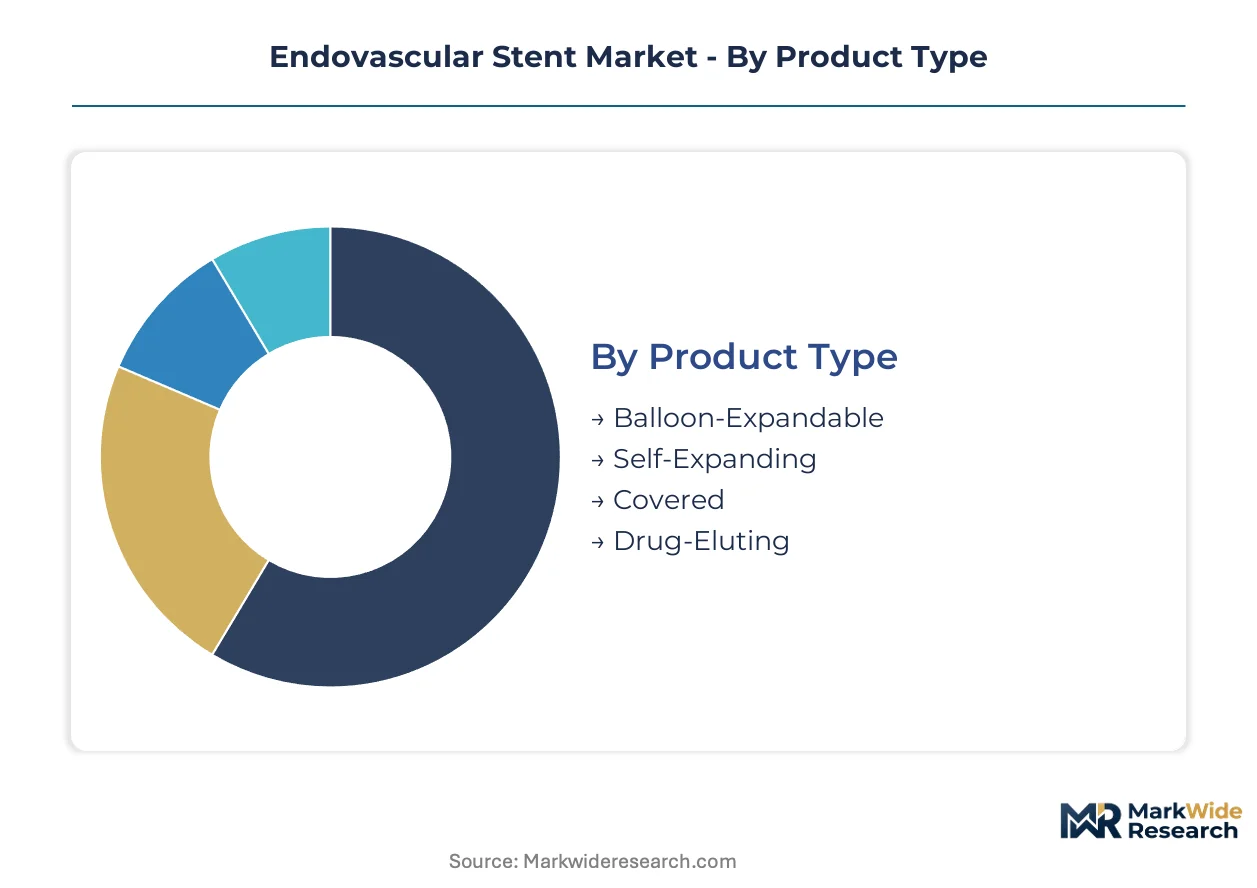
Endovascular stent purchasing patterns diverge sharply across clinical settings and vascular territories, with reimbursement pathways and procedure complexity dictating product mix at the account level. Manufacturers configure sales coverage and technical service teams differently for each segment, as catheterization lab relationships require sustained clinical education investment.
Product Type:
After-sales service intensity peaks with drug-eluting platforms, where clinical specialists must train interventional cardiologists on antiproliferative coating handling and lesion preparation protocols.
- Drug-Eluting:These stents incorporate sirolimus-analog coatings on metallic scaffolds to suppress neointimal hyperplasia. United States hospital systems concentrate demand here, driven by Medicare reimbursement differentials that reward restenosis reduction outcomes. FDA premarket approval requirements extend development timelines and elevate field clinical specialist deployment.
- Self-Expanding:Manufactured from laser-cut nitinol tubing, these platforms deploy via sheath withdrawal rather than balloon inflation. Peripheral intervention suites in Germany and the Netherlands favor this technology for femoropopliteal cases where vessel tortuosity demands conformability. REACH documentation requirements for nickel alloy traceability add compliance overhead.
- Balloon-Expandable:Cobalt-chromium alloys enable thin-strut designs with high radial strength for coronary applications. Supply chain concentration in German metallurgical suppliers creates input cost volatility.
- Covered:Expanded polytetrafluoroethylene or polyester fabric bonded to metallic frames excludes aneurysm sacs from circulation. TAAA and TEVAR procedures in academic medical centers drive selective adoption.
By volume, balloon-expandable platforms lead in coronary procedures. By growth pace, self-expanding systems are gaining share fastest in peripheral applications.
End User:
Customer type determines contract structure, with integrated delivery networks extracting performance guarantees unavailable to standalone facilities.
- Hospitals:Catheterization labs and hybrid operating suites handle complex multivessel disease and emergent STEMI cases. United States IDNs in Texas and Florida consolidate procurement through single-source agreements with exclusive access commitments.
- Ambulatory Surgical Centers:Lower-acuity coronary interventions migrate to these settings as site-of-service payment differentials widen against hospital outpatient departments. Staffing models emphasize procedure efficiency over research participation.
- Specialty Clinics:Peripheral vascular clinics in Germany perform diagnostic angiography and selective intervention without full surgical backup. IQWiG assessment timelines delay premium product adoption.
- Diagnostic Laboratories:Standalone imaging centers identify disease burden but rarely deploy definitive therapy, creating upstream referral relationships with interventionists.
By procedure count, hospitals dominate. By expansion trajectory, ambulatory surgical centers are climbing the fastest.
Material:
Margin structure varies with material processing complexity, with biodegradable polymers commanding development premiums despite commercial headwinds.
- Metal Alloy:Cobalt-chromium and platinum-iridium formulations balance radial strength and fluoroscopic visibility. Established supply chains in Ireland and Switzerland serve European and North American distribution.
- Biodegradable Polymer:Poly-l-lactic acid scaffolds degrade over 24-36 months to restore vessel vasomotion. ABSORB trial outcomes have dampened physician confidence and stalled adoption.
- Coated Stainless Steel:316L stainless steel with passive oxide layers offers cost positioning for price-sensitive markets. India’s procedural gap below 15 interventions per 100,000 population sustains demand for economical platforms.
- Hybrid Material:Metallic scaffolds with bioabsorbable polymer coatings combine mechanical performance with temporary drug delivery. Academic medical centers in the Netherlands pilot these in left main disease protocols.
By installed base, metal alloy platforms lead. By innovation investment, hybrid materials are expanding most quickly.
Application:
Procedure reimbursement and clinical evidence requirements shape competitive intensity across vascular territories.
- Coronary Artery Disease:Complex bifurcation and left main interventions drive thin-strut platform development. FDA five-year follow-up protocols for drug-eluting stents front-load clinical infrastructure costs.
- Peripheral Artery Disease:Femoropopliteal and below-the-knee disease demand flexibility and fracture resistance. Nitinol processing advances with sub-80-micron strut thickness improve deliverability through tortuous anatomy.
- Carotid Artery Disease:Embolic protection devices accompany stent deployment to mitigate stroke risk. Transfemoral and transcarotid access techniques create training infrastructure requirements.
- Renal Artery Stenosis:Transcatheter renal denervation convergence opens adjacent procedure volumes for integrated delivery system manufacturers. Hypertension management guidelines influence referral patterns.
By procedure volume, coronary applications lead. By unmet need expansion, peripheral artery disease shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor commercial access in the United States, while EU MDR transition and REACH nickel traceability requirements reshape European manufacturing economics. Hospital procurement consolidation and catheterization lab expansion drive differentiated growth trajectories across major markets.
United States
Medicare reimbursement policies sustain procedure volumes for drug-eluting platforms, with hospital systems in Texas and Florida consolidating procurement through single-source agreements. FDA five-year follow-up protocols for new drug-eluting stent approvals front-load clinical infrastructure costs for manufacturers. Greater Boston and Minneapolis-St. Paul anchor vascular device R&D clusters where integrated delivery networks extract exclusive catheterization lab access commitments.
Germany
IQWiG assessment timelines delay premium product reimbursement for bioresorbable scaffold alternatives against metallic benchmarks. REACH authorization requirements for nitinol raw material traceability mandate substance-of-very-high-concern declarations for nickel alloy feedstock. Academic medical centers in Munich and Heidelberg pilot thin-strut cobalt-chromium platforms in left main disease protocols, compressing two-stent procedure volumes.
China
NMPA regulatory harmonization with international standards accelerates domestic manufacturer capability building in cobalt-chromium laser-cut tubing. Centralized procurement reforms in coronary stent categories compress pricing premiums previously enjoyed by multinational suppliers. Shanghai and Suzhou concentrate nitinol processing and polymer coating infrastructure serving Asia-Pacific distribution.
India
Coronary intervention penetration below 15 procedures per 100,000 population creates whitespace for training infrastructure investment and economical platform demand. CDSCO medical device registration pathways impose escalating clinical evidence requirements for drug-eluting stent commercial access. Maharashtra and Gujarat host contract manufacturing clusters supplying coated stainless steel platforms for price-sensitive markets.
Switzerland
Swissmedic post-market surveillance requirements align with EU MDR stringency, favoring established manufacturers with dedicated regulatory affairs teams. Captive metallurgical partnerships in Schaffhausen and Vaud absorb REACH compliance costs more efficiently than contract-dependent competitors. Geneva and Basel anchor precision manufacturing for sub-80-micron strut nitinol platforms serving European peripheral intervention suites.
Endovascular Stent Market Competitive Landscape
Capability concentration sits with integrated device manufacturers possessing captive polymer coating expertise and dedicated regulatory infrastructure; scale advantage sits with diversified medtech conglomerates controlling supply chain costs across balloon-expandable and self-expanding product lines. The market structures around three archetypes: integrated stent delivery system specialists, diversified cardiovascular portfolio holders, and regional contract manufacturers. Dominant competitive moves include backward integration into nitinol raw material processing and strategic consolidation of catheterization lab service contracts.
Within the integrated delivery system tier, Abbott Laboratories and Boston Scientific Corporation exemplify capability concentration through vascular device portfolio breadth. Medtronic plc occupies a position representing scale-driven supply chain control across metallic and polymeric scaffold platforms. Among European-based manufacturers, B. Braun Melsungen AG and Biotronik SE & Co. KG sit within the specialized peripheral intervention segment, anchoring regional regulatory compliance expertise.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic plc |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Biotronik SE & Co. KG |
| Cook Medical |
| W. L. Gore & Associates |
| MicroPort Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors channel cobalt-chromium alloy shipments from German metallurgical suppliers to Irish cleanroom facilities, with container rate volatility feeding directly into balloon-expandable stent cost structures and amplifying price spreads between premium drug-eluting platforms and economy-tier coated stainless steel alternatives.
Pricing Analysis
Geographic price spreads between United States hospital systems and Indian procurement channels exceed three-to-one ratios for equivalent cobalt-chromium platforms. Pricing stratifies across premium drug-eluting, standard balloon-expandable, and economy coated stainless steel tiers, with FDA premarket approval tiers and CE marking status serving as primary differentiation drivers. Cost compression in the standard tier intensifies as Chinese centralized procurement reforms compress multinational premiums. Ambulatory surgical centers exhibit highest price sensitivity due to site-of-service reimbursement differentials, while academic medical centers with research participation requirements show lowest sensitivity.
Supply Chain Analysis
REACH authorization requirements for nickel alloy traceability function as de facto export controls on nitinol raw material flows into European manufacturing zones. Supply concentrates in Germany for cobalt-chromium feedstock, Ireland for cleanroom assembly, and Switzerland for precision nitinol processing. Raw material dependencies include specialty metallurgical alloys, laser-cut tubing, and biodegradable polymer coatings. Single-source vulnerability concentrates in German cobalt-chromium suppliers. Distribution runs through hospital purchasing consortiums and integrated delivery networks with exclusive access commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endovascular stent platforms are approaching a platform-economics inflection where integrated delivery system partnerships and catheterization lab service contracts create interoperability moats that transcend individual product specifications.
For Market Incumbents: Entrench catheterization lab relationships through exclusive service contracts with performance guarantees, while backward integration into nitinol raw material processing insulates against REACH documentation cost inflation. Bioresorbable scaffold technical failures and polymer coating expertise scarcity threaten premium positioning; captive metallurgical partnerships in Ireland or Switzerland provide defensive leverage. For New Entrants and Emerging Players: Build out training infrastructure in India's underpenetrated coronary intervention market, where procedural volumes below 15 per 100,000 population create whitespace for economical platform penetration. Peripheral artery disease applications in Germany and the Netherlands offer fastest adoption curves for self-expanding nitinol platforms; target specialty clinics with IQWiG assessment navigation services as differentiated go-to-market angle. For Investors and Strategic Acquirers: Polymer coating formulation specialists with sirolimus-analog elution expertise represent priority acquisition targets given scarce talent pools and front-loaded clinical infrastructure requirements. Long-term viability hinges on regulatory affairs scale advantages across FDA PMA pathways and EU MDR transition; watch for PMA supplement backlog resolution velocity as inflection signal for product iteration capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Catheterization Lab Partnership | Exclusive service contracts with Texas and Florida IDNs lock in procedure volume commitments. |
| Nitinol Processing Investment | Sub-80-micron strut manufacturing in Schaffhausen and Galway absorbs REACH compliance overhead. |
| FDA Premarket Approval Pathway | Five-year follow-up protocol completion separates viable drug-eluting platforms from stranded R&D. |
| India Training Infrastructure | Procedural penetration gaps below Western European benchmarks create whitespace for platform adoption. |
| Bioresorbable Scaffold Recalibration | Poly-l-lactic acid degradation kinetics refinement addresses ABSORB trial outcome dampening. |
Research Methodology
A standing panel of interventional cardiologists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers provided ongoing calibration against secondary validation from FDA PMA filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement consortium records. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates.
Scenario-bracketing around regulatory pathway delays and reimbursement policy shifts anchored projections across the analysis window. Segmentation dimensions modeled include stent platform type, vascular territory application, end-user facility category, and material composition tier. CAGRs derived from procedure volume trajectories, pricing tier evolution, and technology substitution rates, with nitinol processing yield improvements and polymer coating formulation advances serving as key forecast inputs.
Sensitivities concentrate around FDA PMA supplement review cycle extensions, EU MDR notified body consolidation timelines, and REACH nickel traceability enforcement intensity. Forecasts reflect assumptions on catheterization lab expansion rates and centralized procurement reform velocity. Material shifts in Medicare site-of-service reimbursement differentials or bioresorbable scaffold clinical evidence regeneration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market