
 Global Robotic Assisted Surgery Systems Market | 2026-2036
Global Robotic Assisted Surgery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Assisted Surgery Systems Market Foresight
Software-defined service layers including predictive maintenance subscriptions and AI-assisted surgical planning modules is pivoting vendor relationships from capital sales to recurring revenue partnerships. Intuitive Surgical leverages its installed base of da Vinci systems to sustain aftermarket revenue streams across training and instrument replenishment. Stryker competes through its Mako platform's orthopedic specialization, while Medtronic anchors its broader surgical portfolio with integrated navigation and robotic capabilities.
Robotic assisted surgery systems comprise electromechanical platforms with sub-millimeter precision actuators, stereoscopic imaging chains, and surgeon console interfaces that translate hand motions into filtered instrument movements inside the patient body. These systems typically operate at bandwidths exceeding 1 kHz for latency-critical haptic feedback loops, enabling minimally invasive procedures that reduce tissue trauma and recovery times compared to open surgery. Surgical robots and robotic arms occupy the core hardware tier where capital intensity and replacement cycles concentrate manufacturer margins, while AI-assisted surgery and haptic systems represent the fastest-expanding technology layers as hospitals prioritize outcome consistency and surgeon training efficiency. Navigation systems and 3D visualization modules serve as the connectivity tissue integrating preoperative imaging with real-time anatomical guidance.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for system manufacturers seeking market access. ISO 13485 quality management standards and IEC 60601 electrical safety protocols govern manufacturing consistency across Intuitive Surgical's California production, Stryker's Michigan facilities, and Medtronic's Irish and Costa Rican operations. China's NMPA registration requirements and Japan's PMDA orphan device reviews add country-specific validation layers that extend commercialization lead times. Stakeholders must monitor how FDA's evolving software-as-medical-device guidance and the EU AI Act's risk classification framework apply to autonomous surgical decision-support features.
Market Dynamics
Software-as-a-medical-device frameworks and AI-enabled surgical planning modules are restructuring vendor-hospital relationships from one-time capital transactions toward recurring revenue architectures. This shift compresses replacement cycles while embedding manufacturers deeper into clinical workflows.
Growth Catalysts
- EU MDR conformity pathways:Streamlined device registration under the Medical Device Regulation accelerates commercialization timelines for robotic platforms seeking European market access.
- Orthopedic surgical volumes:Knee and hip arthroplasty programs in Germany and the United States are standardizing robotic assistance for implant alignment precision.
- Haptic feedback bandwidth:Sub-millisecond latency systems enable force-sensitive tissue manipulation that expands procedural applicability beyond static positioning tasks.
Market Restraints
- Capital equipment intensity:Surgeon console and patient cart configurations require substantial upfront investment that constrains adoption at mid-tier hospitals.
- Supply concentration in precision actuators:Japanese and German component specialists control high-torque miniature motor supply chains for robotic arm joints.
- FDA software-as-medical-device guidance:Evolving classification criteria for autonomous decision-support features create validation uncertainty and extend development timelines.
Strategic Opportunities
- India's tertiary hospital expansion:Corporate hospital chains in Mumbai, Delhi, and Bangalore are deploying capital for robotic surgery centers targeting medical tourism flows.
- AI-assisted preoperative planning convergence:Integration of patient-specific imaging with real-time anatomical mapping creates differentiated service tiers.
- Japan's PMDA orphan device reviews:Expedited pathways for novel surgical indications reduce time-to-revenue for specialized robotic applications.
Industry Challenges
- Surgeon training credentialing:Proctored case requirements and simulator validation protocols extend onboarding timelines for new robotic systems.
- Legacy navigation system interoperability:Integration with existing imaging archives and EMR architectures demands custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Assisted Surgery Systems Market |
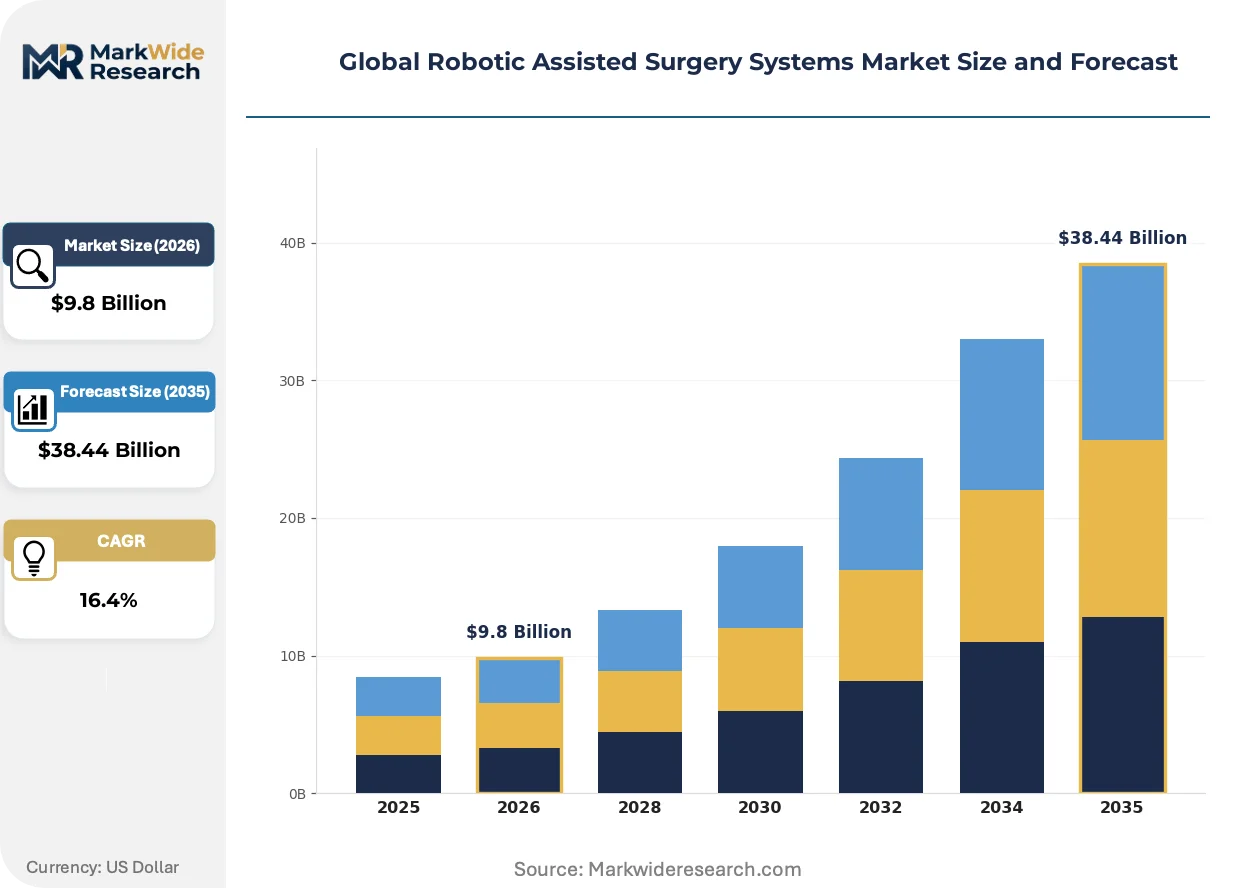
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Robotic Arms, Navigation Systems, Imaging Devices, Endoscopic Instruments Technology: Force Feedback, 3D Visualization, AI-Assisted Surgery, Haptic Systems, Telepresence Controls Application: Gynecology, Urology, Orthopedic Procedures, Cardiothoracic Operations, Neurosurgery End User: Hospitals, Ambulatory Surgical Centers, Research Institutes, Specialty Clinics, Academic Medical Centers |
| Companies Covered | Intuitive Surgical, Stryker, Medtronic, Johnson & Johnson, Zimmer Biomet, Smith & Nephew, Accuray, CMR Surgical, Asensus Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Assisted Surgery Systems Market Shifts & Advancements
Electromechanical architectures, regulatory frameworks, and procurement models are simultaneously evolving to prioritize outcome consistency over hardware specifications. This convergence favors vendors capable of bundling predictive maintenance with clinical training ecosystems.
Digital twin technology is integrating preoperative simulation with intraoperative guidance to reduce anatomic variability errors. Leading academic medical centers in the United States and South Korea are deploying patient-specific organ models for procedure rehearsal. This capability is integrating surgical planning with supply chain forecasting, enabling just-in-time instrument sterilization and reducing OR turnover delays.
China's NMPA registration requirements are tightening clinical evidence standards for robotic surgical systems, mandating domestic trial participation for market authorization. This policy shift is forcing multinational manufacturers to establish local clinical affairs teams and partner with Chinese principal investigators. The regulatory friction most affects orthopedic and urological platforms where domestic competitors are advancing competitive submissions.
Hospital procurement committees are consolidating vendor relationships around comprehensive service agreements that bundle capital equipment, disposable instruments, and surgeon training into per-procedure fees. This model displaces traditional capital purchase cycles with multiyear partnerships. The United States and Germany exhibit the fastest transition toward these consumption-based arrangements, particularly among integrated delivery networks managing multiple surgical sites.
Global Robotic Assisted Surgery Systems Market Segmentation
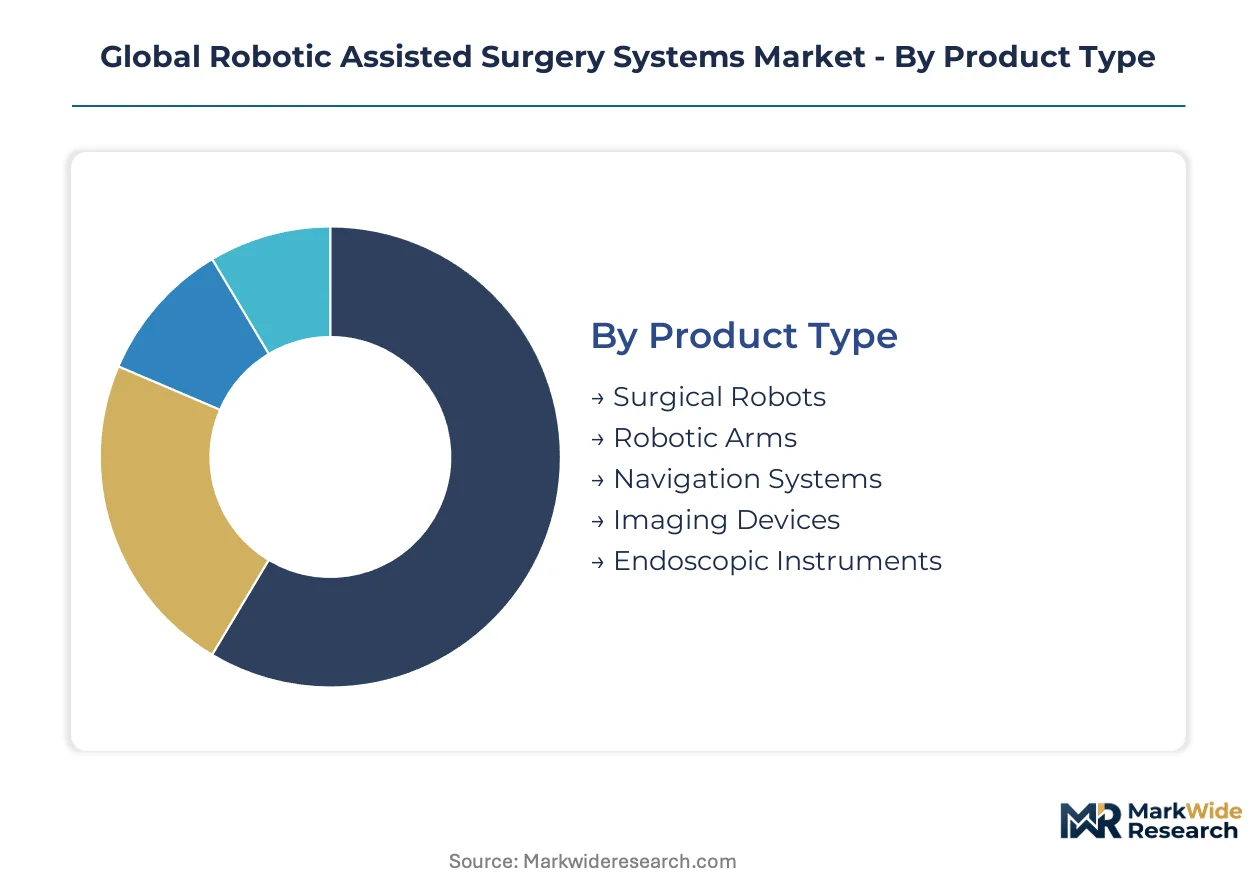
Segmentation in robotic assisted surgery systems reveals how procurement priorities diverge across clinical settings. Capital allocation patterns, reimbursement frameworks, and procedural volumes create distinct demand profiles that manufacturers must address through specialized platform configurations.
Product Type:
Purchasing decisions in this category hinge on replacement cycle timing and consumable attachment rates rather than upfront hardware cost alone.
- Surgical Robots:Integrated electromechanical platforms combining surgeon consoles with patient-side manipulators. Demand concentrates at academic medical centers in the United States and Germany where high-volume programs justify capital intensity through per-procedure instrument replenishment revenue.
- Robotic Arms:Modular articulating manipulators with sub-millimeter precision actuators. Orthopedic service lines in Japanese and German hospitals prioritize these units for knee arthroplasty applications where implant alignment precision directly correlates with revision rates.
- Navigation Systems:Optical and electromagnetic tracking platforms that synchronize instrument position with preoperative imaging.
- Imaging Devices:Stereoscopic visualization chains delivering depth perception to surgeon consoles.
- Endoscopic Instruments:Single-use or limited-reuse graspers, scissors, and needle drivers with integrated force sensing.
Volume sits with surgical robots; growth tilts toward robotic arms as orthopedic standardization accelerates.
Technology:
Technology selection tracks surgeon training investment and liability exposure around autonomous decision-support features.
- Force Feedback:Sub-millisecond latency systems translating tissue resistance to surgeon hand controls. United States teaching hospitals prioritize these capabilities for resident training programs where tactile learning accelerates competency acquisition.
- AI-Assisted Surgery:Machine learning modules for anatomical identification and procedural step guidance. South Korean and Chinese facilities lead deployment as NMPA and MFDS frameworks clarify validation pathways for autonomous features.
- 3D Visualization:High-definition stereoscopic displays with depth-enhanced anatomical rendering.
- Haptic Systems:Vibration and resistance feedback mechanisms augmenting force data with texture discrimination.
- Telepresence Controls:Networked surgeon consoles enabling remote procedure participation.
Deployment concentrates in force feedback; capability expansion centers on AI-assisted surgery as regulatory clarity emerges.
Application:
Application mix reflects reimbursement adequacy and clinical evidence depth for robotic versus open or laparoscopic alternatives.
- Urology:Radical prostatectomy and partial nephrectomy procedures where nerve-sparing precision affects functional outcomes. German and United States urology programs anchor installed base expansion through established positive margin rate data.
- Orthopedic Procedures:Knee and hip arthroplasty with robotic assistance for implant positioning. Japanese orthopedic centers drive adoption as PMDA orphan device reviews expedite novel indication approvals.
- Gynecology:Hysterectomy and myomectomy applications with tissue morcellation constraints.
- Cardiothoracic Operations:Mitral valve repair and coronary bypass procedures requiring motion compensation for cardiac movement.
- Neurosurgery:Deep brain stimulation and tumor resection with stereotactic guidance.
Procedure volume clusters in urology; expansion momentum builds fastest in orthopedic procedures.
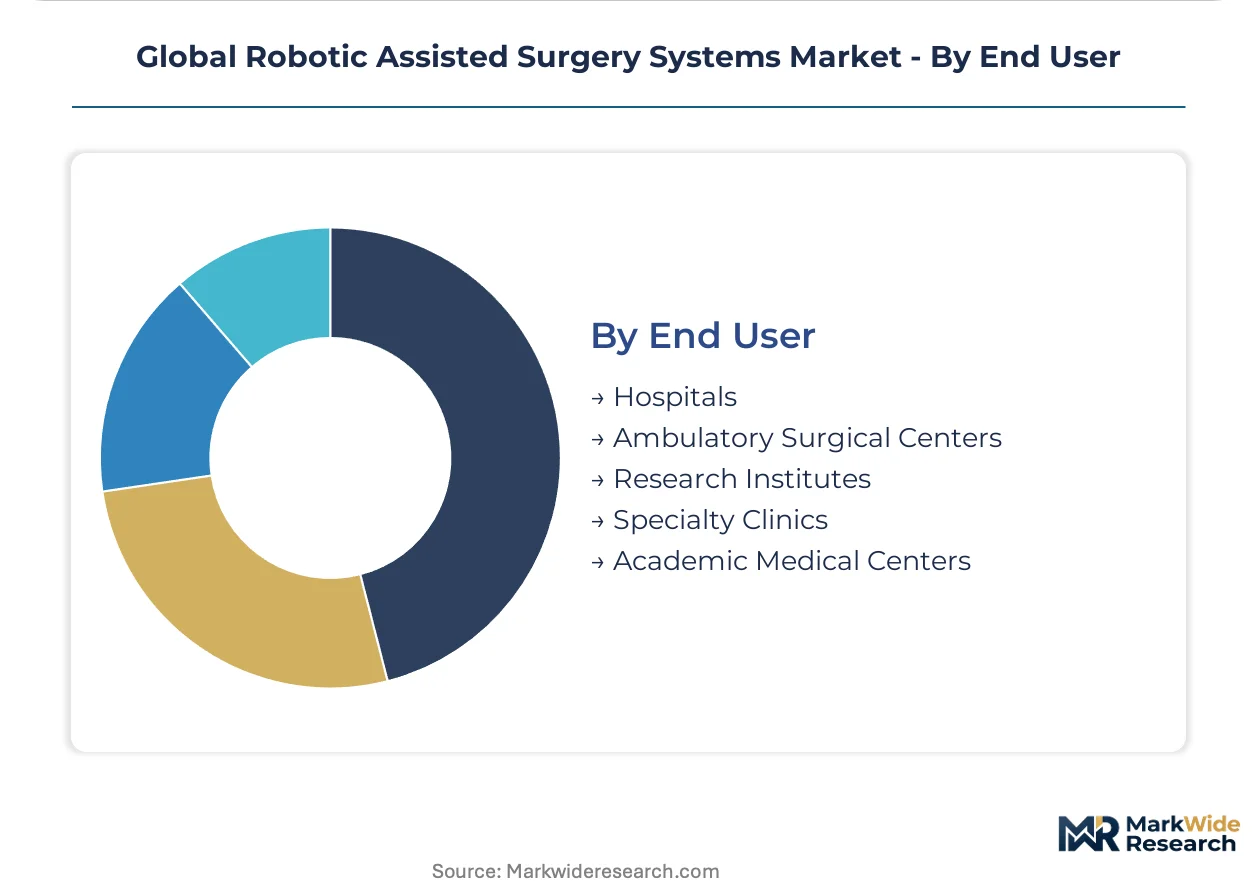
End User:
End user category separates capital capacity from procedural throughput requirements.
- Hospitals:Multi-service-line institutions with centralized sterile processing and dedicated robotic surgery coordinators. United States integrated delivery networks and German university hospitals concentrate procurement through enterprise agreements.
- Ambulatory Surgical Centers:Freestanding facilities performing same-day discharge procedures. Indian corporate hospital chains in Mumbai and Delhi deploy these configurations for medical tourism targeting.
- Academic Medical Centers:Teaching institutions with research mandates and residency programs.
- Specialty Clinics:Single-discipline practices focusing on high-volume specific procedures.
- Research Institutes:Preclinical and clinical trial sites evaluating novel robotic applications.
Installed base concentrates in hospitals; ambulatory surgical centers are climbing the fastest as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors installed base expansion for robotic surgery systems, with Stanford Health Care and UCSF Medical Center driving procedural volume growth through high-throughput urology and gynecology programs.
United States
Integrated delivery networks in Texas and Florida are consolidating vendor relationships around per-procedure service agreements that bundle capital equipment with disposable instrument replenishment. FDA premarket notification pathways for software-as-medical-device features are extending validation timelines for autonomous surgical planning modules. The Cleveland Clinic and Mayo Clinic anchor adoption clusters in the Midwest where academic medical centers prioritize force feedback systems for resident training programs.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are standardizing robotic assistance for knee arthroplasty as implant alignment precision data demonstrates revision rate reductions. EU MDR conformity assessments under the Medical Device Regulation are accelerating commercialization timelines for platforms seeking European market access. The Rhine-Ruhr metropolitan region concentrates orthopedic surgical volumes where robotic arm configurations dominate procurement specifications.
Japan
Metropolitan Tokyo hospitals are deploying capital for cardiothoracic robotic programs as PMDA orphan device reviews expedite approvals for novel surgical indications. METI industrial policy supports domestic component manufacturing for precision actuators used in robotic arm joints. The Osaka-Kobe corridor anchors demand for haptic feedback systems where surgeon training protocols emphasize tactile competency acquisition.
China
Corporate hospital chains in Shanghai and Beijing are expanding robotic surgery centers targeting domestic patient volumes and medical tourism flows. NMPA registration requirements now mandate domestic clinical trial participation for market authorization, forcing multinational manufacturers to establish local clinical affairs teams. The Yangtze River Delta concentrates tertiary hospital expansion where AI-assisted surgical planning modules are prioritizing regulatory validation.
India
Apollo Hospitals and Max Healthcare in Delhi-NCR and Mumbai are deploying capital for robotic surgery infrastructure targeting medical tourism from Gulf states and Southeast Asia. CDSCO medical device regulations are tightening quality management standards for imported surgical robot platforms. Bangalore's corporate hospital clusters are prioritizing navigation system integration with existing imaging archives and EMR architectures.
Global Robotic Assisted Surgery Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as the market structure consolidates around integrated platform vendors with substantial installed bases. Tier-one manufacturers with captive instrument supply chains extract recurring revenue through disposable replenishment, while mid-tier specialists concentrate on single-application orthopedic or urological configurations. Two dominant competitive moves are reshaping positioning: strategic partnerships between hardware vendors and AI software developers, and geographic expansion through localized clinical affairs teams in China and India.
Within the integrated platform tier, Intuitive Surgical and Stryker exemplify contrasting specialization strategies, with the former anchoring general surgery breadth and the latter concentrating on orthopedic precision applications. Medtronic occupies a diversified position spanning navigation integration with broader surgical portfolios. Among emerging challengers, CMR Surgical and Asensus Surgical represent the modular-configuration archetype, targeting mid-tier hospitals with flexible capital deployment models that reduce upfront equipment intensity.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Smith & Nephew |
| Accuray |
| CMR Surgical |
| Asensus Surgical |
| Others |
Supply & Pricing Matrix
Precision electromechanical engineers concentrated in Stuttgart and Osaka command wage premiums that compress margins on mid-tier robotic platforms while enabling three-tier pricing spreads between university hospital, corporate hospital, and ambulatory configurations. Labor-cost differentials between German and Japanese component specialists and assembly operations in Costa Rica and Ireland directly shape instrument replenishment pricing tiers.
Pricing Analysis
Per-procedure outcome guarantees anchor value-based pricing for integrated delivery networks bundling capital equipment with disposable instrument replenishment and surgeon training. Price differentiation rests on FDA 510(k) clearance tier and ISO 13485 certification status, with premium configurations commanding spreads over standard platforms. Pricing pressure stems from CDSCO quality management tightening in India and NMPA domestic trial mandates in China extending commercialization lead times. Ambulatory surgical centers in Mumbai and Delhi exhibit highest price sensitivity; academic medical centers in the United States and Germany demonstrate lowest sensitivity given research funding offsets.
Supply Chain Analysis
Refurbished da Vinci consoles and remanufactured Mako robotic arms flow through certified preowned channels extending asset life cycles and compressing new equipment pricing power. Geographic supply concentrates in Japan for high-torque miniature motors, Germany for precision optical encoders, and the United States for haptic feedback controllers. Component dependencies include rare-earth magnets for actuator torque density, sapphire optics for stereoscopic imaging chains, and medical-grade titanium for instrument shafts. Single-source vulnerability in Japanese motor supply chains poses structural risk. Distribution runs through GPO contracts and direct hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive instrument manufacturing and proprietary haptic controller production determine margin capture. Players are pursuing backward integration into precision actuator supply to defend pricing power.
For Market Incumbents: Anticipate modular-configuration challengers targeting mid-tier hospitals with reduced upfront capital intensity. Consolidate position through captive supply of force-feedback controllers and predictive maintenance software subscriptions. Defend against Stryker's orthopedic specialization and CMR Surgical's flexible deployment models by embedding deeper into resident training protocols at Cleveland Clinic and Mayo Clinic academic networks. For New Entrants and Emerging Players: Capture white-space in India's tertiary hospital expansion where Apollo and Max Healthcare chains seek robotic surgery infrastructure for Gulf state medical tourism. Target ambulatory surgical center configurations in Germany's Rhine-Ruhr corridor where procedure migration accelerates fastest. Penetrate through AI-assisted preoperative planning modules that reduce surgeon onboarding timelines versus integrated platform incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with haptic systems specialists given FDA software-as-medical-device guidance clarity and EU AI Act risk classification finalization. Long-term viability favors asset-light designers with modular platforms over capital-heavy producers tethered to replacement cycles. Monitor NMPA registration timelines in China and PMDA orphan device review throughput in Japan as inflection indicators for multinational revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | AI-assisted surgical planning modules pivot vendor relationships toward recurring revenue architectures. |
| Hospital System Partnership | Per-procedure service agreements with United States integrated delivery networks displace capital purchase cycles. |
| CE Marking Pathway | EU MDR conformity assessments accelerate commercialization timelines for platforms seeking European market access. |
| Reimbursement Strategy | CMS coverage determinations for robotic-assisted procedures shape hospital procurement committee prioritization. |
| FDA Submission | Premarket notification pathways for autonomous decision-support features determine competitive positioning in software layers. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation, and CMS Medicare procedure databases formed the secondary backbone for installed base and procedural volume estimation. Primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and robotic surgery program coordinators validated capital allocation timelines and vendor selection criteria. Bottom-up triangulation across instrument replenishment rates and top-down reconciliation against manufacturer disclosed placements anchored market size estimation.
Historical trendline analysis of da Vinci system placements and Mako robotic arm installations informed penetration trajectory modeling across the projection horizon. Segmentation dimensions included product type, technology layer, surgical application, and end-user facility tier. CAGRs derived from procedure volume growth assumptions and per-system instrument attachment rates. Forecast inputs incorporated PMDA orphan device review throughput and NMPA domestic clinical trial participation mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device guidance evolution and EU AI Act enforcement patterns. Forecasts reflect assumptions around reimbursement adequacy maintenance and supply chain continuity for Japanese precision actuators. Practitioners should monitor CDSCO quality management standard implementation and METI domestic component manufacturing subsidies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Reusable Resuscitators Market
Medical Devices
Latin America Insulin Delivery Devices Market
Medical Devices
Enteral Stents Market
Medical Devices
Infertility Devices Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Anti-Snore Device Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Neuroprosthetics Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Coronary Angiography Devices Market