
 Cardiovascular and Soft Tissue Repair Patches Market | 2026-2036
Cardiovascular and Soft Tissue Repair Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular and Soft Tissue Repair Patches Market Intelligence
Single-source biological patch supply is pivoting toward multi-source agreements as hospital procurement teams seek supply resilience. Baxter leverages its plasma-derived portfolio to sustain leadership in biological patch categories. W.L. Gore & Associates anchors its position through proprietary expanded polytetrafluoroethylene manufacturing. CryoLife differentiates via cryopreserved tissue technologies that occupy specialized cardiac reconstruction niches.
Cardiovascular and soft tissue repair patches comprise implantable biomaterials engineered for structural reinforcement of cardiac walls, vascular conduits, and fascial layers, typically manufactured from extracellular matrix scaffolds or woven polymer matrices with pore sizes calibrated between 50 and 400 micrometers to permit host tissue ingrowth while maintaining tensile strength exceeding 10 MPa. Their primary purpose is to reduce suture-line tension, prevent aneurysmal dilation, and facilitate organized collagen deposition during wound healing. Biological patches command premium positioning due to their remodeling advantages, while synthetic patches in polyester and polypropylene sustain volume leadership through cost accessibility and predictable mechanical performance. Composite patches represent the fastest-growing material configuration as manufacturers blend resorbable matrices with permanent polymer backbones to optimize both integration kinetics and long-term durability.
FDA premarket notification pathways and ISO 10993 biocompatibility standards govern patch commercialization in the United States, with the former dictating clinical evidence requirements and the latter specifying cytotoxicity and hemocompatibility testing protocols that directly shape R&D timelines. The EU Medical Device Regulation imposes additional post-market surveillance obligations through EUDAMED registration that manufacturers must navigate for CE-marked access. Stakeholders should monitor how evolving FDA guidance on animal-derived materials interacts with reimbursement shifts toward value-based cardiac care bundles.
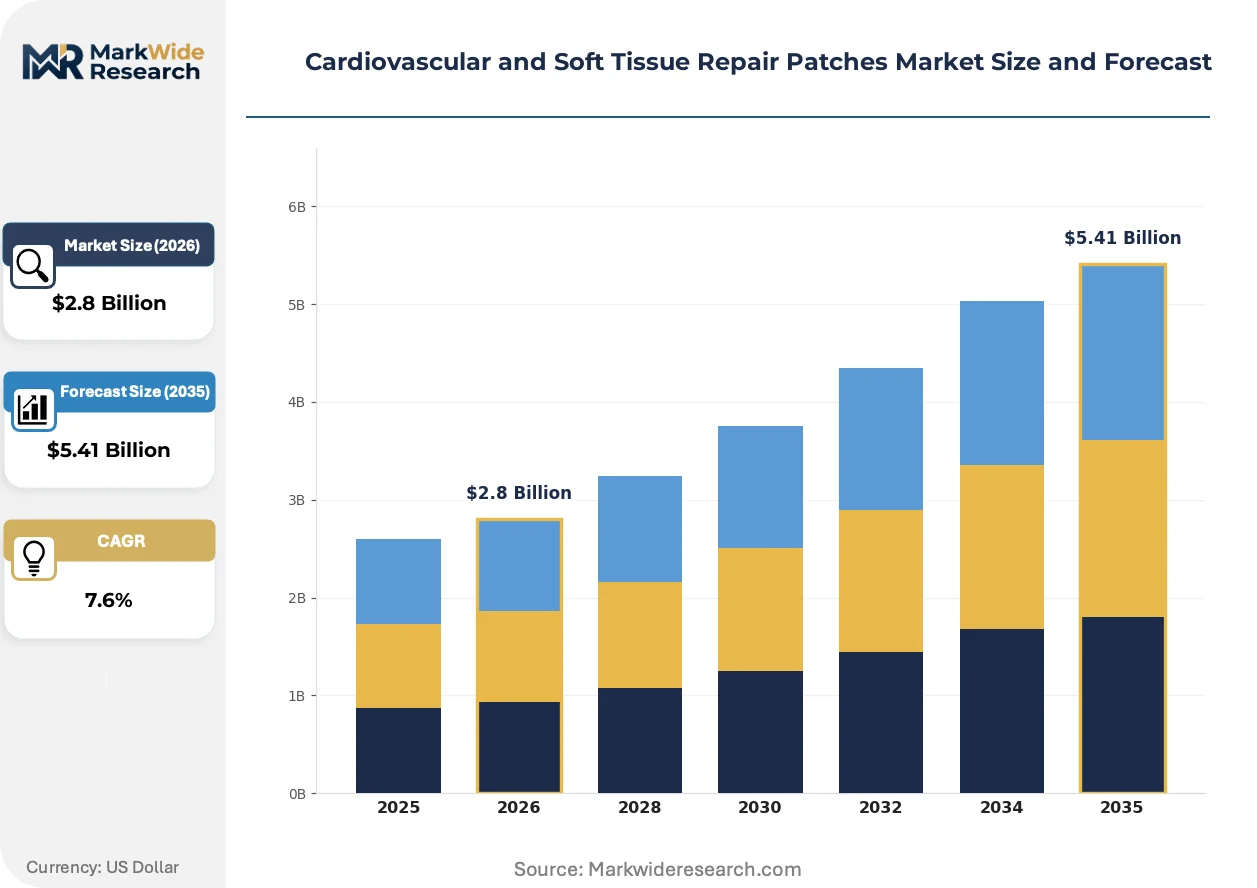
Market Dynamics
Hospital procurement consolidation is compressing supplier margins while accelerating multi-source contracting for biological patches, fundamentally restructuring how cardiovascular patch manufacturers secure volume commitments.
Growth Catalysts
- Biological patch remodeling:Extracellular matrix scaffolds demonstrate superior host tissue integration compared to synthetic alternatives, driving preference shifts in cardiac reconstruction procedures.
- FDA premarket pathway refinement:Streamlined 510(k) notification processes for predicate-based submissions reduce time-to-market for incremental patch innovations.
- Integrated delivery network expansion:US hospital systems are standardizing patch formularies across regional networks, creating concentrated demand pools for qualified suppliers.
Market Restraints
- Bovine pericardium supply concentration:Raw material sourcing clusters in specific agricultural regions, exposing manufacturers to zoonotic disease transmission risks and herd availability volatility.
- ISO 10993 testing burden:Extended cytotoxicity and hemocompatibility validation protocols add eighteen to twenty-four months to biological patch development cycles.
- Synthetic polyester cost floor:Woven polymer patches maintain price accessibility that biological materials cannot match, limiting premium segment expansion.
Strategic Opportunities
- Pediatric cardiac reconstruction:Cryopreserved tissue technologies address unmet needs in congenital heart defect repair where synthetic materials fail to grow with pediatric patients.
- EU MDR transition window:Stricter post-market surveillance requirements through EUDAMED registration favor established manufacturers with robust quality management systems.
- Composite patch convergence:Blending resorbable matrices with permanent polymer backbones opens hybrid positioning between biological remodeling and synthetic durability.
Industry Challenges
- Animal-derived material compliance:Evolving FDA guidance on xenograft sourcing and viral inactivation protocols demands continuous process revalidation.
- Specialized tissue processing talent:Cryopreservation expertise remains concentrated among limited technician pools, constraining manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular and Soft Tissue Repair Patches Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Mesh, Biological Patches, Synthetic Patches, Composite Patches Application: Interventional Cardiology, Open Heart Surgery, Tissue Reconstruction, Wound Closure End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Material: Polyester, Polypropylene, Collagen, Silicone |
| Companies Covered | Baxter, W.L. Gore & Associates, CryoLife, LeMaitre Vascular, Abbott, Edwards Lifesciences Corporation, Terumo Medical Corporation, Medtronic, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular and Soft Tissue Repair Patches Market Strategic Shifts & Innovations
Material science convergence with digital surgical planning is redefining patch selection protocols, moving beyond generic sizing toward patient-specific structural requirements.
Decellularized extracellular matrix patches are absorbing market preference in complex cardiac reconstructions where organized collagen deposition determines long-term outcomes. Academic medical centers in the United States are transitioning procurement specifications toward remodeling-capable materials, compressing volume share for permanent synthetic alternatives that resist physiological integration.
EU Medical Device Regulation post-market surveillance obligations are extending clinical evidence requirements for cardiovascular implants. Manufacturers must now maintain active implant registries and periodic safety update reports, increasing compliance overhead most acutely for small-cap biological patch specialists lacking dedicated regulatory infrastructure.
Hospital value analysis committees are consolidating vendor panels and unbundling patch procurement from suture and closure device bundles. Independent purchasing cooperatives are displacing traditional distributor relationships in the United States, with integrated delivery networks leveraging aggregated volume to extract price concessions and guaranteed supply commitments.
Cardiovascular and Soft Tissue Repair Patches Market Segmentation
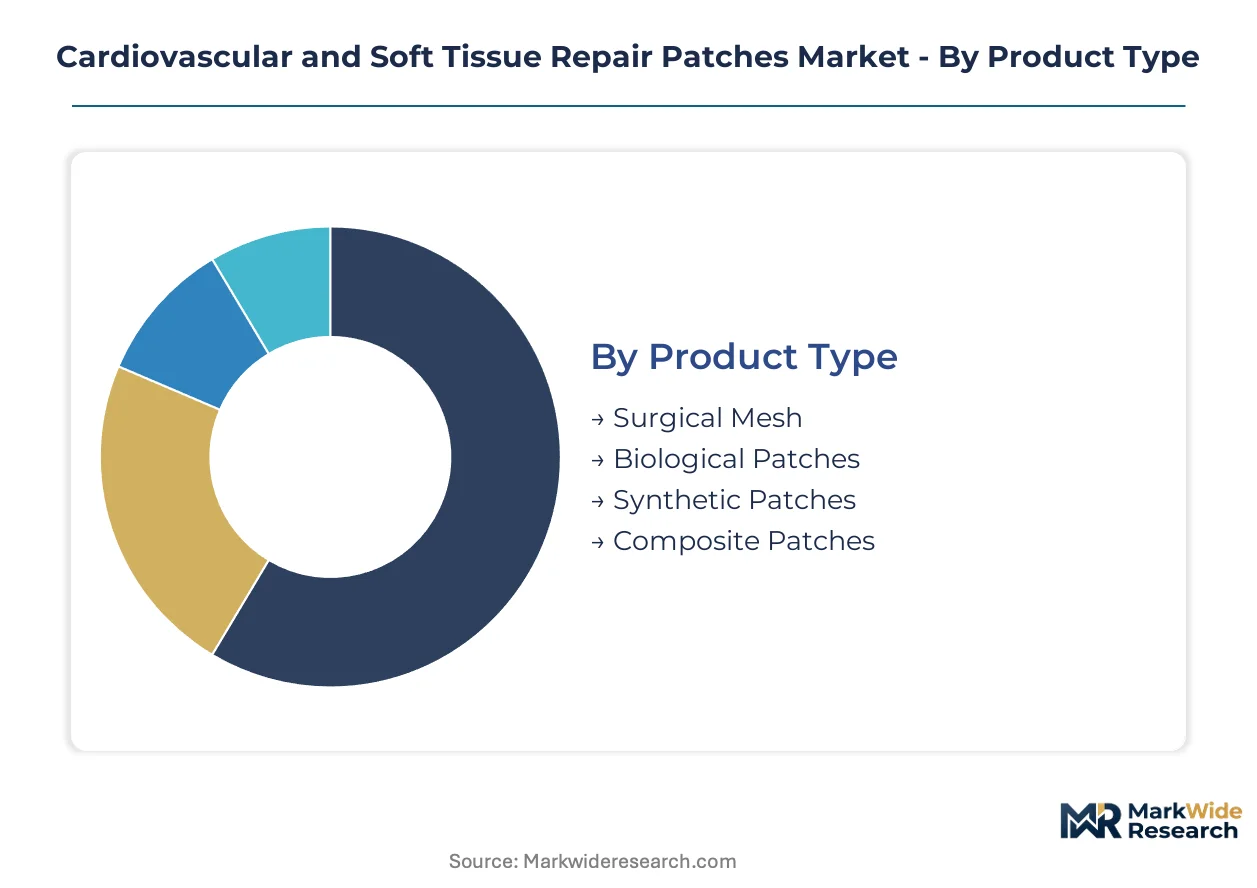
Patch selection protocols increasingly hinge on material certification tiers, with biological constructs demanding extended FDA premarket pathways while synthetics navigate streamlined 510(k) channels. Procurement teams weigh these regulatory burdens against clinical performance requirements when segmenting supplier portfolios across cardiac and soft tissue applications.
Product Type:
FDA 510(k) clearance timelines stretch longest for biological patches requiring viral inactivation validation, while synthetic meshes qualify under abbreviated predicate-based submissions; composite configurations occupy a middle tier with hybrid evidence requirements.
- Biological Patches:Decellularized extracellular matrix scaffolds derived from bovine pericardium or porcine dermis undergo gamma irradiation and terminal sterilization to achieve bioburden reduction below 10^-6 SAL. Demand concentrates in academic medical centers performing complex cardiac reconstructions where remodeling kinetics determine long-term outcomes. FDA guidance on animal-derived tissue sourcing continues tightening viral clearance demonstration standards.
- Composite Patches:Hybrid architectures pair resorbable collagen fronts with permanent polymer backbones, enabling staged mechanical support that transitions from immediate tensile strength to physiological integration. US integrated delivery networks are expanding formulary access for these configurations as value analysis committees seek compromise solutions between biological performance and synthetic cost floors.
- Synthetic Patches:Woven polyester and expanded polytetrafluoroethylene matrices deliver predictable pore geometry and tensile strength exceeding 20 MPa for high-pressure vascular applications.
- Surgical Mesh:Macroporous polypropylene constructs dominate hernia and fascial reinforcement procedures where rapid fibrovascular ingrowth accelerates fixation.
Synthetic patches sit at the top of the volume ranking, with composite patches climbing the fastest.
Application:
Procedure reimbursement tiers directly shape patch selection, with open heart surgery commanding bundled payments that accommodate premium biological materials while interventional cardiology operates under device-specific fee schedules favoring cost containment.
- Open Heart Surgery:Ventricular septal defect closure, valve annuloplasty, and left ventricular reconstruction demand patches with suture retention strength above 2 N and compliance matching native myocardium. US hospital systems performing coronary artery bypass grafting with concomitant patch procedures represent the concentrated demand pool for biological and composite configurations.
- Interventional Cardiology:Transcatheter structural heart procedures utilize low-profile delivery-compatible patches for paravalvular leak closure and septal defect remediation. Ambulatory surgical centers in Germany and the United States are expanding same-day discharge protocols that favor synthetic patches with immediate hemostatic performance.
- Tissue Reconstruction:Fascial defect repair and chest wall reconstruction require large-format patches with handling characteristics suited to contaminated surgical fields.
- Wound Closure:Sternotomy and thoracotomy closure applications prioritize patches with integrated adhesion barriers to prevent mediastinal fibrosis.
Open heart surgery anchors volume concentration, with interventional cardiology expanding most quickly as transcatheter platforms mature.
End User:
Capital equipment requirements and sterilization infrastructure dictate patch category access across facility types, with biological materials requiring cryopreservation or controlled-temperature logistics that exclude smaller clinical settings.
- Hospitals:Tertiary cardiac centers maintain tissue processing laboratories and active implant registries mandated by EU MDR post-market surveillance obligations. These facilities command preferential pricing through multi-year supply agreements covering biological patch categories.
- Ambulatory Surgical Centers:Limited sterilization capacity and same-day discharge protocols restrict formulary access to pre-packaged synthetic patches with immediate availability.
- Clinics:Wound care and minor tissue repair applications utilize off-the-shelf surgical mesh configurations with minimal storage requirements.
- Research Institutions:Preclinical and clinical trial operations drive demand for investigational patch configurations with customizable specifications and batch documentation.
Hospitals dominate procurement volume, with ambulatory surgical centers gaining share fastest as cardiac procedures migrate to lower-acuity settings.
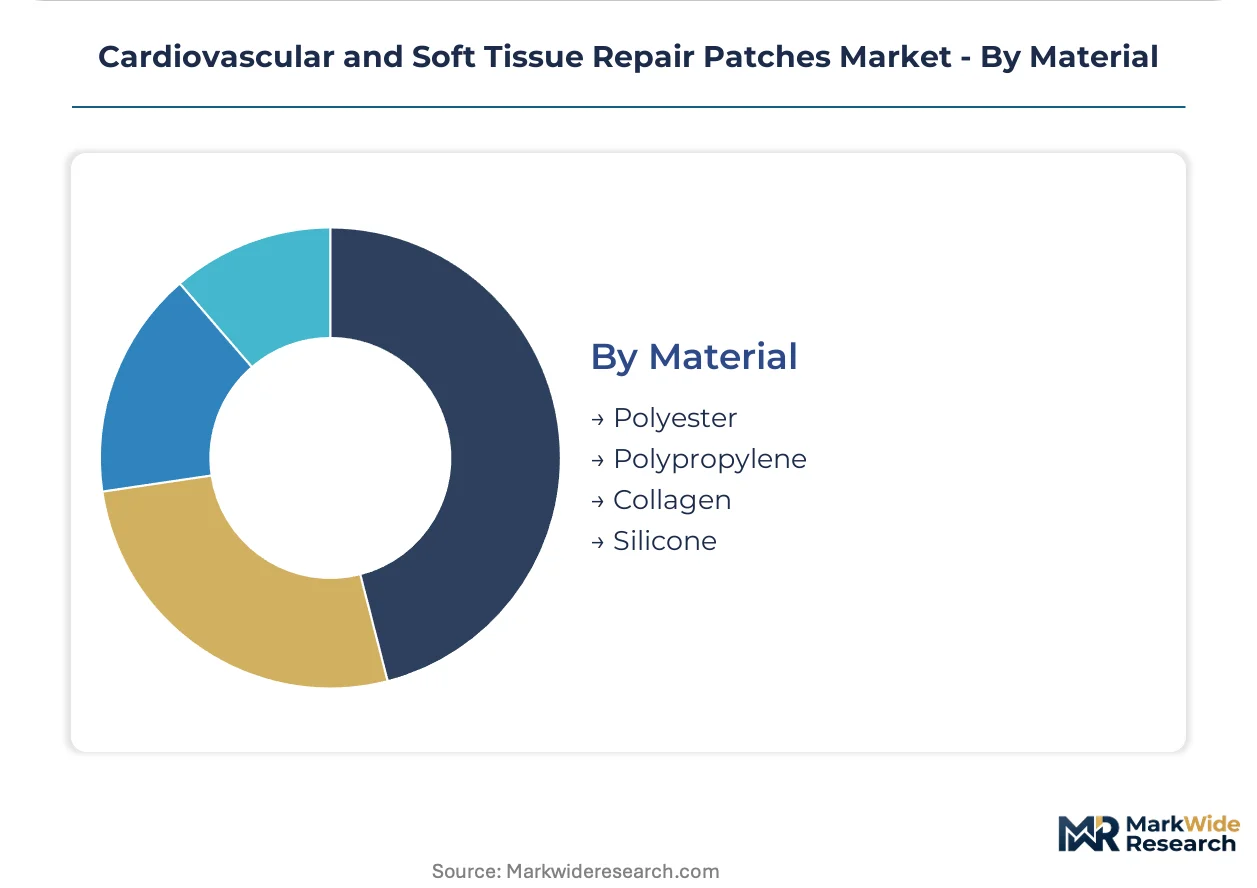
Material:
Raw material sourcing geography and polymer processing capabilities determine regional supply concentration, with collagen extraction clustering near agricultural processing infrastructure and synthetic polymer production centering on petrochemical corridors.
- Collagen:Purified bovine and porcine type I collagen undergoes pepsin digestion and crosslinking with glutaraldehyde or carbodiimide to modulate resorption rates between 30 and 180 days. European manufacturers leverage proximity to regulated abattoirs under EFSA oversight to secure certified raw material streams.
- Polyester:Polyethylene terephthalate fibers woven into double-velour or knitted architectures provide permanent scaffolding for vascular conduits and cardiac patches. Manufacturing concentration in China and India supports cost accessibility that sustains volume leadership across price-sensitive segments.
- Polypropylene:Monofilament and multifilament constructions with pore sizes calibrated between 1 and 4 mm optimize tissue ingrowth while minimizing adhesion formation in hernia applications.
- Silicone:Elastomeric sheeting and reinforced membranes address specialized requirements in diaphragmatic repair and soft tissue contouring where flexibility exceeds mechanical strength priorities.
Polyester leads volume rankings, with collagen ascending fastest as biological remodeling protocols displace permanent synthetic alternatives in cardiac reconstruction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as biological patch producers migrate processing capacity toward jurisdictions with streamlined tissue-sourcing protocols and lower compliance overhead. Cost-of-compliance gaps between established and emerging regulatory environments now drive facility location decisions more than raw material proximity.
United States
FDA premarket notification requirements for cardiovascular implants are tightening quality benchmarks, extending 510(k) timelines for biological patches requiring viral inactivation validation. Hospital procurement consolidation through integrated delivery networks is compressing supplier margins while accelerating multi-source contracting. The Minneapolis-St. Paul corridor hosts concentrated cryopreservation expertise serving tertiary cardiac centers.
Germany
EU Medical Device Regulation post-market surveillance obligations through EUDAMED registration favor established manufacturers with robust quality management systems. Proximity to regulated abattoirs under EFSA oversight secures certified collagen raw material streams for biological patch production. The Baden-Württemberg region anchors specialized textile processing capabilities for synthetic polymer matrices.
China
NMPA medical device registration pathways are converging toward international standards, reducing historical regulatory arbitrage advantages for domestic producers. Local manufacturing of woven polyester patches benefits from petrochemical corridor integration in the Yangtze River Delta. Shanghai-based research institutions are expanding preclinical evaluation capacity for composite patch configurations.
Japan
PMDA consultation procedures for regenerative medical products create structured entry pathways for cryopreserved tissue technologies. Aging demographics are expanding procedural volumes for cardiac reconstruction where biological remodeling advantages command clinical preference. The Osaka-Kobe industrial zone maintains concentrated capabilities in precision polymer processing for vascular applications.
India
CDSCO medical device rules are harmonizing with international standards, enabling export-oriented manufacturing for cost-sensitive synthetic patch segments. Domestic demand for hernia mesh applications is expanding through government health insurance scheme coverage. The Ahmedabad-Surat corridor clusters textile engineering expertise applicable to woven polymer scaffold production.
Cardiovascular and Soft Tissue Repair Patches Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized tissue processing niches and pediatric reconstruction applications. Market structure exhibits tiered consolidation with plasma-derived specialists, cryopreservation experts, and polymer fabricators occupying distinct competitive positions. Strategic archetypes include biological material integrators leveraging captive tissue supply, synthetic mesh scale manufacturers optimizing cost floors, and hybrid innovators bridging resorbable-permanent material boundaries. Dominant competitive moves encompass backward integration into raw material sourcing and geographic expansion through distributor network restructuring.
Within the biological patch tier, Baxter and CryoLife exemplify divergent sourcing strategies—plasma-derived portfolios versus cryopreserved tissue technologies—while W.L. Gore & Associates anchors synthetic positioning through proprietary expanded polytetrafluoroethylene manufacturing. These three entities represent distinct archetype endpoints: diversified healthcare conglomerates with biological material depth, specialized cardiac reconstruction players with niche technical capabilities, and materials science originators with polymer backbone control.
| Leading Market Players |
|---|
| Baxter |
| W.L. Gore & Associates |
| CryoLife |
| LeMaitre Vascular |
| Abbott |
| Edwards Lifesciences Corporation |
| Terumo Medical Corporation |
| Medtronic |
| Integra LifeSciences Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up hospital procurement specialists have consolidated purchasing power across integrated delivery networks, compressing supplier margins while simultaneously demanding guaranteed supply commitments that force manufacturers to absorb inventory carrying costs and cryopreservation logistics overhead.
Pricing Analysis
Distributor margins in biological patch categories run 15-25 percentage points above synthetic mesh equivalents, reflecting cold-chain handling requirements and specialized tissue processing certification. Three-tier pricing structure across premium biological, standard composite, and economy synthetic levels separates academic medical centers with bundled payment flexibility from ambulatory surgical centers constrained by device-specific fee schedules. Pricing pressure stems from procurement consolidation as value analysis committees unbundle patch categories from suture and closure device bundles. Ambulatory surgical centers exhibit highest price sensitivity due to immediate discharge protocols and limited formulary access, while tertiary cardiac centers with active implant registries demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Cryopreservation technician shortages in the Minneapolis-St. Paul corridor and Baden-Württemberg region constrain manufacturing scale-up for biological patch producers. Raw material sourcing clusters in bovine pericardium supply from regulated EFSA abattoirs in Germany and France, while woven polyester production centers on petrochemical corridors in China's Yangtze River Delta and India's Ahmedabad-Surat textile belt. Single-source vulnerability in decellularized extracellular matrix scaffolds exposes manufacturers to zoonotic disease transmission risks and herd availability volatility. Distribution runs through independent purchasing cooperatives displacing traditional distributor relationships in the United States, with integrated delivery networks leveraging aggregated volume for price concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA premarket notification tightening and EU MDR post-market surveillance obligations simultaneously elevate compliance barriers and consolidate demand around established quality management systems.
For Market Incumbents: Deepen backward integration into bovine pericardium sourcing through direct abattoir partnerships under EFSA oversight, securing certified raw material streams against zoonotic disease transmission risks. Expand cryopreservation capacity in the Minneapolis-St. Paul corridor where technician concentration supports manufacturing scale-up. Defend against emerging composite patch specialists by accelerating hybrid product pipelines that blend resorbable matrices with permanent polymer backbones. For New Entrants and Emerging Players: EU MDR transition windows in Germany and neighboring markets open a window for specialized tissue processing niches where established manufacturers face compliance overhead burdens. Target pediatric cardiac reconstruction applications where cryopreserved tissue technologies address unmet needs in congenital heart defect repair. Pursue hospital system partnerships through value-based cardiac care bundle alignment rather than competing on unit price against synthetic mesh scale manufacturers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biological patch specialists lacking dedicated regulatory infrastructure to navigate EUDAMED registration and periodic safety update report obligations. Long-term viability centers on acquisition targets with captive tissue supply relationships and cryopreservation expertise concentrated in limited technician pools. Watch for FDA guidance finalization on animal-derived material viral inactivation protocols as the inflection indicator driving consolidation toward compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined predicate-based pathways reduce time-to-market for incremental patch innovations in biological categories. |
| CE Marking Pathway Investment | EUDAMED registration readiness separates viable EU market participants from compliance-burdened exits. |
| Hospital System Partnership | Integrated delivery network formulary standardization creates concentrated demand pools for qualified suppliers. |
| Reimbursement Strategy Development | Value-based cardiac care bundle alignment determines biological patch access against synthetic cost floors. |
| Composite Product Pipeline Expansion | Hybrid architectures open positioning between biological remodeling advantages and synthetic durability. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EUDAMED registration databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up patch shipment tracking across biological, composite, and synthetic categories triangulated against top-down manufacturer revenue analysis.
Segment-weighting approaches modeled product type, application procedure, end-user facility tier, and raw material sourcing geography across the projection horizon. CAGRs derived from procedure volume elasticity to demographic aging patterns, reimbursement tier shifts, and material substitution dynamics. Forecast inputs incorporated ISO 10993 testing timeline extensions and EU MDR compliance cost burdens specific to biological patch commercialization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under zoonotic disease outbreaks affecting bovine pericardium supply chains or sudden FDA guidance revisions on viral inactivation protocols. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market