
 Global Peripheral IV Catheters Market | 2026-2036
Global Peripheral IV Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peripheral IV Catheters Market Foresight
Aftermarket service revenue from catheter maintenance and replacement protocols is tilting toward manufacturers with integrated hospital supply contracts. Becton Dickinson and Company leverages its direct sales infrastructure to control procurement channels across major health systems. B. Braun Melsungen AG anchors its position through polyurethane material specialization and European manufacturing scale. Terumo Corporation competes in coated catheter segments where infection prevention properties command premium positioning.
Peripheral IV catheters are short, flexible tubes inserted into superficial veins for fluid administration, medication delivery, or blood sampling, typically manufactured from polyurethane, PVC, or silicone in gauges ranging from 14 to 24. These devices serve as the primary vascular access point in acute care, emergency medicine, and perioperative settings where rapid, reliable infusion capability determines clinical outcomes. Over-the-needle catheters occupy the largest volume share due to standardization across hospital protocols, while coated catheters represent the fastest-expanding material segment as antimicrobial surface technologies address central line-associated bloodstream infection prevention mandates. Midline catheters are gaining structural importance in home care transitions where extended dwell times reduce replacement frequency and total cost of therapy.
FDA safety-engineered device requirements under the Needlestick Safety and Prevention Act mandate retractable or shielded needle designs, forcing portfolio rationalization among manufacturers without compliant platforms. Europe's MDR and REACH frameworks impose biocompatibility testing burdens and substance restrictions that favor established players with regulatory affairs capacity across multiple notified body jurisdictions. China's NMPA has accelerated review timelines for innovative vascular access devices, creating asymmetric market access advantages for firms with localized clinical trial data. Stakeholders must monitor evolving reimbursement thresholds for safety-featured catheters against standard devices as payors recalibrate value-based payment models.
Market Dynamics
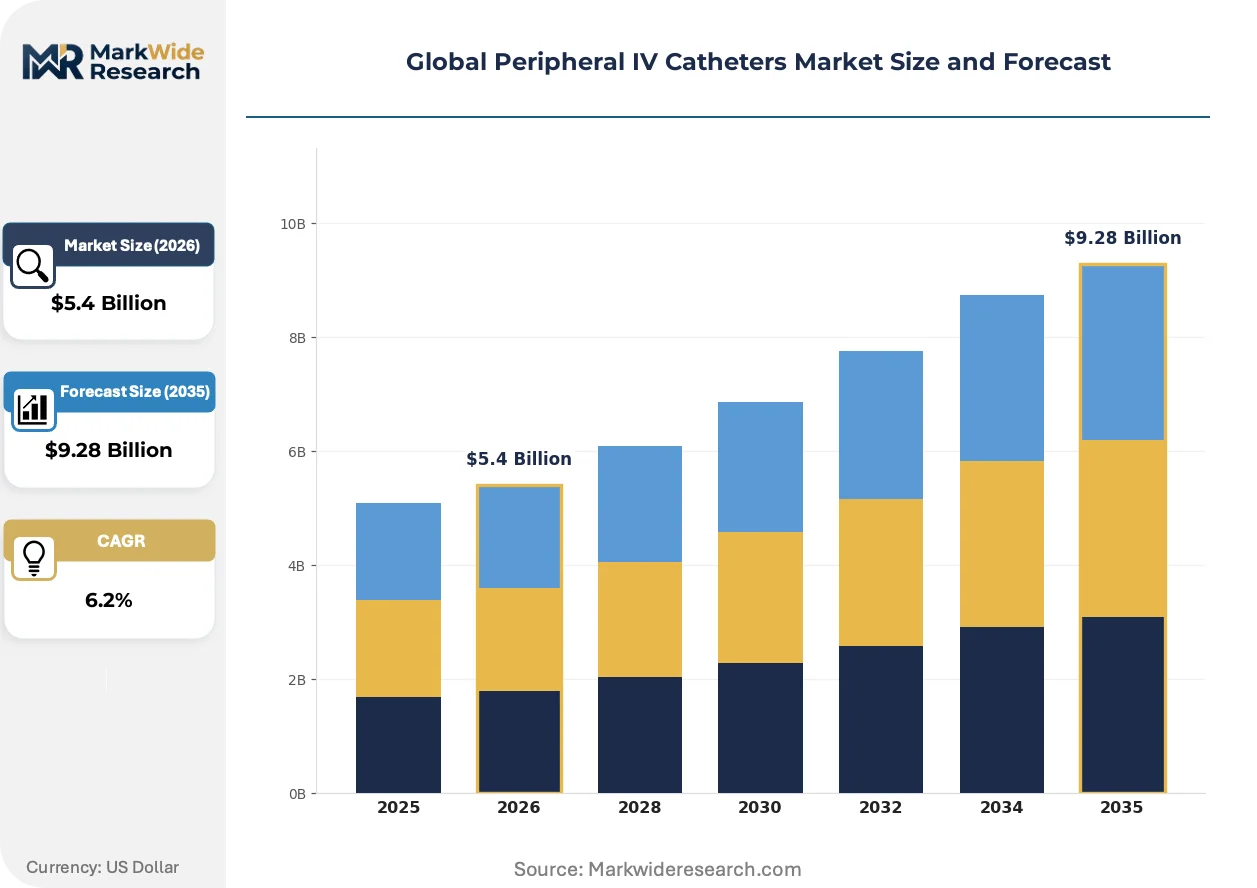
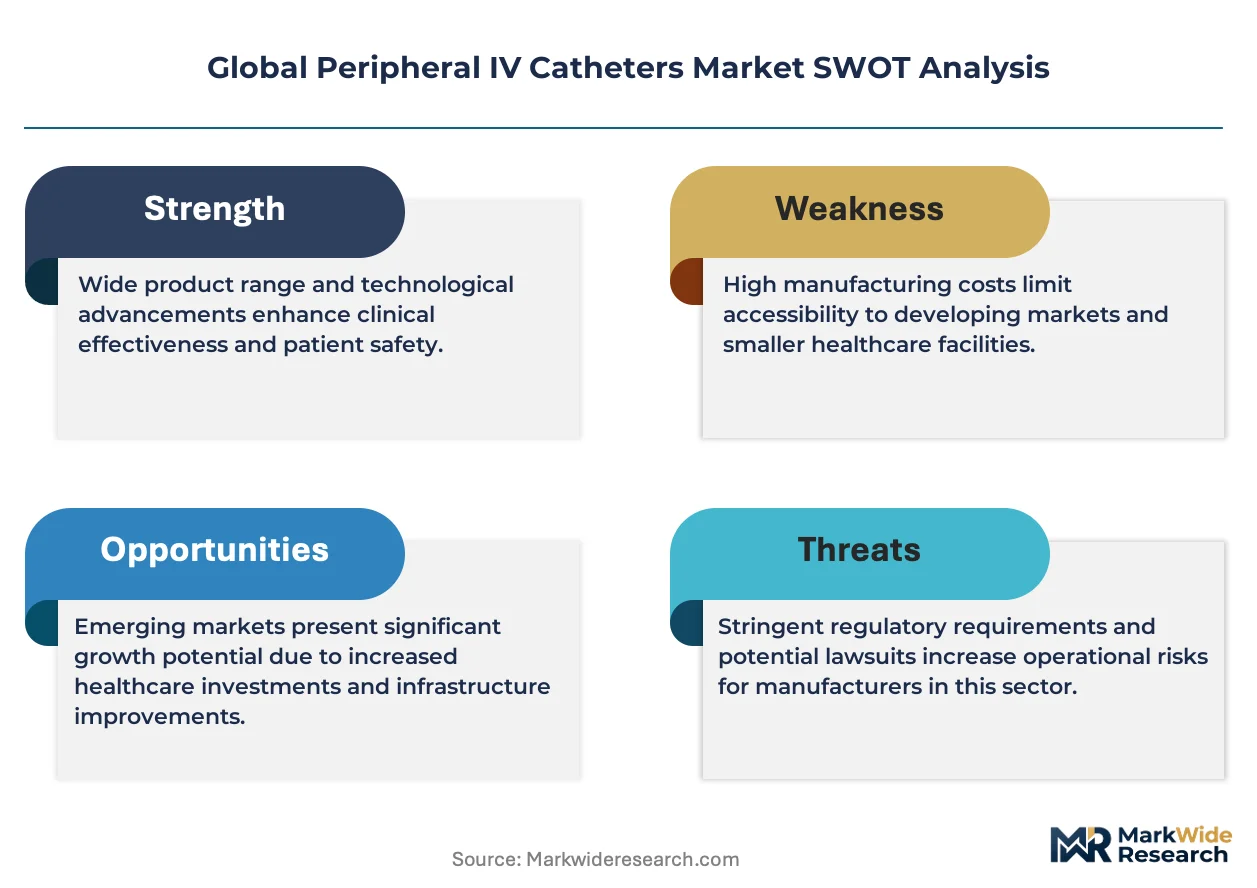
FDA safety-engineered device mandates and Europe's MDR compliance deadlines are compressing manufacturer portfolios while accelerating consolidation around polyurethane antimicrobial platforms. These regulatory pressures favor established players with multi-jurisdictional testing capacity.
Growth Catalysts
- Needlestick Safety and Prevention Act:US hospitals face mandatory conversion to retractable or shielded needle designs, creating replacement demand across installed base.
- Polyurethane antimicrobial coatings:Surface technologies addressing CLABSI prevention protocols command premium positioning in acute care settings.
- Home care transitions:Midline catheter adoption for extended dwell times reduces replacement frequency and total therapy cost in post-acute settings.
Market Restraints
- MDR biocompatibility testing burdens:Europe's substance restrictions and notified body capacity constraints extend certification timelines for new entrants.
- PVC raw material volatility:Chlor-alkali feedstock price swings compress margin stability for standard catheter manufacturers.
- Central line alternatives:Peripherally inserted central catheters and implanted ports capture longer-duration infusion cases.
Strategic Opportunities
- China NMPA accelerated review:Localized clinical trial data creates asymmetric market access for innovative vascular access devices.
- Integrated supply contracts:Aftermarket service revenue from catheter maintenance protocols tilts procurement toward manufacturers with direct hospital infrastructure.
- Antimicrobial surface convergence:Silver-ion and chlorhexidine coatings combine with safety-engineered mechanics to address dual compliance mandates.
Industry Challenges
- Notified body capacity scarcity:MDR transition bottlenecks delay CE marking for mid-tier manufacturers without established European regulatory affairs functions.
- Legacy system integration:Safety-engineered designs require retraining clinical staff accustomed to standard over-the-needle insertion protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peripheral IV Catheters Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-the-Needle, Through-the-Needle, Butterfly, Midline Catheters End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Material: Polyurethane, PVC, Silicone, Coated Catheters Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Retail Pharmacies |
| Companies Covered | Becton Dickinson and Company, B. Braun Melsungen AG, Terumo Corporation, ICU Medical, Teleflex Incorporated, Smiths Medical, Vygon, Nipro Medical Corporation, Retractable Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peripheral IV Catheters Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing product lifecycles while elevating performance thresholds for vascular access devices. Manufacturers must now engineer simultaneously for infection prevention, clinician safety, and dwell time extension.
Antimicrobial-impregnated polyurethane catheters incorporating silver sulfadiazine or chlorhexidine gluconate deliver sustained surface bioburden reduction. US academic medical centers and German university hospitals are standardizing these platforms across emergency and perioperative departments. Conventional uncoated PVC devices are rendering obsolete in institutions with active CLABSI reduction mandates.
Europe's MDR and REACH frameworks impose substance restriction lists and clinical evidence requirements that exceed prior CE marking thresholds. Manufacturers must demonstrate biocompatibility across extended contact durations. Safety-engineered peripheral IV catheters with integrated sharps protection face the steepest compliance burden due to their mechanical complexity and polymer diversity.
Health system procurement consolidation is compressing vendor lists and extending contract durations. US integrated delivery networks and German hospital federations are bundling vascular access devices with infusion therapy services. This concentration shifts purchasing authority from individual clinicians toward centralized supply chain functions with total cost-of-therapy analytics.
Global Peripheral IV Catheters Market Segmentation
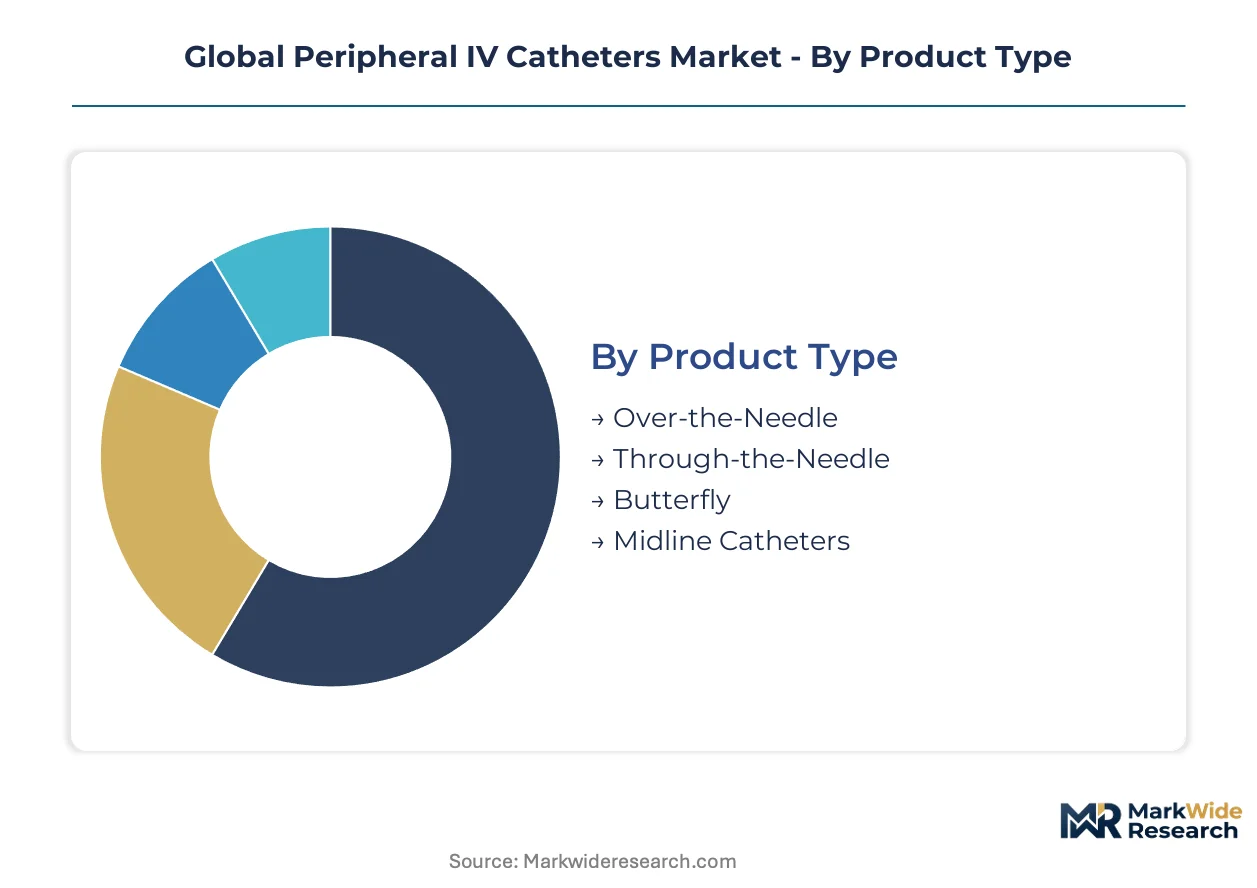
Segmentation in the peripheral IV catheters market reveals divergent service intensity requirements across product categories. Aftermarket protocols for catheter maintenance and replacement vary dramatically by dwell time, material durability, and end-use setting complexity.
Product Type:
After-sales service intensity escalates with catheter complexity and dwell duration, creating tiered manufacturer obligations across insertion technologies.
- Over-the-Needle:Standardized insertion mechanism with integrated needle and catheter assembly. Demand concentrates in US emergency departments and German perioperative units where rapid vascular access protocols dominate. FDA safety-engineered mandates drive replacement cycles across installed hospital bases.
- Midline Catheters:Extended 8-20cm catheters terminating in upper arm veins, engineered for dwell times exceeding standard peripheral devices. Home care transitions in China and post-acute settings in the United States favor these platforms for reduced replacement frequency and lower total therapy cost.
- Through-the-Needle:Catheter advancement through hollow-bore needle designs for specific vascular conditions.
- Butterfly:Winged infusion sets for short-term access and blood sampling applications.
Over-the-Needle holds the largest share; momentum sits with Midline Catheters.
End User:
Cost tier stratification separates acute care infrastructure from decentralized delivery settings with divergent procurement authority structures.
- Hospitals:Dominant volume concentration across 500+ bed academic medical centers and community systems. Integrated delivery networks in the United States and hospital federations in Germany bundle vascular access with infusion therapy services, centralizing purchasing authority.
- Home Care:Fastest-expanding channel as midline adoption enables extended dwell protocols outside institutional walls. China's expanding elderly care infrastructure and US Medicare home health reimbursement shifts accelerate demand.
- Clinics:Outpatient settings with standardized over-the-needle protocols for short-duration therapies.
- Ambulatory Surgical Centers:Same-day procedure volumes requiring rapid-turnover vascular access devices.
Hospitals command the dominant revenue position; Home Care exhibits the steepest expansion trajectory.
Material:
Application requirements dictate material selection across infection prevention mandates, dwell time extension, and mechanical performance specifications.
- Polyurethane:Thermoplastic elastomer with superior kink resistance and biocompatibility profiles. German university hospitals and US academic medical centers standardize antimicrobial-impregnated polyurethane platforms under active CLABSI reduction mandates.
- Coated Catheters:Silver-ion or chlorhexidine surface technologies delivering sustained bioburden reduction. Premium positioning in acute care settings where infection prevention protocols command procurement priority.
- PVC:Cost-optimized standard material facing REACH substance restrictions and chlor-alkali feedstock volatility.
- Silicone:Soft, flexible composition for sensitive vein access and extended dwell applications.
Polyurethane dominates current procurement volumes; Coated Catheters are climbing the fastest as antimicrobial convergence accelerates.
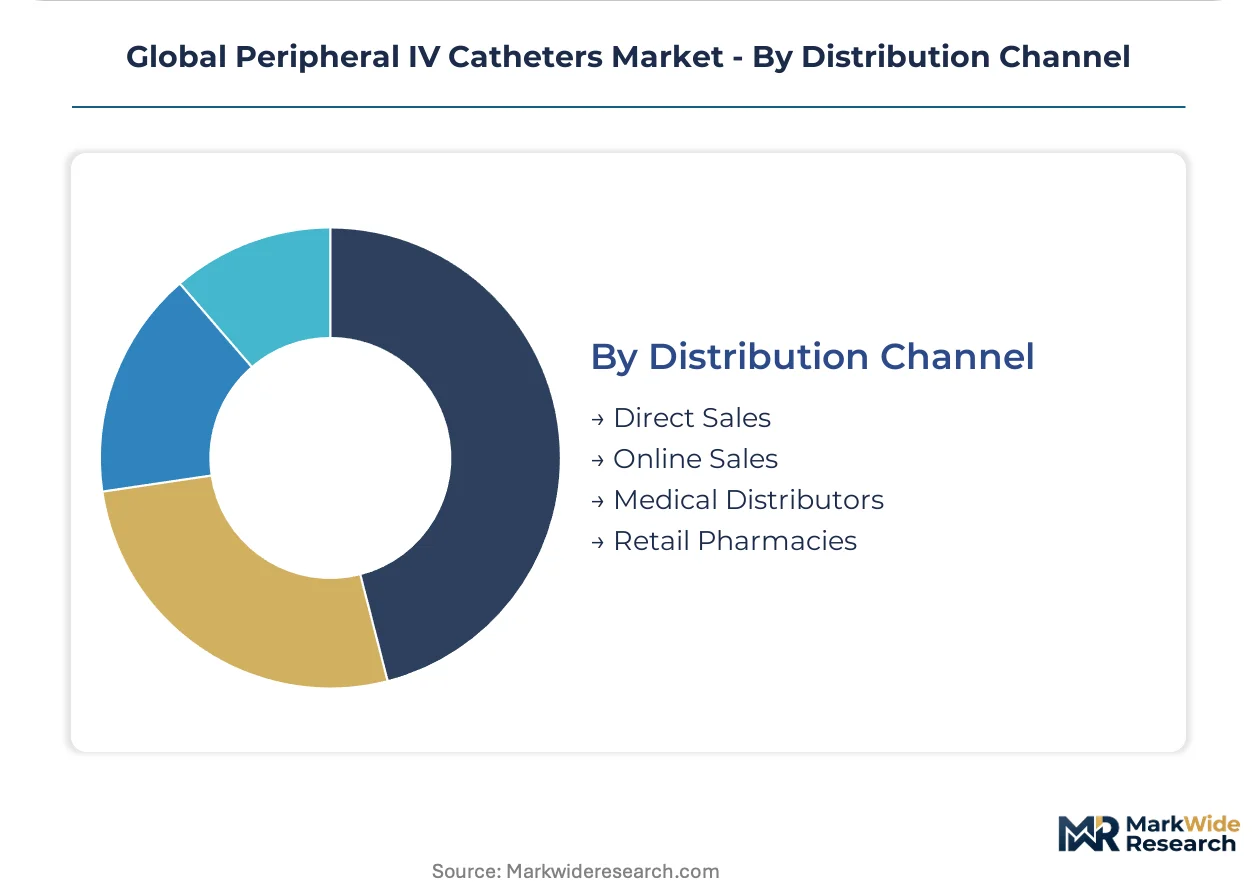
Distribution Channel:
Customer type fragmentation separates institutional procurement from patient-directed acquisition with divergent margin structures.
- Direct Sales:Manufacturer-controlled hospital supply contracts integrating device procurement with maintenance protocols. Becton Dickinson and B. Braun leverage field service infrastructure to lock out distributor intermediaries.
- Medical Distributors:Multi-line intermediaries serving mid-tier hospitals and regional systems with consolidated device portfolios.
- Online Sales:Emerging channel for home care patients and outpatient clinics with standardized product requirements.
- Retail Pharmacies:Limited patient-directed access for butterfly and standard over-the-needle devices.
Direct Sales captures institutional volume leadership; Online Sales is gaining share fastest as home care infrastructure digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major markets. United States buyers absorb premium safety-engineered devices under mandatory conversion timelines, while procurement in India and Southeast Asia prioritizes cost-optimized standard catheters for high-volume institutional contracts.
United States
Academic medical centers in Boston and the Research Triangle drive antimicrobial-coated catheter standardization under active CLABSI reduction protocols. The FDA enforces Needlestick Safety and Prevention Act compliance deadlines through 2026, accelerating hospital replacement cycles. Becton Dickinson's direct sales infrastructure locks procurement channels across integrated delivery networks in Texas and California.
Germany
University hospitals in Munich and Heidelberg standardize polyurethane platforms for extended dwell applications. The MDR transition imposes biocompatibility testing burdens that favor established manufacturers with notified body relationships. B. Braun Melsungen AG anchors European manufacturing scale through its Melsungen headquarters and supply contracts with hospital federations in North Rhine-Westphalia.
China
Home care infrastructure expansion in Shanghai and Guangzhou accelerates midline catheter adoption for elderly patient transitions. The NMPA has compressed review timelines for innovative vascular access devices with localized clinical data. Domestic manufacturers in Jiangsu province scale production of standard over-the-needle devices for provincial hospital procurement tenders.
Japan
Metropolitan Tokyo hospitals prioritize kink-resistant polyurethane catheters for perioperative rapid-access protocols. The PMDA maintains stringent biocompatibility documentation requirements for extended-contact devices. Terumo Corporation leverages domestic manufacturing in Shibuya-ku for coated catheter segments where infection prevention properties command procurement priority.
India
Multi-specialty hospital chains in Maharashtra and Karnataka expand catheter-based infusion therapy capacity for oncology and emergency departments. The CDSCO has streamlined import licensing for safety-engineered devices while domestic BIS certification lags. Price-sensitive procurement at All India Institute of Medical Sciences and comparable public institutions favors standard PVC devices over antimicrobial alternatives.
Global Peripheral IV Catheters Market Competitive Landscape
Capability concentration sits with full-line manufacturers possessing multi-jurisdictional regulatory affairs infrastructure; scale advantage sits with regional specialists serving high-volume tenders. The market structures around three tiers: integrated multinationals with direct hospital contracts, European and Japanese mid-caps with material science specialization, and emerging Asian fabricators competing on standard device cost. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with health systems for bundled vascular access services.
Among integrated multinationals, Becton Dickinson and Company and B. Braun Melsungen AG exemplify the regulatory-capability tier with established notified body relationships and field service infrastructure. Terumo Corporation occupies a position within the coated catheter specialization segment where antimicrobial surface technologies differentiate procurement decisions. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic archetype: US-based full-line players, German material-science specialists, and Japanese precision-device fabricators.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| B. Braun Melsungen AG |
| Terumo Corporation |
| ICU Medical |
| Teleflex Incorporated |
| Smiths Medical |
| Vygon |
| Nipro Medical Corporation |
| Retractable Technologies |
| Others |
Supply & Pricing Matrix
Shanghai-to-Rotterdam container freight corridors transmit chlor-alkali feedstock volatility into polyurethane catheter cost structures, compressing margin stability for manufacturers without backward integration into polymer compounding while amplifying price differentiation between antimicrobial-coated and standard PVC devices across German hospital federations and US integrated delivery networks.
Pricing Analysis
Aftermarket service revenue from catheter maintenance protocols and extended replacement contracts drives lifetime value capture for manufacturers with direct hospital infrastructure. Three-tier pricing structure across premium antimicrobial-coated, standard safety-engineered, and economy PVC devices stratifies procurement decisions, with FDA-mandated safety conversion timelines absorbing premium tiers in US academic medical centers while price-sensitive public institutions in India favor uncoated alternatives. Cost compression in standard PVC segments intensifies due to chlor-alkali raw material swings, with home care channels exhibiting highest price sensitivity and German university hospitals demonstrating lowest.
Supply Chain Analysis
Supplier-financing facilities and extended payment terms from German polymer compounders and Chinese chlor-alkali producers anchor working capital structures for mid-tier manufacturers. Manufacturing concentrates in Germany, China, and the United States, with polyurethane resin supply drawing from BASF and Covestro facilities in Ludwigshafen and Shanghai. Supply chain risk centers on single-source vulnerability for silver-ion coating precursors sourced from Japanese chemical specialists. Distribution runs through manufacturer-direct hospital contracts for institutional volume, with medical distributors serving regional mid-tier systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates asymmetric returns. Multi-jurisdictional notified body relationships and FDA 510(k) predicate libraries constitute structural barriers that compound over time.
For Market Incumbents: Build regulatory moats through notified body capacity expansion across European jurisdictions. Accelerate MDR technical documentation submissions for safety-engineered portfolios before capacity scarcity worsens. Deepen backward integration into polyurethane compounding to defend margin position against chlor-alkali volatility. Channel control through field service infrastructure locks out distributor intermediaries in US integrated delivery networks.
For New Entrants and Emerging Players: Establish a beachhead in China's midline catheter segment where NMPA accelerated review timelines reward localized clinical trial investment. Target home care infrastructure expansion in Shanghai and Guangzhou where extended dwell protocols reduce replacement frequency. Penetrate through digital procurement platforms serving decentralized outpatient clinics with standardized over-the-needle requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates with underoptimized vascular access divisions lacking dedicated regulatory affairs functions. Long-term viability favors platforms with convergent antimicrobial-safety engineering capabilities. Monitor FDA enforcement discretion on Needlestick Safety Act compliance deadlines as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Notified body scarcity in Europe favors early movers with complete biocompatibility dossiers. |
| Hospital System Partnership | Bundled vascular access contracts with US integrated delivery networks lock procurement channels. |
| Antimicrobial Coating Convergence | Silver-ion and chlorhexidine platforms address dual FDA and MDR compliance mandates. |
| Backward Integration into Polymer Compounding | Captive polyurethane supply insulates margin from chlor-alkali feedstock volatility. |
| NMPA Localized Clinical Trial Program | China's compressed review timelines create asymmetric market access for innovative devices. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineers managing vascular access protocols, GPO contracts managers, and regulatory affairs leads at notified bodies anchored the qualitative base. Primary interview findings combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement contract repositories, and CMS Medicare reimbursement schedules. Bottom-up catheter volume modeling and top-down market size triangulation cross-checked segment outputs.
Scenario-bracketing around regulatory enforcement timelines and raw material cost trajectories bounded the analytical framework across the analysis window. Segmentation dimensions modeled include product insertion technology, end-use setting, material composition, and geographic regulatory cluster. CAGRs derived from installed base replacement cycles, home care transition velocity, and antimicrobial coating penetration curves. Forecast inputs incorporated FDA safety-engineered device mandate compliance schedules and MDR notified body capacity constraints.
Sensitivities concentrate around FDA enforcement discretion, MDR transition bottlenecks, and chlor-alkali feedstock price volatility. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hospital procurement consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Therapeutic Respiratory Devices Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
China Anesthesia Devices Market