
 Industrial Ceramics Market | 2026-2036
Industrial Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Ceramics Market Analysis
Silicon carbide is realigning product economics across high-temperature industrial applications by displacing traditional metal alloys in furnace linings and heat exchangers. CoorsTek Inc. leverages captive powder synthesis to sustain margin control across its structural ceramics portfolio. CeramTec GmbH anchors European supply security through specialized alumina and zirconia fabrication in its southern German operations. KYOCERA Corporation dominates fine ceramic substrate production for electronic packaging, extending its reach into telecommunications infrastructure.
Industrial ceramics encompass inorganic, non-metallic materials formed through controlled sintering of oxides, carbides, or nitrides at temperatures exceeding 1,200°C, yielding components with exceptional thermal stability, corrosion resistance, and electrical insulation. Structural ceramics command mature volume pools in heavy manufacturing and construction, while ceramics matrix composites represent the fastest-expanding category as aerospace engine programs pursue lighter, hotter-running architectures. Advanced ceramics concentrate margin pools in electronics and energy applications where sub-micron tolerances and dielectric precision justify premium positioning.
EPA emissions standards in the United States and REACH chemical registration requirements in the European Union are elevating compliance costs for ceramic producers using traditional binder chemistries, while simultaneously creating demand for cleaner-formulation refractories in energy and manufacturing end uses. Japan's METI industrial standards and China's GB certification protocols further fragment market access requirements across major consumption centers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized formulation adaptation or unified platform development delivers superior returns.
Market Dynamics
Semiconductor fabrication equipment manufacturers are accelerating ceramic component procurement as wafer processing temperatures climb beyond 1,400°C, forcing furnace architecture redesigns and material specification upgrades across the supply base.
Growth Catalysts
- REACH compliance tightening:ECHA's additive restrictions in technical ceramic formulations are accelerating cleaner-formulation R&D investments among European producers.
- Japan's METI industrial standards:Precision tolerances for electronic packaging substrates are pulling demand toward sub-micron capable fabrication facilities.
- Silicon carbide displacement:High-temperature industrial applications are abandoning traditional metal alloys for ceramic furnace linings and heat exchangers.
Market Restraints
- Energy input cost volatility:Sintering operations requiring sustained temperatures above 1,200°C face natural gas and electricity price swings that compress operating margins.
- German supply concentration:Precision engineering corridors around Stuttgart and Nuremberg concentrate specialized alumina and zirconia fabrication capacity, creating geographic vulnerability.
- Technical limitation in scale-up:Ceramic matrix composite production remains constrained by batch-processing constraints that resist continuous manufacturing economics.
Strategic Opportunities
- China's dual carbon goals:Energy efficiency mandates in heavy manufacturing are creating demand for thermal insulation ceramics in steel and cement operations.
- Aerospace engine architectures:Hotter-running turbine programs are expanding addressable volume for lighter ceramic matrix composite components.
- Additive manufacturing convergence:Binder jet printing of technical ceramics is opening geometries impossible through conventional pressing or casting methods.
Industry Challenges
- Process engineer scarcity:Sintering parameter optimization and defect control require expertise that outpaces current vocational training pipelines.
- EPA emissions compliance timelines:Traditional binder chemistry reformulation to meet evolving standards demands capital-intensive kiln modifications.
- IP licensing complexity:Powder synthesis patents and proprietary sintering schedules fragment technology access across the competitive landscape.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Ceramics Market |
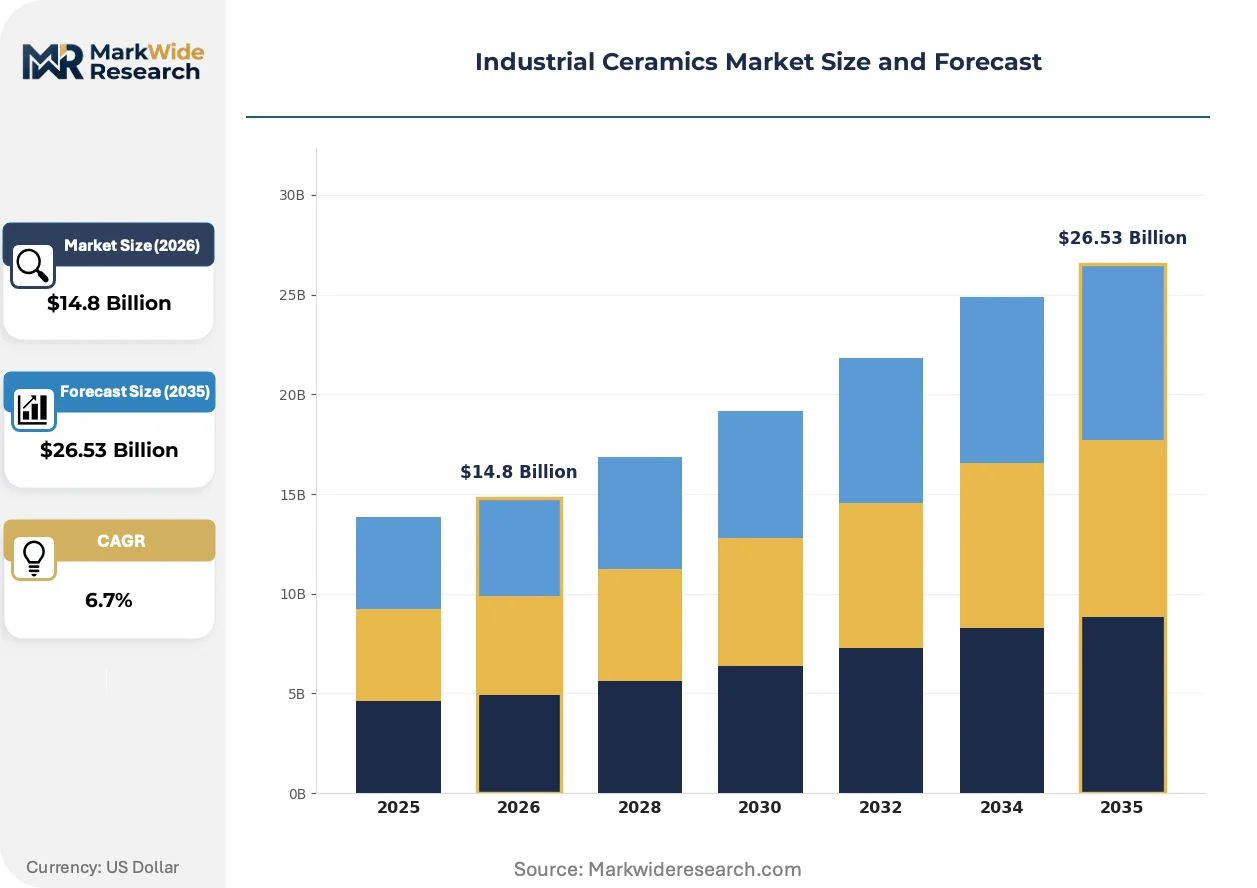
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Ceramics, Advanced Ceramics, Refractories, Ceramics Matrix Composites Application: Aerospace, Automotive, Electronics, Energy Material: Alumina, Zirconia, Silicon Carbide, Titania End User: Manufacturing, Construction, Healthcare, Telecommunications |
| Companies Covered | CoorsTek Inc., CeramTec GmbH, KYOCERA Corporation, Morgan Advanced Materials, Saint-Gobain, 3M, Murata Manufacturing Co., Ltd., AGC Ceramics, Paul Rauschert GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Ceramics Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are jointly redirecting formulation priorities across structural and electronic ceramic segments.
Additive manufacturing of technical ceramics is converging with traditional powder metallurgy supply chains as equipment manufacturers validate binder jet and vat photopolymerization methods for production-scale output. Medical device and aerospace buyers are qualifying printed alumina and zirconia components for end-use applications previously reserved for machined or pressed alternatives. This convergence is compressing minimum viable batch sizes and enabling mass customization without dedicated tooling investments.
EPA emissions standards for hazardous air pollutants are forcing reformulation of traditional phenolic and acrylic binder systems used in green body preparation. Ceramic producers are investing in water-based and bio-derived alternatives that reduce volatile organic compound release during debinding cycles. Structural ceramics for energy and manufacturing applications face the steepest compliance cost escalations, while electronic ceramics with lower binder fractions adapt more rapidly.
Equipment-as-service contracting is displacing traditional component sales in semiconductor fabrication and energy sectors, with ceramic suppliers retaining ownership of high-value hot zone assemblies. Buyers prefer operational expenditure models that transfer performance risk and obsolescence exposure to vendors. This pattern concentrates most visibly in Germany's precision engineering corridor and Japan's semiconductor equipment supply base.
Industrial Ceramics Market Segmentation
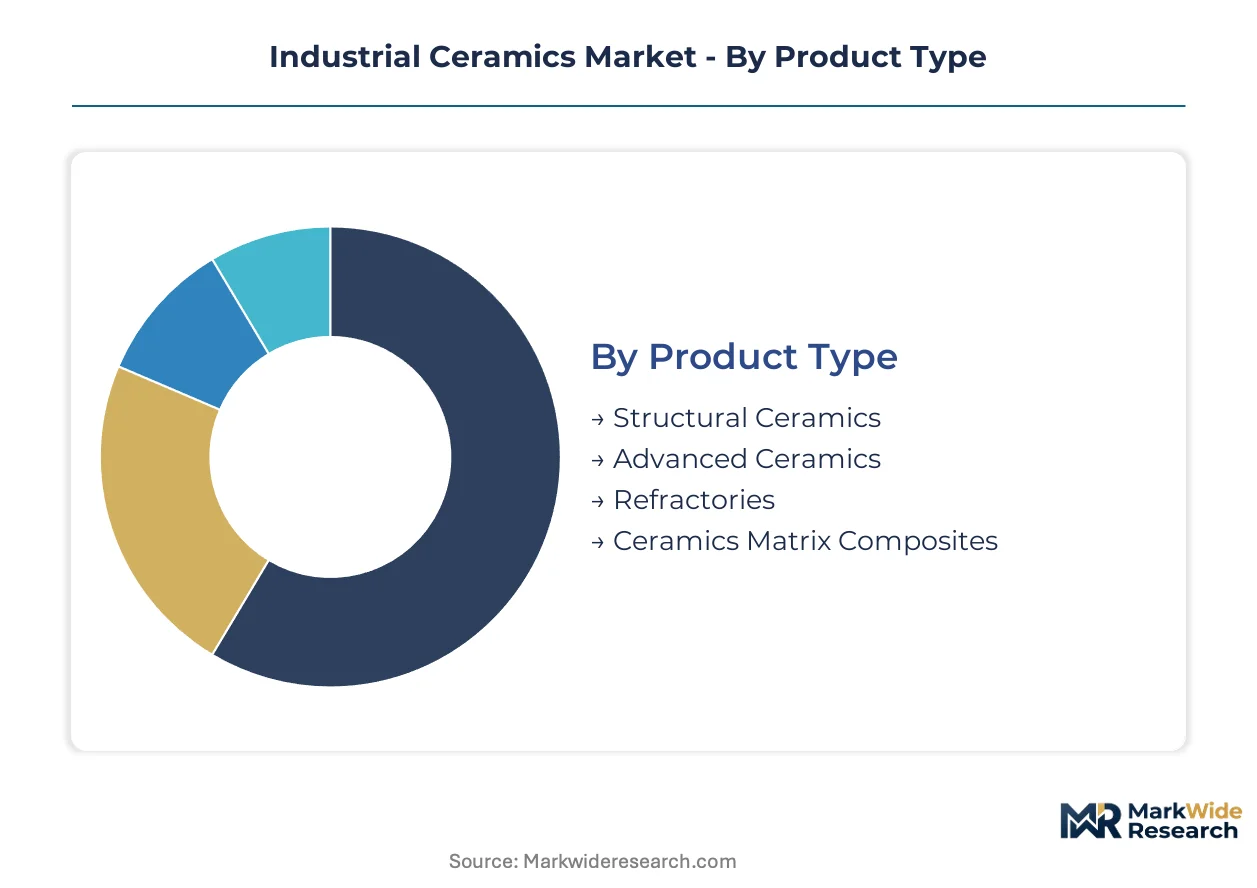
Industrial ceramics segmentation reveals divergent value capture mechanisms across standalone components versus embedded material systems. Product architecture determines whether suppliers compete on specification tolerance or integration depth.
Product Type:
Standalone structural ceramics operate as discrete components in heavy machinery, while advanced ceramics embed into precision electronic assemblies where material properties define system performance.
- Structural Ceramics:Oxide-based formulations withstand mechanical loads in furnace linings and wear-resistant machinery components. German precision engineering corridors around Stuttgart and Nuremberg concentrate fabrication capacity for high-purity alumina structural grades. EPA emissions standards are elevating compliance costs for traditional binder chemistries used in green body preparation.
- Advanced Ceramics:Sub-micron tolerance materials enable dielectric precision in semiconductor packaging and telecommunications infrastructure. KYOCERA Corporation dominates fine ceramic substrate production in Japan under METI industrial standards that mandate precision tolerances for electronic packaging.
- Refractories:High-temperature linings for steel and cement operations face reformulation pressure from REACH additive restrictions.
- Ceramics Matrix Composites:Lighter architectures for hotter-running aerospace engine programs resist continuous manufacturing economics due to batch-processing constraints.
Structural Ceramics leads volumes today; Ceramics Matrix Composites is gaining share fastest.
Application:
Application segmentation tracks temperature exposure thresholds and regulatory intensity across end-use environments.
- Aerospace:Ceramic matrix composite turbine components reduce weight in next-generation engine architectures. Hotter-running programs in the United States and Europe are expanding addressable volume for thermal barrier coatings and structural hot section parts.
- Automotive:Silicon carbide substrates enable power electronics in electric vehicle inverters. Japanese and German automotive suppliers are qualifying ceramic components for thermal management systems under stringent durability protocols.
- Electronics:Fine ceramic substrates provide electrical insulation and thermal dissipation for semiconductor packaging.
- Energy:Refractory linings face dual pressure from efficiency mandates and emissions compliance in heavy manufacturing.
Electronics commands premium margins; Energy shows steepest expansion trajectory.
Material:
Material selection hinges on thermal stability requirements and powder synthesis access.
- Alumina:Cost-effective oxide ceramic dominates structural applications with proven supply chains. CoorsTek leverages captive powder synthesis to sustain margin control across alumina structural portfolios.
- Silicon Carbide:Carbide formulations displace metal alloys in furnace linings and heat exchangers where temperatures exceed 1,400°C. Wafer processing equipment manufacturers are accelerating procurement as thermal requirements climb.
- Zirconia:Transformation-toughened oxide enables dental and medical device applications requiring biocompatibility.
- Titania:Photocatalytic properties drive demand in environmental and chemical processing applications.
Alumina dominates tonnage; Silicon Carbide expands most quickly.
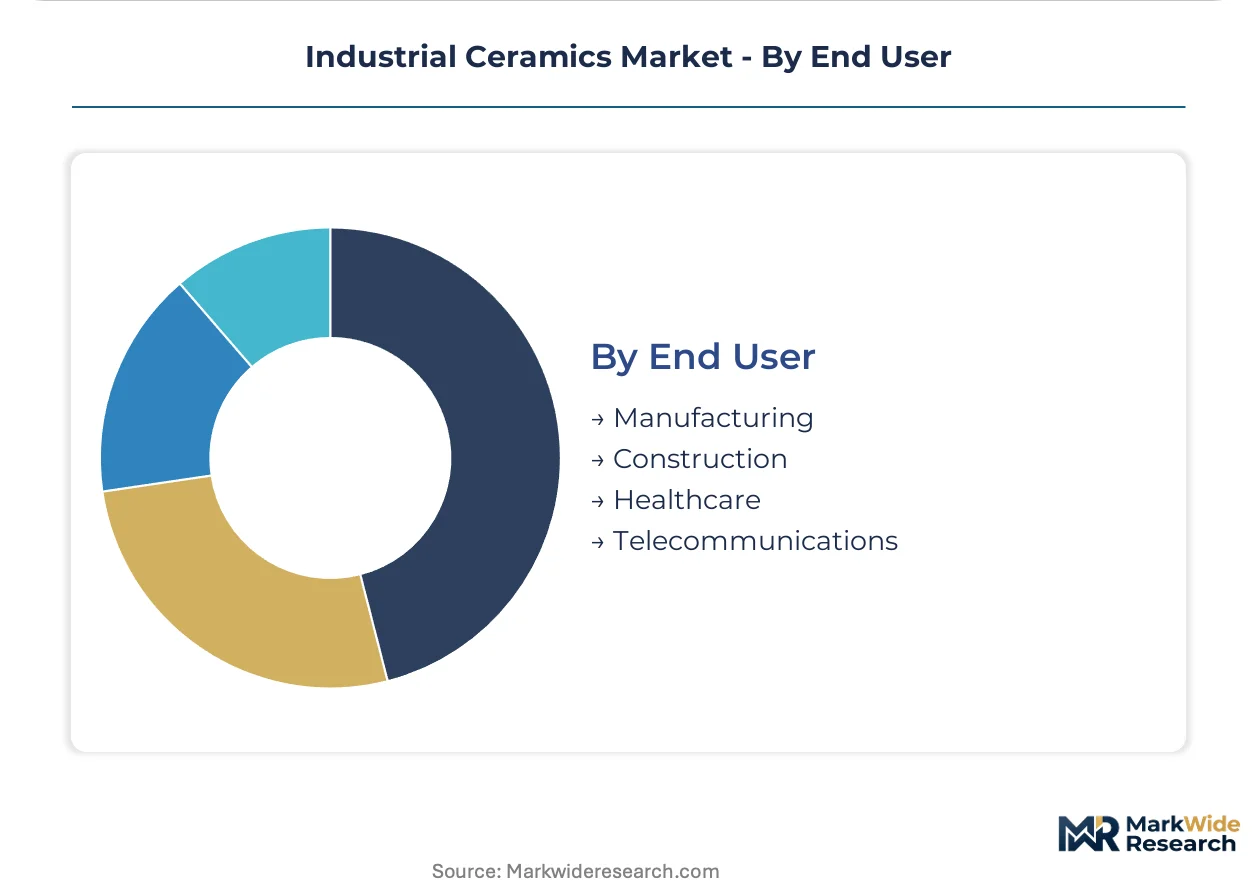
End User:
End user segmentation reflects divergent procurement sophistication and contract structures.
- Manufacturing:Equipment-as-service contracting is displacing component sales in semiconductor fabrication and energy sectors. Buyers in Germany and Japan prefer operational expenditure models that transfer performance risk to ceramic suppliers.
- Construction:Refractory demand concentrates in steel and cement operations facing China's dual carbon goals for energy efficiency.
- Healthcare:Additive manufacturing of alumina and zirconia is qualifying printed components for medical device applications.
- Telecommunications:Fine ceramic substrates support 5G infrastructure deployment requiring dielectric precision.
Manufacturing leads procurement volume; Healthcare shows fastest qualification pace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering corridor around Stuttgart and Nuremberg concentrates specialized alumina and zirconia fabrication capacity for furnace components and semiconductor equipment.
United States
Semiconductor fabrication equipment manufacturers in Arizona and Texas are accelerating ceramic component procurement as wafer processing temperatures climb. EPA emissions standards for hazardous air pollutants are forcing reformulation of traditional phenolic binder systems used in green body preparation. Silicon carbide production clusters in the Pacific Northwest are scaling capacity for high-temperature industrial applications.
Germany
Automotive suppliers in Baden-Württemberg are qualifying ceramic components for thermal management systems in electric vehicle inverters. REACH compliance through ECHA is tightening permissible additive content in technical ceramic formulations. The Stuttgart-Nuremberg corridor anchors European supply security through specialized alumina fabrication operations.
Japan
Telecommunications infrastructure deployment is pulling demand toward sub-micron capable fabrication facilities for fine ceramic substrates. METI industrial standards mandate precision tolerances for electronic packaging substrates that exceed conventional specifications. The Nagoya-Osaka manufacturing belt dominates ceramic substrate production for 5G base station components.
China
Steel and cement operations are sourcing thermal insulation ceramics under dual carbon goals for energy efficiency mandates. GB certification protocols fragment market access requirements compared with Western regulatory frameworks. The Yangtze River Delta hosts expanding silicon carbide capacity for power electronics in renewable energy systems.
South Korea
Memory chip manufacturers are sourcing advanced ceramic components for etching and deposition equipment. The national industrial standards body enforces stringent purity requirements for semiconductor-grade ceramics. The Seoul Capital Area concentrates precision ceramic machining capacity serving display panel and battery production lines.
Industrial Ceramics Market Vendor Landscape
Global majors compete with regional champions across powder synthesis capabilities and sintering parameter expertise. The vendor base organizes into three tiers: integrated material-science conglomerates with captive supply chains, mid-scale specialists focused on single material families, and niche additive manufacturing service providers. Strategic moves concentrate on backward integration into powder production and qualification of printed ceramic components for aerospace and medical end uses.
Among Germany-based fabricators, CeramTec GmbH and Paul Rauschert GmbH & Co. KG occupy positions within the European specialist tier, while KYOCERA Corporation represents the integrated Asia-Pacific archetype with fine ceramic substrate capabilities. These three exemplify divergent approaches to margin protection—regional specialists through application engineering depth, integrated players through captive powder synthesis and electronics integration.
| Leading Market Players |
|---|
| CoorsTek Inc. |
| CeramTec GmbH |
| KYOCERA Corporation |
| Morgan Advanced Materials |
| Saint-Gobain |
| 3M |
| Murata Manufacturing Co., Ltd. |
| AGC Ceramics |
| Paul Rauschert GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
REACH additive restrictions through ECHA gates qualified supply for premium-tier ceramic formulations while compressing margin pools for producers unable to reformulate binder chemistries. Buyers seeking REACH-compliant alumina and zirconia components face 15-20% procurement cost premiums against standard grades, concentrating pricing power among German fabricators with verified clean-formulation capabilities.
Pricing Analysis
Natural gas and electricity pass-through dynamics dominate ceramic pricing as sintering operations above 1,200°C consume 35-45% of production costs. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade substrates from industrial refractories and construction ceramics. Cost compression in standard-grade alumina is intensifying because Chinese capacity expansion floods commodity structural ceramics. Automotive OEMs exhibit highest price sensitivity, while semiconductor equipment manufacturers absorb premiums for sub-micron tolerance guarantees.
Supply Chain Analysis
Dual-sourcing mandates from aerospace and medical device buyers force qualification of second-source suppliers for silicon carbide and zirconia components, extending procurement cycles by 8-14 months. Powder synthesis concentrates in Germany, Japan, and the United States, with high-purity alumina feedstock drawing from captive operations at CoorsTek and KYOCERA. Single-source vulnerability persists in specialized zirconia transformation-toughened grades where CeramTec holds process IP. Distribution runs through direct mill relationships for high-specification grades and regional distributors for commodity structural ceramics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German REACH compliance costs run 40-60% above equivalent US EPA thresholds, creating arbitrage opportunities for producers with dual-certified formulations serving both regulatory environments.
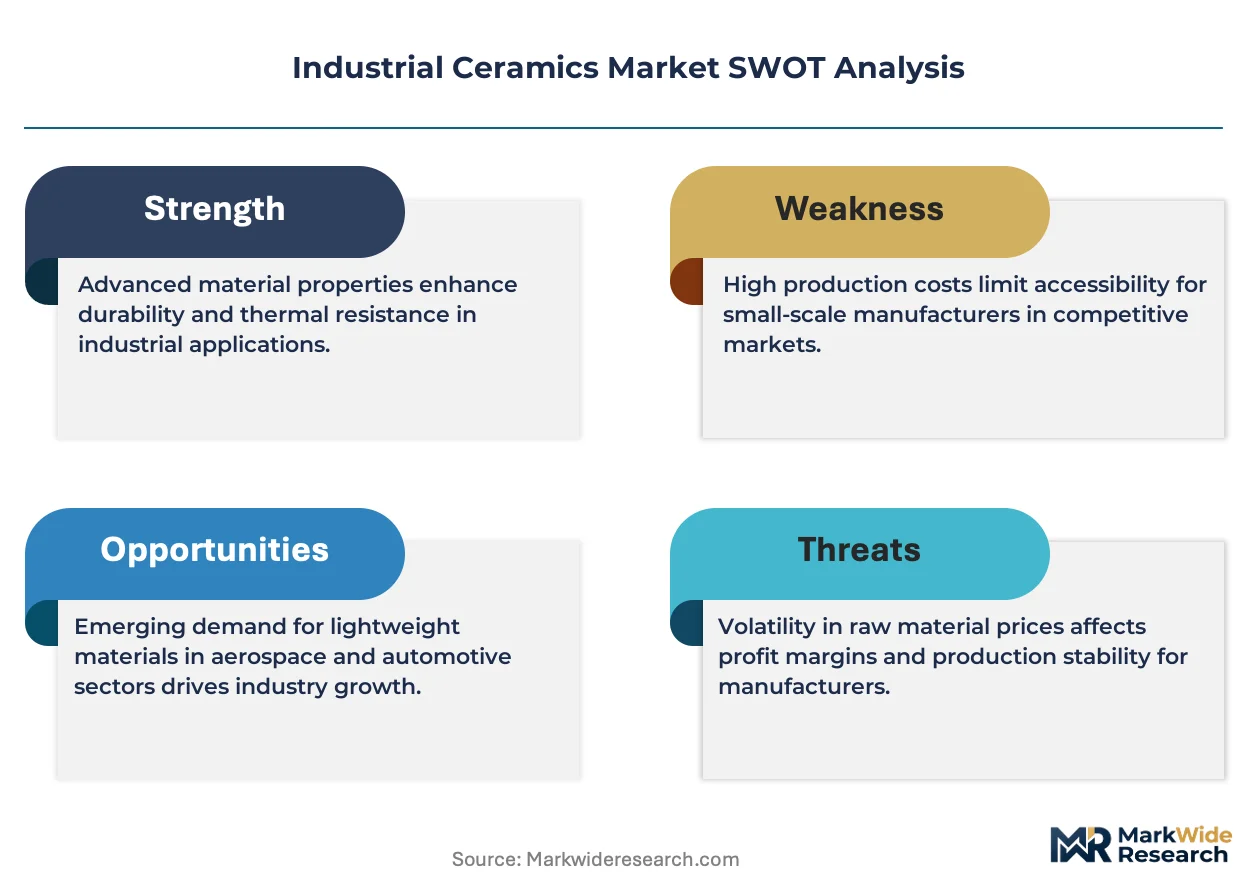
For Market Incumbents: Lock in powder synthesis capabilities through backward integration or long-term offtake agreements with high-purity alumina suppliers. Defend margin pools by accelerating water-based binder qualification ahead of EPA emissions timeline compressions that threaten phenolic-dependent competitors. Prioritize certification investment in semiconductor-grade substrates where KYOCERA's dominance leaves room for specialized second-source positioning. For New Entrants and Emerging Players: Binder jet additive manufacturing offers a technology-first wedge into medical device and aerospace qualification pipelines where batch-size flexibility outweighs incumbent scale advantages. Target ceramic matrix composite turbine components for US and European aerospace programs, the most penetrable segment given batch-processing constraints that resist continuous manufacturing economics. Pursue equipment-as-service contracting models that transfer performance risk and capture recurring revenue streams from manufacturing buyers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ceramic specialists because fragmented powder synthesis IP and proprietary sintering schedules resist rapid technology transfer. Five-to-ten year viability hinges on regulatory compliance capabilities rather than scale alone. Watch ECHA additive restriction expansion timelines as the inflection signal determining which formulation platforms capture stranded premium-tier demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captive alumina supply secures margin control against energy-driven input volatility. |
| Water-Based Binder Reformulation | EPA emissions compliance timelines force capital-intensive kiln modifications at phenolic-dependent facilities. |
| Additive Manufacturing Qualification | Binder jet printing opens geometries impossible through conventional pressing for aerospace medical buyers. |
| Equipment-as-Service Contracting | Operational expenditure models transfer performance risk from German semiconductor equipment buyers to vendors. |
| Ceramic Matrix Composite Capacity Expansion | Hotter-running turbine programs in the United States expand addressable volume for lighter structural components. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at sintering facilities, procurement leads at semiconductor equipment OEMs, technical R&D directors at powder synthesis operations, and aftermarket service heads at refractory installation contractors with secondary validation. Trade data from USITC and Eurostat, SEC 10-K filings from listed ceramic producers, ECHA REACH registration databases, and METI industrial standard disclosures anchored volume estimates. Bottom-up fabrication capacity counts triangulated against top-down end-use demand modeling.
Segment-weighting across material type, application temperature threshold, and regulatory compliance tier drove value allocation throughout the projection horizon. Product-level CAGRs derived from elasticity-adjusted demand curves for semiconductor packaging substrates, aerospace turbine components, and steel refractory linings. Silicon carbide displacement rates in furnace applications and additive manufacturing adoption curves in medical devices served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA additive restriction scope, EPA emissions timeline enforcement, and energy price volatility affecting sintering economics. Forecasts reflect documented assumptions about regulatory implementation pace and technology qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Nanoceramic Powder Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Glazed Bricks Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Ceramic Kilns Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
China Ceramic Market
Ceramics
Global Industrial Clay Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Ceramic Armor Materials Market
Ceramics
2N High Purity Alumina Market
Ceramics
Ceramic Substrate Market