
 Ceramic Pigments Market | 2026-2036
Ceramic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Pigments Market Analysis
Project finance for brownfield kiln upgrades is reconfiguring competitive entry barriers across the ceramic pigments value chain. BASF SE leverages its integrated precursor supply to sustain cost advantages in complex inorganic color crystals. Torrecid Group anchors Mediterranean supply through captive frit production facilities in Spain and Italy. The Shepherd Color Company differentiates via high-performance infrared-reflective pigments for energy-efficient building envelopes.
Ceramic pigments are finely ground inorganic or organic colorants, typically metal oxide compositions fired at 800–1300°C, that impart permanent color to glazes, bodies, and decorative surfaces through solid-state reactions with silicate matrices. Their primary commercial purpose is to deliver thermal stability, chemical resistance, and lightfastness in architectural tile, tableware, sanitaryware, and industrial glass. Inorganic pigments dominate volume due to their cost position in commodity tile production, while specialty pigments command margin pools in automotive glass and artistic ceramics where spectral precision justifies premium positioning. Paints and coatings applications are gaining share as exterior facade systems adopt ceramic-based colorants for UV durability advantages over organic alternatives.
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants constrain chromium and nickel compound usage in U.S. manufacturing facilities. REACH Annex XVII restrictions in Europe limit cadmium, lead, and hexavalent chromium migration in consumer-contact ceramic articles, redirecting formulation R&D toward rare earth and perylene alternatives. China's GB standards for ceramic product safety, administered by SAMR, impose parallel heavy metal leachate thresholds that export-oriented pigment producers must satisfy. Stakeholders must monitor evolving green chemistry mandates across these jurisdictions to anticipate raw material substitution cycles and compliance-driven price resets.
Market Dynamics
REACH Annex XVII cadmium restrictions and EPA National Emission Standards for Hazardous Air Pollutants are forcing wholesale heavy metal substitution across inorganic pigment formulations, compressing legacy supply chains while opening margin pools for rare earth alternatives.
Growth Catalysts
- Residential construction in India:Government housing schemes and urban infrastructure investments drive ceramic tile consumption, absorbing substantial volumes of zircon-based pigments from domestic blending operations.
- REACH compliance deadlines:European regulatory pressure on lead and hexavalent chromium migration accelerates R&D investment in perylene and rare earth substitute chemistries across export-oriented producers.
- Infrared-reflective pigment technology:Energy-efficient building envelope mandates in warm-climate jurisdictions create specification pull for high-performance colorants that reduce thermal load.
Market Restraints
- Cobalt price volatility:Supply concentration in the Democratic Republic of Congo and refined metal processing in China exposes blue pigment margins to raw material cost swings.
- Technical limitation in chromatic range:Cadmium-free alternatives struggle to match the saturation and thermal stability of legacy sulfoselenide reds in high-fire artistic ceramic applications.
- Substitution threat from organic pigments:UV-stable organic colorants encroach on decorative tile segments where thermal performance requirements have relaxed.
Strategic Opportunities
- Underpenetrated Brazil interior markets:Northern and northeastern states exhibit ceramic tile consumption gaps relative to southeast industrial centers, offering volume expansion for regional pigment distributors.
- Automotive glass specification:Spectral precision requirements for windscreen and sunroof applications command premium positioning for complex inorganic color crystals with narrow transmission bands.
- China dual carbon goals:National emissions intensity targets incentivize kiln efficiency upgrades that favor pigments with lower firing temperature requirements and reduced energy input.
Industry Challenges
- Formulation chemist scarcity:Solid-state reaction expertise for silicate matrix compatibility resides with aging technical workforces in Italy and Spain, constraining new product development velocity.
- Certification timeline compression:SAMR GB standard updates for ceramic product safety require accelerated testing protocols that strain quality assurance bandwidth at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Pigments Market |
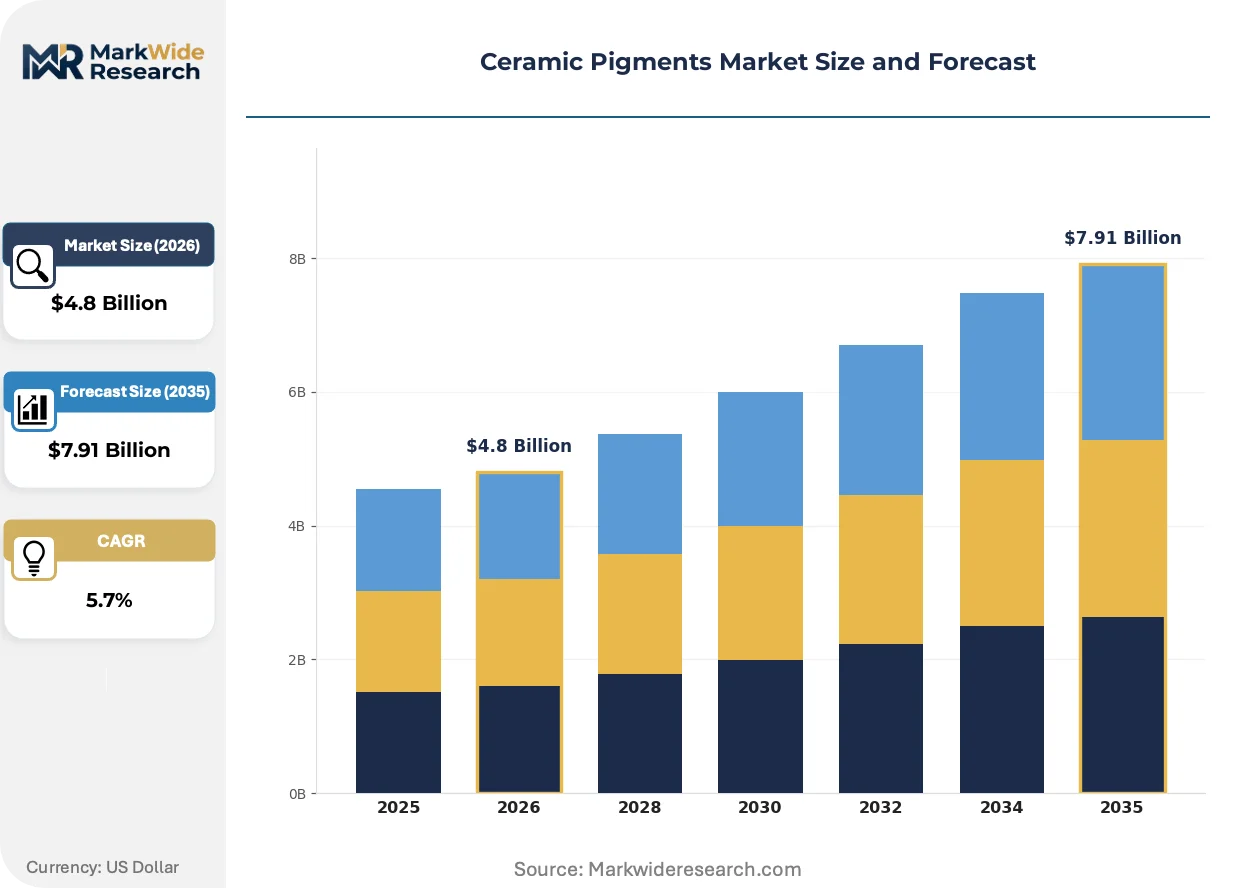
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Pigments, Organic Pigments, Specialty Pigments, Color Additives Application: Ceramic Tiles, Glass Manufacturing, Artistic Ceramics, Paints & Coatings End User: Construction Industry, Automotive Sector, Artisans, Household Goods Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | BASF SE, Torrecid Group, Vibrantz Technologies, Zhonglong Materials, Heubach GmbH, Sun Chemical, Lanxess AG, DIC Corporation, The Shepherd Color Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Pigments Market Emerging Trajectories
Digital inkjet printing adoption in tile manufacturing is collapsing minimum order quantities and accelerating colorway turnover, forcing pigment suppliers to reconfigure batch economics and inventory structures around just-in-time chromatic matching.
Encapsulated cadmium pigment technology is hybridizing heavy metal containment with color performance, enabling compliance with REACH migration limits while preserving the thermal stability that architectural tile producers require for high-fire glazes. Italian equipment manufacturers are integrating these encapsulated systems into digital decoration lines for export markets. The technology is compressing the viable window for fully cadmium-free alternatives in saturation-critical applications.
EPA hazardous air pollutant standards for chromium compounds are constraining U.S. manufacturing facility emissions profiles, redirecting domestic production toward precursor importation and toll processing arrangements. Pigment blenders in Ohio and Tennessee are restructuring supply contracts to source calcined intermediates from European tollers. The sanitaryware segment faces the steepest compliance cost escalation due to its reliance on nickel and chromium-based blacks.
Buyer consolidation among Chinese tile producers in Guangdong province is concentrating procurement leverage among a handful of vertically integrated manufacturers. Specification decisions now centralize at headquarters technical centers rather than distributed plant laboratories, compressing supplier access points and favoring pigment houses with direct technical service presence in Foshan. This concentration is most visible in commodity zircon-based opacifier and stain volumes.
Ceramic Pigments Market Segmentation
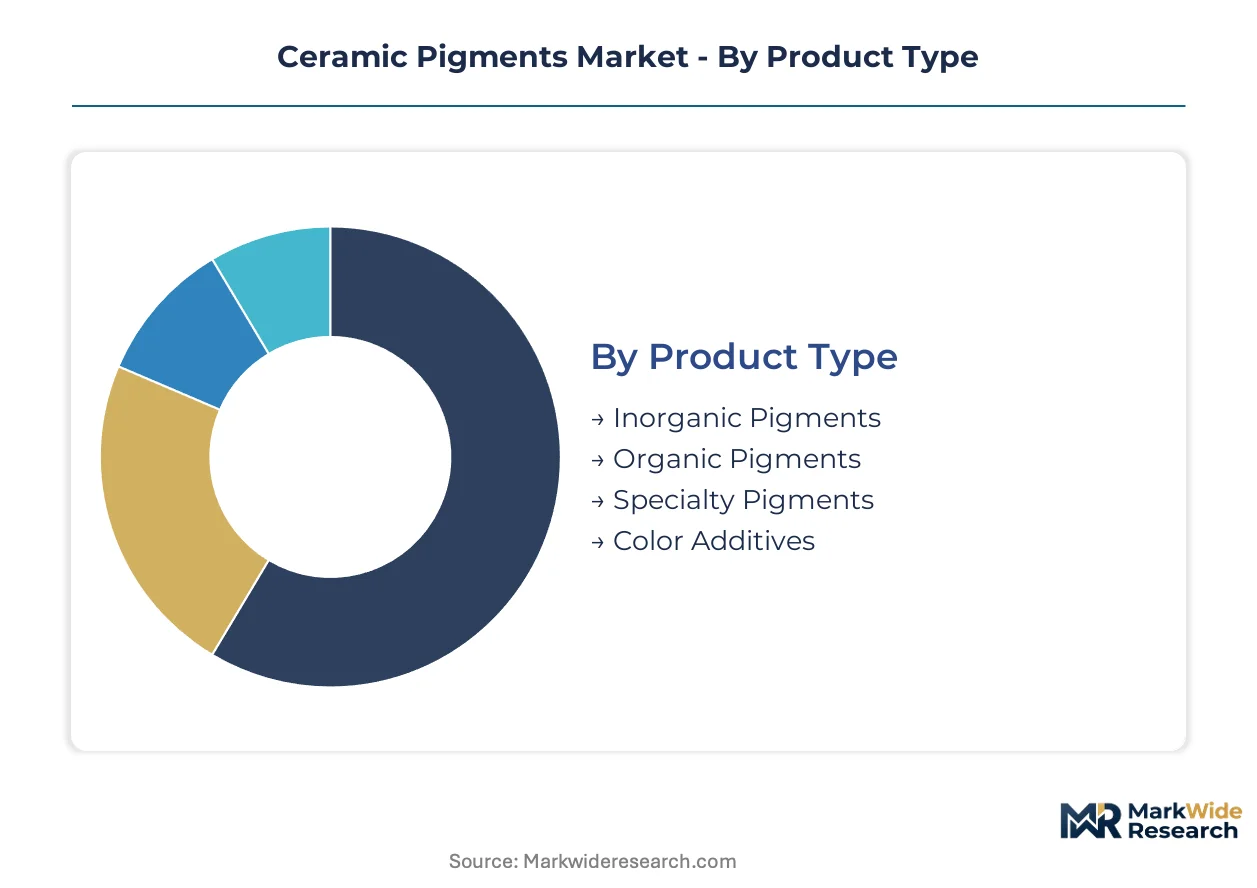
Ceramic pigments fragment across technical performance tiers and procurement channels that dictate formulation cycles and margin capture. Understanding where specification authority concentrates versus where price competition dominates separates viable market entry from commodity trap exposure.
Product Type:
Cycle times vary dramatically across pigment chemistries, with commodity inorganic formulations turning inventory monthly while specialty crystal structures require quarterly production runs and customer qualification periods.
- Inorganic Pigments:Metal oxide compositions—primarily iron, chromium, cobalt, and manganese oxides—deliver thermal stability above 1000°C through solid-state reactions with silicate matrices. Demand concentrates in China's Guangdong province tile clusters, where zircon-based opacifiers and cobalt blues absorb volume from domestic blending operations facing SAMR heavy metal compliance deadlines.
- Specialty Pigments:Complex inorganic color crystals engineered for narrow spectral transmission bands and infrared reflectance. Automotive glass specifications for windscreen and sunroof applications in Germany and Japan command premium positioning, with Shepherd Color Company and BASF SE anchoring supply through direct technical service relationships.
- Organic Pigments:UV-stable azo and phthalocyanine chemistries encroaching on decorative tile segments where thermal performance requirements have relaxed below 800°C firing temperatures.
- Color Additives:Concentrated dispersions and masterbatches simplifying downstream handling for mid-scale tile producers in India and Brazil.
Inorganic pigments dominate installed base. Specialty pigments are where expansion concentrates.
Application:
Cost tiers separate architectural commodity volumes from precision specification markets, with glazing line automation driving divergent procurement patterns across segments.
- Ceramic Tiles:Wall and floor tile glazes, bodies, and decorative surfaces consuming the majority of zircon-based opacifiers and stains. India's government housing schemes and urban infrastructure investments drive absorption, with Rajasthan and Gujarat production clusters sourcing from domestic blending operations.
- Glass Manufacturing:Architectural and automotive glass requiring spectral precision for solar control and aesthetic transmission. REACH-compliant encapsulated cadmium systems from Italian equipment integrators serve export markets, while domestic U.S. production faces EPA chromium compound emission constraints.
- Paints & Coatings:Exterior facade systems adopting ceramic-based colorants for UV durability advantages over organic alternatives in warm-climate construction.
- Artistic Ceramics:High-fire studio and tableware applications where cadmium-free sulfoselenide red alternatives struggle to match saturation and thermal stability.
Ceramic tiles anchor volume throughput. Glass manufacturing commands margin concentration.
End User:
Customer type determines specification authority, with consolidated procurement at headquarters technical centers displacing distributed plant-level decision-making.
- Construction Industry:Residential and commercial building projects across India, China, and Brazil absorbing commodity pigment volumes. Buyer consolidation among Guangdong tile producers centralizes procurement leverage among vertically integrated manufacturers.
- Automotive Sector:OEM glass specifications for windscreen, sunroof, and display applications requiring narrow transmission band precision. Torrecid Group anchors Mediterranean supply through captive frit production facilities in Spain and Italy.
- Household Goods:Sanitaryware and tableware producers facing steepest compliance cost escalation due to nickel and chromium-based black reliance under EPA hazardous air pollutant standards.
- Artisans:Studio ceramicists and small-batch producers sourcing through specialty distributors with technical support for high-fire glaze formulation.
Construction Industry holds installed base concentration. Automotive Sector shows the steepest expansion trajectory.
Distribution Channel:
Supply concentration shapes access economics, with direct technical service presence in production clusters displacing arm's-length distributor relationships.
- Direct Sales:Technical service teams embedded in Foshan, Guangdong and Sassuolo, Italy providing formulation support and just-in-time chromatic matching for digital inkjet printing lines.
- Distributors:Regional pigment blenders in Ohio and Tennessee restructuring toward toll processing arrangements as EPA emissions standards constrain domestic calcination capacity.
- Online Retail:Emerging channel for artisan and small-batch producers requiring low minimum order quantities and rapid colorway turnover.
- Specialty Stores:Local supply points for studio ceramicists with technical consultation on glaze compatibility and firing behavior.
Direct Sales commands specification authority. Distributors retain volume scale in fragmented regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction material procurement in India, China, and Brazil absorbs the majority of commodity ceramic pigment volumes, while European and North American demand concentrates in specification-driven automotive and sanitaryware applications.
China
Guangdong province tile manufacturers consolidate procurement leverage through vertically integrated headquarters technical centers in Foshan. SAMR GB standards for ceramic product safety impose heavy metal leachate thresholds that export-oriented pigment producers must satisfy. The Pearl River Delta production clusters absorb substantial volumes of zircon-based opacifiers and cobalt blues from domestic blending operations.
India
Government housing schemes and urban infrastructure investments drive ceramic tile consumption across Rajasthan and Gujarat production clusters. BIS certification requirements for construction materials create compliance barriers for imported pigment formulations. Rajasthan and Gujarat tile manufacturers source zircon-based pigments from domestic blending operations facing technical workforce constraints.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain chromium and nickel compound usage in Ohio and Tennessee manufacturing facilities. Pigment blenders in these states restructure supply contracts toward toll processing arrangements and calcined intermediate importation. The sanitaryware segment faces steepest compliance cost escalation due to reliance on nickel and chromium-based blacks.
Germany
Automotive glass specifications for windscreen and sunroof applications command premium positioning for complex inorganic color crystals with narrow transmission bands. REACH Annex XVII restrictions on cadmium and hexavalent chromium migration redirect formulation R&D toward rare earth alternatives. Technical service relationships with OEMs concentrate specification authority among pigment houses with direct automotive presence.
Brazil
Northern and northeastern states exhibit ceramic tile consumption gaps relative to southeast industrial centers, offering volume expansion for regional pigment distributors. ANVISA regulatory alignment with international heavy metal standards shapes import qualification timelines for European and Asian suppliers. São Paulo and Minas Gerais anchor production capacity while distribution networks extend toward underpenetrated interior markets.
Ceramic Pigments Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct margin pools. BASF SE leverages integrated precursor supply to sustain cost advantages in complex inorganic color crystals. The vendor base organizes around three archetypes: diversified chemical conglomerates with captive raw material positions, regional frit and pigment blenders with embedded technical service, and niche specialists in high-performance infrared-reflective or encapsulated systems. Capacity expansion in China's Guangdong province and toll processing arrangements in the United States represent the dominant competitive moves.
Within the diversified chemical tier, BASF SE and Lanxess AG exemplify integrated upstream positions. Among regional specialists with captive frit production, Torrecid Group anchors Mediterranean supply through Spain and Italy facilities. The Shepherd Color Company occupies a position in high-performance specialty pigments for energy-efficient building envelope applications. These three archetypes represent distinct competitive positions without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| BASF SE |
| Torrecid Group |
| Vibrantz Technologies |
| Zhonglong Materials |
| Heubach GmbH |
| Sun Chemical |
| Lanxess AG |
| DIC Corporation |
| The Shepherd Color Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Guangdong province calcination facilities is compressing spot pricing for zircon-based opacifiers while simultaneously accelerating supplier consolidation around toll-processing arrangements that preserve margin for technical service-heavy pigment houses. This utilization dynamic feeds directly into buyer procurement leverage, as vertically integrated tile manufacturers in Foshan centralize specification authority and demand volume-discounted contract structures from domestic blenders operating below breakeven utilization thresholds.
Pricing Analysis
Certification level (REACH-compliant vs. standard-grade) creates the primary spread between pigment tiers, with cadmium-free and lead-free formulations commanding substantial premia over legacy heavy metal compositions in European and North American markets. Three-tier pricing structure across premium specialty crystals, standard inorganic oxides, and economy-grade stains separates automotive glass specifications from commodity tile applications. Cost compression in the standard-grade tier is intensifying because of buyer consolidation among Guangdong tile producers and parallel import competition from Indian domestic blenders. Small-batch artisan producers exhibit the highest price sensitivity due to minimum order quantity constraints, while automotive OEMs demonstrate the least sensitivity given the qualification costs of pigment substitution.
Supply Chain Analysis
Upstream feedstock concentration in the Democratic Republic of Congo for cobalt metal and China's Jiangxi province for rare earth oxides anchors pigment cost structures to geopolitically exposed supply nodes. Manufacturing draws from South African chromite, Australian zircon, and Chinese processed intermediates as core mineral inputs. Single-source vulnerability in cobalt refining—where Chinese processors control the majority of global capacity—exposes blue pigment margins to supply disruption risk from export licensing shifts. Distribution runs through direct technical service teams embedded in Foshan and Sassuolo for large tile producers, with regional distributors handling fragmented artisan and sanitaryware accounts in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ceramic Pigments Market is positioned for cyclical recovery as residential construction activity rebounds across India and Brazil following post-pandemic infrastructure investment cycles. Government housing schemes and urbanization mandates in these markets will absorb excess commodity pigment capacity and restore pricing power to technical service-differentiated suppliers.
For Market Incumbents: Entrench specification authority through embedded technical service teams in Guangdong and Rajasthan production clusters, defending against substitute encroachment from UV-stable organic pigments in decorative tile segments. Prioritize backward integration into rare earth oxide sourcing to offset cobalt price volatility exposure, while accelerating REACH-compliant encapsulated cadmium qualification timelines to preserve saturation-critical architectural applications before fully cadmium-free alternatives mature.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's northern and northeastern interior states, where ceramic tile consumption gaps relative to southeast industrial centers offer volume expansion without confronting entrenched supplier relationships in São Paulo. Target the automotive glass specification segment through narrow-band complex crystal development, leveraging toll-processing partnerships with European calciners to bypass EPA emission constraints on domestic U.S. manufacturing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pigment houses with captive frit production and direct OEM technical service relationships, as these structures lock in multi-year qualification cycles and resist spot-price commoditization. Long-term viability over the coming decade hinges on regulatory compliance agility and rare earth substitution chemistry capabilities. Monitor SAMR GB standard update implementation timelines as the critical inflection signal for raw material substitution cycles and compliance-driven price resets across export-oriented producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxides | Reduces cobalt price volatility exposure for blue pigment portfolios through Jiangxi province supply partnerships. |
| Encapsulated Cadmium Qualification Acceleration | Preserves architectural tile market access under REACH migration limits before fully cadmium-free alternatives achieve parity. |
| Technical Service Expansion in Foshan | Secures specification authority with consolidating Guangdong tile producers centralizing procurement at headquarters technical centers. |
| Toll Processing Partnerships in Ohio | Restructures U.S. manufacturing toward calcined intermediate importation to satisfy EPA hazardous air pollutant standards. |
| Infrared-Reflective Pigment R&D Investment | Captures energy-efficient building envelope mandates in warm-climate jurisdictions through Shepherd Color Company-type positioning. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ceramic pigment plant managers, tile producer procurement leads, frit manufacturing technical directors, and automotive glass specification engineers; and secondary validation through customs trade data, SEC 10-K filings of diversified chemical conglomerates, SAMR GB standard documentation, and ECHA REACH restriction updates. Bottom-up triangulation across these sources anchored volume estimates in actual production capacity and procurement contract structures, while top-down cross-checks against construction material consumption indices and automotive glass production databases ensured segmentation coherence.
Forecast inputs incorporated pigment grade tier, end-use application intensity, regional regulatory cluster, and kiln technology adoption patterns across the projection horizon. CAGRs were derived from segmented volume build-ups calibrated to construction activity indices and automotive production schedules, with explicit modeling of substitution effects from organic pigments in low-fire decorative segments and rare earth alternatives in heavy metal-restricted formulations.
Stress conditions across cobalt price volatility bands, REACH enforcement intensity scenarios, and Chinese tile producer consolidation trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure investment continuity. Cross-checking against ceramic tile production databases and automotive glass shipment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Ware Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Optical Ceramics Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Aluminium Nitride Market
Ceramics
Automotive Ceramics Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Calcined Kaolin Market
Ceramics
Fire Clay Market
Ceramics
Cement Castables Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Mullite Market
Ceramics
Dielectric Ceramics Market
Ceramics
Alumina Slurry Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Global High Performance Ceramic Coatings Market