
 Global Ceramic Foams Market | 2026-2036
Global Ceramic Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Foams Market Intelligence
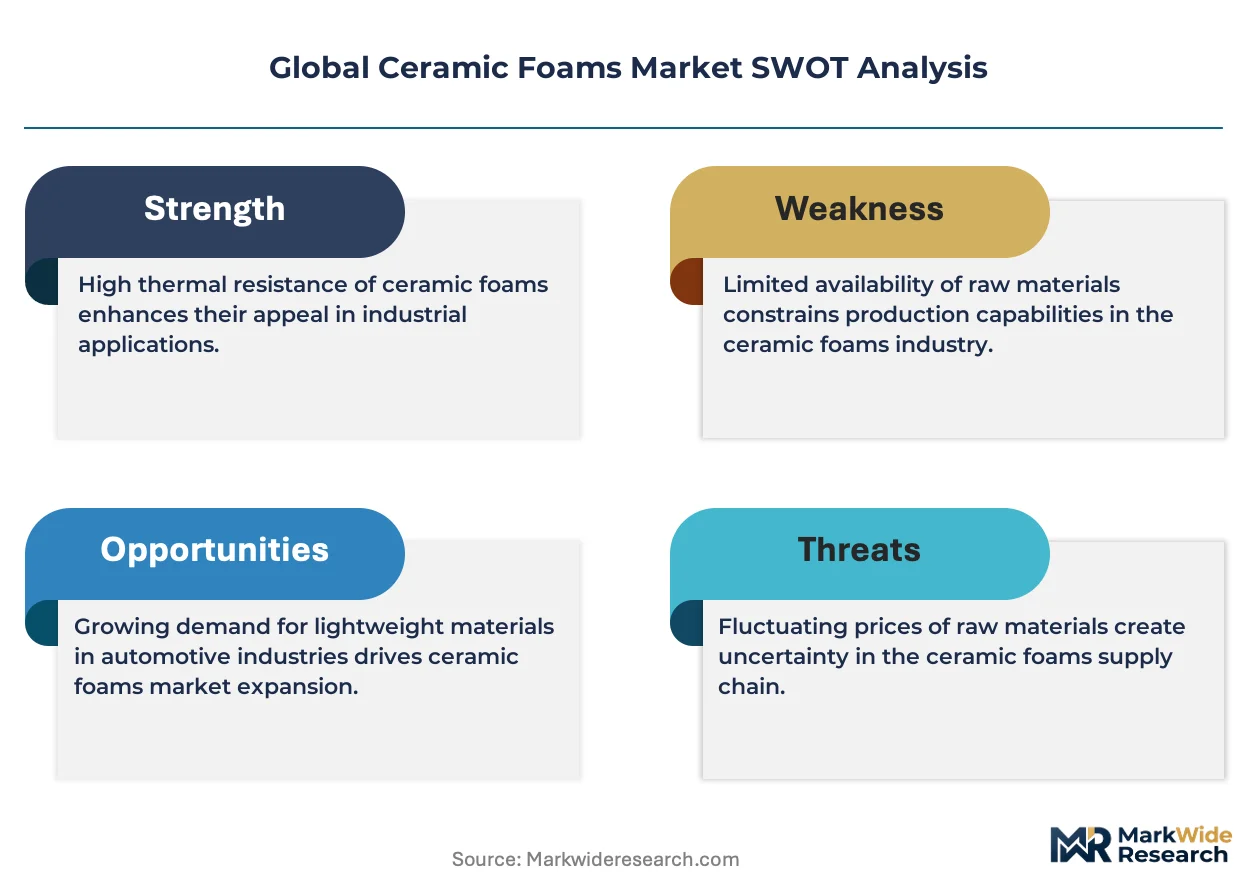
The development of high-purity, uniform-pore-structure foams is reorganizing material selection criteria in high-temperature applications. Saint-Gobain leverages its extensive materials science portfolio to address filtration and refractory needs across multiple industries. Morgan Advanced Materials specializes in advanced ceramic components for demanding thermal environments. SELEE Corporation competes with its focused expertise in molten metal filtration systems.
Ceramic foams are porous, three-dimensional structures composed of interconnected ceramic struts. These materials, often produced via the polymer sponge method, possess high thermal stability and low thermal conductivity, making them ideal for molten metal filtration. Alumina and silicon carbide foams command the largest share among product types due to their widespread use in foundries. The filtration media application represents the most mature segment, while catalyst supports show significant potential in chemical processing.
Environmental regulations, including the EU's REACH framework and EPA rules in the United States, influence material composition and disposal. Concurrently, ISO standards for thermal performance and material purity guide product specifications for aerospace and defense applications. Future competitiveness depends on developing cost-effective manufacturing for advanced materials like zirconia and silicon nitride foams.
Market Dynamics
Intensifying performance demands from aerospace and chemical processing sectors are creating a structural tension. This is because cost-effective production of mature alumina foams conflicts with the high-purity, specialized manufacturing required for advanced zirconia and silicon nitride materials.
Growth Catalysts
- Aerospace Lightweighting:Demand for lightweighting in commercial and defense aircraft drives adoption for thermal management systems and composite tooling, where low density and high thermal stability are critical.
- Foundry Modernization:Foundries in industrial clusters across China and India require higher-purity alumina and silicon carbide foams to improve casting yields and reduce inclusion defects in molten metals.
- Environmental Mandates:EU and EPA emissions rules for industrial furnaces and vehicles compel the use of ceramic foams as efficient catalyst supports to meet stricter pollution control standards.
Market Restraints
- Raw Material Volatility:The high cost of precursor materials like high-purity zirconia powder directly impacts profitability and limits competitiveness against traditional refractories in cost-sensitive applications.
- Mechanical Brittleness:Inherent brittleness complicates final part machining and handling during installation, leading to higher scrap rates and operational risk for end-users in demanding environments.
- Energy-Intensive Production:Sintering processes create significant exposure to volatile electricity prices, a key challenge for manufacturers located in Germany and other high-energy-cost regions.
Strategic Opportunities
- Biomedical Scaffolds:Zirconia and calcium phosphate-based foams are being explored as scaffolds for bone tissue engineering, representing a high-value, underpenetrated medical device market.
- Advanced Material Development:Developing cost-effective manufacturing for silicon nitride foams can unlock applications in semiconductor processing equipment and high-wear industrial components.
- Chemical Process Intensification:Porous silicon carbide foams offer significant potential as compact, efficient heat exchangers and reactor packings in the chemical industry, improving energy efficiency.
Industry Challenges
- Pore Structure Uniformity:Achieving consistent, uniform pore structures across large-volume production batches remains a primary manufacturing hurdle, affecting performance predictability in filtration applications.
- Standardization Gaps:A lack of universally accepted ISO testing standards for mechanical properties like compressive strength creates procurement friction for aerospace and defense buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Foams Market |
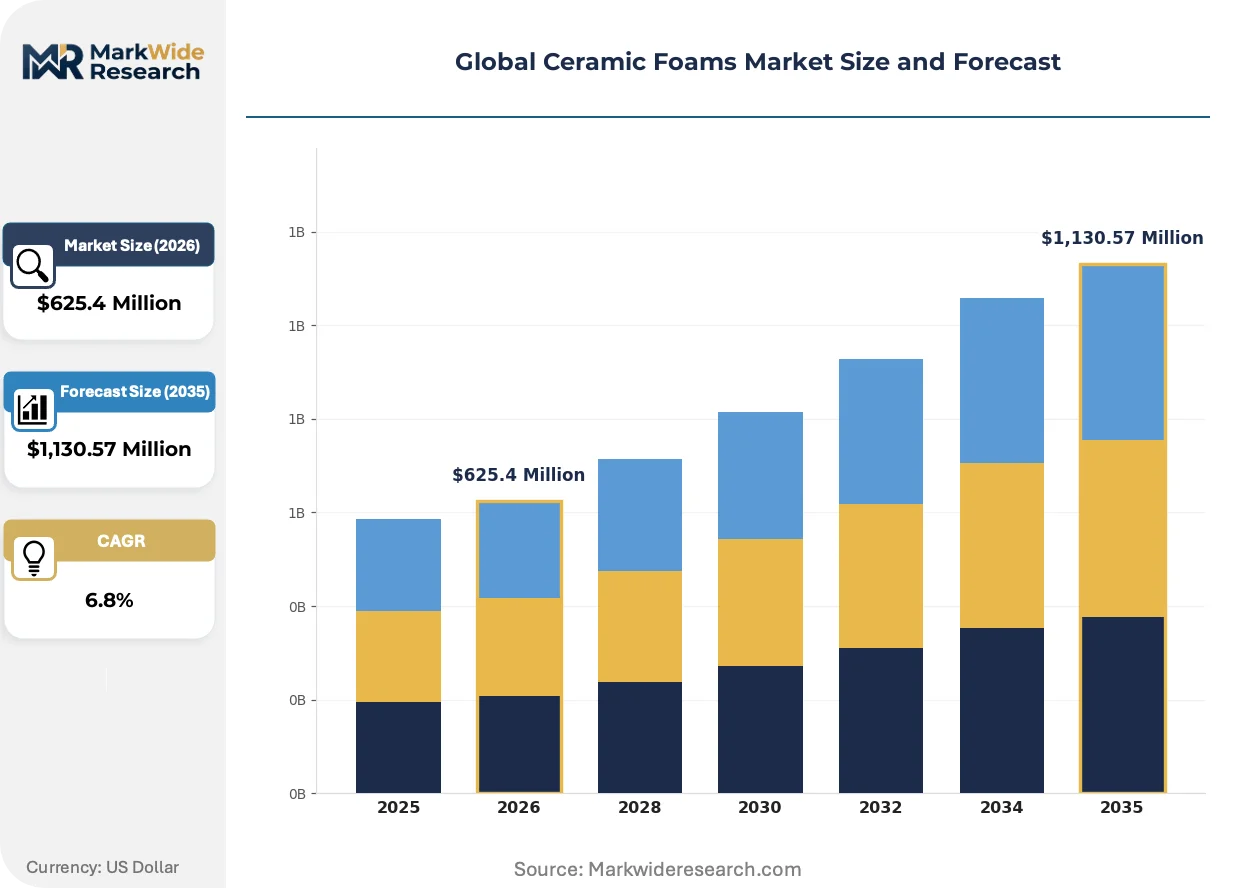
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,130.57 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Zirconia, Silicon Carbide, Mullite, Porcelain, Silicon Nitride Application: Filtration Media, Thermal Insulation, Catalyst Supports, Acoustic Dampening, Refractory Linings, Biomedical Implants Manufacturing Technique: Sintering, Polymer Sponge Method, Replica Technique, Direct Foaming, Freeze Casting, Sol-Gel Process End User Industry: Chemical Processing, Power Generation, Aerospace, Electronics, Environmental, Defense |
| Companies Covered | Vesuvius plc, Saint-Gobain, SELEE Corporation, Ultramet, Pyrotek, ERG Aerospace Corporation, CoorsTek, Inc., Morgan Advanced Materials, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Foams Market Strategic Shifts & Innovations
A pivot from commodity filtration media toward engineered materials with specified performance attributes defines the market's evolution. Process intensification in end-use sectors like chemical manufacturing and aerospace is accelerating this transition to application-specific foam architectures.
Direct foaming and freeze-casting techniques create highly uniform, tailored pore structures for advanced applications. Aerospace and biomedical sectors are the primary adopters, seeking precise material properties for thermal management and tissue scaffolds. This controlled manufacturing capability is displacing the less precise polymer sponge replication method for high-performance components where consistency is critical.
The European Union's REACH regulation continues to influence material selection by restricting substances of very high concern used in binders or as raw materials. This directly impacts producers of filtration and refractory products, forcing reformulation to ensure market access within the EU. Alumina and silicon carbide product lines are most affected, requiring investment in compliance and alternative material validation.
Buyer behavior is shifting toward procurement based on performance certifications rather than just bulk material composition. Aerospace and defense contractors increasingly specify foams meeting ISO standards for thermal conductivity and purity, disrupting traditional supplier relationships based on volume. This trend is most prominent in North America and Europe, favoring specialized manufacturers with robust quality assurance systems.
Global Ceramic Foams Market Segmentation
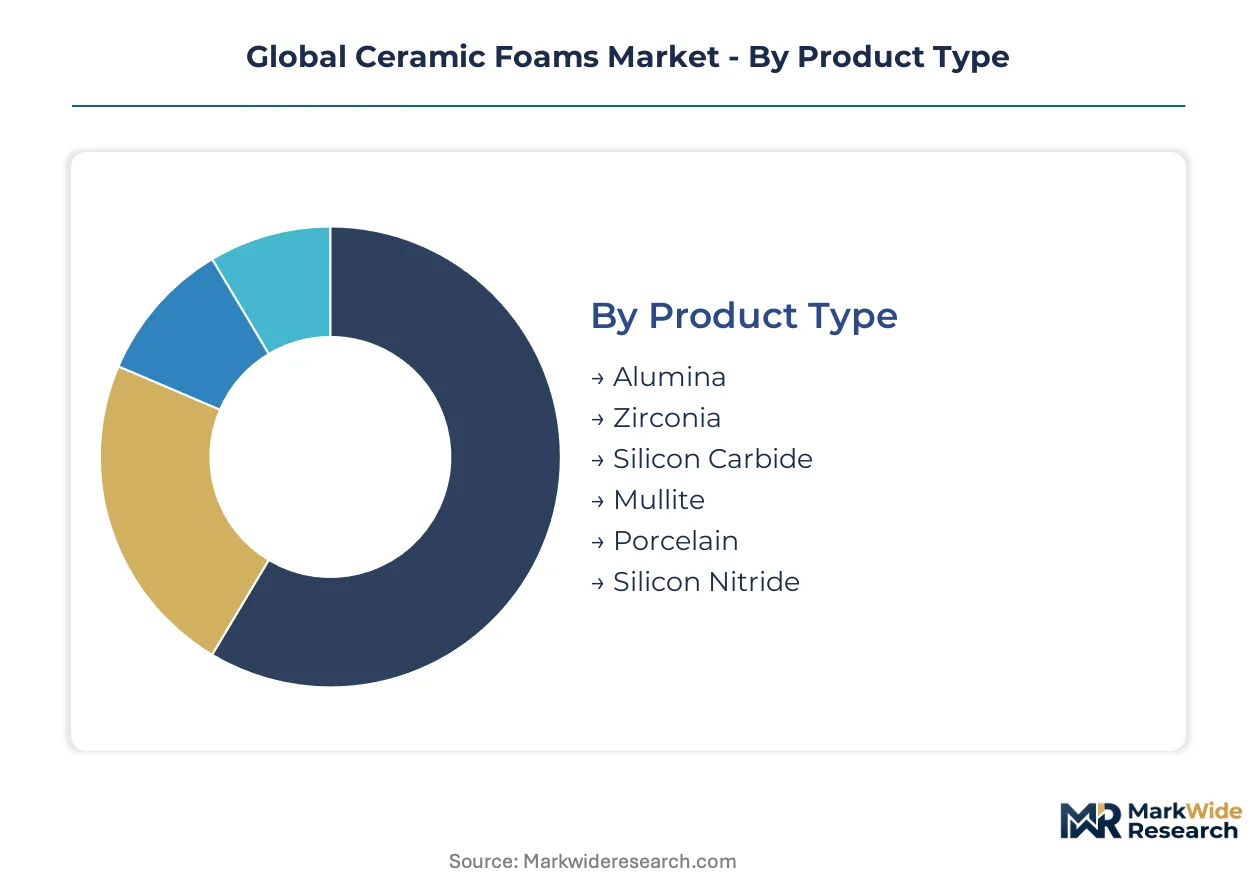
The ceramic foams market segments across diverse product types, applications, manufacturing techniques, and end-user industries. Understanding these distinctions helps identify where performance requirements drive material innovation versus where cost-efficiency dictates material selection. Each segment presents unique growth trajectories and competitive dynamics.
Product Type:
The ceramic foams market faces substitution pressure from traditional refractories, particularly in segments where cost-performance ratios are critical.
- Alumina:These foams, primarily composed of aluminum oxide, offer high thermal stability and chemical inertness. Foundries in China and India increasingly demand alumina foams to enhance molten metal filtration and reduce casting defects.
- Silicon Carbide:Known for its exceptional hardness, high thermal conductivity, and chemical resistance, silicon carbide foams are crucial for high-temperature applications. Demand for these materials is concentrating in chemical processing for catalyst supports and heat exchangers.
- Zirconia:Zirconia foams provide superior high-temperature strength and corrosion resistance, making them suitable for extreme environments.
- Mullite:Mullite-based foams exhibit good thermal shock resistance and low thermal expansion, finding use in refractory applications.
- Porcelain:Porcelain foams offer an economical option for less demanding thermal or structural applications.
- Silicon Nitride:Silicon nitride foams are prized for their excellent mechanical strength and thermal shock resistance, especially in advanced industrial components.
Alumina retains volume leadership; Silicon Nitride holds the steepest expansion curve.
Application:
Market maturity varies significantly across application segments, influencing investment and innovation priorities.
- Filtration Media:This segment is the most mature, utilizing ceramic foams to remove impurities from molten metals and hot gases. Foundries globally rely on these media to improve final product quality and reduce waste.
- Catalyst Supports:Ceramic foams provide high surface area and porous structures, making them ideal supports for catalysts in chemical reactions and emissions control. Environmental regulations in the EU and US are driving demand for more efficient catalyst systems.
- Thermal Insulation:These applications leverage the low thermal conductivity of ceramic foams for energy efficiency in furnaces, kilns, and aerospace components.
- Acoustic Dampening:Porous ceramic structures effectively absorb sound, finding use in noise reduction applications within industrial settings.
- Refractory Linings:Ceramic foams serve as lightweight, thermally stable linings in high-temperature furnaces and other industrial equipment.
- Biomedical Implants:Zirconia and calcium phosphate-based foams are being researched for bone tissue engineering due to their biocompatibility and porous structures.
Filtration Media represents the largest segment by volume; Biomedical Implants are expanding most quickly.
Manufacturing Technique:
Production centers for ceramic foams are concentrating in regions with specialized expertise and industrial infrastructure.
- Polymer Sponge Method:This widely used technique involves impregnating a polymer foam with a ceramic slurry, followed by drying and sintering. It offers a cost-effective route for producing various foam types, particularly alumina and silicon carbide.
- Direct Foaming:This method involves directly creating foam from a ceramic slurry by introducing gas, allowing for precise control over pore size and distribution. Aerospace and biomedical sectors adopt direct foaming for tailored material properties.
- Sintering:Sintering is the fundamental process of consolidating ceramic particles through heat, forming a solid, porous structure.
- Replica Technique:Similar to the polymer sponge method, this technique uses a sacrificial template to create the desired porous structure.
- Freeze Casting:Freeze casting involves solidifying a ceramic suspension by directional freezing, then sublimating the ice to create highly aligned pore structures.
- Sol-Gel Process:This chemical method allows for the creation of ceramic foams with very fine and uniform pore structures at lower temperatures.
The Polymer Sponge Method remains a dominant production route; Direct Foaming and Freeze Casting offer advanced capabilities.
End User Industry:
Performance demands from various end-user industries are creating distinct material specifications for ceramic foams.
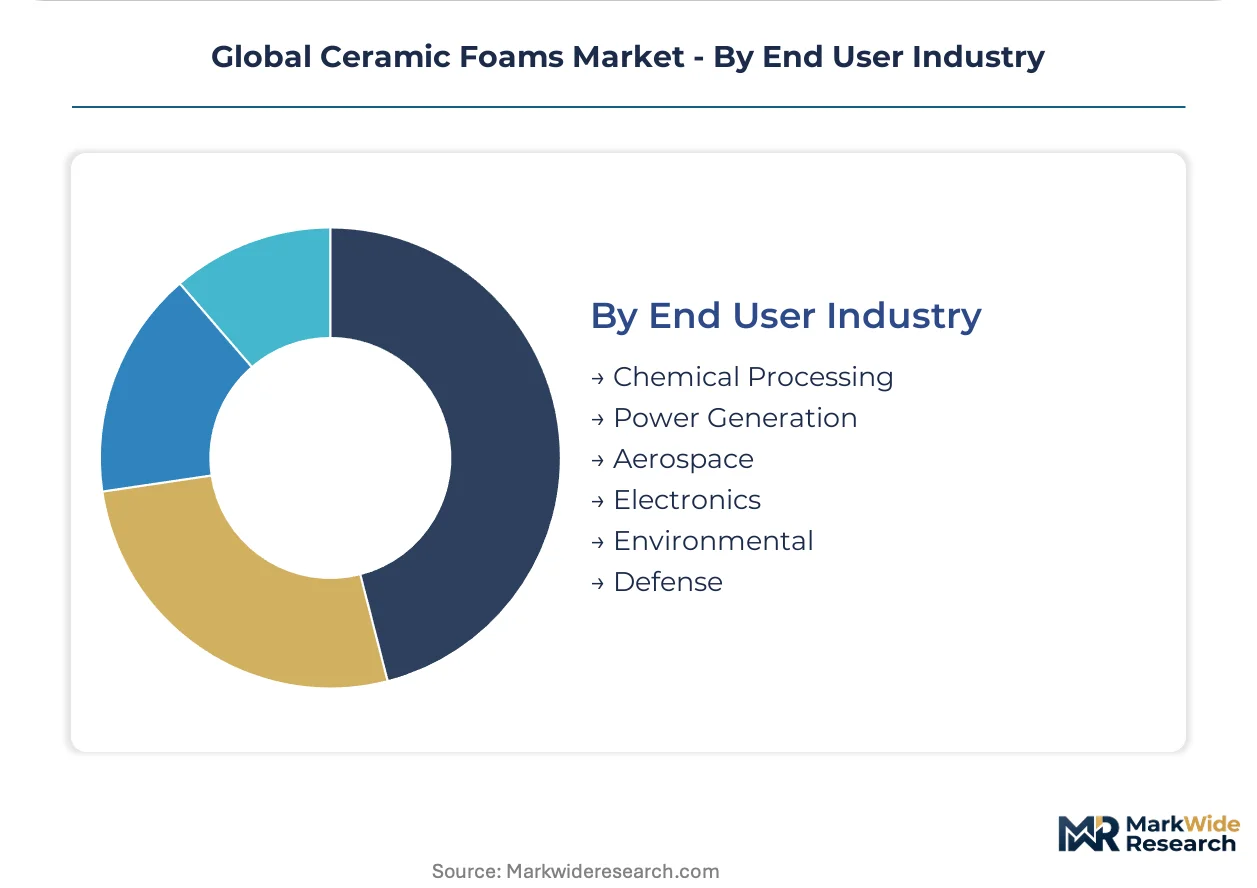
- Aerospace:This industry requires lightweight ceramic foams for thermal management systems, engine components, and composite tooling. Demand for low density and high thermal stability is critical for commercial and defense aircraft.
- Chemical Processing:Ceramic foams serve as catalyst supports, filter media, and heat exchangers in chemical reactors and industrial processes. Stringent EU and EPA emissions regulations compel the use of efficient catalyst systems.
- Power Generation:Ceramic foams are used in thermal insulation and filtration applications within power plants to improve efficiency and reduce emissions.
- Electronics:These foams find niche applications in electronic components requiring high-temperature resistance or specific dielectric properties.
- Environmental:The environmental sector utilizes ceramic foams for water filtration, air purification, and waste treatment systems.
- Defense:Similar to aerospace, the defense industry demands ceramic foams for lightweight armor, thermal protection, and specialized filtration in military equipment.
Aerospace and Chemical Processing drive significant innovation; Environmental applications exhibit consistent, regulatory-driven demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ceramic foams market exhibits a dynamic export-import balance, with production centers often supplying specialized materials to advanced manufacturing hubs globally. Demand for high-performance foams in aerospace and chemical processing drives significant international trade flows.
United States
Demand for lightweighting in defense aircraft and commercial aerospace drives ceramic foam adoption for thermal management systems. Federal Aviation Administration (FAA) regulations for material performance and safety influence product specifications for aviation components. Aerospace manufacturing clusters in Washington State, particularly around Seattle, concentrate demand for high-strength, low-density ceramic foams.
Germany
Germany's chemical processing sector requires advanced catalyst supports and heat exchangers, boosting demand for silicon carbide foams. The European Union's REACH framework directly influences material composition and safety standards for ceramic foam manufacturers. Industrial clusters in Bavaria, known for advanced materials research and automotive manufacturing, foster innovation in high-purity foam production.
China
China's extensive foundry industry requires higher-purity alumina and silicon carbide foams to improve casting yields and reduce inclusion defects. Compliance with GB standards for industrial emissions and material quality guides product development for local manufacturers. Production centers within the Yangtze River Delta, a major industrial hub, are expanding capacity for polymer sponge method ceramic foams.
India
India's foundry modernization efforts and infrastructure development projects create substantial demand for cost-effective alumina and silicon carbide filtration media. The government's Production Linked Incentive (PLI) scheme for manufacturing can support domestic production capabilities for advanced materials. Industrial clusters around Ahmedabad and Pune are emerging as key consumption points for ceramic foams in metal casting applications.
Japan
Japan's high-tech manufacturing, particularly in semiconductor processing, requires high-purity ceramic foams for specialized equipment and thermal management. Initiatives from the Ministry of Economy, Trade and Industry (METI) support research into advanced materials for industrial applications. Specialized manufacturers in Kyushu, a hub for electronics and automotive components, focus on developing silicon nitride foams with superior mechanical properties.
Global Ceramic Foams Market Key Industry Players
Concentration sits with established materials science conglomerates, while specialized manufacturers occupy niche segments for advanced ceramic foams. The market structure displays a tiered landscape, balancing high-volume commodity production with bespoke engineering solutions. Strategic archetypes include diversified materials giants, focused advanced ceramic component producers, and application-specific filtration specialists. Companies pursue capacity expansion and strategic partnerships to secure raw material supply and penetrate new end-user markets.
Within the diversified materials giants, Saint-Gobain represents a broad portfolio approach, leveraging extensive materials science capabilities for various industrial and refractory applications. Morgan Advanced Materials exemplifies a focus on advanced ceramic components, particularly for demanding thermal environments where precision engineering is critical. SELEE Corporation occupies a position as a specialized expert in molten metal filtration systems, demonstrating deep application expertise in foundry processes. These companies collectively anchor different segments of the ceramic foams market, from high-volume filtration to high-performance engineered solutions.
| Leading Market Players |
|---|
| Vesuvius plc |
| Saint-Gobain |
| SELEE Corporation |
| Ultramet |
| Pyrotek |
| ERG Aerospace Corporation |
| CoorsTek, Inc. |
| Morgan Advanced Materials |
| CeramTec GmbH |
| Others |
Cost & Logistics Intelligence
Ceramic foam production lead times for advanced materials reflect complex manufacturing processes, enabling premium pricing for specialized products. Conversely, shorter lead times for commodity alumina foams drive intense price competition. This structural difference dictates profitability across market segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for specialized ceramic foams. Pricing stratifies across performance tiers, with ISO standards for aerospace applications commanding a premium. Price differentiation stems from certification levels and customization requirements for specific end-uses. Pricing pressure intensifies for high-volume alumina foams due to overcapacity in China. Foundries in India exhibit significant price sensitivity for basic filtration media, while aerospace manufacturers prioritize performance over cost.
Supply Chain Analysis
China anchors polymer sponge method production of alumina and silicon carbide foams, leveraging extensive industrial infrastructure. Germany specializes in advanced material production, including high-purity zirconia and silicon nitride foams. The supply chain draws from high-purity alumina powder, silicon carbide precursors, and specialized zirconia powder. Raw material volatility, particularly for high-purity precursors, represents a structural risk. Distribution runs through direct sales channels for large industrial customers and specialized distributors for niche applications requiring technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by diverse performance demands from aerospace and biomedical sectors creating specialized niches.
For Market Incumbents: Fortify core market positions by investing in advanced manufacturing techniques like direct foaming and freeze casting. Secure long-term raw material contracts for high-purity precursors to mitigate supply chain volatility. Invest in R&D for silicon nitride and zirconia foams to counter emerging specialized manufacturers. Pursue ISO and other performance certifications for aerospace and defense applications to maintain market access.
For New Entrants and Emerging Players: Anchor in high-value, underpenetrated segments such as biomedical scaffolds and advanced semiconductor processing equipment. Target applications requiring precise pore structures and tailored material properties. A specific go-to-market angle involves offering rapid prototyping services for custom ceramic foam solutions. Focus on developing proprietary material science expertise to differentiate from established players.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven materials play because performance attributes directly correlate with manufacturing innovation. Acquisition targets should include specialized manufacturers holding patented direct foaming or freeze casting intellectual property. The signal to watch is increased adoption of silicon nitride foams in semiconductor processing, indicating readiness for broader industrial application.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Advanced Foams | This move addresses the growing demand for specialized materials in aerospace and biomedical applications. |
| R&D in Freeze Casting Techniques | This research unlocks highly uniform, tailored pore structures for next-generation thermal management systems. |
| Strategic Partnerships with Aerospace OEMs | These collaborations ensure product development aligns with critical requirements for lightweight thermal insulation. |
| Investment in High-Purity Raw Material Sourcing | This action mitigates supply chain risks and supports consistent quality for high-performance ceramic foams. |
| Certification for Biomedical Applications | This step validates biocompatibility and structural integrity for high-value tissue engineering scaffolds. |
Research Approach
Operator-level perspectives from plant managers, R&D directors, procurement leads, and material scientists anchored the qualitative base of this study. The analysis combined these primary interviews with rigorous secondary validation from company 10-K filings, industry association reports, patent databases, and government trade statistics. Researchers employed both bottom-up and top-down triangulation to ensure data accuracy and market coverage.
Sensitivity analysis informed the development of a robust analytical framework, projecting market trends across the modeling period. The framework modeled segmentation dimensions including product type, application, manufacturing technique, end-user industry, and regional demand profile. Compound annual growth rates were derived from detailed volume and value projections. Raw material price forecasts and aerospace production schedules served as critical industry-specific forecast inputs.
Material uncertainties — unforeseen regulatory changes, significant technological breakthroughs, or major shifts in global trade policies — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Solid End Mills Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Ceramics Packaging Market
Ceramics
Lithium Silicate Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
ME K-Feldspar Market
Ceramics
Lithium Zirconate Market
Ceramics
Alumina Slurry Market
Ceramics
Graphite Crucibles Market
Ceramics
Calcium Silicate Boards Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Zeolite 4A Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Iran Ceramic Tiles Market