
 Liquid Sodium Silicate Market | 2026-2036
Liquid Sodium Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Sodium Silicate Market Outlook
The gap between furnace-process and hydrothermal synthesis technologies is narrowing as energy efficiency becomes a decisive cost factor. PQ Corporation leverages captive alkali supply chains to sustain margin structures across North American operations. Evonik Industries AG anchors its position through R&D intensity in specialty silicate derivatives for electronics applications. BASF SE competes on global manufacturing scale, with integrated soda ash sourcing supporting volume flexibility.
Liquid sodium silicate is an aqueous solution of sodium oxide and silicon dioxide, typically produced via the dissolution of silica sand in molten sodium carbonate at temperatures exceeding 1300°C, yielding molar ratios between 1.6 and 3.75 SiO₂:Na₂O that determine binding strength and solubility. The material functions primarily as an inorganic adhesive, binder, and detergent builder across industrial and consumer formulations. Water glass formulations dominate volume flows in detergent and construction applications where cost-performance thresholds favor standard-grade alkalinity. Metasilicate segments command premium positioning in metal cleaning and textile processing, where controlled alkalinity and chelation properties justify higher unit economics. Adhesives and coatings applications show structural growth in automotive and paper end uses, driven by water-based formulation mandates replacing solvent-borne alternatives.
EPA effluent guidelines and OSHA silica exposure standards shape product specifications and plant-level compliance investments for U.S.-based producers. REACH registration requirements and the EU Green Deal chemicals strategy restrict certain heavy metal impurities while incentivizing lower-carbon production pathways across European supply chains. India's BIS certification and PLI scheme for specialty chemicals are creating new compliance benchmarks for import-dependent downstream sectors. Stakeholders must monitor how carbon border adjustment mechanisms and regional alkali price volatility reshape sourcing economics and capacity location decisions.
Market Dynamics
Energy intensity differentials between furnace-process and hydrothermal synthesis routes are compressing margin structures and forcing capacity relocation toward captive alkali supply sources.
Growth Catalysts
- EPA effluent guidelines:Tightening discharge standards for phosphate-containing detergents in the United States accelerate substitution toward sodium silicate builders in laundry formulations.
- Construction sector uptake:India's infrastructure investment cycle drives procurement of sodium silicate-based concrete admixtures for accelerated curing and waterproofing applications.
- Hydrothermal synthesis advancement:Energy-efficient production methods reduce carbon intensity and align with EU Green Deal chemicals strategy incentives for lower-carbon pathways.
Market Restraints
- Soda ash price volatility:Input cost swings tied to energy markets and synthetic versus natural ash sourcing disrupt margin predictability for non-integrated producers.
- Silica sand supply concentration:High-purity sand deposits cluster in specific geographies, creating geographic dependency risks for furnace-process operators.
- Zeolite substitution in detergents:Alternative builder chemistries compete for phosphate-replacement formulations in price-sensitive consumer segments.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Production-linked incentives attract capacity investments serving import-dependent downstream sectors including textiles and metal finishing.
- Electronics-grade silicate derivatives:Semiconductor packaging and display substrate applications create premium positioning for ultra-low-impurity formulations.
- Water-based coating mandates:Automotive and industrial coating regulations in Europe and North America displace solvent-borne systems with silicate-binder alternatives.
Industry Challenges
- REACH registration timelines:Extended substance evaluation periods for sodium silicate derivatives delay market access for specialty grades in European formulations.
- High-temperature furnace maintenance:Refractory replacement cycles and energy optimization require sustained capital deployment that strains mid-scale producer balance sheets.
- Silica exposure compliance:OSHA permissible exposure limit enforcement necessitates plant-level engineering controls and worker monitoring systems.
Report Scope
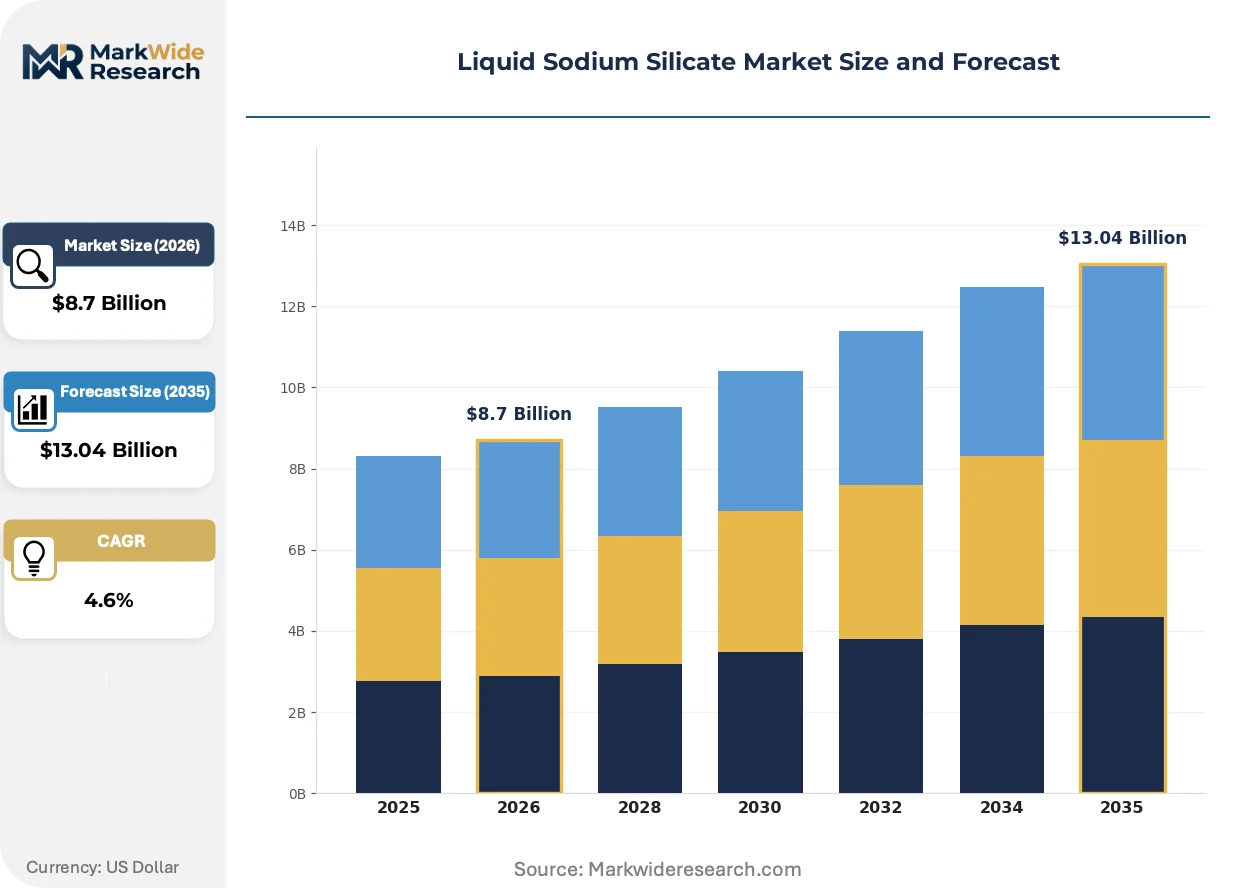
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Sodium Silicate Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Glass, Metasilicate, Trisilicate, Other Forms Application: Detergents, Adhesives, Coatings, Concrete End User: Construction, Automotive, Paper, Textile Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | PQ Corporation, Evonik Industries AG, BASF SE, Solvay S.A., Occidental Petroleum Corporation, Nippon Chemical Industrial Co., Ltd., Tokuyama Corporation, W. R. Grace & Co., Oriental Silicas Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Sodium Silicate Market Strategic Shifts
Process control systems and formulation science are converging to enable mass-customization of silicate ratios, compressing the traditional trade-off between scale economies and application specificity.
Advanced sensor arrays coupled with machine learning algorithms are digitizing furnace temperature and melt chemistry monitoring in real-time production environments. Cement and adhesive manufacturers with stringent binder consistency requirements adopt these systems fastest. The technology is digitizing quality assurance workflows, reducing batch rejection rates and enabling just-in-time silicate ratio adjustments without line stoppages.
REACH registration requirements and the EU Green Deal chemicals strategy restrict heavy metal impurities while incentivizing lower-carbon production pathways across European supply chains. Downstream detergent and coating formulators reformulate specifications to preempt compliance-driven supply disruptions. Specialty silicate derivatives for electronics applications face the steepest purity escalation, with producers investing in ion-exchange and membrane filtration upgrades.
Specification-driven procurement is consolidating buyer power among multinational detergent and construction chemical formulators. Long-term offtake agreements with volume commitments and technical service provisions displace spot-market purchasing for standard-grade material. This pattern concentrates most visibly in India and Southeast Asia, where capacity expansion outpaces local formulation expertise and buyers demand embedded technical support.
Liquid Sodium Silicate Market Segmentation
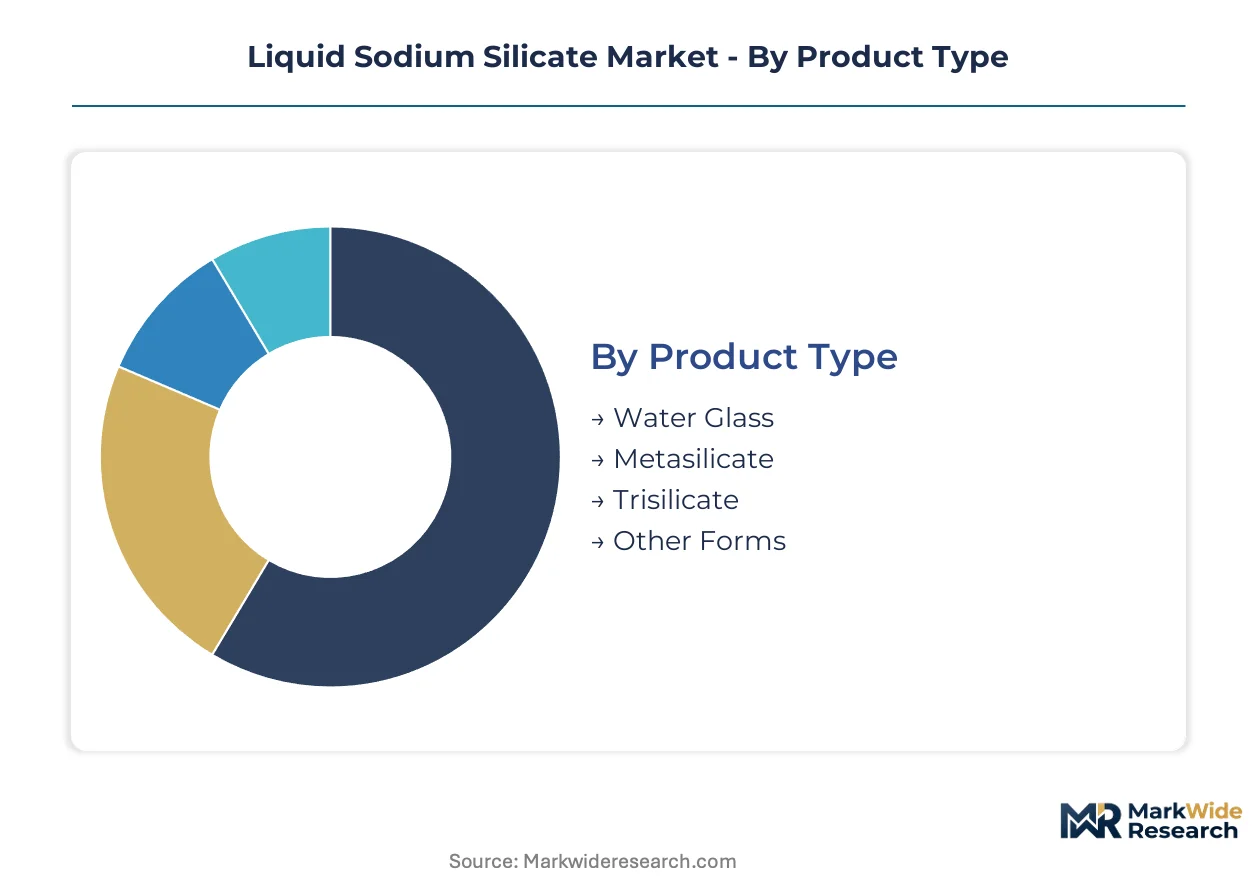
Molar ratio specifications and alkali content differentiate silicate grades across industrial applications. Procurement patterns concentrate around detergent builders and concrete admixtures, with purity thresholds diverging sharply between commodity and specialty end uses.
Product Type:
Mature furnace-process grades dominate volume flows, while emerging hydrothermal synthesis methods reshape premium segment economics.
- Water Glass:Aqueous solutions with SiO₂:Na₂O ratios between 1.6 and 3.75 serve as the foundational binder for detergents and construction admixtures. Detergent manufacturers in India procure standard-grade alkalinity for phosphate-free laundry formulations under BIS certification requirements.
- Metasilicate:Crystalline sodium metasilicate pentahydrate delivers controlled alkalinity and chelation properties for metal cleaning and textile processing. Metal finishing operations in Southeast Asia absorb premium-priced metasilicate grades for precision surface preparation applications.
- Trisilicate:Higher silica-content formulations provide milder alkalinity for sensitive substrate cleaning.
- Other Forms:Specialty derivatives including colloidal silicates and modified ratios address niche electronics and catalyst applications.
Water Glass handles the majority of throughput; Metasilicate is expanding most quickly on share.
Application:
Cost tier differentiation separates commodity builders from performance-critical binders and protective coatings.
- Detergents:Sodium silicate builders replace phosphates in laundry and automatic dishwashing formulations, with EPA effluent guidelines accelerating substitution in United States consumer markets. Formulators balance cost against chelation efficiency and fabric safety profiles.
- Adhesives:Water-based silicate binders displace solvent-borne systems in paper lamination and corrugated board manufacturing. Automotive interior assembly specifications in Germany and Japan specify silicate adhesives for reduced VOC emissions.
- Coatings:Inorganic zinc-rich primers and intumescent fireproofing layers leverage silicate film-forming properties.
- Concrete:Accelerated curing admixtures and waterproofing agents penetrate infrastructure projects across India's cement-intensive construction cycle.
Detergents anchor volume demand; Adhesives are gaining share fastest as water-based mandates proliferate.
End User:
Customer type segmentation reveals divergent specification intensity between project-driven construction and continuous-process manufacturing.
- Construction:Cement admixture procurement concentrates around India's infrastructure investment corridors, with state-level public works departments specifying sodium silicate for tunnel lining and marine concrete durability.
- Automotive:Coating and adhesive specifications from OEM assembly plants in Germany, Japan, and the United States drive demand for low-impurity silicate grades meeting ISO quality benchmarks.
- Paper:Corrugated packaging and recycled fiber de-inking operations consume standard-grade binders.
- Textile:Bleaching auxiliary and dye-fixing applications in Bangladesh and Vietnam absorb metasilicate grades.
Construction handles the majority of throughput; Automotive is climbing the fastest on specification intensity.
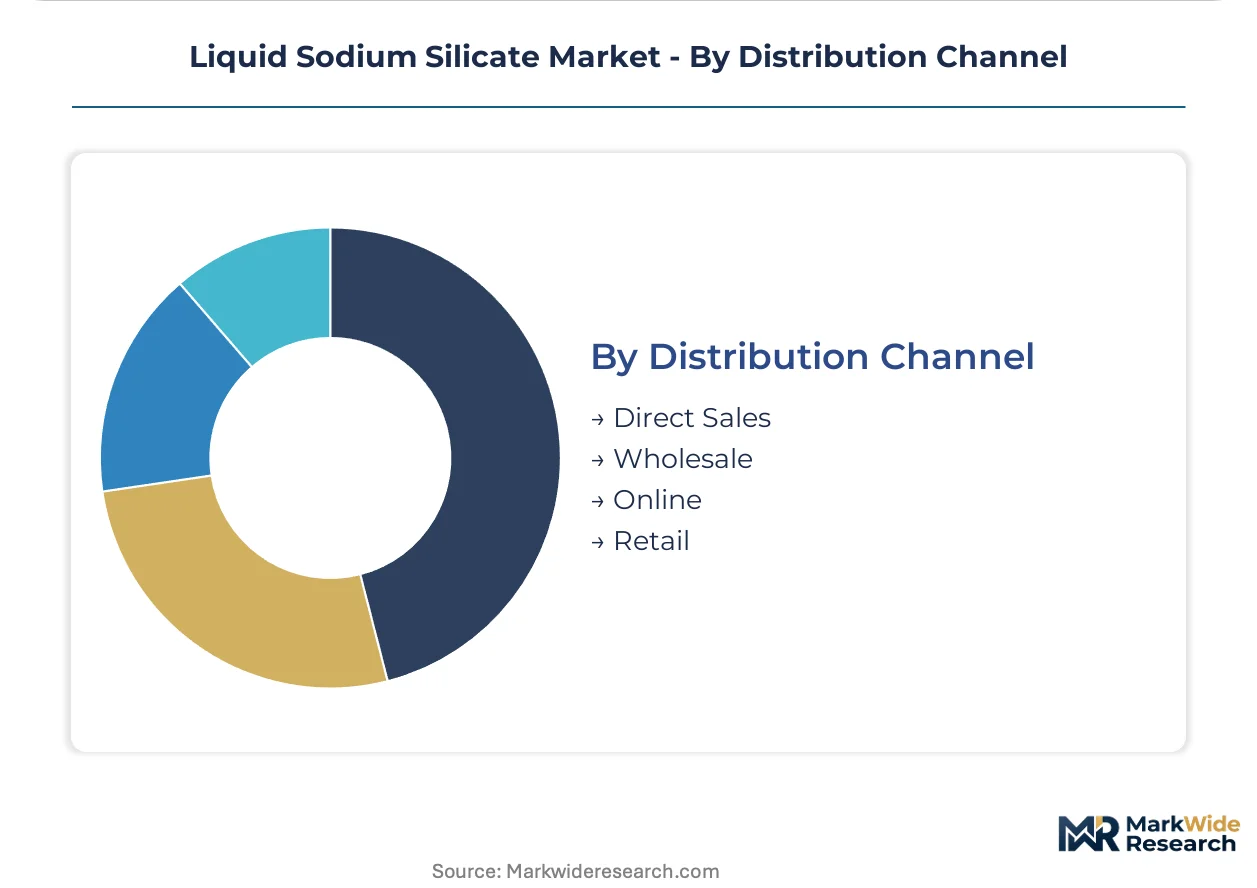
Distribution Channel:
Supply concentration favors direct relationships for bulk industrial offtake, with wholesale intermediaries serving fragmented regional formulators.
- Direct Sales:Long-term offtake agreements with volume commitments and embedded technical service dominate detergent and construction chemical procurement. Multinational formulators in India and Southeast Asia consolidate purchasing power through direct mill relationships.
- Wholesale:Regional distributors stock standard-grade material for mid-scale metal finishing and textile operations lacking storage infrastructure.
- Online:Digital procurement platforms penetrate small-batch specialty grade orders.
- Retail:Packaged consumer and artisan applications represent minimal volume share.
Direct Sales handles the majority of throughput; Online is the fastest mover on channel share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in liquid sodium silicate track regional alkali sourcing economics and downstream formulation demand. Export-oriented capacity clusters near captive soda ash supply, while import dependency concentrates in construction and detergent growth markets.
United States
Detergent manufacturers accelerate phosphate substitution under EPA effluent guidelines. OSHA silica exposure standards enforce plant-level engineering investments across Gulf Coast production facilities. Texas and Louisiana house integrated furnace operations serving domestic detergent and adhesives demand.
Germany
Automotive OEM coating specifications drive low-impurity silicate procurement for water-based primer formulations. REACH registration requirements and EU Green Deal chemicals strategy restrict heavy metal thresholds. The Ruhr industrial corridor concentrates specialty silicate derivatives for metal finishing and electronics applications.
India
Infrastructure investment cycles boost sodium silicate concrete admixture consumption for accelerated curing. BIS certification and PLI scheme incentives reshape import-dependent textile and metal finishing sectors. Gujarat and Maharashtra host capacity expansion serving domestic detergent and construction chemical formulators.
China
Construction sector absorption of waterproofing admixtures sustains volume demand despite industrial restructuring. MEE environmental standards and dual carbon goals pressure high-temperature furnace operators toward energy efficiency retrofits. The Yangtze River Delta concentrates hydrothermal synthesis capacity for lower-carbon production pathways.
Japan
Electronics-grade silicate derivatives face purity escalation for semiconductor packaging substrates. METI industrial standards and JIS certification frameworks govern ultra-low-impurity specifications. The Kansai region around Osaka anchors specialty silicate R&D for display and advanced materials applications.
Liquid Sodium Silicate Market Competitive Environment
On the supply side, the industry is consolidating around integrated alkali producers and specialty chemical diversifiers. Furnace-process operators compete on captive raw material access, while hydrothermal synthesis specialists capture premium positioning through carbon intensity advantages. Three archetypes dominate: integrated soda ash-silicate producers, diversified multinational chemical conglomerates, and regional specialists with downstream formulation partnerships. Capacity relocation toward India and Southeast Asia accelerates, alongside ion-exchange filtration upgrades for electronics-grade purity tiers.
Among the integrated producers, PQ Corporation exemplifies captive alkali supply chain structures. Evonik Industries AG and BASF SE occupy positions within diversified chemical portfolios, anchoring specialty and commodity tier exposure respectively. These three entities represent the span from upstream integration to downstream formulation reach, illustrating how margin sustainability depends on raw material control and application-specific technical service depth.
| Leading Market Players |
|---|
| PQ Corporation |
| Evonik Industries AG |
| BASF SE |
| Solvay S.A. |
| Occidental Petroleum Corporation |
| Nippon Chemical Industrial Co., Ltd. |
| Tokuyama Corporation |
| W. R. Grace & Co. |
| Oriental Silicas Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive soda ash production in the United States and synthetic ash capacity in China concentrate upstream margin control with integrated furnace operators, leaving non-integrated hydrothermal synthesis specialists exposed to alkali price volatility. This structural asymmetry positions downstream detergent and construction formulators as price-takers in contract negotiations, while electronics-grade purity tiers command premium positioning through ion-exchange filtration investments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with three-tier pricing structure across premium, standard, and economy levels driven by certification grade and volume scale. Price differentiation separates metasilicate grades for metal cleaning from water glass formulations for detergent builders, with the latter absorbing the most intense cost compression due to zeolite substitution threats. Pricing pressure stems from energy cost pass-through clauses in furnace-process supply agreements.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for hydrothermal synthesis equipment imports. Geographic supply concentrates in the United States, China, and Germany, with raw material dependencies on high-purity silica sand deposits, synthetic and natural soda ash, and caustic soda alkali sources. Distribution runs through direct mill relationships for bulk detergent and construction chemical procurement, supplemented by wholesale intermediaries for fragmented metal finishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where regulatory entrenchment through REACH registration timelines and BIS certification requirements creates substantial switching costs for downstream formulators. Incumbents benefit from embedded technical service relationships that resist price-only competition.
For Market Incumbents: Pre-empt zeolite substitution threats in detergent applications by accelerating hydrothermal synthesis capacity additions in Gujarat and Maharashtra to capture India's PLI scheme incentives. Deepen captive alkali supply control through backward integration into synthetic soda ash production, insulating margin structures from energy market volatility that strains non-integrated competitors.
For New Entrants and Emerging Players: Build out electronics-grade silicate derivative capacity targeting semiconductor packaging substrates in Japan's Kansai region, where METI industrial standards and JIS certification frameworks create barrier-protected premium tiers. Enter through technical partnership structures with display substrate manufacturers seeking ultra-low-impurity formulations, bypassing capital-intensive furnace infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional specialists holding downstream formulation partnerships in India's textile and metal finishing corridors. Five-to-ten year viability hinges on carbon intensity differentiation as EU Green Deal chemicals strategy incentives reshape European procurement patterns. Monitor hydrothermal synthesis patent filings as inflection signal for production technology substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash | PQ Corporation's captive alkali supply chains demonstrate margin protection against energy-driven input volatility. |
| Hydrothermal Synthesis Capacity Expansion | Lower-carbon production pathways align with EU Green Deal incentives and compress furnace-process competitiveness. |
| Electronics-Grade Purity Upgrades | Ion-exchange and membrane filtration investments unlock semiconductor packaging substrate premiums in Japan. |
| Long-term Supply Agreement | Direct mill relationships with embedded technical service consolidate multinational formulator purchasing power in India. |
| Joint Venture with Downstream Formulator | Construction chemical partnerships in India's infrastructure corridors secure volume commitments for concrete admixture grades. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across detergent formulation laboratories, construction chemical procurement desks, and metal finishing operations. Primary interviews with plant managers at furnace-process facilities, technical R&D directors developing hydrothermal synthesis methods, and procurement leads at downstream OEMs were triangulated against secondary sources including customs and trade data, American Chemistry Council and Cefic industry reports, and SEC 10-K filings from integrated chemical conglomerates. Bottom-up volume modeling and top-down value reconciliation anchored segmentation outputs.
Calibration against historical capacity utilization rates and regional alkali price indices refined projection outputs across the analysis window. Segmentation dimensions modeled include molar ratio grade tier, end-use application intensity, and regional production hub configuration. CAGRs were derived from slope-log analysis of normalized demand curves, with forecast inputs incorporating EPA effluent guideline implementation timelines and India's infrastructure investment cycle phasing.
Stress conditions across soda ash price volatility bands, REACH registration timeline extensions, and hydrothermal synthesis technology diffusion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and energy cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Barium Carbonate Market
Ceramics
Mullite Market
Ceramics
Calcium Oxide Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Ceramic Proppant Market
Ceramics
Ceramic Frit Market
Ceramics
Ceramic Ware Market
Ceramics
Colloidal Alumina Market
Ceramics
Ceramic Additives Market
Ceramics
Global Alumina Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Pottery Ceramics Market
Ceramics
Calcium Silicate Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Ceramic and Natural Stone Tiles Market