
 Wollastonite Market | 2026-2036
Wollastonite Market Size, Share, and Industry Trends Forecast 2026-2036
Wollastonite Market Analysis
China's Jiangxi and Liaoning provinces is tilting the global supply balance through expanded beneficiation capacity and downstream grinding investments. Imerys leverages its integrated mining-to-distribution network across multiple continents to sustain long-term offtake agreements with ceramics producers. Xinyu South Wollastonite Co., Ltd. anchors the domestic Chinese market with captive reserves and rail-linked processing infrastructure. NYCO Minerals Inc. competes through specialized high-purity grades tailored to polymer reinforcement specifications in North American manufacturing.
Wollastonite is a calcium metasilicate mineral (CaSiO₃) formed by contact metamorphism of impure limestone, characterized by high aspect ratio acicular crystals, a Mohs hardness of 4.5, and thermal stability exceeding 1,100°C that suits it for ceramic fluxing and polymer reinforcement. Natural wollastonite dominates volume flows due to lower energy intensity versus synthetic alternatives, though calcined variants command premium positioning in high-temperature refractory applications. The plastics application segment leads value generation as automotive lightweighting drives acicular-grade demand for nylon and polypropylene composites, while coatings consumption concentrates among architectural paint formulators seeking functional fillers with low oil absorption and pH buffering capacity.
China's SAMR enforces GB standards on industrial mineral purity and labeling that constrain export-grade production parameters, while the EU REACH framework mandates registration and hazard communication for wollastonite fillers used in consumer-facing coatings and construction materials. The US OSHA permissible exposure limits for respirable silica intersect with wollastonite processing, shaping dust control investments and workplace monitoring protocols at milling facilities. Stakeholders must track evolving regulatory thresholds for crystalline silica content and end-of-life recyclability mandates across their priority sales corridors.
Market Dynamics
Construction-grade wollastonite demand accelerates as builders across multiple continents substitute it for banned short-fiber asbestos in cement boards, tightening supply chains around high-aspect-ratio beneficiation capacity.
Growth Catalysts
- EU REACH framework:Hazard communication mandates for filler safety in consumer-facing coatings drive formulators toward certified wollastonite grades with documented crystalline silica thresholds.
- Automotive lightweighting:Acicular wollastonite reinforcement in nylon and polypropylene composites displaces heavier mineral fillers in under-hood and structural components.
- Morbi ceramic cluster:India's western tile belt sources high-aspect-ratio grades for glaze reinforcement, creating dedicated offtake corridors from Chinese and domestic suppliers.
Market Restraints
- Energy cost volatility:Calcined wollastonite production for refractory applications faces margin compression from natural gas price swings at rotary kiln operations.
- Jiangxi-Liaoning supply concentration:China's dual-province dominance in beneficiation and grinding infrastructure creates single-geography vulnerability for export-dependent buyers.
- Competing mineral fibers:Milled glass fiber and wollastonite-lookalike silicates capture specification share in lower-temperature polymer applications.
Strategic Opportunities
- US OSHA silica alignment:Dust control investments at North American milling facilities open premium positioning for compliant grades in workplace-safety-sensitive coatings markets.
- Bio-based polymer convergence:Wollastonite reinforcement of polylactic acid and other compostable matrices addresses end-of-life recyclability mandates in EU packaging directives.
- Rail-linked processing nodes:Captive logistics infrastructure in China's interior provinces enables cost-competitive export-grade production for Southeast Asian ceramics manufacturers.
Industry Challenges
- Aspect ratio certification bottlenecks:Standardized measurement protocols for acicularity remain fragmented across Chinese GB, ASTM, and JIS methodologies, delaying customer qualification timelines.
- Legacy grinding asset retrofit:Ball mill and roller mill installations require dust collection upgrades to meet respirable silica exposure limits without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wollastonite Market |
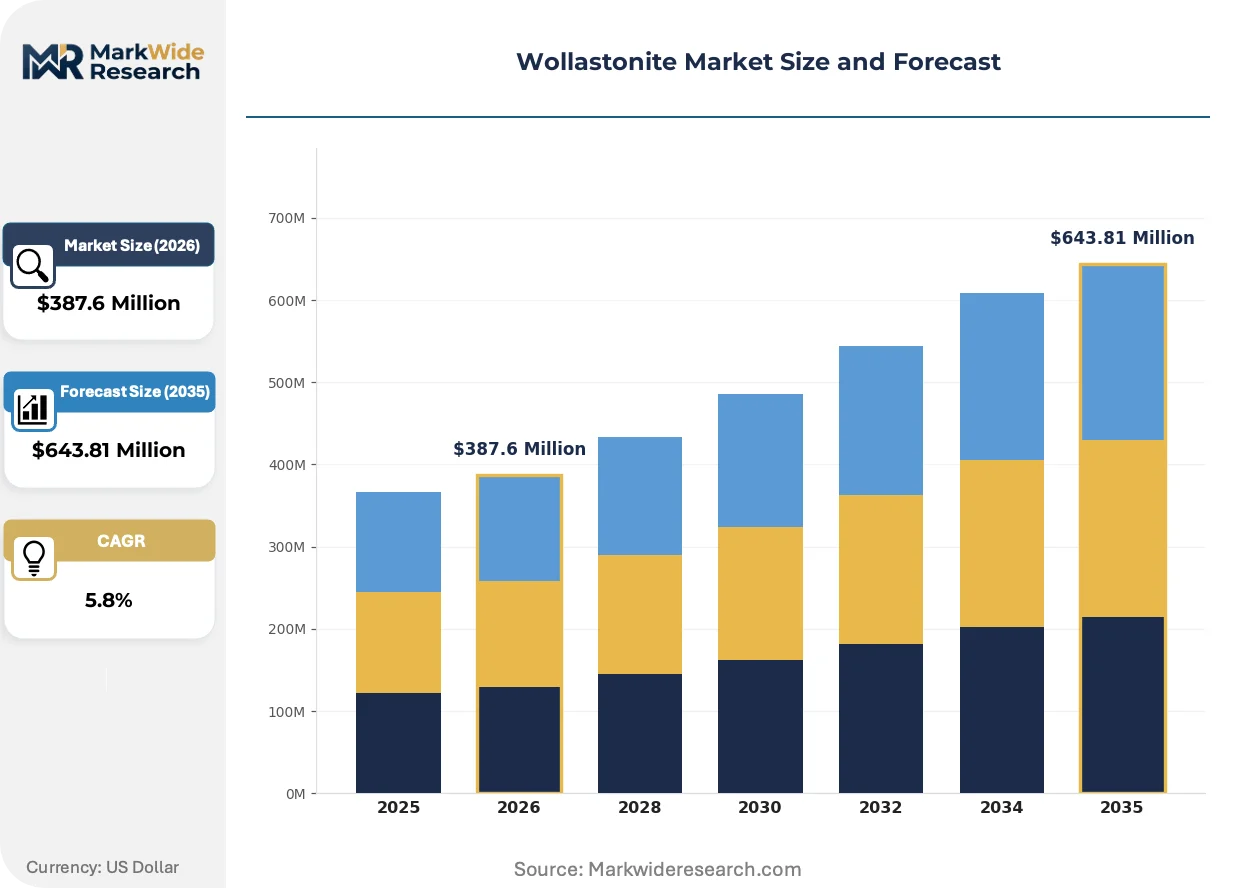
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wollastonite, Synthetic Wollastonite, Calcined Wollastonite, Functional Wollastonite Application: Plastics, Ceramics, Coatings, Construction End User: Building Materials, Automotive, Electronics, Paints Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Nordkalk Corporation, ACBM JSC, Imerys, Canadian Wollastonite, Xinyu South Wollastonite Co., Ltd., R.T. Vanderbilt Holding Company, NYCO Minerals Inc., Jilin Shanwei Wollastonite Mining Co., Ltd., Wolkem India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wollastonite Market Emerging Trajectories
Beneficiation technology and regulatory chemistry specifications are compressing the competitive set around producers capable of delivering certified low-silica, high-aspect-ratio grades at industrial scale.
Surface-modified wollastonite with silane coupling agents improves dispersion in hydrophobic polymer matrices. Automotive compounders in Germany and the US Midwest specify these treated grades for glass-filled nylon hybrid systems. The technology is migrating from specialty automotive applications toward commodity polypropylene in appliance housings.
China's SAMR enforcement of GB standards on industrial mineral purity and labeling constrains export-grade production parameters. Milling facilities must document crystalline silica content below threshold levels for coatings and construction materials bound for EU and North American markets. Ceramic tile manufacturers in Italy and Spain now require third-party certification of acicularity metrics.
Specification-driven procurement concentrates buying power among large ceramics and polymer compounders with dedicated technical qualification teams. Smaller paint formulators and regional tile producers lose direct mill access, sourcing instead through distributor consignment programs. This pattern is most visible in India's Morbi belt, where volume aggregators now intermediate between Chinese exporters and mid-size kiln operators.
Wollastonite Market Segmentation
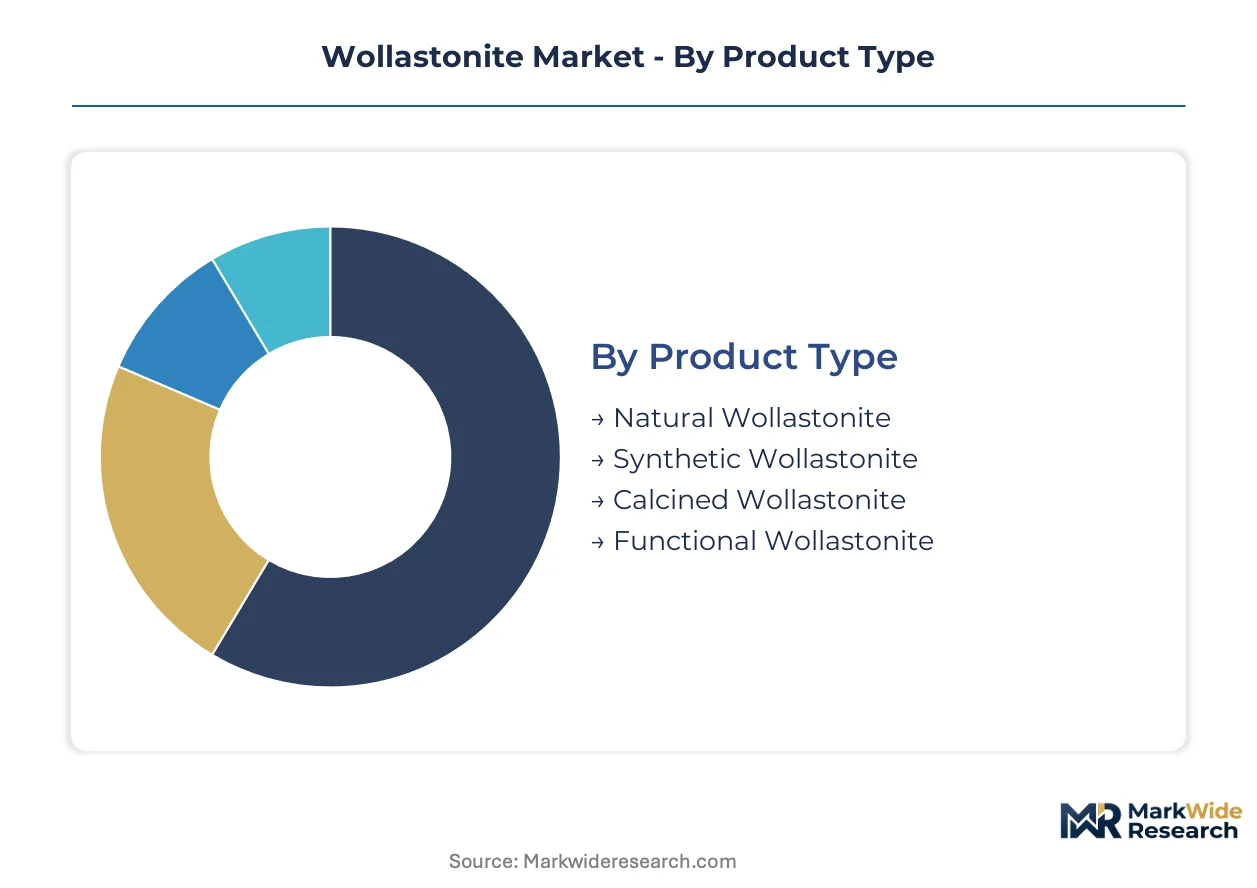
Wollastonite specifications diverge sharply across end-use contexts, from bulk construction fillers to precision polymer reinforcement. Each segment demands distinct beneficiation intensity, aspect ratio certification, and regulatory compliance documentation.
Product Type:
Calcium metasilicate grades span a cost-performance spectrum from raw ore to surface-engineered functional variants.
- Natural Wollastonite:Acicular crystals formed by contact metamorphism of impure limestone deliver Mohs 4.5 hardness and thermal stability exceeding 1,100°C. India's Morbi ceramic cluster sources high-aspect-ratio natural grades for glaze reinforcement, constrained by GB standards documentation requirements for crystalline silica content.
- Calcined Wollastonite:Rotary kiln processing at 1,000-1,200°C drives off chemically bound water and carbonates, producing dense alpha-phase material for refractory linings and high-temperature insulation. EU REACH registration mandates hazard communication for these thermally activated variants used in consumer-facing applications.
- Synthetic Wollastonite:Slag-based or chemical precipitation routes yield controlled purity for specialized electronics and medical ceramic applications.
- Functional Wollastonite:Silane-treated surfaces improve dispersion in hydrophobic polymer matrices for automotive nylon composites.
Established volume favors natural wollastonite; emerging adoption favors functional wollastonite.
Application:
Beneficiation intensity and aspect ratio certification requirements segment the market by technical threshold.
- Plastics:Acicular grades reinforce nylon and polypropylene composites in under-hood automotive components, displacing heavier mineral fillers. German compounders specify silane-coupled variants for glass-filled nylon hybrid systems now migrating toward commodity appliance housings.
- Ceramics:High-aspect-ratio natural wollastonite fluxes ceramic tile glazes at lower firing temperatures than traditional feldspar. Spain's tile manufacturers require third-party acicularity certification under tightening EU product safety frameworks.
- Coatings:Low oil absorption and pH buffering capacity suit architectural paint formulators seeking functional filler performance.
- Construction:Cement board manufacturers substitute wollastonite for banned short-fiber asbestos, tightening supply chains around construction-grade beneficiation capacity.
Plastics commands premium pricing; construction drives absolute tonnage.
End User:
Procurement sophistication varies from specification-driven automotive compounders to price-sensitive regional builders.
- Automotive:Tier-1 suppliers mandate lot-level aspect ratio documentation and respirable silica testing for under-hood composite components.
- Building Materials:Cement board and calcium silicate insulation manufacturers prioritize volume scale over grade precision.
- Electronics:Synthetic wollastonite serves high-frequency substrate and ceramic packaging applications requiring low dielectric loss.
- Paints:Architectural formulators source functional fillers through distributor consignment programs, losing direct mill access as buying power concentrates.
Automotive demands the most stringent certification; building materials absorb the highest volume.
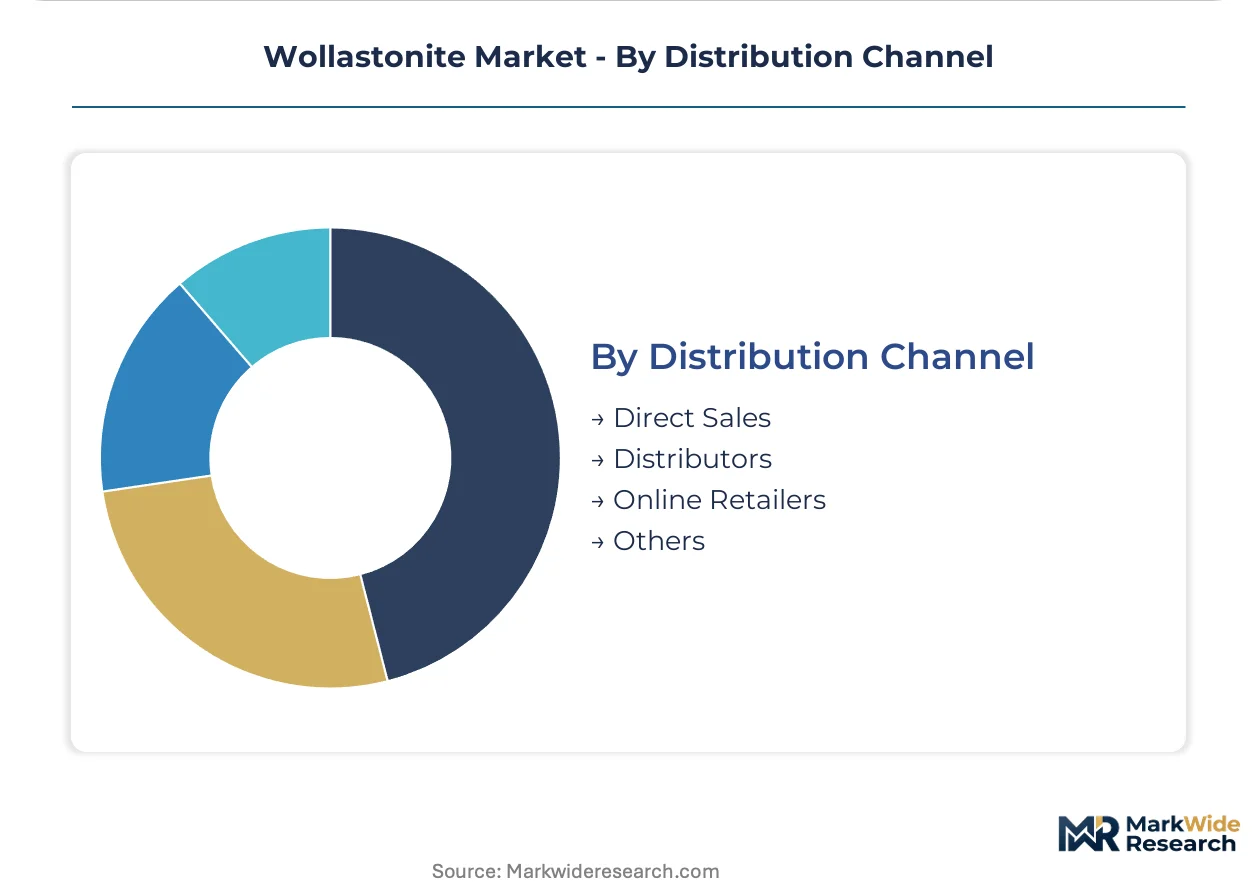
Distribution Channel:
Channel selection tracks customer scale and technical qualification capabilities.
- Direct Sales:Large ceramics and polymer compounders with dedicated technical teams negotiate long-term offtake agreements. Imerys and NYCO Minerals maintain direct relationships with North American automotive compounders and Italian tile manufacturers.
- Distributors:Volume aggregators intermediate between Chinese exporters and mid-size kiln operators in India's western ceramic belt, consolidating fragmented regional demand.
- Online Retailers:Specialty grades for research laboratories and small-batch polymer formulators.
- Others:Agent-based procurement for emerging market construction projects.
Direct sales capture specification premiums; distributors expand geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards on industrial mineral purity that constrain export-grade production parameters, while the EU REACH framework mandates hazard communication for fillers used in consumer-facing applications across multiple corridors.
China
Jiangxi and Liaoning provinces anchor beneficiation and grinding infrastructure for high-aspect-ratio grades bound for ceramics and polymer reinforcement. MEE oversight of crystalline silica emissions shapes dust control investments at milling facilities. Rail-linked processing nodes in interior provinces enable cost-competitive export-grade production for Southeast Asian ceramics manufacturers.
United States
OSHA permissible exposure limits for respirable silica intersect with wollastonite processing, driving workplace monitoring protocols at milling facilities. NYCO Minerals competes through specialized high-purity grades tailored to polymer reinforcement specifications in North American manufacturing. Automotive compounders in the Midwest specify silane-coupled variants for under-hood composite components.
India
The western ceramic belt around Morbi, Gujarat sources high-aspect-ratio grades for glaze reinforcement, creating dedicated offtake corridors from Chinese and domestic suppliers. BIS standards on industrial mineral labeling constrain import specifications for construction-grade material. Volume aggregators now intermediate between Chinese exporters and mid-size kiln operators across the cluster.
Germany
Automotive compounders specify acicular wollastonite reinforcement for nylon and polypropylene composites in under-hood and structural components. ECHA REACH registration mandates hazard communication for thermally activated variants used in consumer-facing applications. Technical qualification teams at tier-1 suppliers mandate lot-level aspect ratio documentation and respirable silica testing.
Italy
Ceramic tile manufacturers require third-party certification of acicularity metrics under tightening EU product safety frameworks. Imerys leverages integrated mining-to-distribution networks to sustain long-term offtake agreements with producers across the ceramics corridor. Spanish tile manufacturers mirror these certification requirements, compressing supplier qualification timelines.
Wollastonite Market Vendor Landscape
Integrated multinationals and regional specialists split the market along certification capability and geographic proximity to demand clusters. The vendor base concentrates around players capable of delivering documented low-silica, high-aspect-ratio grades at industrial scale. Two archetypes dominate: diversified industrial mineral houses with captive reserves and grinding assets, and focused wollastonite purists with specialized beneficiation technology. Competitive moves center on M&A for reserve access and strategic partnerships for rail-linked distribution nodes.
Within the integrated industrial mineral tier, Imerys exemplifies the diversified archetype through multi-continent mining-to-distribution networks. NYCO Minerals Inc. and Xinyu South Wollastonite Co., Ltd. occupy positions as regional anchors—NYCO representing North American specialization in high-purity grades, Xinyu South representing Chinese domestic market integration through captive reserves and processing infrastructure. These three entities represent the competitive spectrum from global diversification to regional vertical control.
| Leading Market Players |
|---|
| Nordkalk Corporation |
| ACBM JSC |
| Imerys |
| Canadian Wollastonite |
| Xinyu South Wollastonite Co., Ltd. |
| R.T. Vanderbilt Holding Company |
| NYCO Minerals Inc. |
| Jilin Shanwei Wollastonite Mining Co., Ltd. |
| Wolkem India Ltd. |
| Others |
Supply Flow & Price Mechanics
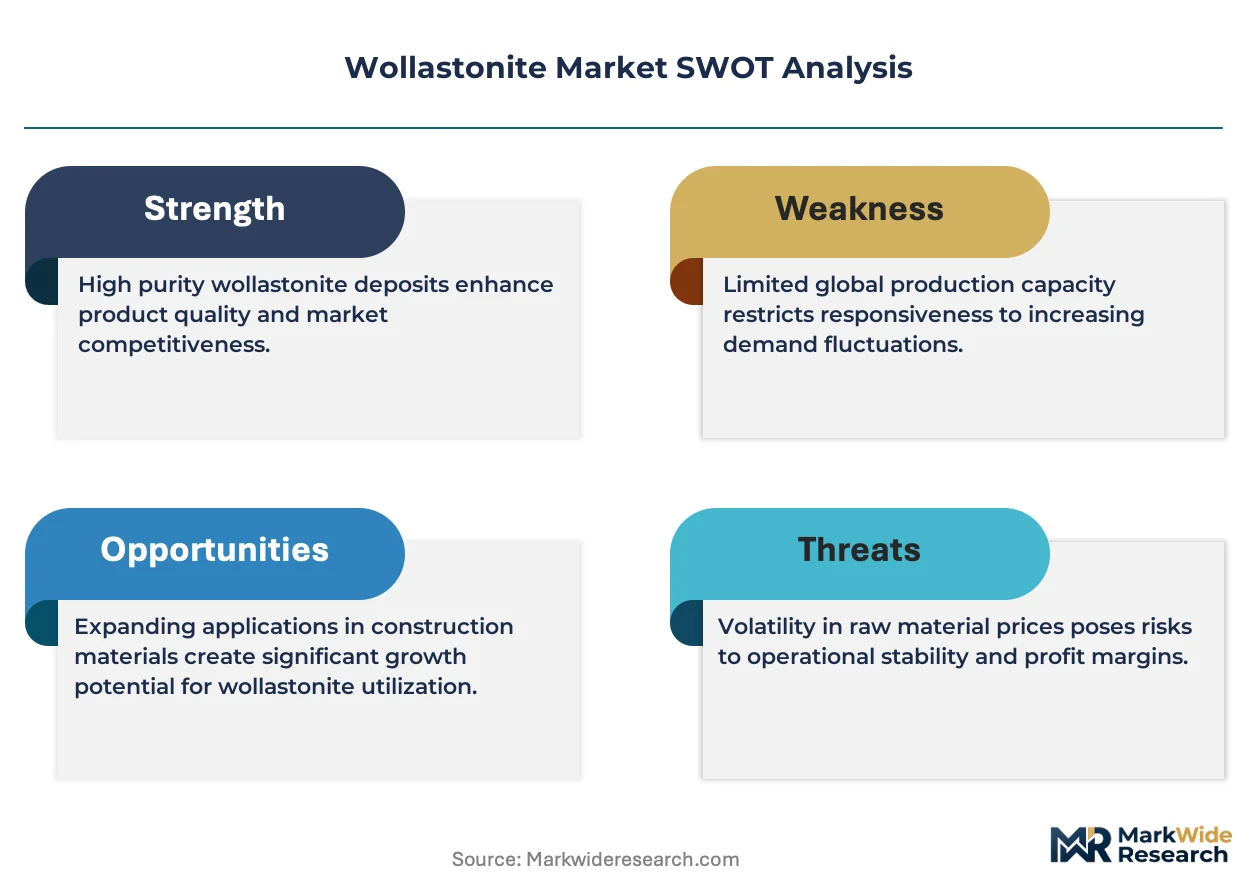
Jiangxi and Liaoning provinces concentrate beneficiation capacity for high-aspect-ratio grades, anchoring margin pools downstream with automotive compounders and ceramic tile manufacturers who pay premiums for certified low-silica documentation.
Pricing Analysis
Chinese export-grade wollastonite trades at a 15-25% discount to North American milled product, reflecting rail-linked logistics advantages against US OSHA-compliant dust control investments. Three-tier pricing structure across silane-coupled functional grades, standard acicular material, and raw ore concentrates separates specification premiums from commodity bulk. Cost compression in calcined variants is intensifying because natural gas price volatility at rotary kiln operations erodes refractory-grade margins. Building materials manufacturers exhibit highest price sensitivity, while automotive tier-1 suppliers absorb premiums for lot-level aspect ratio certification.
Supply Chain Analysis
Contact metamorphism deposits in China's Jiangxi-Liaoning corridor, US Adirondack region, and Finland's Lappeenranta formation anchor upstream feedstock availability. Beneficiation draws from limestone parent rock, acicular crystal sorting infrastructure, and silane surface treatment chemicals. Single-geography vulnerability concentrates in Chinese dual-province dominance, exposing export-dependent buyers to MEE emissions enforcement disruptions. Distribution runs through direct mill relationships with large compounders, volume aggregators serving India's Morbi ceramic belt, and distributor consignment programs for fragmented paint formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wollastonite market sits at a platform-economics inflection where REACH-registered grade interoperability determines supplier stickiness across EU automotive and ceramics procurement systems.
For Market Incumbents: Harden certification moats by investing in third-party acicularity measurement protocols that accelerate customer qualification timelines against ASTM-JIS methodology fragmentation. Secure backward integration into rail-linked processing nodes in China's interior provinces to defend margin position against emerging Southeast Asian ceramics demand. Prioritize silane-coupling R&D for bio-based polymer matrices as EU packaging recyclability mandates reshape specification requirements. For New Entrants and Emerging Players: Mid-tier cement board manufacturers in Southeast Asia represent the most penetrable entry point, as construction-grade substitution for banned asbestos tightens supply chains around regional beneficiation capacity. Functional wollastonite for polylactic acid reinforcement in EU compostable packaging offers specification-driven margin capture with lower incumbent lock-in. Pursue toll-milling partnerships with established Chinese processors to bypass captive reserve requirements while building brand recognition. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated regional specialists with documented GB-REACH dual certification and captive logistics infrastructure spanning mine-to-port corridors. Long-term viability hinges on positioning for automotive lightweighting acceleration and ceramic glaze flux substitution trends. Monitor ECHA crystalline silica threshold revisions as the inflection signal for compliance-cost restructuring across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Secures ore supply for Imerys and NYCO Minerals against Chinese export quota volatility. |
| Silane Surface Treatment Scale-Up | Enables German automotive compounders to specify dispersion-optimized grades for glass-filled nylon hybrids. |
| REACH Registration Completion | Mandates hazard communication documentation for EU coatings and construction material formulators. |
| Rail-Linked Processing Node Development | Positions Xinyu South Wollastonite for cost-competitive Southeast Asian ceramics exports. |
| Third-Party Acicularity Certification | Accelerates Italian and Spanish tile manufacturer qualification timelines under tightening EU safety frameworks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with ceramic tile technical directors, automotive polymer compounders, cement board procurement managers, and wollastonite milling facility engineers. Secondary validation drew from SAMR GB standards documentation, ECHA REACH registration filings, USGS mineral commodity summaries, and India BIS industrial mineral labeling requirements. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across Jiangxi, Liaoning, and North American mining jurisdictions.
Calibration against historical price spreads between Chinese export-grade and North American milled product informed elasticity assumptions across the projection horizon. Segmentation modeling spanned product type tiers, application intensity levels, end-user procurement sophistication, and distribution channel structures. CAGRs were derived from regression analysis of construction-grade substitution rates, automotive lightweighting penetration curves, and ceramic glaze formulation shifts. Industry-specific inputs included rotary kiln natural gas cost pass-through coefficients and respirable silica compliance investment cycles.
Macroeconomic conditions sit as an overlay; deviation in Chinese industrial electricity pricing, EU carbon border adjustment implementation, or US infrastructure spending levels would shift the trajectory. Forecasts reflect documented assumptions regarding beneficiation technology diffusion and regulatory threshold evolution. Cross-checking against USGS Mineral Commodity Summaries and trade flow data from Chinese customs authorities is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Kaolin Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Glazed Bricks Market
Ceramics
Potassium Feldspar Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Ceramic Additives Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Alumina Slurry Market
Ceramics
Quartz Powder Market
Ceramics
Vaterite Market
Ceramics
Pottery Ceramics Market
Ceramics
China Ceramic Market
Ceramics
Ceramic Frit Market
Ceramics
Advanced Structural Ceramics Market