
 High Purity Mullite Powder Market | 2026-2036
High Purity Mullite Powder Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Mullite Powder Market Insights
The divergence between premium and commodity tiers is repositioning competitive dynamics in high purity mullite powder. Imerys leverages its fused mineral expertise to command premium positioning in optical-grade formulations. Washington Mills anchors North American supply through dense refractory-grade output. Denka Company differentiates via nanopowder specialization for electronics substrates.
High purity mullite powder is a synthetic aluminum silicate ceramic material typically exceeding 99% purity with controlled alumina-to-silica ratios near 3:2, produced through sintering or fusion processes for thermal stability above 1800°C. Its primary purpose centers on insulating layers, kiln furniture, and precision ceramic components where thermal shock resistance and low creep deformation prove critical. Micropowder grades dominate current volume flows across refractory coatings, while nanopowder commands expanding share in ceramic substrates for semiconductor packaging. Granular formats sustain mature demand in insulating materials for power generation infrastructure.
EPA oversight of particulate emissions and OSHA workplace exposure limits shape domestic manufacturing compliance costs for U.S. producers. REACH registration requirements and RoHS substance restrictions in Europe filter market access for non-compliant suppliers. Stakeholders must monitor evolving purity certifications from ISO standards bodies and regional environmental agencies as end-user specifications tighten across aerospace and electronics applications.
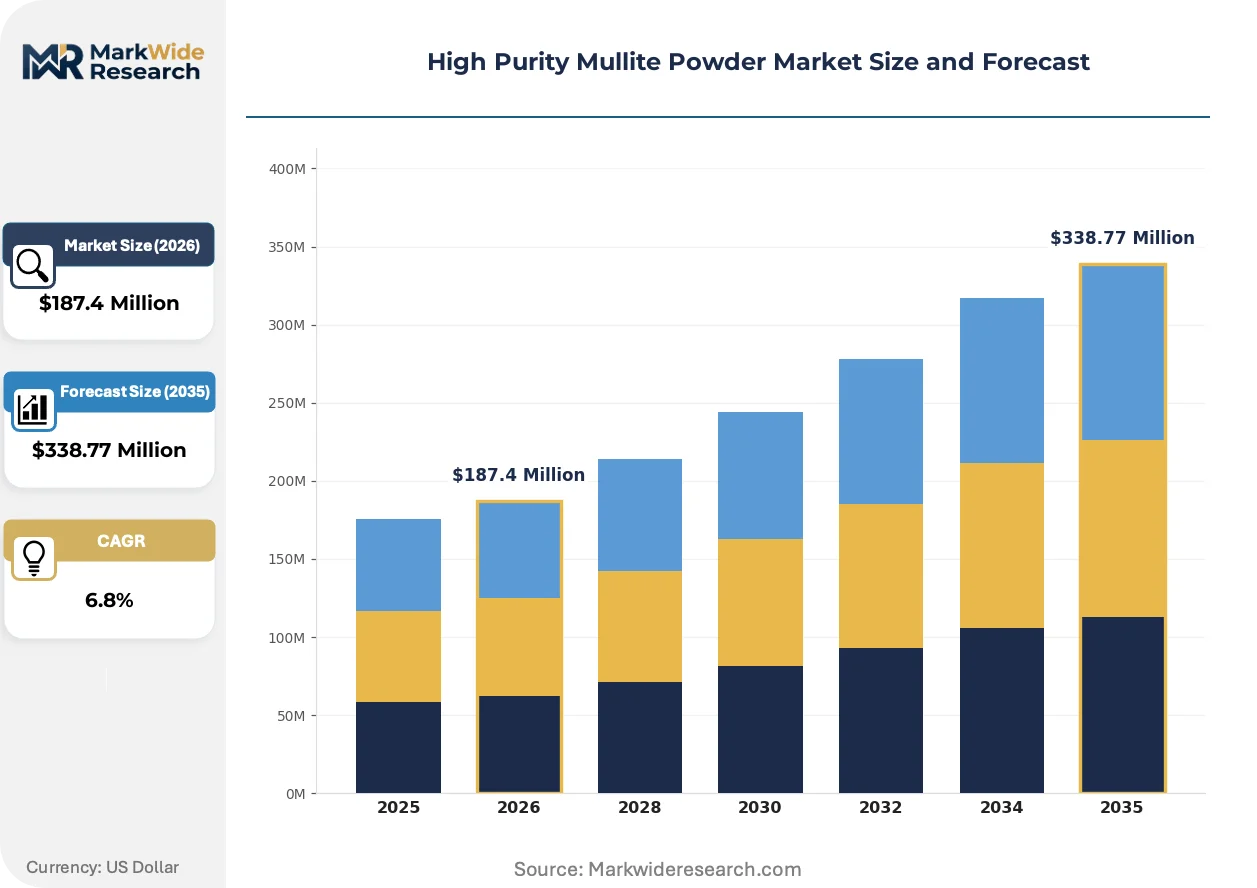
Market Dynamics
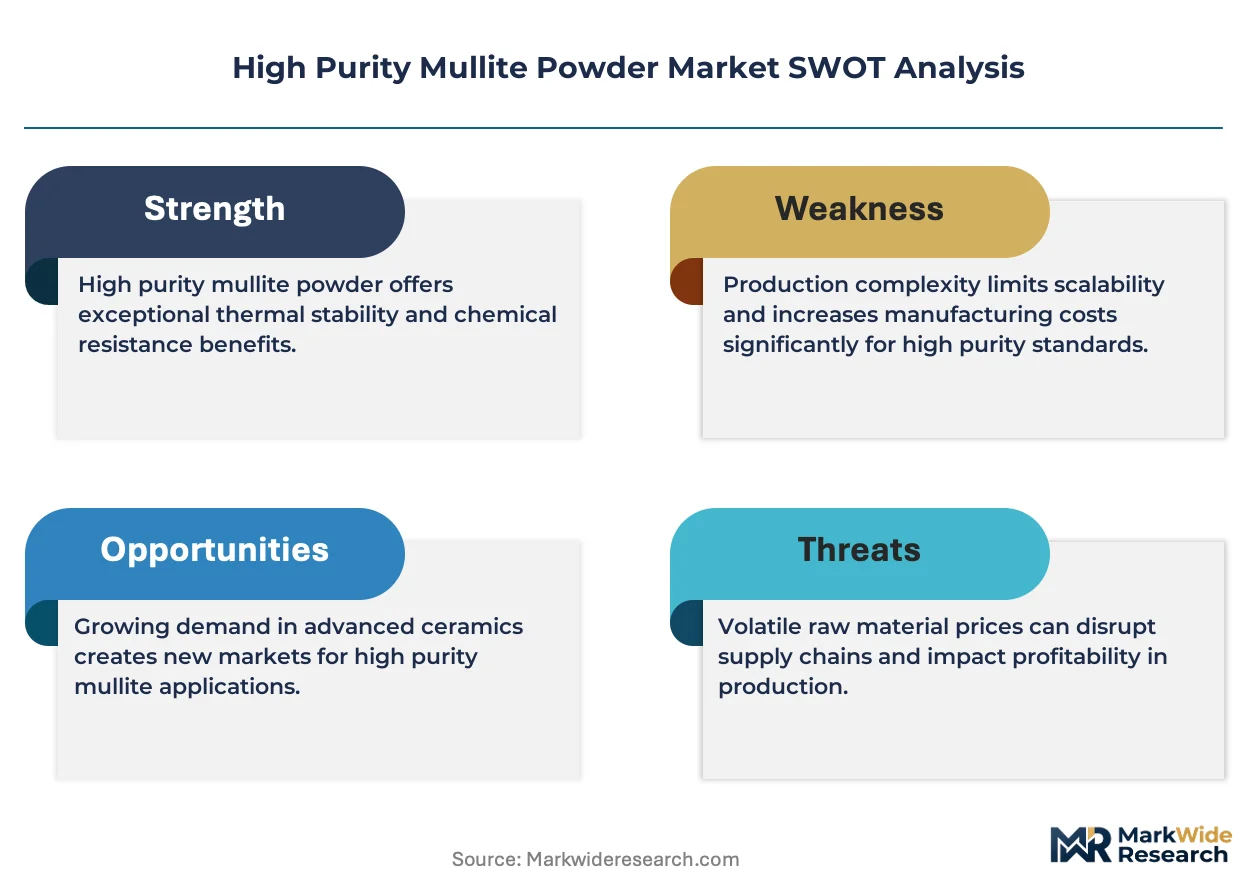
Substrate miniaturization in semiconductor packaging is compressing tolerances for thermal expansion coefficients, forcing powder suppliers to recalibrate fusion parameters and purity thresholds beyond legacy refractory specifications.
Growth Catalysts
- EPA particulate emission standards:Tightening OSHA workplace exposure limits in the United States are accelerating plant upgrades toward closed-loop synthesis systems that yield higher-purity output as a byproduct of compliance.
- Electronics substrate demand:Advanced packaging for heterogeneous integration in semiconductor foundries is pulling nanopowder grades into volume production for thermal interface layers.
- China domestic ceramics expansion:Concentrated investment in kiln furniture and precision ceramic components is absorbing granular and micropowder grades at scale.
Market Restraints
- Fused alumina price volatility:Energy-intensive fusion processes expose producers to natural gas and electricity cost swings that compress margin buffers on fixed-price contracts.
- Supply concentration in East Asian fusion capacity:A limited number of operational electric arc furnaces with 99%+ purity capability creates single-source vulnerability for optical-grade formulations.
- Technical limitation in sub-100nm agglomeration control:Nanopowder batch consistency remains below semiconductor packaging yield requirements, constraining qualified supplier pools.
Strategic Opportunities
- India refractory market penetration:Underdeveloped domestic high-purity synthesis capacity creates import substitution openings for compliant exporters as steel and cement capacity expands.
- EU Green Deal carbon border adjustments:Emerging compliance frameworks will favor low-carbon fusion routes, rewarding early adopters of renewable-powered production.
- Additive manufacturing convergence:Binder jet and selective laser sintering of technical ceramics is expanding addressable demand beyond traditional pressing and casting applications.
Industry Challenges
- ISO 9001 and IATF 16949 certification timelines:Automotive and aerospace qualification protocols demand 18-24 month validation cycles that delay revenue recognition for new entrants.
- Legacy refractory customer integration:Established kiln furniture specifications lock in alumina-silica ratios that conflict with next-generation electronics substrate requirements, forcing dual-product-line complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Mullite Powder Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Micropowder, Nanopowder, Flake, Others Application: Refractory Coatings, Insulating Materials, Ceramic Substrates, Catalyst Supports, Optical Devices End User Industry: Ceramics Manufacturing, Electronics Assembly, Chemical Processing, Aerospace Engineering, Power Generation Packaging Type: Bulk Bags, Plastic Drums, Fiber Drums, Valve Bags, Cardboard Boxes |
| Companies Covered | Imerys, Washington Mills, Denka Company, Sibelco, Almatis, CoorsTek, AGC Ceramics, Minerals Technologies, RHI Magnesita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Mullite Powder Market Trends and Innovations
Process intensification and regulatory calibration are simultaneously reshaping how purity grades are certified, produced, and procured across diverging end-use specifications.
Sol-gel synthesis routes for nanopowder production are expanding into semiconductor substrate applications where thermal conductivity and dielectric stability must coexist. Foundry packaging engineers are specifying these grades for 2.5D and 3D integration schemes at accelerating qualification pace. The technology is expanding into territory previously reserved for fused silica and aluminum nitride, compressing the viable performance gap between ceramic families.
REACH registration requirements for aluminum silicate substances are elevating documentation burdens for non-European suppliers seeking European electronics market access. ECHA substance evaluation protocols now demand comprehensive toxicological dossiers that smaller fusion operators cannot assemble without consortium participation. German and French ceramic substrate manufacturers are responding by tightening supplier qualification to pre-registered sources, effectively filtering the vendor base before product testing begins.
Direct procurement from synthesis plants is displacing distributor intermediation for volume refractory consumers seeking lot-to-lot consistency guarantees. Large steel and cement groups are establishing technical audit programs that bypass traditional merchant channels. This pattern is most visible in China, where state-owned materials conglomerates are consolidating supplier relationships through equity-linked offtake arrangements rather than spot market transactions.
High Purity Mullite Powder Market Segmentation
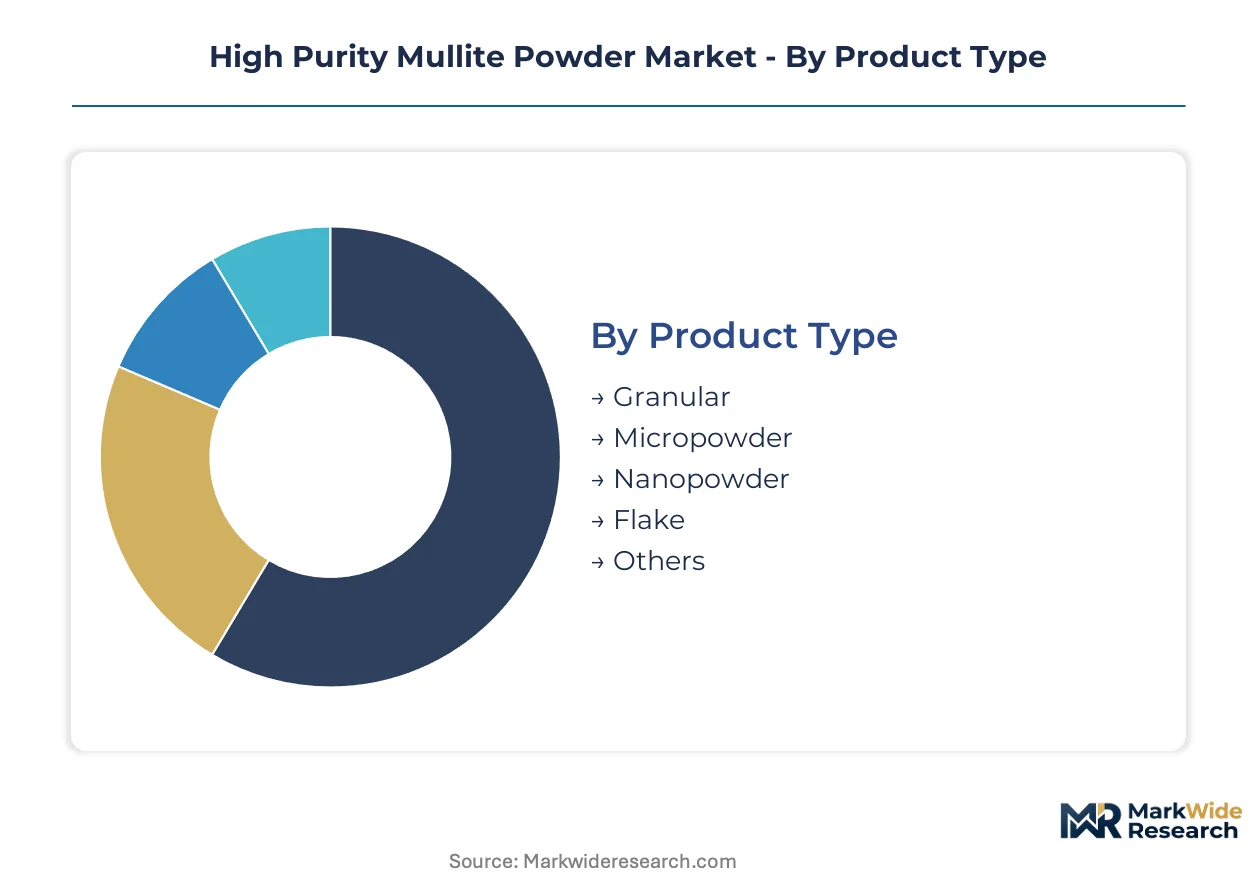
High purity mullite powder serves divergent performance requirements across electronics miniaturization and industrial thermal management. Segmentation reveals how purity thresholds, particle morphology, and packaging protocols fragment procurement patterns across end-use verticals.
Product Type:
ISO 9001 certification governs granular and micropowder grades for refractory applications, while IATF 16949 and semiconductor-grade cleanliness protocols constrain nanopowder qualification timelines for electronics substrates.
- Nanopowder:Sub-100nm particle distributions engineered through sol-gel or plasma synthesis routes achieve the thermal expansion precision demanded by 2.5D and 3D semiconductor packaging. Foundry qualification cycles in Taiwan and South Korea are absorbing volume as heterogeneous integration architectures proliferate.
- Micropowder:1-50μm fused or sintered grades dominate spray-dried refractory coatings where lot-to-lot consistency determines kiln furniture service life. Chinese steel and cement producers are consolidating procurement through direct synthesis plant relationships to secure batch uniformity.
- Granular:Dense fused aggregates serve insulating firebrick and monolithic refractory installations in power generation boilers.
- Flake:Platelet morphologies from controlled crystallization enhance thermal shock resistance in specialty ceramic matrix composites.
- Others:Custom agglomerated or spray-dried formulations address niche aerospace thermal protection specifications.
Micropowder sits at the top of the volume ranking, with nanopowder climbing the fastest.
Application:
Application segmentation tracks how thermal performance requirements stratify across mature industrial maintenance cycles and emerging electronics packaging investments.
- Ceramic Substrates:Low-temperature co-fired ceramic (LTCC) and high-temperature co-fired ceramic (HTCC) formulations require nanopowder grades with dielectric constants below 7 and thermal conductivity above 3 W/m·K. Semiconductor foundries in Japan and Germany are qualifying these materials for chiplet-based architectures.
- Refractory Coatings:Sprayable and trowable formulations protect steel ladles, cement kilns, and boiler tubes from slag corrosion and thermal spalling. Indian steel capacity expansion is pulling import volumes as domestic high-purity synthesis remains underdeveloped.
- Insulating Materials:Lightweight castables and insulating firebrick reduce energy consumption in high-temperature industrial furnaces.
- Catalyst Supports:High surface area mullite carriers withstand hydrothermal degradation in petrochemical and environmental catalysis.
- Optical Devices:Fused transparent grades with sub-50ppm iron content serve infrared windows and lamp envelopes.
Refractory coatings command the largest installed base, with ceramic substrates gaining share fastest.
End User Industry:
End user segmentation exposes how electronics assembly purity standards are diverging from legacy ceramics manufacturing tolerances.
- Electronics Assembly:Substrate miniaturization and heterogeneous integration are compressing thermal expansion coefficient tolerances to ±0.5 ppm/°C. Packaging engineers at semiconductor foundries are specifying nanopowder grades that fuse at lower temperatures while maintaining dielectric stability.
- Ceramics Manufacturing:Kiln furniture, crucibles, and precision structural components absorb granular and micropowder grades where creep resistance above 1600°C determines product selection. Chinese state-owned materials conglomerates are securing supply through equity-linked offtake arrangements.
- Chemical Processing:Corrosion-resistant linings and catalyst supports require chemical stability in acid and alkali environments.
- Aerospace Engineering:Thermal protection systems and radomes demand low thermal mass with high ablation resistance.
- Power Generation:Boiler insulation and gas turbine components sustain mature demand cycles with extended replacement intervals.
Ceramics manufacturing anchors current volume, with electronics assembly expanding most quickly.
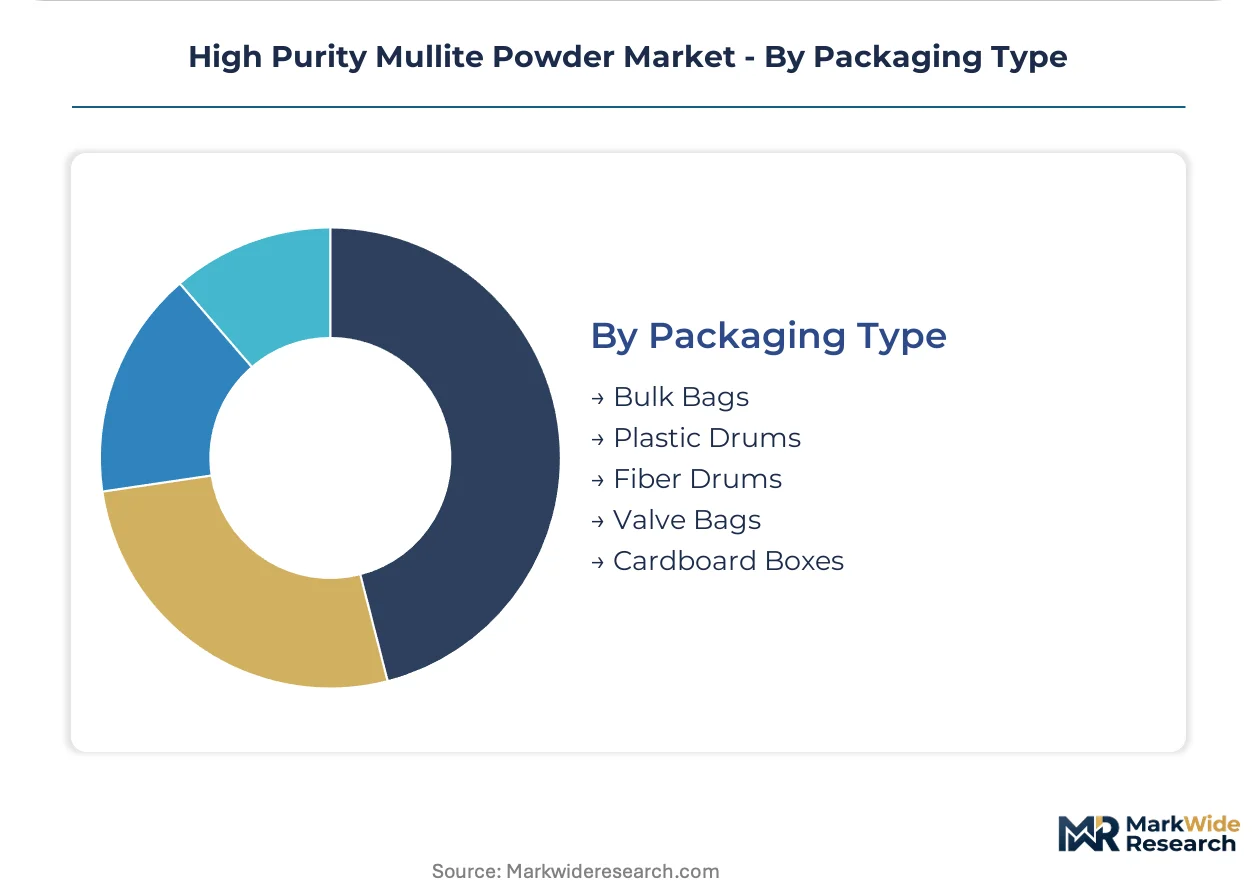
Packaging Type:
Packaging segmentation reflects how contamination sensitivity and handling automation shape logistics configurations across customer scales.
- Bulk Bags:One-ton flexible intermediate bulk containers with polyethylene liners serve high-volume refractory consumers where pneumatic conveying systems minimize handling contamination. Large steel and cement groups in China specify lot traceability through integrated barcode systems.
- Plastic Drums:25-50kg sealed polyethylene containers protect nanopowder grades from moisture pickup and cross-contamination during semiconductor foundry qualification.
- Fiber Drums:Multiwall fiber construction with foil liners balances moisture protection and recyclability for mid-volume ceramic manufacturers.
- Valve Bags:Paper-plastic laminated construction enables dust-free discharge into automated mixing systems.
- Cardboard Boxes:Corrugated containment with inner polyethylene bags serves laboratory and prototype-scale procurement.
Bulk bags dominate tonnage movements, with plastic drums expanding fastest on nanopowder qualification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and fusion process engineers cluster in Germany, Japan, and the United States, anchoring optical-grade and semiconductor-grade synthesis capabilities. China concentrates volume production capacity for refractory and electronics substrate applications.
China
State-owned materials conglomerates in Jiangsu and Shandong provinces are consolidating supplier relationships through equity-linked offtake arrangements for kiln furniture and precision ceramic components. MEE enforcement of dual carbon goals is pressuring electric arc furnace operators toward renewable energy sourcing. The Yangtze River Delta semiconductor packaging corridor is absorbing nanopowder grades at accelerating qualification pace.
United States
EPA particulate emission standards and OSHA workplace exposure limits are accelerating plant upgrades toward closed-loop synthesis systems in Tennessee and Kentucky refractory belts. The Inflation Reduction Act's domestic manufacturing incentives are supporting ceramics supply chain reshoring for power generation infrastructure. Greater Pittsburgh retains dense refractory-grade production anchored to legacy steel industry relationships.
Germany
REACH registration requirements and ECHA substance evaluation protocols are filtering non-compliant aluminum silicate suppliers from European electronics market access. Bavarian ceramic substrate manufacturers are tightening supplier qualification to pre-registered sources before product testing begins. The Rhine-Ruhr industrial corridor sustains demand for insulating materials in chemical processing and power generation applications.
Japan
METI technology roadmaps for heterogeneous integration are pulling nanopowder grades into volume production for thermal interface layers in 2.5D and 3D packaging schemes. Kyushu-based foundry packaging engineers are specifying thermal expansion coefficients compressed to ±0.5 ppm/°C tolerances. The Nagoya ceramic manufacturing cluster maintains precision structural component demand for aerospace thermal protection systems.
India
Underdeveloped domestic high-purity synthesis capacity is creating import substitution openings for compliant exporters as Odisha and Jharkhand steel capacity expands. BIS certification timelines and CDSCO material safety documentation requirements are elevating entry barriers for non-compliant fusion operators. The Gujarat ceramic manufacturing corridor is absorbing granular grades for refractory coatings in cement kiln installations.
High Purity Mullite Powder Market Competitive Landscape
Top-tier vendors anchor premium optical-grade and semiconductor-grade formulations, while mid-scale specialists occupy refractory and industrial thermal management tiers. The vendor base stratifies across fused mineral conglomerates, nanopowder technology developers, and regional refractory-grade producers. Three archetypes dominate: multinational materials conglomerates with integrated fusion assets, Japanese ceramics specialists with semiconductor substrate qualification expertise, and North American dense refractory producers with steel industry supply relationships. Competitive moves concentrate on capacity expansion in East Asian electric arc furnace clusters and strategic partnerships for sol-gel nanopowder technology licensing.
Within the multinational conglomerate tier, Imerys and Washington Mills exemplify divergent geographic and grade positioning strategies. Imerys leverages its fused mineral expertise to represent premium optical-grade formulation capabilities, while Washington Mills anchors North American supply relationships through dense refractory-grade output. Among Japanese ceramics specialists, Denka Company occupies a position exemplifying nanopowder specialization for electronics substrate applications, with its semiconductor-grade qualification protocols serving as an archetype for foundry packaging integration. These three companies illustrate how purity thresholds and end-use specifications fragment competitive positioning across diverging customer requirements.
| Leading Market Players |
|---|
| Imerys |
| Washington Mills |
| Denka Company |
| Sibelco |
| Almatis |
| CoorsTek |
| AGC Ceramics |
| Minerals Technologies |
| RHI Magnesita |
| Others |
Pricing and Supply Chain Analysis
Premium-to-commodity purity divergence splits procurement economics across electronics and refractory tiers, compressing margins on legacy micropowder grades while nanopowder commands certification premiums. Contract structures bifurcate between long-term offtake arrangements for granular refractory supply and spot-qualified nanopowder batches for semiconductor foundries, with EPA compliance costs and REACH registration burdens feeding differentially into tier-specific pricing.
Pricing Analysis
Contracted technical service bundles separate qualified nanopowder supply from unbundled granular commodity transactions. Pricing stratifies across premium, standard, and economy tiers keyed to ISO 9001, IATF 16949, and semiconductor-grade cleanliness protocols. Cost compression in micropowder refractory grades intensifies as Chinese steel and cement producers consolidate direct synthesis plant relationships. Foundry packaging engineers exhibit lowest price sensitivity due to yield-critical qualification requirements, while Indian refractory importers face acute budget constraints amid BIS certification timelines.
Supply Chain Analysis
Regional distribution centers in Tennessee, Kentucky, and the Yangtze River Delta buffer against fusion capacity concentration in East Asian electric arc furnace clusters. Raw material sourcing draws from high-grade bauxite deposits and fused alumina supply anchored to energy-intensive production nodes. Single-source vulnerability pervades optical-grade formulations where 99%+ purity capability concentrates among limited operational furnaces. Distribution runs through direct synthesis plant relationships displacing distributor intermediation for volume refractory consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high purity mullite powder market compounds steadily as substrate miniaturization in semiconductor packaging tightens thermal expansion tolerances and extends qualification-driven replacement cycles.
For Market Incumbents: Hedge against nanopowder batch consistency risks by securing sol-gel synthesis licensing partnerships before sub-100nm agglomeration control becomes yield-critical for heterogeneous integration architectures. Anchor refractory-grade margin buffers through backward integration into renewable-powered fusion routes ahead of EU Green Deal carbon border adjustments. For New Entrants and Emerging Players: Indian refractory coating specialists represent the most penetrable buyer archetype given underdeveloped domestic high-purity synthesis capacity and expanding Odisha-Jharkhand steel capacity. Target Gujarat cement kiln installations with BIS-pre-certified granular grades. Pursue technical audit bypass strategies that displace traditional merchant channels through direct plant relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where nanopowder qualification expertise concentrates among Japanese ceramics specialists with METI-aligned technology roadmaps. Long-term viability favors acquisition targets possessing captive electric arc furnace assets with optical-grade purity capability and pre-registered REACH dossiers. Watch for ECHA substance evaluation protocol expansions that filter non-compliant aluminum silicate suppliers from European electronics market access.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adds East Asian electric arc furnace nodes to address optical-grade supply concentration. |
| Backward Integration | Captures high-grade bauxite sourcing to buffer fused alumina price volatility exposure. |
| Green Manufacturing Transition | Aligns with MEE dual carbon enforcement and EU carbon border adjustment frameworks. |
| Long-term Supply Agreement | Locks in equity-linked offtake arrangements with Chinese state-owned materials conglomerates. |
| Joint Venture | Combines sol-gel nanopowder technology with foundry packaging qualification expertise. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fusion process engineers, semiconductor packaging procurement leads, refractory plant managers, and ceramic substrate R&D directors with secondary validation from SEC filings, customs and trade databases, ACC and Cefic industry reports, and ECHA substance registration dossiers. Bottom-up grade-specific volume estimates and top-down end-use demand aggregation provided cross-verification.
Segment-weighting approaches distributed value across nanopowder, micropowder, and granular product tiers, ceramic substrate and refractory coating applications, and electronics assembly versus ceramics manufacturing end-use industries across the projection horizon. CAGRs derived from regression analysis against semiconductor packaging investment cycles, steel capacity expansion trajectories, and regulatory compliance cost indices.
Underlying measurement precision varies by segment; nanopowder volumes carry tighter precision than refractory-grade estimates due to concentrated foundry qualification visibility. Forecasts reflect documented assumptions around EPA enforcement trajectories, REACH registration timelines, and electric arc furnace capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ball Clay Market
Ceramics
Graphite Crucibles Market
Ceramics
North America Activated Alumina Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Ceramic Additives Market
Ceramics
Vaterite Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Ceramic Pigments Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Quartz Powder Market
Ceramics
Aluminium Nitride Market
Ceramics
Refractories Market
Ceramics
Strontium Carbonate Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Global Magnesium Silicate Market