
 Zirconium Dioxide Market | 2026-2036
Zirconium Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Zirconium Dioxide Market Analysis
Modular supply arrangements for zirconia powder and milling services is realigning procurement patterns among dental laboratories and industrial buyers. Tosoh Corporation leverages captive chemical processing to sustain cost advantages across tetragonal grades. Saint-Gobain Zirpro anchors European refractory demand through integrated fusion-casting operations. American Elements competes on rare-earth co-production economics, extending its position in specialty oxide distribution.
Zirconium dioxide, ZrO₂, is a ceramic oxide existing in monoclinic, tetragonal, and cubic crystalline phases, with yttria-stabilized variants achieving fracture toughness exceeding 10 MPa·m½ for load-bearing biomedical implants. The material's ionic conductivity at elevated temperatures enables solid-oxide fuel cell electrolyte applications. Cubic zirconia for dental restorations commands premium positioning due to ISO 13356 biocompatibility certification and chairside milling compatibility. Refractory applications in glass and steel contact represent mature volume pools with compressed margins, while fuel cell electrolyte demand exhibits the fastest trajectory contingent on hydrogen infrastructure buildout.
REACH registration through ECHA mandates comprehensive toxicological dossiers for nano-scale zirconia, elevating compliance costs for non-European suppliers. FDA 510(k) clearance pathways for dental zirconia impose predicate-device equivalence requirements that shape R&D prioritization among manufacturers. Stakeholders must monitor yttrium oxide supply concentration and alternative stabilizer development to secure formulation continuity.
Market Dynamics
Modular procurement of zirconia powder and milling services is fragmenting traditional supply relationships, forcing refractory and dental buyers to manage multi-vendor qualification programs rather than single-source contracts.
Growth Catalysts
- Solid-oxide fuel cell electrolytes:Hydrogen infrastructure buildout in Germany and Japan is pulling tetragonal-grade zirconia into gigawatt-scale electrolyzer manufacturing.
- REACH nano-registration:ECHA's 2023 dossier requirements for nano-scale powders are accelerating consolidation among compliant European suppliers, tightening quality differentiation.
- Chairside CAD/CAM dentistry:German and Italian dental clinics are expanding same-day crown production, consuming high-translucency yttria-stabilized blanks at triple the rate of lab-based workflows.
Market Restraints
- Yttrium oxide supply concentration:Over 60% of global yttrium processing sits with Chinese rare-earth refiners, exposing stabilizer costs to export quota volatility.
- Monoclinic-tetragonal phase transformation:Unstabilized zirconia's 3-5% volume expansion during thermal cycling limits its deployment in thermal barrier coatings without costly dopant addition.
- FDA 510(k) predicate equivalence:New dental zirconia formulations must demonstrate substantial equivalence to cleared devices, extending regulatory timelines by 12-18 months for novel compositions.
Strategic Opportunities
- Scandia-stabilized variants:Scandium-doped zirconia achieves ionic conductivity 40% above yttria grades, positioning it for next-generation intermediate-temperature fuel cells in South Korean and Japanese demonstration projects.
- Modular milling service contracts:Dental laboratories in France and Spain are outsourcing block machining to specialized service bureaus, reducing capital requirements and enabling just-in-time inventory models.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms are incentivizing electric-arc furnace operators to specify high-purity zirconia nozzles for extended campaign life and reduced refractory waste.
Industry Challenges
- Ceramicist talent scarcity:Precision sintering of biomedical-grade zirconia requires expertise in atmosphere-controlled furnaces that retiring European technicians are not replenishing through apprenticeship pipelines.
- ISO 13356 certification backlog:Biocompatibility testing queues at notified bodies in Germany and Switzerland are extending time-to-market for new dental block formulations by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zirconium Dioxide Market |
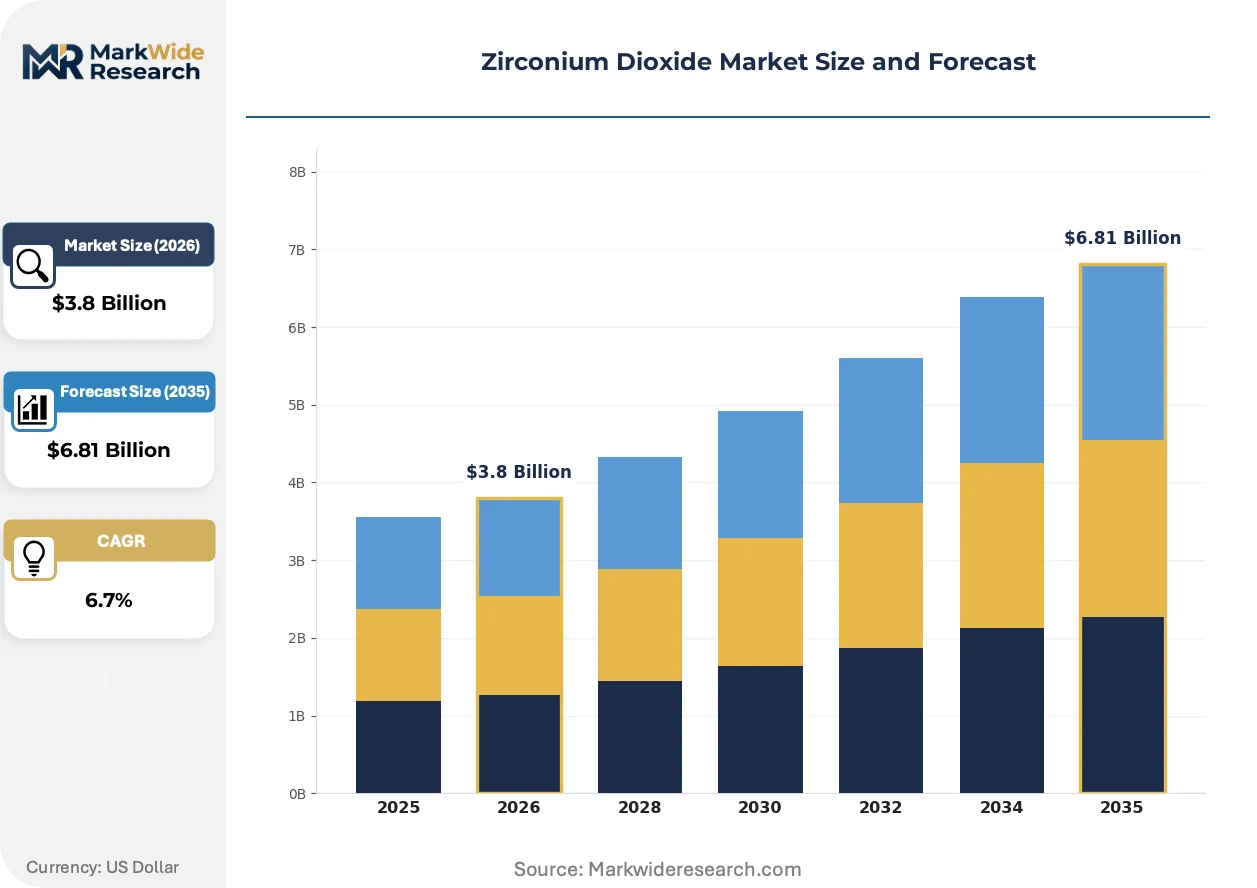
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclinic, Tetragonal, Cubic, Zirconia Toughened Application: Dental Ceramics, Fuel Cells, Coatings, Refractories End User: Healthcare, Automotive, Electronics, Aerospace Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | TUYAN INDUSTRIES, American Elements, Saint-Gobain Zirpro, Lorad Chemical Corporation, Tosoh Corporation, Zircoa, Zircomet Limited, Stanford Advanced Materials, ZIRCONIUM CHEMICALS PVT. LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zirconium Dioxide Market Emerging Trajectories
Digital manufacturing workflows and alternative stabilizer chemistries are compressing traditional qualification cycles while opening performance tiers that legacy supply structures cannot address.
Additive manufacturing of zirconia ceramics through binder jetting and lithography-based methods is absorbing development resources from conventional pressing operations. German orthopedic implant manufacturers are piloting patient-specific acetabular cups with lattice structures impossible to achieve through machining. This technology is absorbing market share from wrought titanium in hip resurfacing applications where wear resistance and biocompatibility converge.
REACH authorization requirements for nano-scale zirconia are tightening toxicological data obligations beyond what legacy dossiers contain. ECHA's 2024 guidance on inhalation exposure limits is forcing powder handlers to upgrade containment systems. Dental block producers in Italy and Germany are responding by shifting toward pre-sintered blanks that minimize airborne particle exposure during chairside milling.
Dental laboratories are consolidating purchasing power through group procurement organizations that negotiate directly with powder synthesizers, bypassing traditional distributor markups. French and Spanish lab networks now contract for quarterly powder allocations with price collars tied to yttrium oxide spot indices. This concentration is most visible in the Düsseldorf-Cologne corridor, where three buying cooperatives represent over 200 independent laboratories.
Zirconium Dioxide Market Segmentation
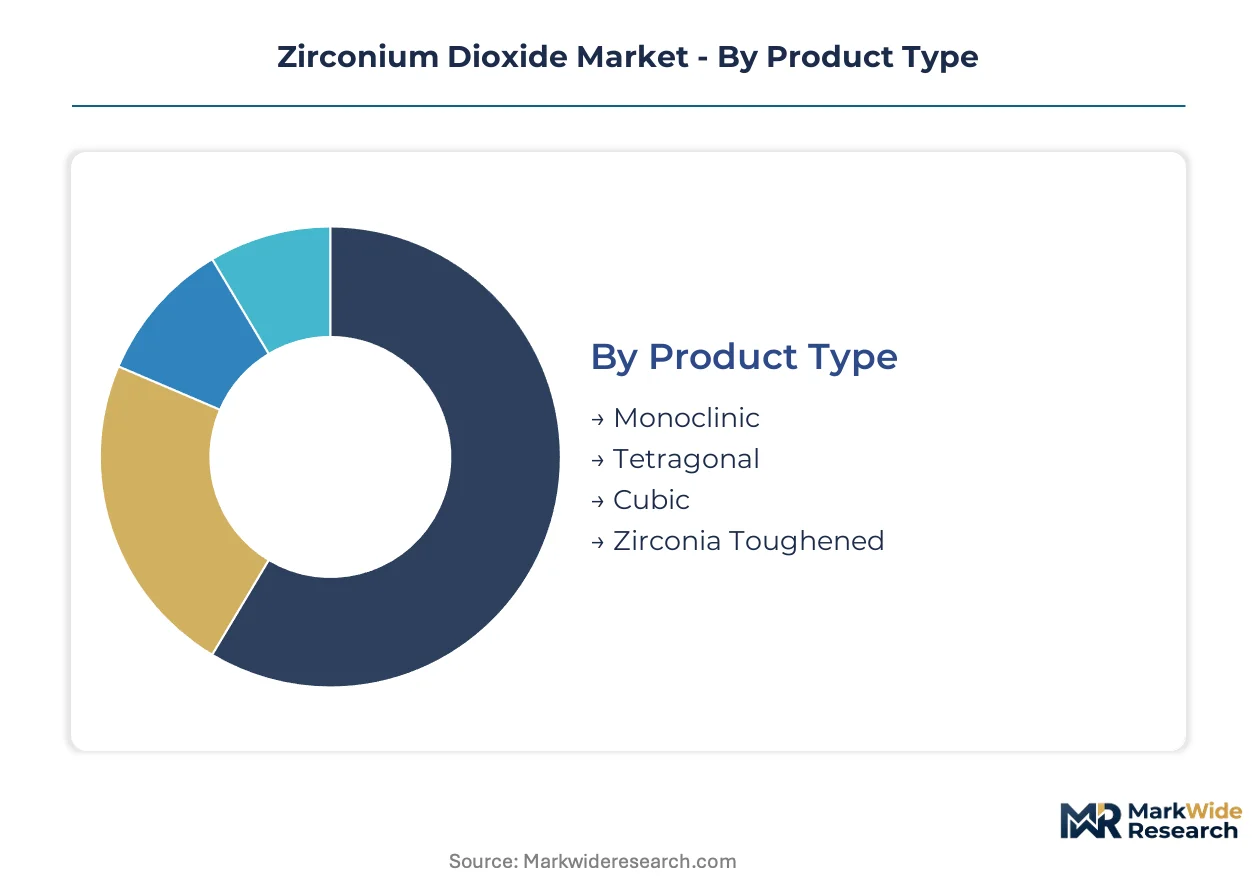
Crystalline phase stability and yttria doping levels determine performance thresholds across biomedical, energy, and industrial applications. Specification differentiation creates distinct procurement channels and qualification requirements that shape supplier relationships.
Product Type:
Tetragonal-phase stabilization via yttrium oxide doping governs fracture toughness and ionic conductivity specifications.
- Monoclinic:Unstabilized zirconia exhibits 3-5% volume expansion during thermal cycling. Refractory manufacturers in Germany limit its use to non-thermal-shock applications such as glass tank superstructures.
- Tetragonal:Yttria-stabilized variants achieve fracture toughness exceeding 10 MPa·m½. Solid-oxide fuel cell electrolyte manufacturers in Japan and Germany consume this grade for gigawatt-scale hydrogen production infrastructure.
- Cubic:Fully stabilized with 8 mol% yttria for maximum ionic conductivity. High-temperature sensor applications in aerospace propulsion systems specify this phase for thermal stability above 1000°C.
- Zirconia Toughened:Partially stabilized composites leverage stress-induced phase transformation for crack deflection. Biomedical implant producers favor this grade for load-bearing orthopedic components requiring wear resistance.
Mature deployment sits with monoclinic grades in refractory linings. Newer deployment is concentrated in tetragonal variants for fuel cell electrolytes.
Application:
End-use performance requirements drive specification fragmentation across biomedical certification tiers and industrial durability standards.
- Dental Ceramics:ISO 13356 biocompatibility certification and chairside CAD/CAM compatibility define premium positioning. German and Italian clinics are expanding same-day crown production, consuming high-translucency yttria-stabilized blanks at accelerated rates.
- Fuel Cells:Solid-oxide electrolyte applications demand tetragonal-grade purity above 99.9% with controlled grain boundary chemistry. Hydrogen infrastructure buildout in Germany and Japan is pulling material into gigawatt-scale electrolyzer manufacturing.
- Coatings:Thermal barrier applications require dopant-modified formulations to suppress monoclinic-tetragonal phase transformation. Aerospace turbine manufacturers specify plasma-sprayed layers for extended component life in high-thermal-gradient environments.
- Refractories:Glass and steel contact applications represent volume pools with compressed margins. Electric-arc furnace operators in the EU are specifying high-purity nozzles under carbon border adjustment incentives for extended campaign life.
Volume concentration remains with refractory applications. Value expansion is climbing the fastest in fuel cell electrolytes contingent on hydrogen infrastructure deployment.
End User:
Regulatory pathways and qualification timelines segment procurement behavior across safety-critical sectors.
- Healthcare:FDA 510(k) predicate equivalence requirements and ISO 13356 certification queues at German and Swiss notified bodies extend time-to-market. Dental laboratories are consolidating purchasing power through group procurement organizations that negotiate directly with powder synthesizers.
- Automotive:Oxygen sensor manufacturers specify stabilized zirconia for exhaust gas monitoring. Emissions regulation stringency in the EU and Japan sustains replacement demand for lambda probe ceramics.
- Electronics:Solid-oxide fuel cell stack assemblers and high-temperature sensor producers drive specification for ultra-high-purity grades. South Korean and Japanese demonstration projects are piloting scandia-stabilized variants for intermediate-temperature operation.
- Aerospace:Thermal barrier coating applicators and propulsion system sensor manufacturers require cubic-phase stability. US and European turbine engine producers maintain qualified supplier lists with multi-year certification cycles.
Procurement maturity sits with automotive sensor applications. Regulatory complexity is expanding most quickly in healthcare as biocompatibility dossier requirements tighten.
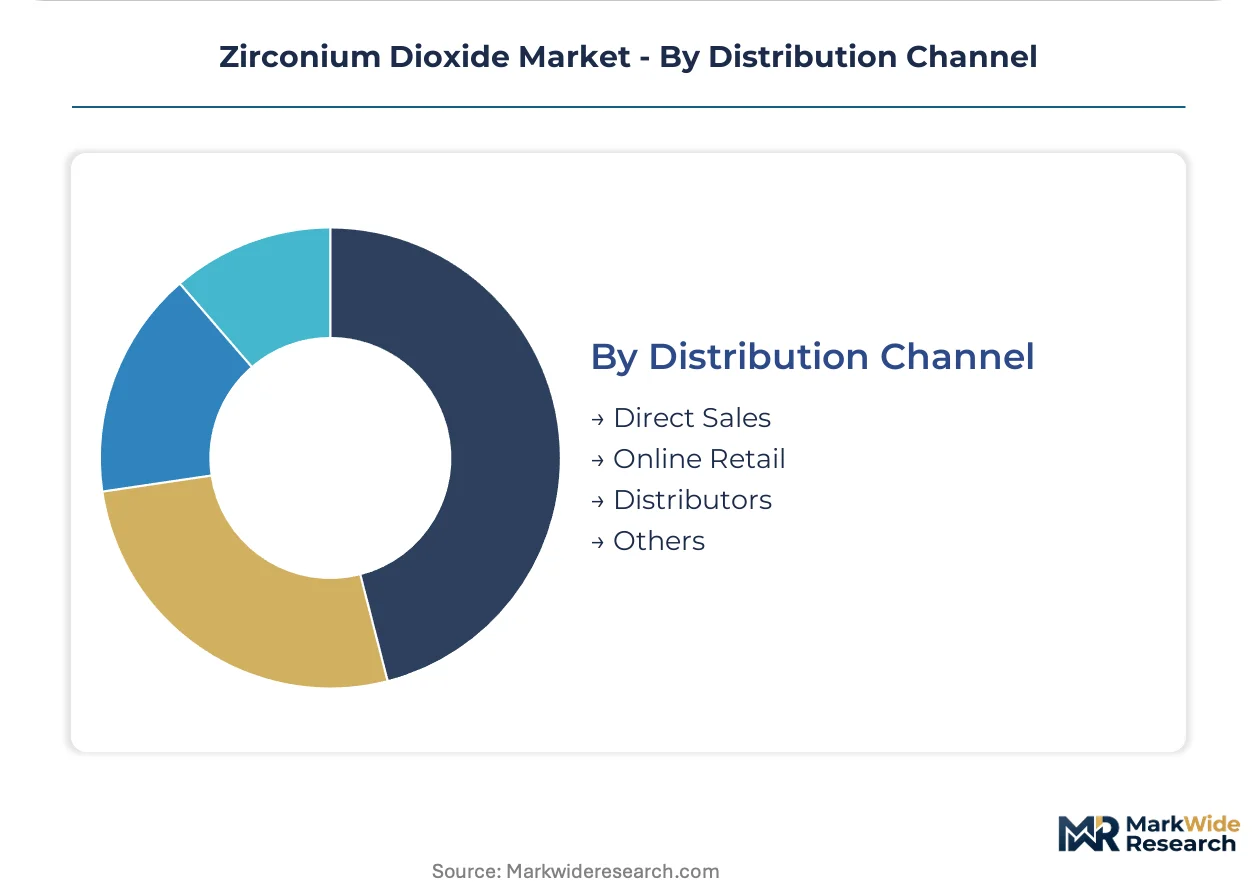
Distribution Channel:
Supply chain configuration segments by order scale, technical service intensity, and geographic proximity to manufacturing clusters.
- Direct Sales:Volume contracts with refractory manufacturers and fuel cell stack assemblers bypass distributor markups. Tosoh Corporation and Saint-Gobain Zirpro maintain dedicated technical service teams for specification development.
- Online Retail:Small-laboratory procurement of pre-sintered dental blanks through specialized ceramic supply platforms. French and Spanish lab networks use this channel for just-in-time inventory of standardized block geometries.
- Distributors:Regional inventory holding for industrial buyers requiring rapid replenishment of standardized refractory grades. German precision ceramics clusters around Cologne and Düsseldorf concentrate distributor warehousing capacity.
- Others:Modular milling service bureaus that contract for powder allocation with dental laboratories, functioning as outsourced manufacturing partners rather than traditional resellers.
Relationship stability sits with direct sales to industrial volume consumers. Channel experimentation is gaining share fastest in dental procurement through service bureau models and cooperative buying structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates zirconium dioxide feedstock refining while Germany and Japan concentrate value-added ceramic fabrication. Consumption clusters in dental and fuel cell applications pull processed material toward European and East Asian manufacturing centers.
Germany
Solid-oxide fuel cell electrolyte demand and chairside CAD/CAM dentistry expansion drive tetragonal-grade consumption. ECHA REACH nano-registration requirements tighten purity thresholds for biomedical-grade powder imports. The Cologne-Düsseldorf corridor hosts precision ceramics clusters where dental laboratories consolidate purchasing through group procurement organizations.
Japan
Hydrogen infrastructure buildout accelerates tetragonal zirconia demand for gigawatt-scale electrolyzer manufacturing. METI funding programs support intermediate-temperature fuel cell demonstrations using scandia-stabilized variants. Osaka-based ceramic producers maintain qualified supplier relationships with domestic stack assemblers for aerospace sensor applications.
United States
FDA 510(k) predicate equivalence requirements shape dental zirconia formulation development timelines. EPA emissions standards sustain automotive oxygen sensor replacement demand for stabilized grades. California orthopedic implant manufacturers pilot additive manufacturing of patient-specific zirconia components through binder jetting methods.
China
Rare-earth refiners control over 60% of global yttrium oxide processing for stabilizer supply. MIIT industrial standards govern purity specifications for export-grade zirconia powder. Yangtze River Delta chemical processors leverage co-production economics to supply specialty oxide distributors serving European dental block producers.
Italy
Dental ceramics adoption accelerates across clinics expanding same-day crown production capabilities. EU Green Deal carbon border adjustments incentivize electric-arc furnace operators to specify high-purity refractory nozzles. Lombardy-based laboratories outsource block machining to specialized service bureaus, reducing capital requirements through just-in-time inventory models.
Zirconium Dioxide Market Vendor Landscape
The competitive structure tilts toward integrated chemical processors with captive stabilizer supply and specialized ceramic fabricators with ISO 13356 certification depth. Market concentration varies sharply by crystalline phase: monoclinic refractory grades operate on compressed margins with fragmented regional supply, while tetragonal biomedical and fuel cell grades favor qualified supplier relationships with multi-year certification cycles. Three archetypes dominate: rare-earth co-producers leveraging yttrium oxide economics, precision sintering specialists with atmosphere-controlled furnace expertise, and modular milling service bureaus displacing traditional distributor channels. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with dental laboratories consolidating purchasing power through cooperative structures.
Among Japanese chemical processors, Tosoh Corporation occupies a position exemplifying captive chemical processing advantages across tetragonal grades. Saint-Gobain Zirpro anchors European refractory demand through integrated fusion-casting operations. American Elements sits within the specialty oxide distribution tier, competing on rare-earth co-production economics. These three represent distinct strategic positions: backward integration into feedstock refining, forward integration into refractory fabrication, and horizontal breadth across rare-earth oxide portfolios.
| Leading Market Players |
|---|
| TUYAN INDUSTRIES |
| American Elements |
| Saint-Gobain Zirpro |
| Lorad Chemical Corporation |
| Tosoh Corporation |
| Zircoa |
| Zircomet Limited |
| Stanford Advanced Materials |
| ZIRCONIUM CHEMICALS PVT. LTD. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Germany's precision ceramics cluster anchor supply discipline through multi-generational technical expertise, translating into pricing power that resists commoditization despite yttrium oxide cost volatility. Their captive furnace operations and ISO 13356 certification depth create procurement stickiness among dental laboratories that cannot easily qualify alternative suppliers.
Pricing Analysis
Margin tightening in refractory-grade monoclinic powder traces to Chinese rare-earth refinery concentration and compressed steel-glass contact application economics. Three-tier pricing structure across premium biomedical, standard industrial, and economy refractory levels separates ISO 13356-certified dental blocks from uncertified industrial grades. Cost-down pressure on tetragonal fuel cell electrolyte grades accelerates because gigawatt-scale hydrogen infrastructure procurement favors volume contract aggregation. Dental laboratories consolidating through French and Spanish buying cooperatives exhibit highest price sensitivity, while aerospace thermal barrier coating applicators maintaining qualified supplier lists show least.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth refiners controlling over sixty percent of global yttrium oxide processing for stabilizer supply. Raw material dependencies draw from Australian zircon sand, Chinese yttrium oxide, and Japanese chemical processing equipment. Tariff exposure on biomedical-grade powder imports into the EU under carbon border adjustment mechanisms threatens margin structures for non-compliant Asian suppliers. Distribution runs through direct sales contracts for industrial volume consumers, specialized ceramic supply platforms for small-laboratory procurement, and modular milling service bureaus functioning as outsourced manufacturing partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH nano-registration requirements for zirconium dioxide powder create a cost-of-compliance story that erects barrier-to-entry moats for European suppliers with existing toxicological dossiers while excluding undercapitalized entrants.
For Market Incumbents: Hedge against yttrium oxide supply concentration by accelerating scandia-stabilized variant development for intermediate-temperature fuel cells. Deepen backward integration into rare-earth co-processing or secure long-term offtake agreements with Australian zircon sand miners. Tosoh Corporation's captive chemical processing model demonstrates how in-house stabilizer production defends margin position against Chinese export quota volatility. For New Entrants and Emerging Players: Enter via modular milling service bureau contracts serving Italian and Spanish dental laboratories seeking capital-light just-in-time inventory models. Target the chairside CAD/CAM dentistry segment where high-translucency yttria-stabilized blank consumption triples lab-based workflows. Partner with French buying cooperatives for quarterly powder allocation contracts with price collars tied to yttrium oxide spot indices. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision sintering specialists with atmosphere-controlled furnace expertise in Germany's Cologne-Düsseldorf corridor. Long-term viability over the next decade hinges on ISO 13356 certification depth and REACH nano-registration compliance rather than commodity volume scale. Watch ECHA inhalation exposure limit guidance enforcement as inflection indicator for pre-sintered blank demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Processing | Captive yttrium oxide supply insulates Tosoh Corporation from Chinese export quota volatility. |
| ISO 13356 Certification Investment | Biocompatibility dossier depth secures multi-year supplier relationships with German dental laboratories. |
| Modular Milling Service Bureau Launch | Just-in-time inventory models reduce capital requirements for French and Spanish dental networks. |
| Scandia-Stabilized Variant Development | Forty percent ionic conductivity advantage positions South Korean and Japanese fuel cell demonstrations. |
| REACH Nano-Registration Compliance | ECHA toxicological dossier requirements exclude non-European suppliers from biomedical-grade powder markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ceramic plant managers, dental laboratory procurement leads, fuel cell stack assemblers, and ECHA regulatory affairs specialists. SEC 10-K disclosures from Saint-Gobain and Tosoh Corporation, Cefic chemical industry reports, and German customs export statistics provided volume and value triangulation. Bottom-up segment sizing across crystalline phase grades reconciled with top-down market value estimates from trade association aggregates.
Data-stream reconciliation combined production capacity surveys with end-use consumption modeling across the projection horizon. Segmentation dimensions included crystalline phase stability, yttria doping level, application certification tier, and geographic manufacturing cluster. CAGRs derived from slope analysis of historical volume trends and elasticity-adjusted demand projections. Hydrogen infrastructure deployment schedules and dental CAD/CAM adoption curves served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA regulatory acceleration or Chinese rare-earth export restriction scenarios. Assumptions underlying projections reflect documented stakeholder input and secondary source validation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Europe Aluminum Oxide Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Graphite Crucibles Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Transparent Ceramics Market
Ceramics
Titanates Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
ME K-Feldspar Market
Ceramics
Global Functional Ceramics Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Ceramic Binders Market
Ceramics
Saudi Arabia Ceramic Tiles Market