
 Glazed Ceramic Tile Market | 2026-2036
Glazed Ceramic Tile Market Size, Share, and Industry Trends Forecast 2026-2036
Glazed Ceramic Tile Market Insights
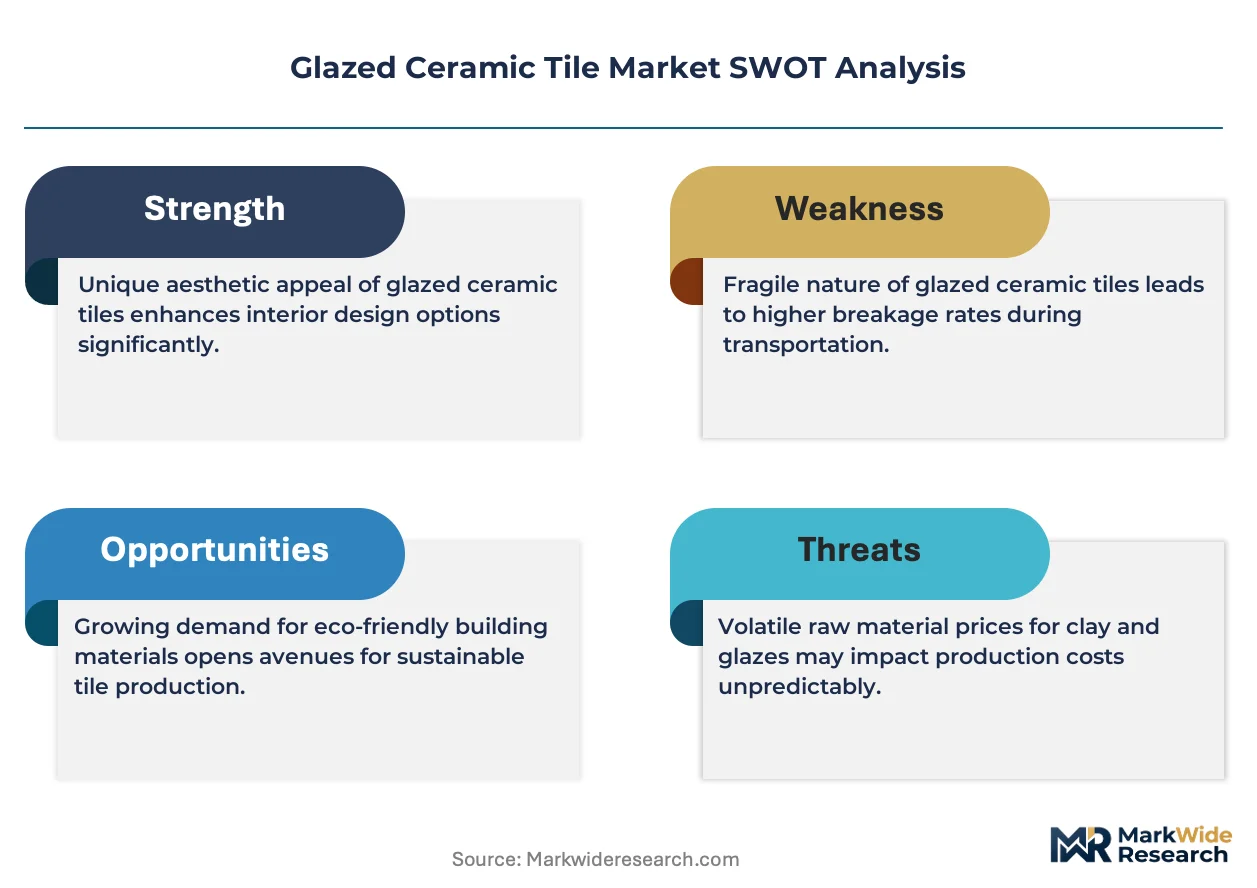
ISO 13006 certification for ceramic tiles is unwinding the competitive field, forcing smaller producers toward costly lab upgrades or exit. Mohawk Industries leverages its North American manufacturing footprint to sustain premium positioning in specification-grade products. RAK Ceramics anchors Middle East and African supply through integrated clay-to-distribution operations. Kajaria Ceramics dominates India's branded retail channel with extensive dealer networks.
Glazed ceramic tile consists of a clay body coated with a glass-forming mineral slip, fired above 1000°C to create a non-porous, stain-resistant surface specified for interior and exterior cladding and flooring. Floor tiles command the largest volume share as hard-surface flooring displaces carpet in commercial and residential settings. Decorative tiles generate disproportionate margin pools through artisanal glazing and custom digital printing. Wall tiles in large-format rectangular dimensions are gaining specification in hospitality bathrooms and kitchen backsplashes.
EPA emission standards for ceramic kiln operations in the United States and REACH chemical restrictions across Europe constrain glaze formulation choices, pushing manufacturers toward lead-free and low-VOC alternatives. China's MEE enforces stricter air-quality thresholds in ceramic-producing provinces, reshaping plant location decisions. India's BIS mandatory certification for ceramic tiles creates compliance barriers for unorganized producers. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and facility relocation.
Market Dynamics
China's MEE emission thresholds for ceramic kilns are compressing capacity in Shandong and Guangdong provinces, forcing producers toward gas-fired tunnel kilns or relocation to Vietnam and Indonesia.
Growth Catalysts
- REACH chemical restrictions:Lead-free glaze formulations from European manufacturers are capturing specification-grade hospitality projects in Dubai and Riyadh.
- Residential construction:Vietnam's urban corridor from Ho Chi Minh City to Da Nang is absorbing large-format porcelain stoneware for high-rise cladding.
- Digital inkjet decoration:Single-pass printers with nano-pigment suspensions enable batch-size-one production for custom residential interiors.
Market Restraints
- Feldspar supply concentration:Turkish and Indian feldspar deposits control 60% of global ceramic-grade flux supply, exposing glaze costs to shipping rate volatility.
- Natural gas price spreads:European kiln operators face threefold energy costs versus Iranian or Egyptian competitors, eroding export competitiveness.
- Thin-set mortar substitution:Luxury vinyl tile and SPC flooring with click-lock installation are capturing mid-market residential flooring specifications.
Strategic Opportunities
- Indonesia's industrial zones:Batam and Java offer MEE-compliant kiln locations with ASEAN market access and lower emission compliance costs than China.
- BIS mandatory certification:India's quality mark creates acquisition opportunities for organized producers to consolidate unorganized capacity in Morbi and Thangadh.
- Photovoltaic-thermal integration:Kiln waste heat recovery systems paired with rooftop solar are qualifying producers for EU Green Deal carbon border adjustment exemptions.
Industry Challenges
- ISO 13006 testing backlog:Laboratory accreditation queues in Southeast Asia stretch 14-18 weeks, delaying export shipments to Saudi Arabia and Australia.
- Legacy kiln reconfiguration:Converting coal-fired Hoffmann kilns to natural gas requires 18-24 month timelines with production downtime exceeding 40%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazed Ceramic Tile Market |
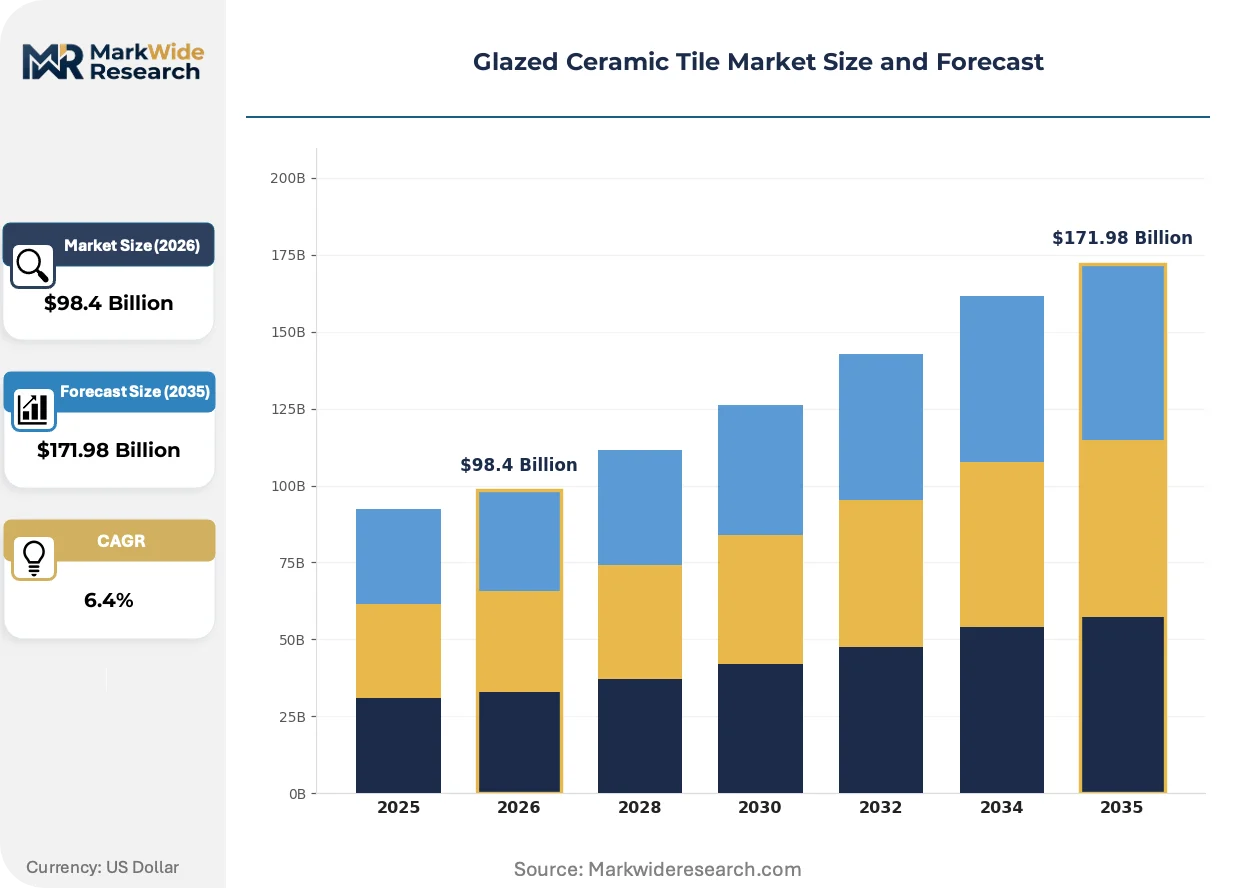
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $171.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Tiles, Wall Tiles, Decorative Tiles, Mosaic Tiles End Use: Residential, Commercial, Hospitality, Educational Shape: Rectangular, Square, Hexagonal, Circular Glaze Type: Satin, Glossy, Matt, Textured |
| Companies Covered | Mohawk Industries, Inc., RAK Ceramics, Kajaria Ceramics Limited, Porcelanosa Grupo, Atlas Concorde S.p.A., Grupo Lamosa, China Ceramics Co., Ltd., Florim Ceramiche S.p.A., Crossville, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazed Ceramic Tile Market Trends and Innovations
Digital decoration and low-carbon kiln technologies are fragmenting the traditional mass-production model, enabling regional specialists to compete on customization rather than scale.
Single-pass inkjet printing with reactive nano-glazes is decomposing the economics of rotary screen decoration. Italian equipment suppliers are retrofitting existing roller kilns with drop-in inkjet modules for mid-size producers. This technology is compressing minimum order quantities from 2,000 square meters to 200 square meters, enabling architect-specified custom batches.
China's GB standards for building materials are tightening particulate and NOx thresholds in ceramic-producing provinces. Shandong manufacturers are installing selective catalytic reduction systems or relocating kilns to Indonesia. Export-oriented producers in Foshan are absorbing 12-15% cost increases for emission control equipment.
Specification-grade buyers are consolidating vendor lists around certified producers with documented carbon footprints. Hospitality developers in Singapore and Australia are requiring EPD-compliant tiles for LEED and Green Star ratings. This preference shift favors integrated producers with captive clay reserves and renewable energy contracts over trading-house distributors.
Glazed Ceramic Tile Market Segmentation
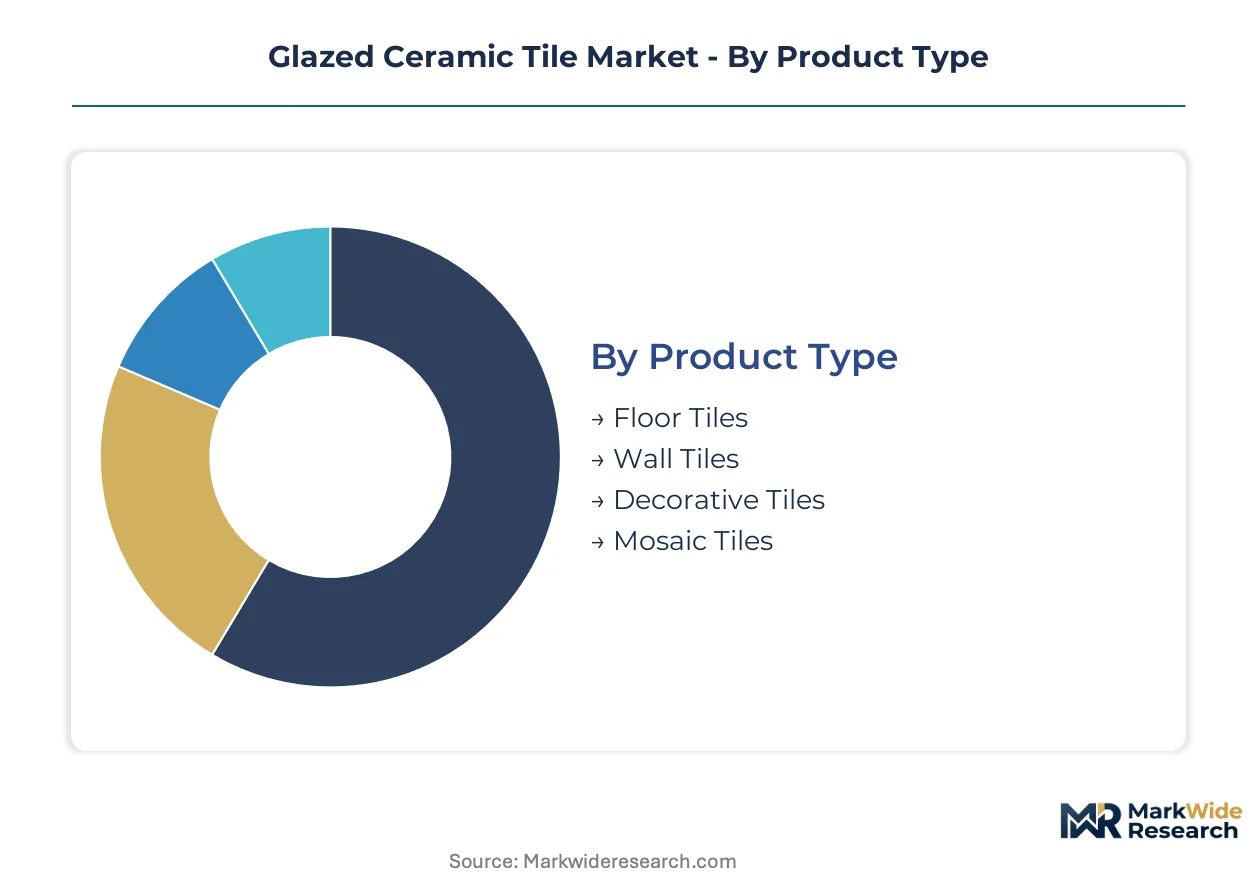
Glazed ceramic tile procurement channels diverge sharply by segment, with specification-grade products flowing through architect-specified distribution while commodity tiles move through retail dealer networks. Understanding these channel dynamics reveals where margin pools concentrate and which segments reward brand investment versus scale efficiency.
Product Type:
Floor tiles dominate contractor-direct procurement through building supply distributors, while decorative tiles concentrate in design-showroom channels with specification support.
- Floor Tiles:These tiles carry the highest clay body density and breaking strength ratings for load-bearing applications. Demand concentrates in Vietnam's high-rise residential towers from Ho Chi Minh City to Da Nang, where hard-surface flooring displaces carpet in both commercial and residential settings.
- Wall Tiles:Large-format rectangular dimensions with lighter clay bodies enable vertical installation with reduced adhesive consumption. Hospitality bathroom specifications in Singapore and Australia are driving procurement of EPD-compliant products for LEED and Green Star ratings.
- Decorative Tiles:Artisanal glazing and custom digital printing command premium positioning through designer showrooms.
- Mosaic Tiles:Small-format mesh-mounted sheets serve niche backsplash and accent wall applications.
By volume, Floor Tiles leads. By growth pace, Wall Tiles is ahead.
End Use:
Cost tier stratification separates specification-grade hospitality projects from price-sensitive residential renovations.
- Residential:Single-family and multi-family housing absorbs standard-grade glazed ceramic through retail dealer networks and home improvement centers. Southeast Asia's urban corridor expansion is channeling procurement toward large-format porcelain stoneware for cladding and flooring.
- Commercial:Office and retail specifications prioritize durability ratings and slip resistance for high-traffic applications. REACH-compliant lead-free glaze formulations from European manufacturers are capturing specification-grade projects in Dubai and Riyadh.
- Hospitality:Hotel and resort developments require documented carbon footprints and EPD certification for green building compliance.
- Educational:Schools and universities specify abrasion-resistant surfaces for corridor and common area applications.
Residential commands the widest channel reach. Hospitality delivers the steepest expansion trajectory.
Shape:
Manufacturing setup costs and cutting waste rates vary dramatically by dimensional format.
- Rectangular:Large-format planks and subway formats enable contemporary aesthetic specifications with minimal grout lines. Digital inkjet decoration with single-pass printers supports batch-size-one production for custom residential interiors.
- Square:Traditional modular formats maintain inventory efficiency for standard commercial specifications.
- Hexagonal:Geometric formats require specialized cutting equipment and generate higher installation labor costs.
- Circular:Niche decorative formats serve accent applications with limited volume scale.
Square formats retain the broadest installer familiarity. Rectangular dimensions are gaining share fastest.
Glaze Type:
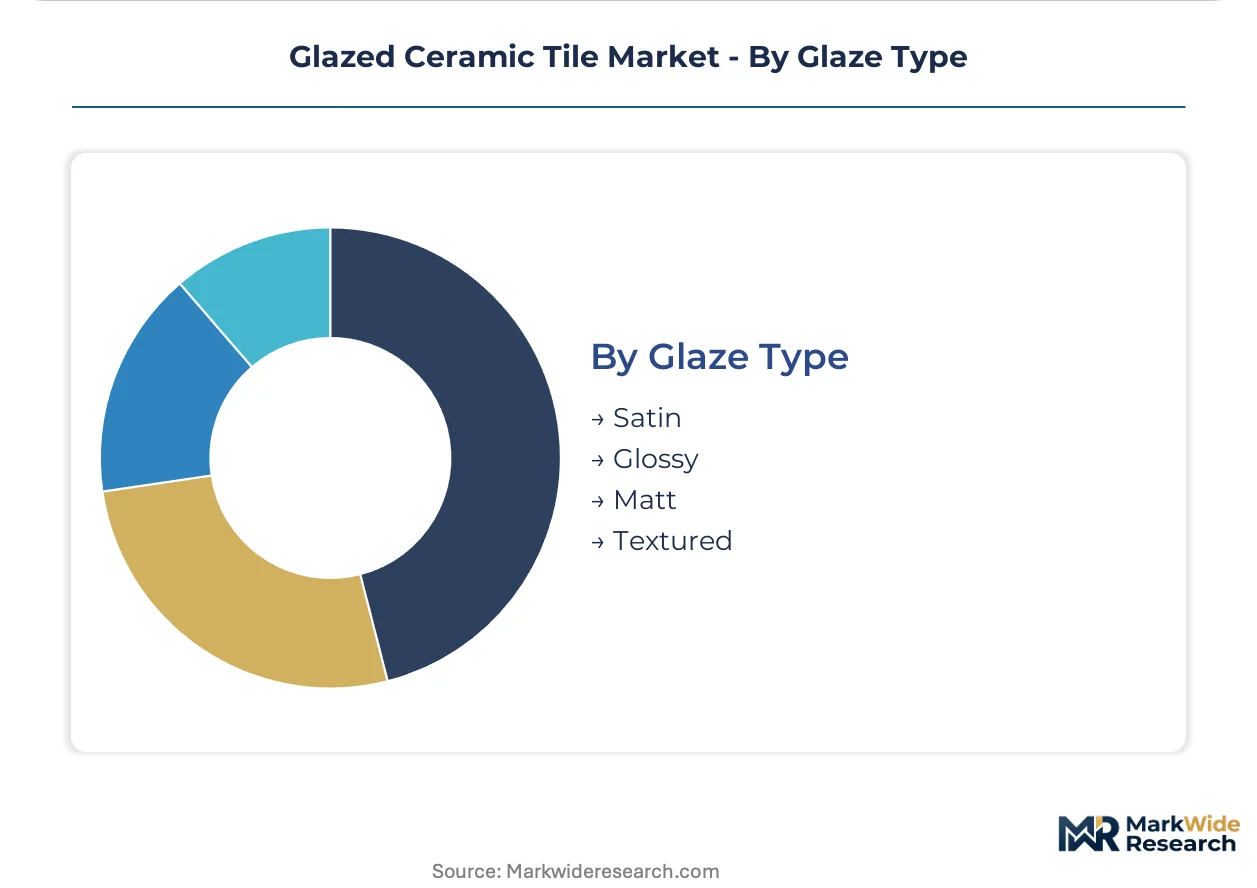
Surface finish determines both aesthetic positioning and functional performance in wet and high-traffic environments.
- Satin:Intermediate sheen levels balance slip resistance with cleanability for residential bathrooms and kitchens. EPA emission standards and REACH chemical restrictions are constraining formulation choices toward lead-free and low-VOC alternatives.
- Glossy:High-sheine surfaces maximize light reflection but require higher slip resistance ratings for commercial wet areas.
- Matt:Low-sheine finishes dominate commercial flooring specifications for slip resistance compliance.
- Textured:Relief surfaces enable anti-slip performance for exterior and wet-area applications.
Matt finishes lead in commercial volume. Satin glazes are climbing the fastest in residential replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specification-grade buyers in hospitality and high-rise residential sectors concentrate procurement decisions in four countries with diverging regulatory frameworks and industrial cluster configurations.
China
Shandong and Guangdong provinces host the densest kiln concentrations, yet MEE emission thresholds are compressing capacity and forcing producers toward gas-fired tunnel kilns or relocation. GB standards for building materials now mandate selective catalytic reduction for particulate and NOx control. Foshan manufacturers absorb 12-15% cost increases for emission control equipment while maintaining export orientation.
Vietnam
Urban corridor expansion from Ho Chi Minh City to Da Nang drives large-format porcelain stoneware absorption for high-rise cladding and flooring. The country's national construction regulator enforces evolving building material standards aligned with ASEAN harmonization. Industrial zones in Binh Duong and Dong Nai provinces attract relocated Chinese kiln capacity seeking lower compliance costs.
India
Morbi and Thangadh clusters in Gujarat state concentrate unorganized production capacity now facing BIS mandatory certification barriers. Residential construction across Maharashtra and Karnataka channels branded retail procurement through extensive dealer networks. Organized producers leverage quality mark requirements to consolidate fragmented supply.
Italy
Modena and Sassuolo districts anchor European specification-grade production with heritage in rotary screen and digital inkjet decoration technologies. REACH chemical restrictions constrain glaze formulation choices toward lead-free alternatives. Italian equipment suppliers retrofit existing roller kilns with drop-in inkjet modules for mid-size regional producers.
United States
EPA emission standards for ceramic kiln operations constrain glaze formulation choices in Tennessee and Texas manufacturing locations. Commercial flooring specifications prioritize durability ratings and slip resistance for high-traffic applications. Crossville and domestic manufacturing footprints sustain premium positioning in architect-specified distribution channels.
Glazed Ceramic Tile Market Competitive Landscape
Player mix skews toward integrated producers with captive clay reserves and renewable energy contracts alongside trading-house distributors facing margin compression from certification requirements. Three archetypes dominate: specification-grade specialists with documented carbon footprints, scale-driven commodity producers with ASEAN relocation strategies, and equipment-technology licensors capturing value from digital decoration transitions. Consolidation pressures concentrate around M&A targeting BIS-certified capacity in India and greenfield kiln investments in Indonesia's industrial zones.
Among North American integrated producers, Mohawk Industries, Inc. occupies a position exemplifying premium-tier specification-grade positioning through manufacturing footprint control. Crossville, Inc. represents the domestic specialist archetype serving architect-specified distribution. RAK Ceramics anchors Middle East and African supply chain configuration through integrated clay-to-distribution operations. Kajaria Ceramics Limited exemplifies branded retail channel dominance through dealer network density in India's organized tier. Porcelanosa Grupo and Florim Ceramiche S.p.A. sit within the European specification-grade tier where REACH-compliant formulations capture hospitality project mandates in Dubai and Riyadh.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| RAK Ceramics |
| Kajaria Ceramics Limited |
| Porcelanosa Grupo |
| Atlas Concorde S.p.A. |
| Grupo Lamosa |
| China Ceramics Co., Ltd. |
| Florim Ceramiche S.p.A. |
| Crossville, Inc. |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week laboratory accreditation queues in Southeast Asia compress working capital cycles and amplify pricing power for ISO 13006-certified producers serving Saudi Arabia and Australia. Inventory carrying costs for feldspar-dependent glaze formulations rise when Turkish and Indian shipping rates spike, forcing tile manufacturers to embed volatility clauses in long-term supply agreements.
Pricing Analysis
Cost-plus contracts indexed to natural gas benchmarks dominate kiln-operator procurement agreements, with price adjustments triggered at quarterly resets. Price differentiation rests on certification grade and volume scale, with BIS-mandated quality marks commanding premiums over unorganized Morbi output. Pricing pressure intensifies in mid-market residential flooring as luxury vinyl tile and SPC alternatives capture specifications. Price-sensitive residential renovators drive volume, while LEED-compliant hospitality developers absorb premium positioning.
Supply Chain Analysis
Strategic feldspar stockpiling persists among integrated producers, while smaller operators maintain just-in-time clay body sourcing vulnerable to Binh Duong logistics congestion. Supply concentration centers on Turkey, India, and China for ceramic-grade flux, with captive clay reserves in Vietnam and Indonesia anchoring relocated kiln capacity. Shipping rate volatility on feldspar routes constitutes the primary structural risk. Distribution runs through architect-specified channels for specification-grade products and retail dealer networks for commodity tiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. BIS mandatory certification and ISO 13006 compliance create switching costs that lock specification-grade buyers into validated supplier relationships.
For Market Incumbents: Compound certification advantages by acquiring BIS-certified capacity in Morbi and Thangadh before quality mark enforcement accelerates. Deepen upstream control over captive clay reserves in Vietnam's Binh Duong and Dong Nai industrial zones. Defensive positioning against SPC flooring substitution requires accelerating EPD-compliant product lines for Singapore and Australia hospitality mandates.
For New Entrants and Emerging Players: Custom batch-size-one production represents a service-layer gap where incumbents under-serve architect-specified residential interiors. Penetrate Indonesia's Batam and Java industrial zones with MEE-compliant kiln investments serving ASEAN markets. Deploy single-pass inkjet modules for 200-square-meter minimum orders, capturing specification-grade hospitality backsplash and accent wall demand.
For Investors and Strategic Acquirers: Carve-out targets emerge from European trading-house distributors facing margin compression from carbon footprint documentation requirements. Long-term viability favors integrated producers with renewable energy contracts qualifying for EU Green Deal carbon border adjustment exemptions. Watch for feldspar shipping rate spikes as inflection indicators triggering consolidation waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Clay Reserves | Vietnam's Binh Duong deposits secure supply for relocated Chinese kiln capacity. |
| ISO 13006 Laboratory Accreditation Investment | Fourteen-week testing queues in Southeast Asia create first-mover certification advantages. |
| Photovoltaic-Thermal Kiln Retrofit | Waste heat recovery paired with rooftop solar qualifies producers for EU carbon border exemptions. |
| Single-Pass Inkjet Module Deployment | Italian equipment retrofits compress minimum orders from 2,000 to 200 square meters for custom batches. |
| BIS-Certified Capacity Acquisition | Quality mark enforcement in Morbi and Thangadh enables organized-tier consolidation of unorganized supply. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Plant managers at gas-fired tunnel kiln operations, procurement leads at Dubai and Riyadh hospitality developers, distribution channel partners in India's dealer networks, and technical R&D directors at Italian equipment suppliers provided operational context. Secondary sources include China's MEE emission disclosure databases, India's BIS certification registries, EU ECHA REACH restriction updates, and ASEAN customs trade flows. Bottom-up capacity surveys and top-down construction spending models triangulate volume estimates.
Sensitivity analysis around natural gas price spreads and feldspar shipping rate volatility tests projection robustness across the analysis window. Segmentation dimensions encompass product type, end-use sector, dimensional format, and glaze finish, with regulatory compliance tier modeled as an industry-specific cross-cutting variable. CAGRs derive from installed base replacement cycles and urban corridor construction absorption rates. Forecast inputs incorporate kiln relocation timelines from Shandong to Indonesia and BIS certification penetration curves in Gujarat clusters.
Underlying assumptions cover MEE enforcement continuity in ceramic-producing provinces, with deviation risk concentrated in regulatory acceleration or relaxation scenarios. Revision becomes warranted when feldspar supply concentration crosses monopoly threshold indicators or when EU carbon border adjustment implementation timelines shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Calcite Market
Ceramics
Traditional Ceramic Market
Ceramics
Industrial Ceramics Market
Ceramics
Ceramic Frit Market
Ceramics
Colloidal Alumina Market
Ceramics
Optical Ceramics Market
Ceramics
Titanates Market
Ceramics
Refractory Material Market
Ceramics
Titanium Carbide Market
Ceramics
Calcined Bauxite Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Calcined Kaolin Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Ceramics Market
Ceramics
Refractories Market
Ceramics
Global High Performance Ceramic Coatings Market