
 Global Industrial Anti Scaling Chemical Market | 2026-2036
Global Industrial Anti Scaling Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Anti Scaling Chemical Market Intelligence
Demand from buyers seeking specialized, high-performance formulations is collapsing the traditional dominance of procurement focused solely on bulk commodity pricing. Ecolab Inc. leverages its extensive service-led model to capture this value-added segment with customized treatment programs. In contrast, BASF SE competes across the market with a vast portfolio spanning multiple performance tiers, while Kemira Oyj specializes in high-efficacy solutions for water-intensive industries like pulp and paper.
Industrial anti-scaling chemicals are formulations engineered to inhibit mineral scale deposition, primarily calcium carbonate and sulfate, in process equipment. These products, often based on phosphonates, acrylates, or other advanced polymers, prevent efficiency losses and equipment failure in industrial water systems. Within product types, organic chemicals and phosphate esters command significant share due to their cost-effectiveness and proven performance. The water treatment application remains the largest end market, driven by its critical role in maintaining operational uptime in cooling towers and boilers.
Regulatory frameworks are tightening performance and environmental standards for anti-scaling agents globally. The US EPA's effluent limitation guidelines and the European Chemicals Agency's (ECHA) substance evaluations under REACH directly influence formulation chemistry. In China, Ministry of Ecology and Environment (MEE) directives on industrial water quality push for more efficient and biodegradable solutions. Navigating the complex trade-off between scale inhibition efficacy and evolving environmental compliance requirements remains the central strategic challenge for formulators.
Market Dynamics
The central dynamic is the escalating tension between the industrial necessity for high-efficacy scale inhibition and the global regulatory push for environmentally benign chemical formulations. This conflict forces continuous product redevelopment to meet tightening standards from bodies like the EPA and ECHA.
Growth Catalysts
- Stringent Water Quality Mandates:Directives from China's Ministry of Ecology and Environment (MEE) on industrial water reuse and discharge quality compel operators in power generation and chemical manufacturing to adopt more effective anti-scaling treatments to achieve compliance.
- Industrial Infrastructure Expansion:Massive investment in water-intensive manufacturing and energy infrastructure, particularly in industrial hubs across China and India, directly expands the addressable market for water treatment chemicals needed to protect new capital equipment.
- Focus on Operational Efficiency:In sectors like pulp and paper, preventing scale buildup in boilers and evaporators is critical for maintaining thermal efficiency and production uptime, creating consistent demand for high-performance antiscalants.
Market Restraints
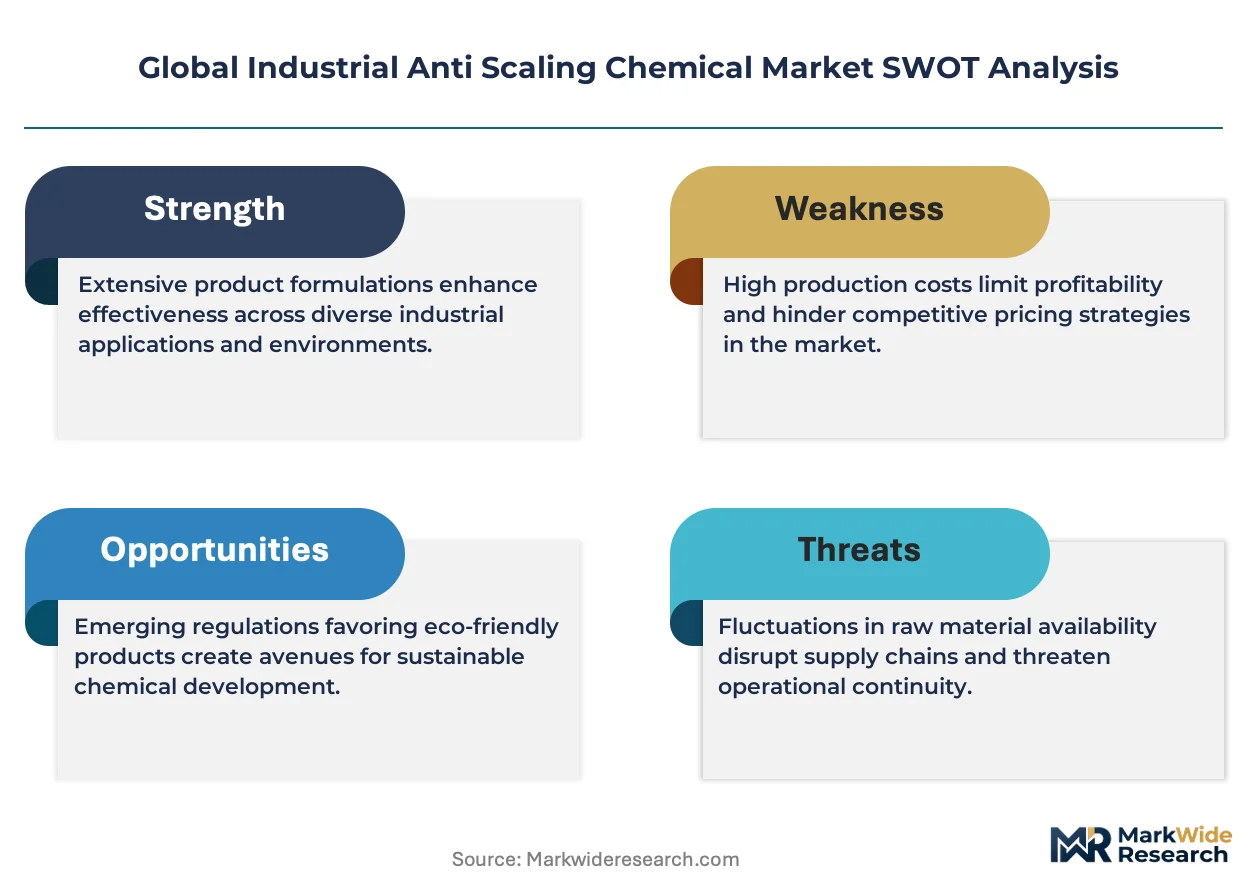
- Raw Material Price Volatility:The cost and availability of key precursors, such as phosphorus-based compounds for phosphonates and monomers for acrylate polymers, are subject to significant price fluctuations, impacting formulator margins and final product pricing.
- Regulatory Restrictions on Chemistries:Substance evaluations under the European Union's REACH framework can lead to the restriction or outright ban of effective, well-established scale inhibitors, forcing costly and time-consuming reformulation efforts.
- Threat from Non-Chemical Alternatives:Physical water treatment technologies, including magnetic, ultrasonic, and electrostatic systems, are marketed as chemical-free substitutes, posing a long-term substitution risk in less demanding applications despite variable performance records.
Strategic Opportunities
- Biodegradable Formulations:Developing and marketing highly effective, readily biodegradable antiscalants creates a significant opportunity to capture share in environmentally sensitive industries like food and beverage processing or in regions with strict effluent regulations.
- Smart Dosing Systems:Integrating chemical formulations with IoT-enabled sensors and AI-driven software allows for real-time monitoring and automated, optimized dosing, creating a value-added service opportunity beyond simple chemical sales.
- Geographic Market Penetration:Industrial growth in Southeast Asian nations presents an untapped opportunity for advanced water treatment solutions as local regulations on industrial wastewater begin to align with more stringent international standards.
Industry Challenges
- Divergent Global Compliance:Formulators face the operational challenge of developing products that can simultaneously satisfy the distinct and evolving regulatory requirements of the US EPA, Europe's ECHA, and China's MEE, increasing R&D complexity.
- Technical Service Skill Gap:A shortage of qualified field technicians who possess the dual expertise in water chemistry and digital control systems limits the effective deployment and management of advanced, service-intensive treatment programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Anti Scaling Chemical Market |
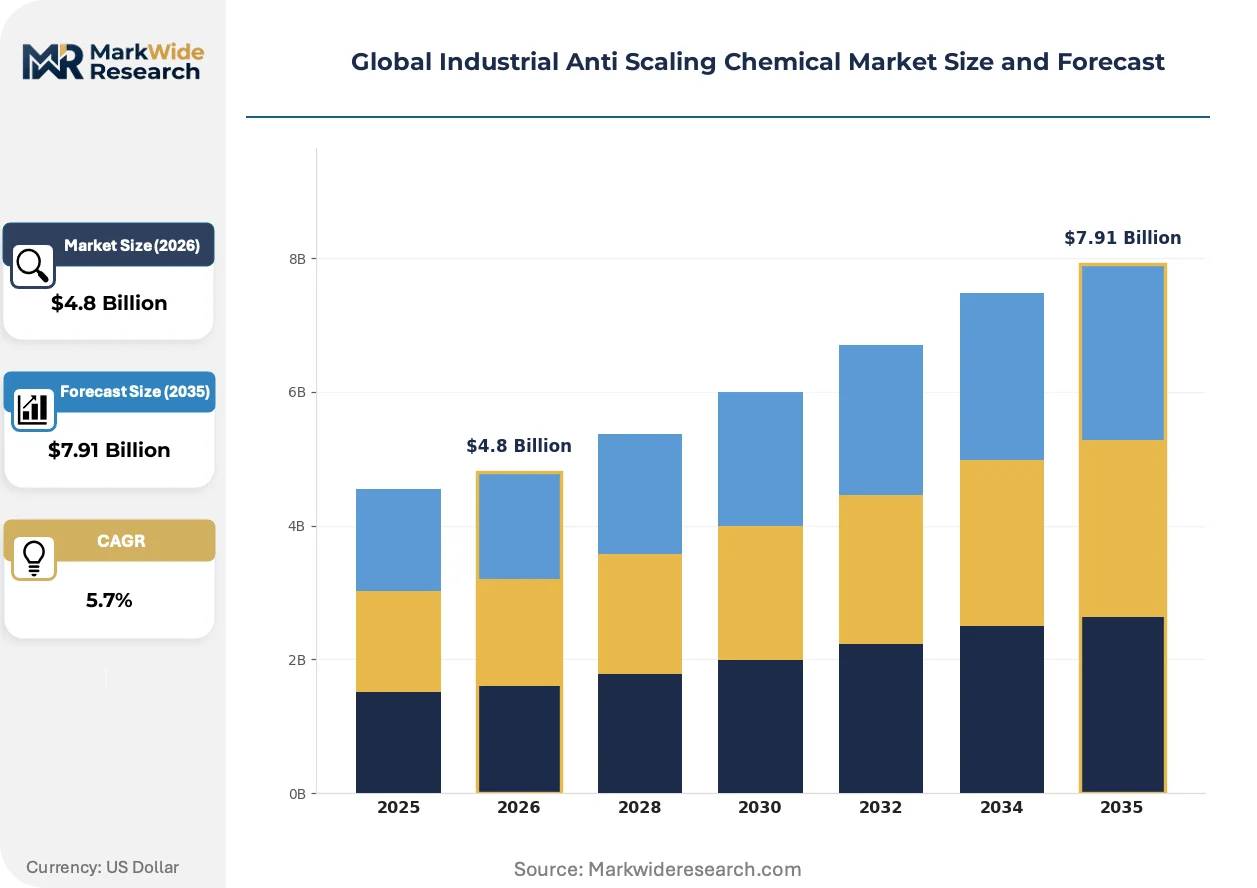
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Chemicals, Inorganic Chemicals, Phosphate Esters, Others Application: Water Treatment, Oil & Gas, Cooling Towers, Boilers End User: Manufacturing, Power Generation, Oil Refining, Food Processing Distribution Channel: Direct Sales, Online Retail, Distributors, Third-party Vendors |
| Companies Covered | Akzo Nobel N.V., American Water Chemicals Inc., Ashland Global Holdings Inc., Avista Technologies Inc., BASF SE, Clariant AG, Dow Inc., Ecolab Inc., Kemira Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Anti Scaling Chemical Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot toward intelligent chemical management, where digital optimization tools and green chemistry principles converge. This shift prioritizes performance and sustainability over sheer volume, altering product design and service delivery models for industrial water systems.
Advanced polymer chemistry, including modified acrylates and novel phosphonate-free molecules, provides superior scale inhibition under high-stress conditions like extreme pH, temperature, or water hardness. Power generation and hydrocarbon processing industries are adopting these specialized formulations to enhance asset reliability and meet stringent environmental permits. This technological specialization is fragmenting the once-monolithic market for commodity antiscalants into a series of distinct, high-performance application niches.
The European Chemicals Agency's (ECHA) substance evaluation process under REACH continues to scrutinize the ecotoxicological profiles of widely used antiscalant chemistries. This regulatory pressure directly influences formulation strategies, accelerating the phase-out of certain phosphonates and polymers in favor of more biodegradable alternatives. The water treatment application segment is most affected, with formulators investing heavily in green chemistry to ensure continued market access within the EU.
A fundamental change in buying behavior sees end-users move from transactional chemical purchases toward performance-based service contracts. This model shifts the focus from cost-per-gallon of chemical to total cost of operation, with providers guaranteeing outcomes like heat exchanger efficiency or reduced downtime. This trend is most prominent in capital-intensive sectors across North America and Europe, where operational continuity is the paramount economic driver.
Global Industrial Anti Scaling Chemical Market Segmentation
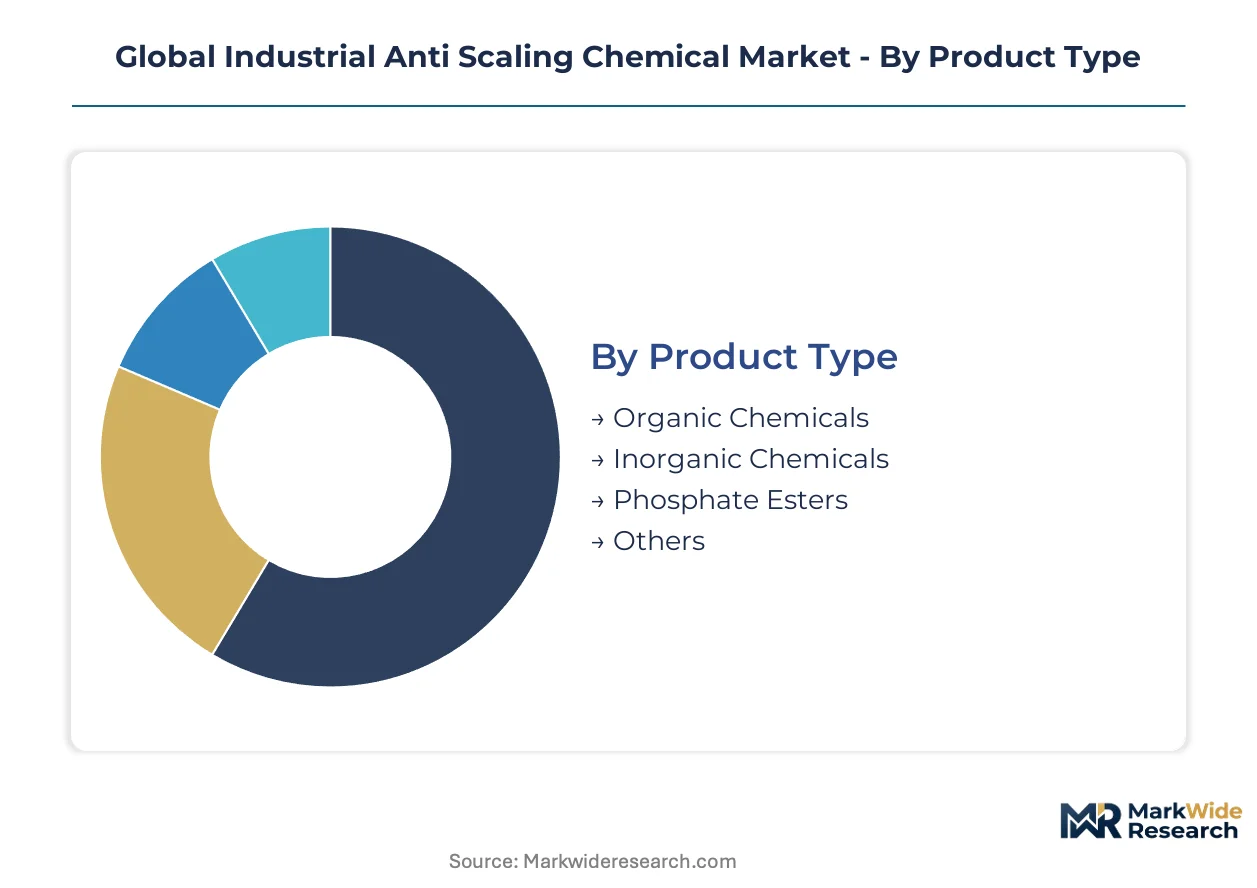
The industrial anti-scaling chemical market segments illuminate diverse product chemistries and application methods. Understanding these divisions helps formulators align development with specific industrial needs. This granular view allows stakeholders to identify high-growth niches and optimize distribution strategies across varied end-user environments.
Product Type:
The product type segmentation reveals how certain chemistries are favored in specific regions, influencing their domestic production versus international trade.
- Organic Chemicals:Organic chemicals, including phosphonates and polyacrylates, are synthetic compounds designed to sequester metal ions and disperse scale-forming minerals. Demand for these versatile formulations concentrates in industrial hubs across China, driven by the country's massive manufacturing and energy infrastructure expansion.
- Phosphate Esters:Phosphate esters are organophosphorus compounds providing strong scale inhibition and corrosion protection, often used in severe process conditions. Their application is significant in European water treatment systems, where their proven performance balances against evolving regulatory scrutiny under REACH.
- Inorganic Chemicals:Inorganic chemicals like silicates and polyphosphates offer cost-effective scale control, particularly in less demanding industrial water systems.
- Others:This category encompasses emerging chemistries and specialized blends, including phosphonate-free and biodegradable alternatives, addressing niche environmental requirements.
Organic Chemicals commands the established base. The steepest expansion runs through Phosphate Esters.
Application:
Application categories highlight the varying volumes of anti-scaling agents consumed across different industrial processes.
- Water Treatment:Water treatment applications involve preventing scale deposition in industrial water systems, ensuring optimal performance and longevity of equipment. This segment sees substantial demand across North America, driven by the need for continuous operational uptime in capital-intensive sectors.
- Cooling Towers:Cooling towers require specialized anti-scaling chemicals to maintain heat transfer efficiency and prevent biofouling in recirculating water systems. Stricter water quality mandates in India compel power generation and chemical manufacturing to adopt more effective anti-scaling treatments for these critical assets.
- Oil & Gas:The oil and gas sector utilizes anti-scaling chemicals to prevent mineral buildup in pipelines and production equipment, maintaining flow assurance.
- Boilers:Boilers depend on anti-scalants to protect heat exchange surfaces from mineral deposits, preserving thermal efficiency and preventing equipment failure.
Water Treatment accounts for the largest volume. Cooling Towers are expanding most quickly.
End User:
End-user segments reflect how specific industry requirements shape the demand for anti-scaling chemical formulations and service models.
- Power Generation:The power generation sector requires robust anti-scaling solutions for boilers, cooling towers, and heat exchangers to ensure continuous operation and prevent efficiency losses. Investment in new energy infrastructure across Southeast Asia creates significant opportunities for advanced water treatment solutions in this critical industry.
- Manufacturing:Manufacturing industries, including pulp and paper, utilize anti-scalants to protect process equipment and maintain product quality in water-intensive operations. China's expanding industrial base, coupled with MEE directives, drives substantial demand for effective and compliant anti-scaling treatments in this segment.
- Oil Refining:Oil refining operations employ anti-scaling agents to prevent fouling in heat exchangers and distillation units, maintaining throughput and process integrity.
- Food Processing:Food processing facilities demand highly effective and often biodegradable anti-scaling chemicals for water systems, adhering to strict hygiene and environmental standards.
Power Generation represents a foundational segment. Manufacturing demonstrates significant growth potential.
Distribution Channel:
Distribution channels illustrate the maturity and complexity of how anti-scaling chemicals reach their diverse industrial customers.
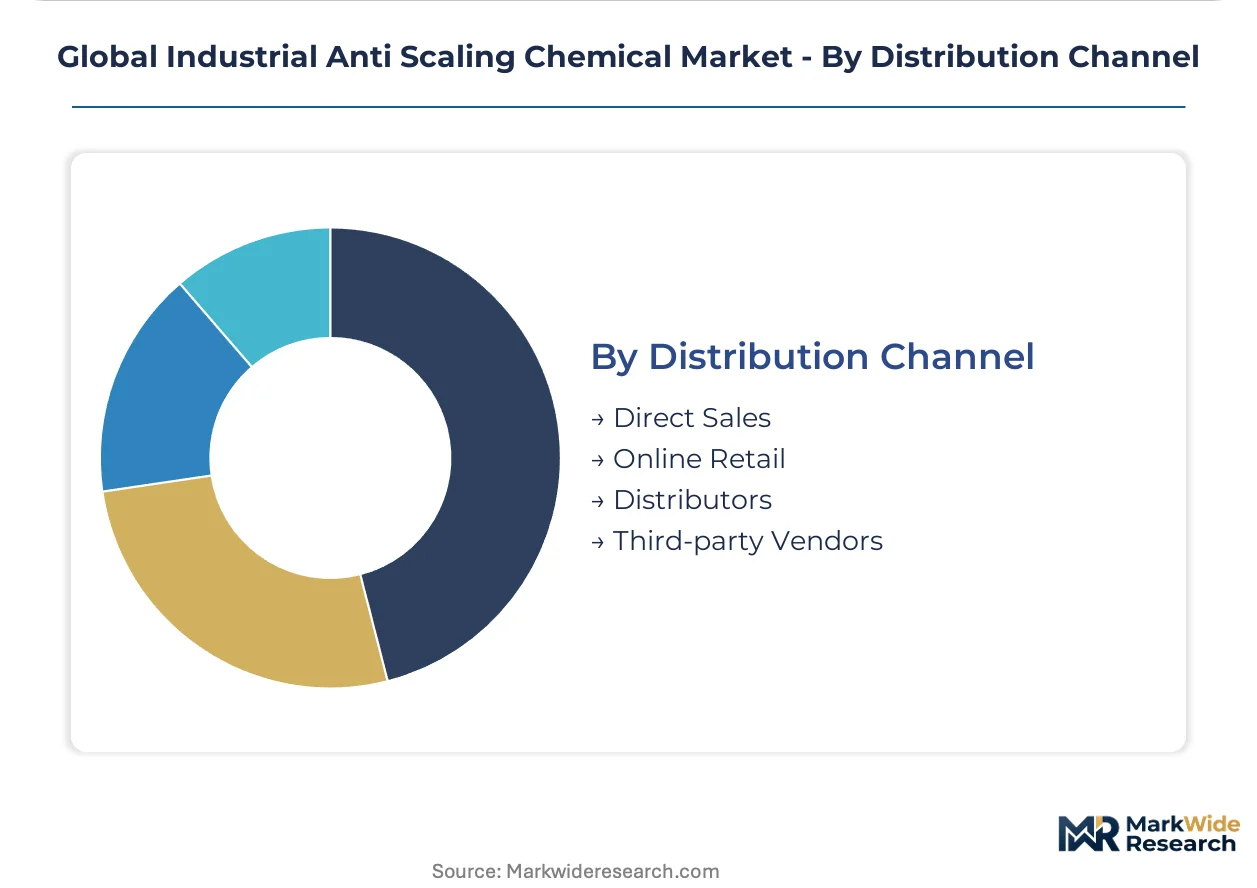
- Direct Sales:Direct sales involve chemical manufacturers selling directly to large industrial end-users, often accompanied by technical support and customized service contracts. This channel is prevalent in North America and Europe, where performance-based service contracts are becoming the preferred buying behavior for capital-intensive sectors.
- Distributors:Distributors provide a crucial link for smaller and medium-sized enterprises, offering localized inventory, logistics, and technical assistance for anti-scaling products. This model is essential for market penetration in fragmented industrial landscapes, particularly across India and emerging Southeast Asian markets.
- Online Retail:Online retail platforms are emerging for standardized anti-scaling formulations, offering convenience and broader access for smaller volume purchases.
- Third-party Vendors:Third-party vendors integrate chemical supply with broader water management services, providing comprehensive solutions to industrial clients globally.
Direct Sales remains a primary route. Online Retail is gaining traction for specialized products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial anti-scaling chemical demand from China heavily influences global supply chains, particularly for water-intensive manufacturing and power generation applications. This demand drives regional and international trade flows of specialized chemical formulations. Regulatory bodies across different regions impose varying environmental and performance standards, shaping regional product development.
China
Massive investment in manufacturing and energy infrastructure drives demand for anti-scaling chemicals in China. Ministry of Ecology and Environment (MEE) directives on industrial water quality compel operators to adopt effective treatments. The Yangtze River Delta region, with its dense industrial clusters, demonstrates significant consumption of anti-scaling agents.
United States
North American capital-intensive sectors require robust anti-scaling solutions to maintain operational uptime and equipment longevity. The US Environmental Protection Agency's (EPA) effluent limitation guidelines influence the formulation chemistry of discharged water. Chemical processing facilities along the Gulf Coast represent a concentrated demand center for water treatment solutions.
Germany
European water treatment systems utilize anti-scaling chemicals for proven performance in severe process conditions. The European Chemicals Agency's (ECHA) substance evaluations under REACH directly influence the availability and use of certain chemistries. The Rhine-Ruhr industrial region, a hub for heavy industry, sees consistent demand for high-efficacy antiscalants.
India
Power generation and chemical manufacturing in India require effective anti-scaling treatments for critical assets like cooling towers and boilers. Stricter water quality mandates compel operators to adopt compliant solutions. Gujarat's chemical industrial zones and power plants across the country are key end-users for these products.
Vietnam
Industrial growth in Southeast Asian nations, including Vietnam, presents an opportunity for advanced water treatment solutions. Local regulations on industrial wastewater are beginning to align with more stringent international standards. Manufacturing expansion around Ho Chi Minh City necessitates effective anti-scaling agents for process water systems.
Global Industrial Anti Scaling Chemical Market Key Industry Players
Player mix skews toward large, diversified chemical manufacturers and specialized water treatment solution providers. The market exhibits a tiered structure, with global leaders offering broad portfolios and niche players focusing on high-performance formulations. This creates archetypes of integrated solution providers, specialized chemistry innovators, and regional commodity suppliers. Companies pursue strategic partnerships for technology co-development and geographic expansion into industrializing regions.
Within the diversified portfolio archetype, BASF SE, a German chemical giant, represents a broad market presence across multiple performance tiers. Ecolab Inc., a US-based entity, exemplifies the integrated solution provider, leveraging its service-led model to capture value-added segments. Kemira Oyj, a Finnish corporation, sits within the specialized chemistry innovator segment, focusing on high-efficacy solutions for water-intensive industries like pulp and paper.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| American Water Chemicals Inc. |
| Ashland Global Holdings Inc. |
| Avista Technologies Inc. |
| BASF SE |
| Clariant AG |
| Dow Inc. |
| Ecolab Inc. |
| Kemira Oyj |
| Others |
Cost & Logistics Intelligence
Biodegradable formulations substituting traditional phosphonate chemistries are reshaping supply chains, shifting production investment towards green chemistry hubs and influencing pricing structures based on environmental compliance rather than pure efficacy. This dynamic recalibrates pricing economics globally.
Pricing Analysis
Next-generation green chemistry formulations command a premium over established phosphonate-based products, reflecting higher R&D costs and environmental compliance. Pricing predominantly follows a contract-based long-term offtake model, often bundled with value-added services. Performance efficacy under high-stress conditions and customization levels drive price differentiation. Raw material price volatility and regulatory restrictions on certain chemistries exert pricing pressure, while buyers seeking specialized, high-performance formulations exhibit lower price sensitivity than those focused on bulk commodity pricing.
Supply Chain Analysis
China and India anchor the global supply of commodity organic anti-scaling chemicals, drawing heavily from localized production of precursors. Germany specializes in advanced polymer chemistries and phosphate esters, catering to high-efficacy solution demand. The supply chain relies on phosphorus-based compounds for phosphonates and monomers for acrylate polymers. Raw material price volatility and evolving regulatory restrictions under REACH represent structural risks. Distribution runs through direct sales channels for large industrial end-users and localized distributors for smaller enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global industrial anti-scaling chemical market is in an early-cycle expansion phase, driven by massive investments in manufacturing and energy infrastructure across industrial hubs in China and India. This tailwind accelerates the adoption of advanced water treatment solutions.
For Market Incumbents: Consolidate market share by aggressively investing in R&D for biodegradable and phosphonate-free formulations, preempting future regulatory restrictions from bodies like ECHA. Deepen service-led models, such as Ecolab's, to capture value-added segments and reinforce customer loyalty against commodity pricing pressures. Expand technical service capabilities to manage advanced dosing systems, leveraging existing customer relationships. This mitigates the threat posed by tightening environmental compliance and shifting buyer behavior.
For New Entrants and Emerging Players: Differentiate on technology integration by offering smart dosing systems that combine IoT-enabled sensors with AI-driven software for real-time optimization. Target underpenetrated industrial growth markets in Southeast Asian nations, such as Vietnam, where local regulations are tightening. Focus on high-efficacy, specialized solutions for niche water-intensive industries like food processing, emphasizing biodegradable formulations. This approach leverages environmental compliance as a competitive advantage.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established, diversified chemical manufacturers seeking to divest non-core anti-scaling divisions, offering carve-out opportunities. The market maintains long-term viability due to the essential role of anti-scalants in industrial operational uptime and environmental compliance. Target specialized chemistry innovators with strong R&D pipelines for green formulations or integrated solution providers with robust service-led models. Increased adoption of performance-based service contracts signals market maturity and value capture potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry R&D Investment | Accelerates development of biodegradable formulations meeting strict global environmental regulations. |
| IoT-Enabled Dosing System Integration | Enhances operational efficiency and offers value-added service beyond chemical sales. |
| Geographic Market Penetration | Captures new demand from industrializing regions with evolving water treatment standards. |
| Vertical Integration into Key Precursors | Mitigates raw material price volatility and secures supply for critical chemistries. |
| Performance-Based Service Contract Expansion | Aligns provider incentives with customer outcomes, reducing total cost of operation for end-users. |
Research Approach
Desk research of regulatory filings, trade association reports, and company financial statements preceded structured interviews with plant managers, R&D directors, procurement leads, and environmental compliance officers. This approach combined primary insights with secondary validation, ensuring a robust data foundation. Bottom-up data aggregation from specific industrial applications was triangulated with top-down market sizing for accuracy.
Variance decomposition isolated the impact of key drivers and restraints on market growth across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected future growth drivers. Industrial infrastructure investment rates and evolving water reuse mandates served as critical forecast inputs.
The analysis sits within stated boundaries; outcomes outside unforeseen geopolitical events or abrupt shifts in raw material supply would require recalibration. Forecasts reflect assumptions regarding technological evolution and regulatory stability. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
South Africa Lime Market
Industrial Chemicals
Europe Modified Bitumen Market
Industrial Chemicals
Babassu Oil Market
Industrial Chemicals
1,3-Propanediol (PDO) Market