
 FCCL Coating Machine Market | 2026-2036
FCCL Coating Machine Market Size, Share, and Industry Trends Forecast 2026-2036
FCCL Coating Machine Market Insights
Premium precision coating systems for sub-10-micron dielectric layers is decoupling from commodity roll-to-roll equipment serving standard PCB applications. Hitachi High-Tech Corporation leverages its electron beam lithography heritage to anchor high-end semiconductor coating lines in Japan. Hirano Tecseed Co., Ltd. competes on thermal management expertise for continuous web processing. Screen Holdings Co., Ltd. dominates display coating with inkjet deposition systems that handle OLED encapsulation layers.
FCCL coating machines deposit uniform polymer, adhesive, or metal layers onto flexible copper clad laminates using roll-to-roll, screen printing, or spin coating methods, achieving thickness tolerances below ±3% for multilayer flex circuit fabrication. The equipment serves electronics manufacturers producing smartphones, electric vehicles, and medical imaging devices where bend radius requirements now reach sub-2-millimeter specifications. Roll-to-roll technology leads volume throughput for flexible display and RFID tag production, while spin coating commands premium positioning in semiconductor wafer-level packaging where planarization uniformity dictates yield. Digital printing emerges fastest in smart card personalization and prototype runs, though screen printing retains margin pools in thick-film conductor deposition for automotive sensor modules.
Japan's METI enforces JIS standards for flame retardancy and dimensional stability in electronic substrate materials, directly influencing coating machine calibration protocols for export-bound production lines. The EU REACH regulation restricts halogenated flame retardants in imported flex circuits, compelling European automotive suppliers to verify coating chemistry compliance through supplier audits. China's GB standards and MIIT directives on dual carbon goals pressure domestic equipment makers to reduce solvent emissions in coating processes. Stakeholders must monitor how substrate thinning below 12 micrometers reshapes tension control specifications and whether regional carbon border adjustments alter equipment sourcing decisions.
Market Dynamics
Substrate thinning below 12 micrometers is forcing wholesale recalibration of tension control systems and web handling architectures across coating machine portfolios. Equipment makers must now guarantee defect-free processing of materials with mechanical properties approaching tissue paper while maintaining throughput economics viable for consumer electronics volumes.
Growth Catalysts
- Flexible Display Investment:South Korean panel producers are expanding roll-to-roll coating capacity for foldable smartphone substrates. Domestic equipment suppliers capture follow-on service contracts.
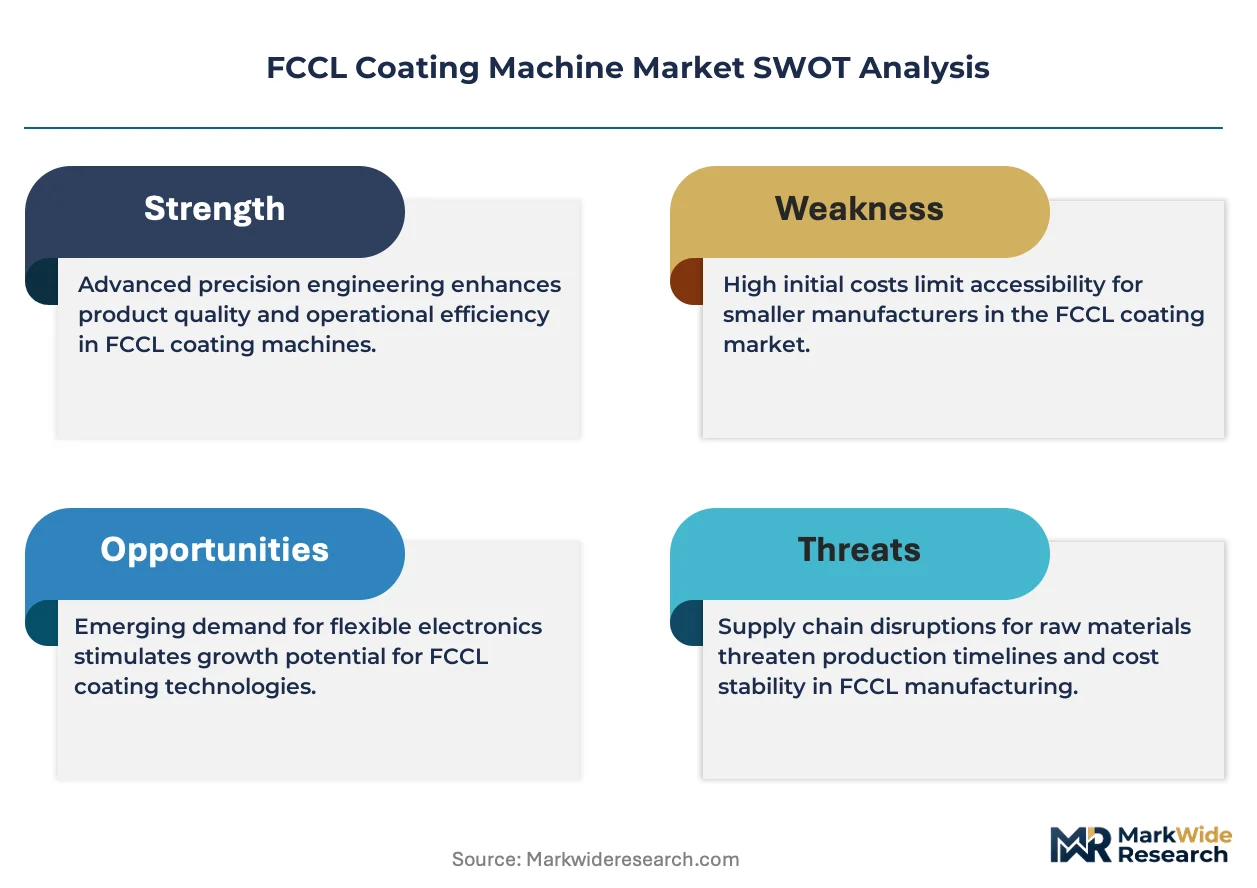
- EU REACH Compliance:Restrictions on halogenated flame retardants in imported flex circuits drive European automotive suppliers to audit coating chemistry. Verified equipment lines gain preferred vendor status.
- Dual Carbon Mandates:China's MIIT directives pressure domestic manufacturers to reduce solvent emissions. Low-VOC coating architectures qualify for state procurement preference.
Market Restraints
- Copper Foil Volatility:Electrodeposited copper substrate costs fluctuate with London Metal Exchange pricing. Machine buyers defer capital commitments during raw material spikes.
- Japanese Component Concentration:Precision tension rollers and edge position sensors source predominantly from Nagoya and Osaka manufacturing clusters. Geopolitical friction threatens spare parts availability.
- Thickness Uniformity Ceiling:Current roll-to-roll architectures struggle to hold ±2% tolerance below 8-micron dielectric layers. Semiconductor packaging applications remain captive to spin coating.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme subsidies for mobile phone and component production create first-mover advantage for coating equipment establishing local service presence.
- Solid-State Battery Interface Layers:Ceramic-polymer composite deposition for lithium-metal anode protection represents adjacent application with similar precision requirements.
- Digital Print Convergence:Integration of inkjet heads with traditional roll-to-roll webs enables rapid prototyping and lot-size-one production for medical device flex circuits.
Industry Challenges
- Mechatronics Talent Scarcity:Simultaneous mastery of web transport dynamics, thermal management, and coating rheology resides in aging Japanese and German engineering cohorts. Knowledge transfer mechanisms remain underdeveloped.
- Cleanroom Integration Complexity:Class 1000 compatibility requirements for semiconductor-adjacent applications extend installation timelines. Site acceptance testing protocols consume 20-30% of project duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FCCL Coating Machine Market |
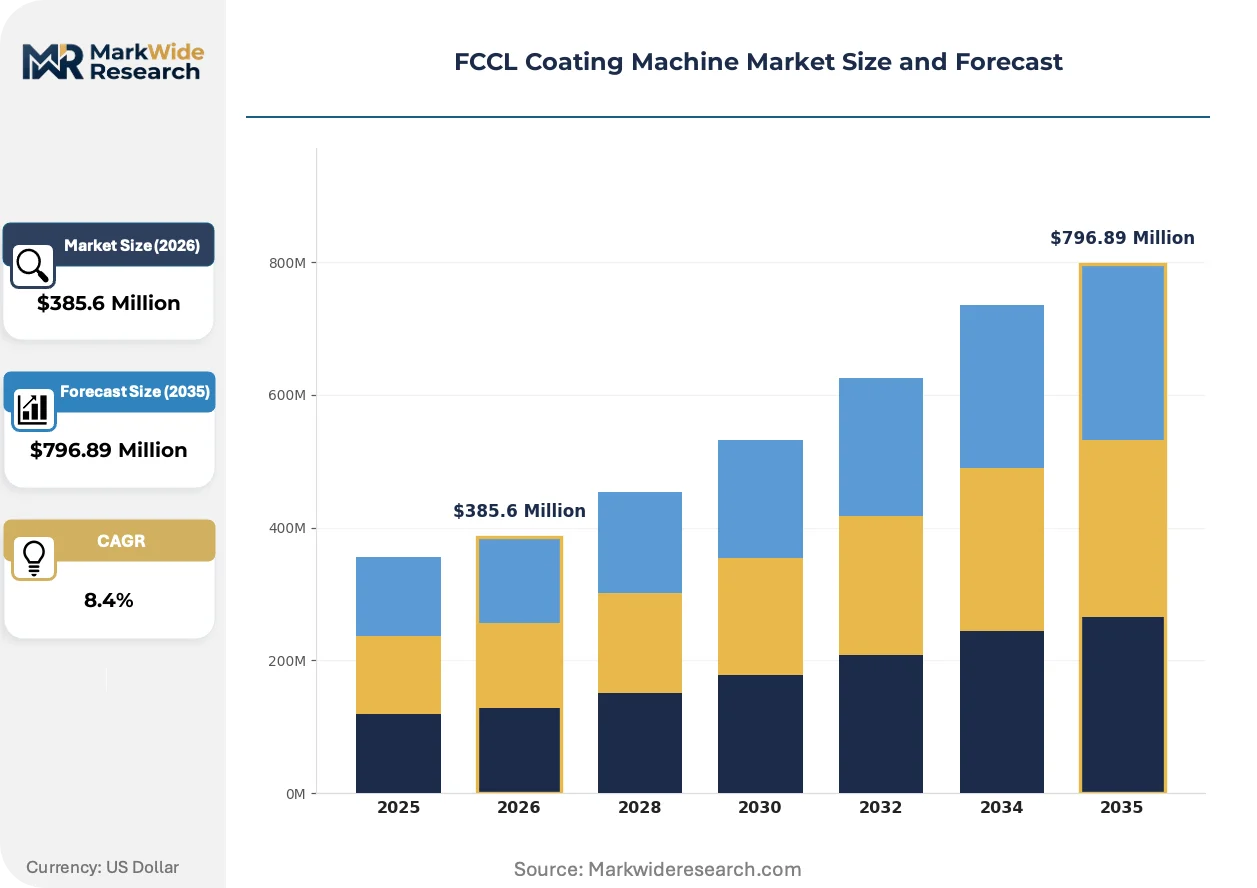
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductor Coating, Solar Cell Coating, Display Coating, PCB Coating Technology: Roll-to-Roll, Digital Printing, Screen Printing, Spin Coating End User: Electronics Manufacturers, Automotive Suppliers, Aerospace Companies, Medical Device Manufacturers Application: Flexible Displays, Smart Cards, RFID Tags, Photovoltaics |
| Companies Covered | Hitachi High-Tech Corporation, Hirano Tecseed Co., Ltd., Screen Holdings Co., Ltd., Mycronic AB, DN Co., Ltd., KISCO Ltd., Sung An Machinery Co., Ltd., Shenzhen Capchem Technology Co., Ltd., IPCO Germany GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FCCL Coating Machine Market Trends and Innovations
Process control architectures are migrating from reactive feedback loops to predictive models trained on real-time web tension and coating weight data. This shift compresses defect response times and enables statistical process control integration.
In-situ spectroscopic monitoring is absorbing quality assurance functions previously handled by offline metrology stations. Smartphone display manufacturers in South Korea deploy these systems for 100% inspection of OLED encapsulation layers. The technology is absorbing capital budgets that previously funded separate laboratory equipment, consolidating vendor relationships.
Japan's METI has tightened JIS flame retardancy standards for electronic substrates exported under bilateral trade agreements. Coating machine calibration protocols now require documented verification of additive dispersion uniformity. Equipment makers serving Toyota and Honda automotive sensor supply chains have re-engineered thermal cure profiles to meet the revised specifications.
After-sales service contracts are unbundling from initial equipment sales as buyers seek operational expenditure flexibility. Korean panel producers now procure coating machines on capital leases while purchasing predictive maintenance subscriptions separately. This bifurcation is most pronounced in Gyeonggi Province manufacturing corridors where equipment utilization rates exceed 85%.
FCCL Coating Machine Market Segmentation
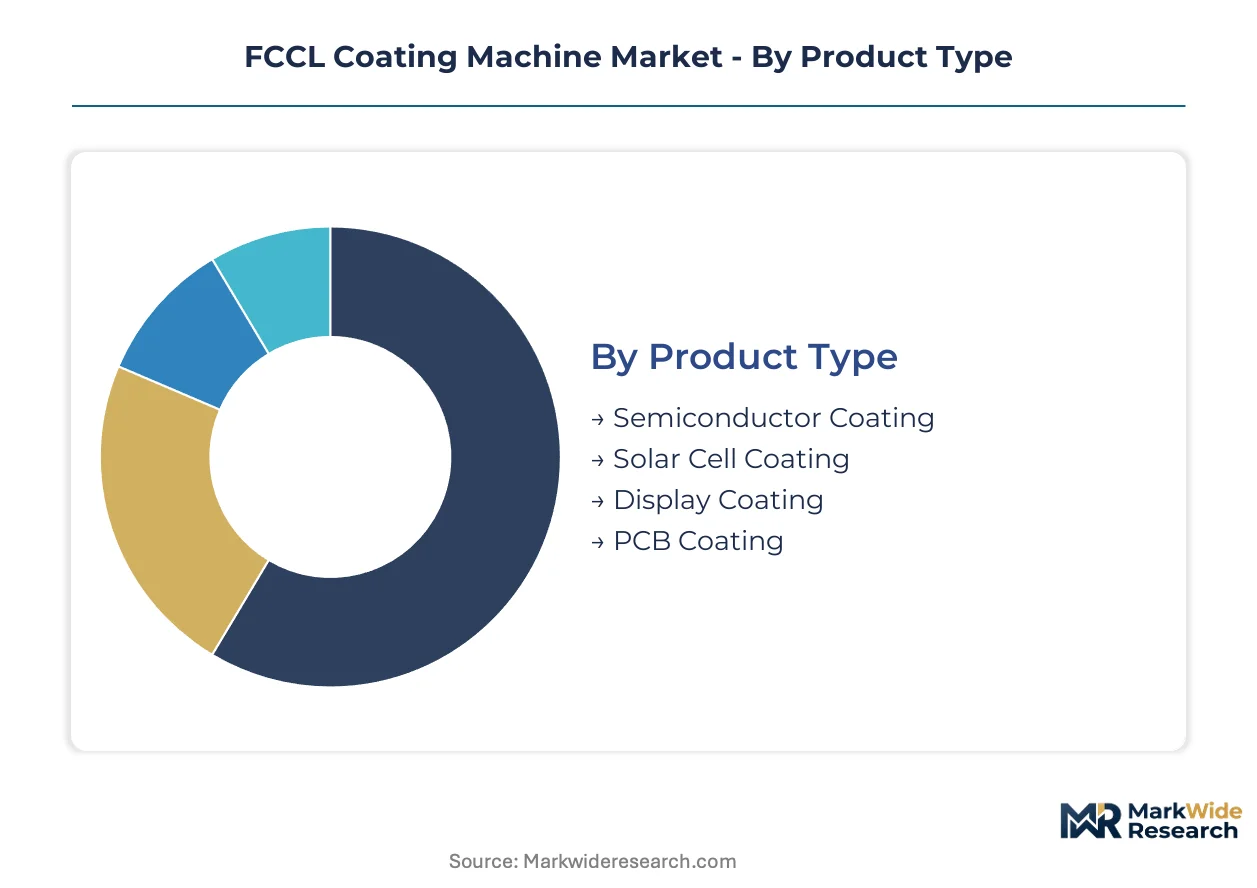
FCCL coating machine buyers face divergent capital requirements depending on whether they serve semiconductor packaging or commodity PCB fabrication. Segmentation reveals where equipment makers capture premium pricing versus competing on throughput economics.
Product Type:
Capital intensity peaks in semiconductor-grade systems requiring sub-micron precision, while PCB coating operates at substantially lower equipment price points.
- Semiconductor Coating:Wafer-level packaging demands vacuum-compatible chambers and electrostatic chuck integration. South Korean memory manufacturers anchor demand as advanced packaging nodes proliferate.
- Display Coating:Roll-to-roll architectures for OLED encapsulation require tension control systems handling 12-micron polyimide webs. Samsung Display and LG Display operations in Gyeonggi Province concentrate procurement volume.
- PCB Coating:Standard flex circuit production utilizes commodity roll-to-roll equipment with solvent-based adhesive deposition.
- Solar Cell Coating:Perovskite and heterojunction cell manufacturing drives demand for atmospheric-pressure slot-die coating heads.
Most installed capacity flows through PCB Coating. Expansion is steepest in Display Coating.
Technology:
Process selection determines both upfront equipment cost and ongoing consumables expenditure, with digital printing disrupting traditional screen printing economics in short-run applications.
- Roll-to-Roll:Continuous web processing achieves throughput exceeding 100 meters per minute for flexible display substrates. Japanese tension roller suppliers in Nagoya and Osaka manufacturing clusters constrain capacity scaling.
- Spin Coating:Rotational deposition delivers thickness uniformity below ±1% for semiconductor wafer-level packaging. The technology commands premium positioning where planarization dictates yield.
- Screen Printing:Thick-film conductor deposition for automotive sensor modules retains margin pools despite slower throughput.
- Digital Printing:Piezoelectric inkjet heads enable lot-size-one production without photomask costs.
Roll-to-Roll dominates current installed base. Digital Printing is climbing the fastest as medical device manufacturers adopt rapid prototyping workflows.
End User:
Customer type shapes procurement patterns, with automotive suppliers emphasizing audit trails and medical device manufacturers demanding validation documentation.
- Electronics Manufacturers:Smartphone and tablet producers in South Korea and China drive volume procurement of display coating lines. Foldable device ramp-ups are accelerating capital deployment cycles.
- Automotive Suppliers:Flex circuit integration into EV battery management systems and sensor modules requires flame-retardant coating verification under EU REACH protocols.
- Medical Device Manufacturers:Implantable device applications demand biocompatible adhesive layers with full batch traceability.
- Aerospace Companies:Satellite and avionics applications prioritize radiation-hardened substrate coatings with extended thermal cycling durability.
Electronics Manufacturers command the largest installed equipment base. Medical Device Manufacturers are gaining share fastest as diagnostic device miniaturization accelerates.
Application:
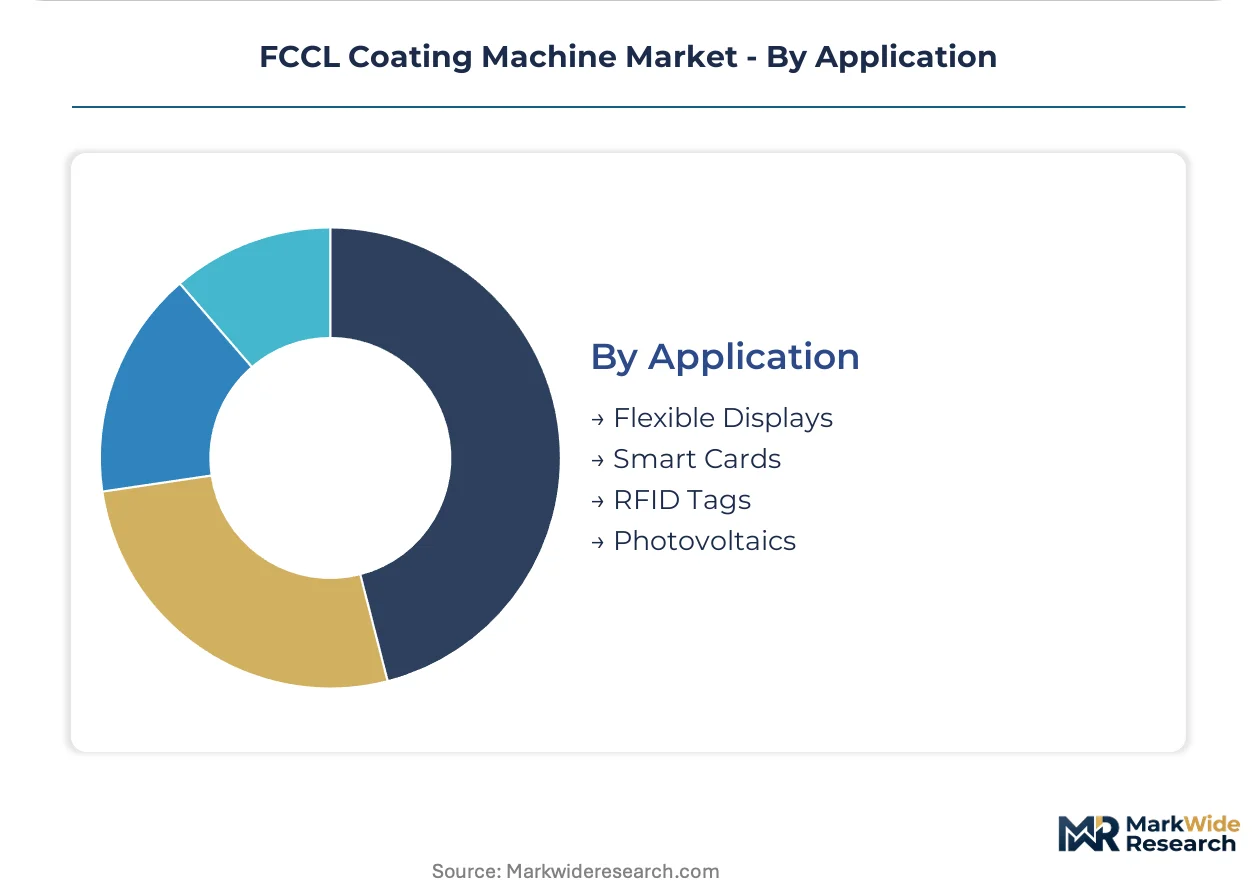
Application focus determines coating thickness specifications and substrate handling requirements, with flexible displays pushing mechanical property boundaries.
- Flexible Displays:Sub-2-millimeter bend radius specifications require polymer dielectric layers below 10 microns. South Korean panel producers are expanding Gyeonggi Province capacity for foldable smartphone substrates.
- RFID Tags:High-volume antenna printing for supply chain tracking utilizes screen printing with silver nanoparticle inks.
- Smart Cards:Embedded chip modules demand precision adhesive coating for contact pad reliability.
- Photovoltaics:Flexible solar cell manufacturing requires barrier coating for moisture ingress protection.
RFID Tags represent the largest current application by unit volume. Flexible Displays show the steepest expansion trajectory as foldable device penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea commands premium equipment procurement volumes for flexible display manufacturing, while China scales domestic coating capacity under import substitution mandates. Japan retains precision component supply chain dominance through Nagoya and Osaka manufacturing clusters.
South Korea
Samsung Display and LG Display drive roll-to-roll coating machine deployment for foldable smartphone substrates. The Ministry of Trade, Industry and Energy (MOTIE) channels semiconductor equipment subsidies toward domestic panel supply chain localization. Gyeonggi Province manufacturing corridors concentrate equipment utilization rates exceeding 85 percent.
China
Flexible circuit producers in the Yangtze River Delta and Pearl River Delta expand coating capacity for electric vehicle battery management systems. MIIT dual carbon directives pressure equipment makers to reduce solvent emissions in coating processes. Shenzhen and Dongguan industrial zones attract domestic equipment assembly operations serving consumer electronics brands.
Japan
Precision tension roller and edge position sensor manufacturers in Nagoya and Osaka supply critical components to global coating machine builders. METI enforces JIS flame retardancy standards for electronic substrate materials exported under bilateral trade agreements. Chubu region engineering cohorts retain scarce mechatronics expertise spanning web transport dynamics and thermal management.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg audit coating chemistry compliance under EU REACH restrictions on halogenated flame retardants. The KBA (Kraftfahrt-Bundesamt) oversees type approval processes for flex circuit integration into EV sensor modules. Stuttgart and Munich industrial corridors concentrate equipment procurement for thick-film conductor deposition.
United States
Medical device manufacturers in Minnesota and Massachusetts demand biocompatible adhesive coating with full batch traceability for implantable applications. FDA quality system regulations extend validation documentation requirements to coating equipment qualification. Greater Boston and Twin Cities metro areas anchor diagnostic device miniaturization programs.
FCCL Coating Machine Market Competitive Landscape
Top-tier vendors anchor precision semiconductor and display coating segments, while mid-tier fabricators compete on throughput economics for standard PCB applications. Japanese and South Korean equipment makers concentrate in high-tolerance roll-to-roll architectures, whereas European specialists dominate thermal management and cleanroom integration. Strategic archetypes include precision component suppliers, integrated system builders, and regional service providers. Competitive moves center on predictive maintenance subscription unbundling and local service presence establishment in emerging manufacturing corridors.
Within the precision-tier vector, Hitachi High-Tech Corporation and Screen Holdings Co., Ltd. occupy positions reflecting electron beam lithography heritage and inkjet deposition specialization respectively. Hirano Tecseed Co., Ltd. exemplifies thermal management expertise for continuous web processing. These Japanese entities represent distinct competitive archetypes: lithography-anchored semiconductor coating, display-focused inkjet encapsulation, and web-handling thermal engineering. South Korea's Sung An Machinery Co., Ltd. sits within the regional equipment supply tier serving domestic panel producers with follow-on service contracts.
| Leading Market Players |
|---|
| Hitachi High-Tech Corporation |
| Hirano Tecseed Co., Ltd. |
| Screen Holdings Co., Ltd. |
| Mycronic AB |
| DN Co., Ltd. |
| KISCO Ltd. |
| Sung An Machinery Co., Ltd. |
| Shenzhen Capchem Technology Co., Ltd. |
| IPCO Germany GmbH |
| Others |
Pricing and Supply Chain Analysis
China's MIIT dual carbon directives gate qualified supply and premium-tier pricing access, as equipment lines demonstrating solvent emission reductions capture state procurement preference while non-compliant fabricators face margin compression in standard PCB segments.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for display coating systems as Samsung Display and LG Display expand Gyeonggi Province manufacturing corridors. Three-tier pricing structure across precision semiconductor, display-grade roll-to-roll, and commodity PCB equipment segments stratifies by certification tier and after-sales bundling. Cost compression in standard flex circuit equipment intensifies because Chinese domestic suppliers scale assembly operations in Shenzhen and Dongguan. Automotive suppliers under EU REACH audit protocols prove least price-sensitive, while commodity PCB fabricators in Southeast Asia exhibit highest sensitivity to capital expenditure timing.
Supply Chain Analysis
ISO 14644-1 Class 1000 cleanroom certification and JIS flame retardancy verification gate supplier qualification for semiconductor-adjacent and automotive export applications. Precision tension rollers and edge position sensors concentrate in Japan's Nagoya and Osaka manufacturing clusters, while complete system assembly scales in South Korea and China. Copper foil electrodeposited substrates, piezoelectric inkjet heads, and ceramic-polymer composite feedstocks anchor raw material dependencies. Single-source vulnerability in Japanese precision component supply threatens equipment delivery timelines during geopolitical friction. Distribution runs through direct OEM relationships for premium tiers and regional distributor networks for standard PCB equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as substrate thinning below 12 micrometers forces specification upgrades toward sub-10-micron dielectric precision that only qualified equipment lines can deliver.
For Market Incumbents: To counter mechatronics talent scarcity in aging Japanese and German engineering cohorts, anchor knowledge transfer programs with technical universities in Gyeonggi Province and Chubu region. Backward integration into precision tension roller manufacturing reduces Nagoya and Osaka supplier concentration risk. Predictive maintenance subscription unbundling defends service revenue streams against capital lease pricing pressure from Korean panel producers. For New Entrants and Emerging Players: India's PLI scheme subsidies for mobile phone and component production open a window for establishing local service presence ahead of multinational equipment makers. Solid-state battery interface layer coating represents the most penetrable adjacent application with similar precision requirements to semiconductor packaging. Rapid prototyping workflows for medical device flex circuits offer a go-to-market angle through digital print convergence with traditional roll-to-roll webs. For Investors and Strategic Acquirers: Roll-up economics work for regional service providers with established spare parts logistics because equipment utilization rates exceeding 85 percent in Gyeonggi Province manufacturing corridors generate predictable aftermarket revenue streams. Target mid-tier fabricators with thermal management expertise for continuous web processing and demonstrated cleanroom integration capabilities. Watch for inflection when substrate thinning specifications breach 8-micron tolerance ceilings currently limiting roll-to-roll architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Unbundling | Korean panel producers now procure coating machines on capital leases while purchasing maintenance separately. |
| Cleanroom Integration Partnership | Class 1000 compatibility requirements extend installation timelines and consume substantial project duration. |
| Regional Service Presence Establishment | Indian PLI scheme subsidies create first-mover advantage for coating equipment establishing local operations. |
| Digital Print Convergence Development | Piezoelectric inkjet heads enable rapid prototyping and lot-size-one production for medical device flex circuits. |
| Precision Component Backward Integration | In-house production of tension rollers reduces dependency on Nagoya and Osaka manufacturing clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating equipment engineering directors, electronics manufacturer procurement leads, automotive supplier quality audit managers, and cleanroom integration specialists with secondary validation against METI JIS standard filings, MIIT dual carbon directive disclosures, EU REACH restriction updates, and SEC 10-K equipment maker financials. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Segment-weighted modeling across product type, technology, end user, and application dimensions drove value projections across the analysis window. CAGRs derived from historical equipment shipment patterns and forward-looking capital expenditure announcements by Samsung Display, LG Display, and Yangtze River Delta flex circuit producers. Thickness tolerance specifications and substrate handling requirements informed technology adoption curves.
Revisions become necessary when copper foil London Metal Exchange pricing volatility triggers capital commitment deferrals or when geopolitical friction disrupts Japanese precision component supply chains. Forecasts reflect documented assumptions on foldable smartphone penetration and electric vehicle battery management system integration rates. A model refresh is warranted upon material change in MIIT emission reduction mandates or EU REACH flame retardant restriction scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
E-Fluids Market