
 Babassu Oil Market | 2026-2036
Babassu Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Babassu Oil Market Outlook
Brazil is rewriting competitive dynamics in babassu oil through cooperative-led sustainable harvesting networks across Maranhão and Piauí. Citróleo anchors its position through deep vertical ties to Amazonian extraction communities. Natura & Co. differentiates via certified organic supply chains tied to biodiversity commitments.
Babassu oil is a non-drying lipid extracted from Attalea speciosa kernels, containing roughly 44% lauric acid and 15% myristic acid with a melting point near 24°C, making it valuable for stable emulsion systems in cosmetics and food processing. Refined babassu oil dominates value capture due to consistent quality specifications demanded by multinational personal care manufacturers, while organic babassu oil commands premium positioning through Ecocert and USDA Organic certification requirements. Fractionated babassu oil represents the fastest-growing product type as cosmetic formulators seek lighter, non-comedogenic alternatives to coconut-derived medium-chain triglycerides.
Brazil's ANVISA governs cosmetic ingredient safety assessments, while the European Union's REACH framework and ECHA classification requirements constrain market access for unrefined crude grades with variable contaminant profiles. The U.S. FDA's GRAS designation for food applications opens distinct channel opportunities separate from cosmetic regulatory pathways. Stakeholders must monitor how emerging EU deforestation-free supply chain regulations reshape traceability requirements for Amazon-sourced botanical lipids.
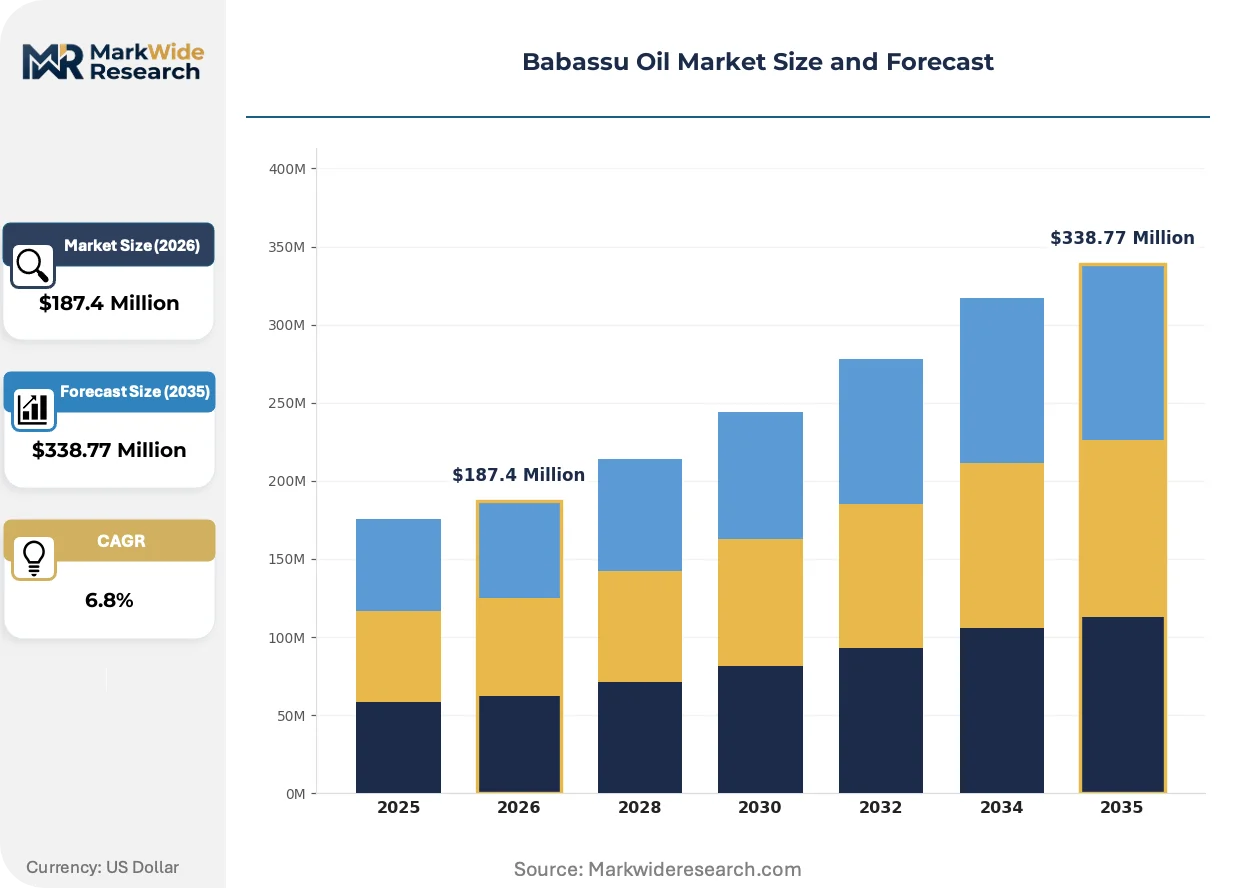
Market Dynamics
Cooperative-led extraction networks across Maranhão and Piauí are consolidating supply-side control while EU deforestation-free regulations force traceability investments that reshape competitive entry costs.
Growth Catalysts
- REACH compliance requirements:European cosmetic ingredient safety frameworks drive demand for refined babassu oil with documented contaminant profiles, filtering out unrefined competitors.
- Fractionation technology:Advanced lipid separation processes enable cosmetic formulators to access lighter, non-comedogenic MCT alternatives derived from babassu kernels.
- Maranhão state clusters:Dense cooperative harvesting networks around São Luís and Imperatrio secure raw material flows to international personal care manufacturers.
Market Restraints
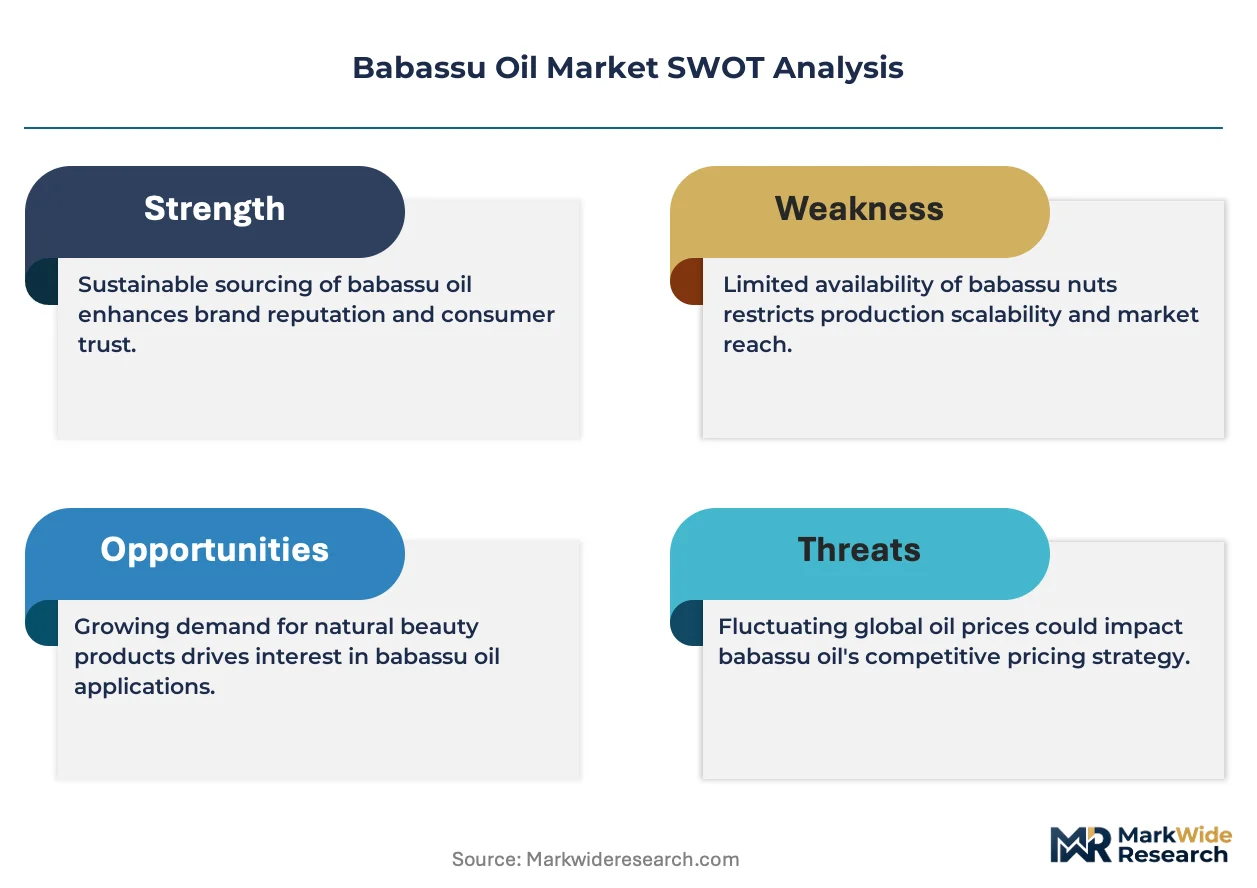
- Wild harvest dependency:Attalea speciosa palm kernels rely entirely on extractivist collection from native stands, creating volume ceilings that synthetic lauric acid sources bypass.
- Brazilian real volatility:Currency fluctuations against the euro and US dollar compress margins for exporters locked into long-term supply contracts.
- Coconut oil substitution:Established tropical oil supply chains with lower certification burdens compete directly in emollient and food-grade applications.
Strategic Opportunities
- US food-grade channel:FDA GRAS designation for babassu oil opens distinct commercial pathways separate from cosmetic regulatory complexity.
- Organic certification premium:Ecocert and USDA Organic standards command price differentiation in clean-label personal care segments.
- Biocarbon credit stacking:Native palm maintenance within extractive reserves qualifies for emerging carbon market mechanisms tied to standing forest preservation.
Industry Challenges
- Extractivist labor mobilization:Seasonal kernel collection requires coordinated community engagement across dispersed rural settlements, complicating workforce planning.
- Batch-to-batch consistency:Variable fatty acid profiles in wild-harvested kernels challenge refinery optimization for multinational cosmetic specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Babassu Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Babassu Oil, Crude Babassu Oil, Fractionated Babassu Oil, Organic Babassu Oil Application: Cosmetics, Food Industry, Pharmaceutical Sector, Biofuel Delivery Mode: Bulk Supply, Retail Packaging, Online Sales, Direct Distribution End User: Personal Care Manufacturers, Food Producers, Health Professionals, Energy Companies |
| Companies Covered | Dr. Adorable Inc., Citróleo, Cargill, BASF SE, Hallstar, Mielle Organics, ANITA GRANT, Natura & Co., Sheabutter Cottage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Babassu Oil Market Strategic Shifts
Supercritical CO2 extraction and enzymatic interesterification are reshaping how babassu lipids enter high-value cosmetic formulations, while regulatory traceability mandates force supply chain digitization.
Supercritical CO2 extraction systems bypass hexane solvent residues entirely, delivering pharmaceutical-grade lauric acid fractions. European fragrance houses and clean beauty brands are adopting these systems at pilot scale. Cold-press mechanical methods are rendering obsolete traditional hexane-based extraction for premium cosmetic grades.
EU Deforestation Regulation (EUDR) mandates geolocation verification for all Amazon-sourced botanical inputs entering European cosmetic supply chains. Compliance requires satellite-linked traceability systems that smaller cooperatives cannot self-finance. Refined babassu oil shipments to Rotterdam and Hamburg now face documentation barriers that crude grades cannot clear.
Ingredient sourcing teams at multinational personal care companies now require blockchain-verified chain-of-custody records from kernel collection through final refining. Direct purchasing agreements with certified cooperatives are displacing traditional commodity broker intermediaries. This restructuring concentrates most visibly in German and French cosmetic manufacturing clusters where EUDR enforcement timelines are shortest.
Babassu Oil Market Segmentation
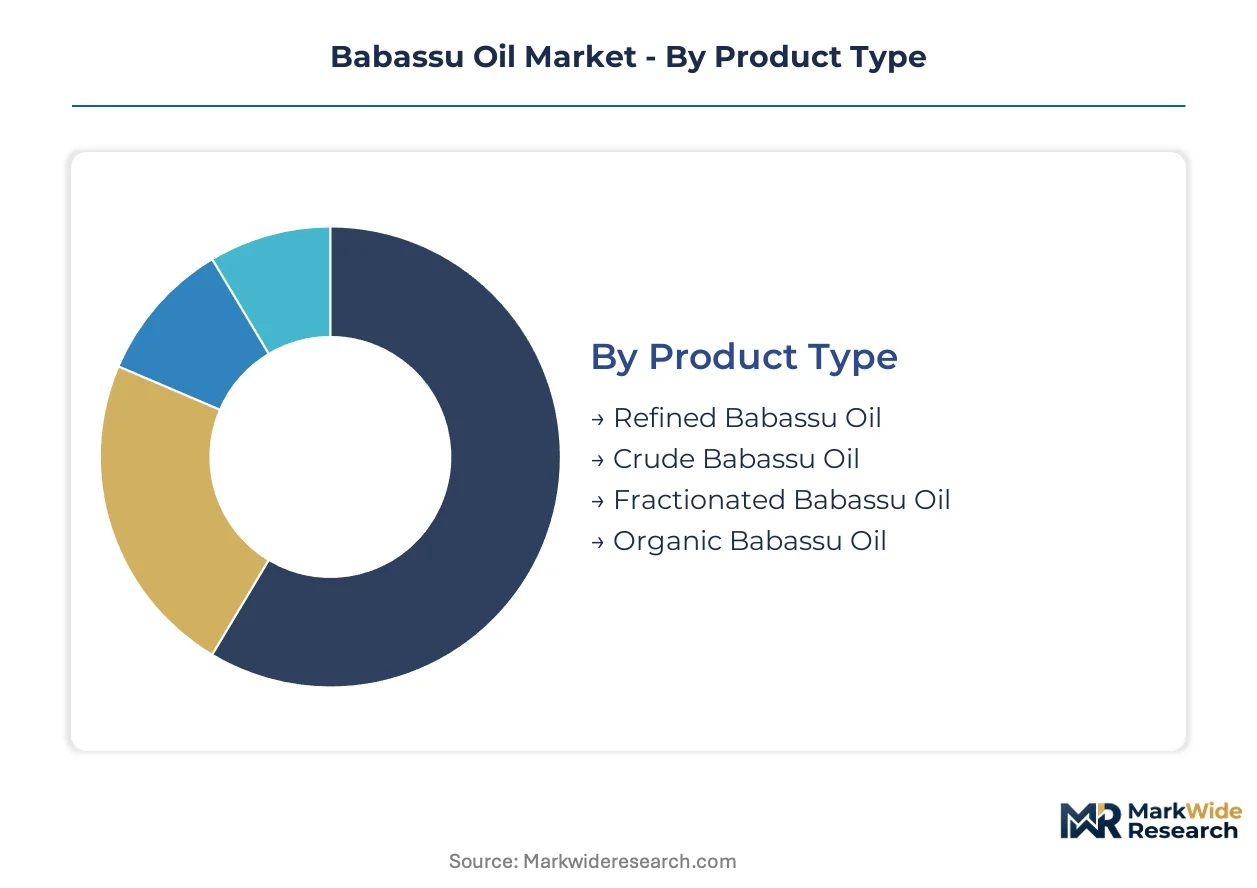
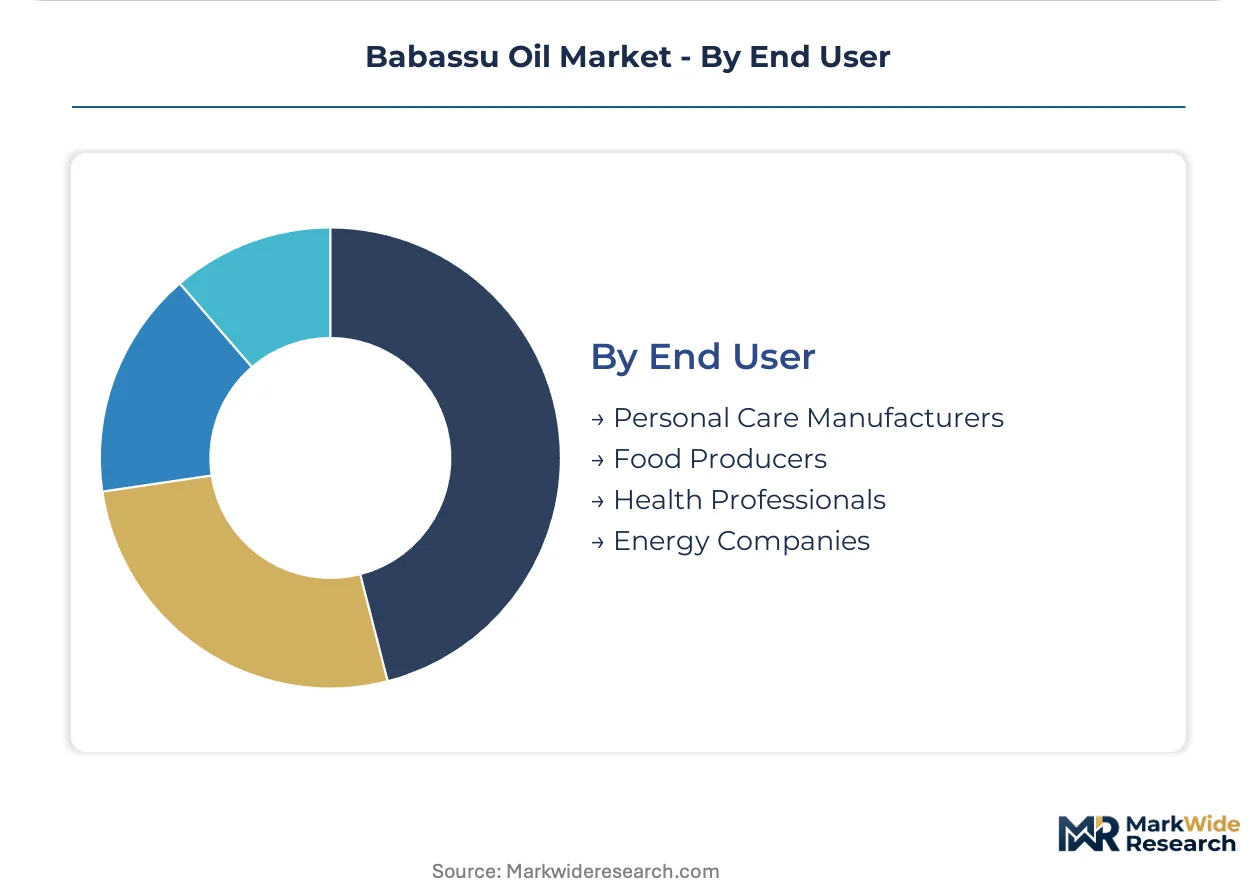
Babassu oil's commercial structure splits across four dimensions that determine pricing power and regulatory exposure. Product type stratification separates commodity volumes from certified premiums, while application channels dictate which compliance frameworks govern market access.
Product Type:
Mature refining infrastructure dominates value capture, with emerging fractionation technology opening differentiated positioning.
- Refined Babassu Oil:Standardized fatty acid profiles through bleaching and deodorization meet multinational cosmetic specifications. REACH documentation requirements in Rotterdam and Hamburg concentrate procurement around established Brazilian refiners with contaminant testing capabilities.
- Fractionated Babassu Oil:Advanced lipid separation isolates medium-chain triglyceride fractions for non-comedogenic skincare formulations. German and French clean beauty brands are expanding pilot procurement of these lighter alternatives to coconut-derived MCTs.
- Crude Babassu Oil:Hexane-extracted base grade with variable lauric acid content serves regional Brazilian food processors.
- Organic Babassu Oil:Ecocert and USDA Organic certified supply chains command premium positioning through documented wild-harvest traceability from Maranhão cooperatives.
Refined babassu oil retains volume leadership; fractionated babassu oil holds the steepest expansion curve.
Application:
Cosmetic formulators anchor premium pricing, while food and pharmaceutical pathways operate under divergent regulatory architectures.
- Cosmetics:Emollient properties in hair and skin formulations drive specification-grade demand. EUDR geolocation mandates are restructuring how European fragrance houses source from São Luís extraction clusters.
- Food Industry:FDA GRAS designation enables U.S. channel development distinct from cosmetic regulatory complexity. Bakery and confectionery applications leverage babassu oil's 24°C melting point for stable shortening systems.
- Pharmaceutical Sector:Supercritical CO2 extracted grades supply topical excipient requirements with zero solvent residue profiles.
- Biofuel:Fatty acid methyl ester conversion from crude grades serves regional Brazilian biodiesel blending mandates.
Cosmetics commands absolute revenue concentration; pharmaceutical applications are climbing the fastest toward formal monograph recognition.
Delivery Mode:
Volume scale separates industrial procurement from certified retail channels with divergent margin structures.
- Bulk Supply:Tanker and flexitank shipments from Itaqui Port serve Rotterdam and Hamburg refineries with 20,000+ liter minimums.
- Retail Packaging:250ml to 5-liter containers target artisanal cosmetic formulators through specialized distributors.
- Online Sales:Direct-to-formulator platforms are displacing traditional commodity brokers for organic certified grades.
- Direct Distribution:Long-term offtake agreements between Maranhão cooperatives and German cosmetic manufacturers eliminate intermediary markups.
Bulk supply retains volume leadership; direct distribution holds the steepest expansion curve as EUDR compliance concentrates procurement relationships.
End User:
Personal care manufacturers exercise specification-setting power, while energy companies represent volume opportunism at lower margins.
- Personal Care Manufacturers:Multinational formulators in Germany and France mandate blockchain-verified chain-of-custody documentation from kernel collection through final delivery.
- Food Producers:U.S. and Brazilian bakery operations utilize GRAS-designated grades for clean-label shortening applications.
- Health Professionals:Naturopathic and dermatological channels drive small-volume organic certification premiums.
- Energy Companies:Brazilian biodiesel blenders absorb crude grade surpluses when cosmetic specifications tighten.
Personal care manufacturers retain volume leadership; health professional channels are gaining share fastest through wellness positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Attalea speciosa palm stands concentrate in Brazil's eastern Amazon, with extraction networks radiating from Maranhão state. German and French cosmetic manufacturers anchor import demand through Rotterdam and Hamburg entry points. Regulatory divergence between FDA GRAS pathways and EU deforestation-free mandates shapes distinct commercial corridors.
Brazil
Maranhão state cooperative networks supply kernel volumes to international refiners. ANVISA cosmetic ingredient safety assessments govern domestic formulation standards. São Luís and Imperatriz clusters consolidate wild-harvest collection before Itaqui Port export.
Germany
Fragrance houses and clean beauty formulators drive specification-grade procurement of fractionated grades. ECHA REACH documentation requirements filter crude shipments from Rotterdam. Hamburg refining clusters now mandate blockchain-verified chain-of-custody for Amazon-sourced inputs.
United States
Bakery and confectionery channels absorb GRAS-designated food-grade volumes distinct from cosmetic regulatory complexity. FDA food additive safety frameworks enable clean-label shortening applications. East Coast personal care manufacturers pilot organic-certified supply direct from Maranhão cooperatives.
France
Luxury cosmetic houses command premium positioning for Ecocert-certified organic grades. EU Deforestation Regulation geolocation mandates force satellite-linked traceability investments. Paris-region formulators consolidate procurement relationships around direct cooperative offtake agreements.
Netherlands
Rotterdam serves as the primary European entry point for bulk tanker shipments from northern Brazil. EUDR compliance documentation requirements concentrate refining relationships around established traders. Amsterdam cosmetic ingredient distributors mediate between Maranhão extraction networks and German manufacturing clusters.
Babassu Oil Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. Cooperative-led extraction networks in Maranhão and Piauí consolidate supply-side control against fragmented downstream refining. Three archetypes dominate: vertically integrated Brazilian operators with community extraction ties, multinational chemical processors with fractionation capabilities, and clean beauty brands with certified organic positioning. Competitive moves center on direct purchasing agreements that displace commodity brokers, plus traceability technology investments that satisfy EUDR mandates.
Among Brazilian-origin operators, Citróleo exemplifies the cooperative-anchored archetype through its vertical ties to Amazonian extraction communities. Natura & Co. occupies a position within the certified organic tier, linking biodiversity commitments to supply chain documentation. Multinational processors including BASF SE and Cargill sit at the scale-driven refining end, converting raw kernel flows into specification-grade cosmetic ingredients. Hallstar represents the specialty chemical intermediary archetype, bridging Maranhão supply clusters with European formulator requirements.
| Leading Market Players |
|---|
| Dr. Adorable Inc. |
| Citróleo |
| Cargill |
| BASF SE |
| Hallstar |
| Mielle Organics |
| ANITA GRANT |
| Natura & Co. |
| Sheabutter Cottage |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Maranhão state extraction networks during peak kernel collection seasons drives supplier hoarding behavior and spot-price volatility, compressing margins for Rotterdam-bound refiners while rewarding cooperatives with storage capabilities.
Pricing Analysis
EU Deforestation Regulation dictates the pricing tier structure across the Babassu Oil Market, separating blockchain-verified organic grades from undocumented crude shipments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and contaminant testing depth. Cost compression in unrefined tiers is intensifying because EUDR documentation barriers filter out smaller cooperatives. Personal care manufacturers in Germany and France show least price sensitivity for Ecocert-certified supply, while Brazilian biodiesel blenders absorb economy-grade surpluses at highest sensitivity.
Supply Chain Analysis
Wild harvest dependency across Maranhão, Piauí, and Pará states creates single-source vulnerability for Attalea speciosa kernel flows. Raw material procurement draws from dispersed extractivist communities, mechanical pressing infrastructure, and hexane-based extraction facilities. Seasonal labor mobilization gaps represent the dominant structural risk. Distribution runs through São Luís consolidation points to Itaqui Port, then bulk tanker to Rotterdam and Hamburg refining clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and French cosmetic formulators mandating EUDR-compliant documentation, fragmenting supplier access for uncertified grades.
For Market Incumbents: Pre-empt coconut oil substitution threats by deepening direct cooperative offtake agreements in Imperatriz clusters. Secure ANVISA pre-approval dossiers ahead of regulatory tightening. Channel control through long-term contracts with Maranhão extraction networks remains the priority lever against spot-market volatility. For New Entrants and Emerging Players: Build out supercritical CO2 extraction capacity to serve pharmaceutical-grade lauric acid demand from European fragrance houses. The US food-grade channel offers most penetrable white-space given FDA GRAS designation and lower certification barriers. A clean-label positioning targeting East Coast bakery operations provides viable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated operators with captive Maranhão cooperative networks and existing EUDR compliance infrastructure. Long-term viability rests on defensibility against synthetic lauric acid cost curves. Watch for EUDR enforcement acceleration as inflection indicator for certified supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extraction Networks | Direct cooperative ties in Maranhão secure EUDR-compliant kernel flows to Rotterdam refiners. |
| Supercritical CO2 Capacity Expansion | Pharmaceutical-grade lauric acid output captures premium positioning in German cosmetic formulations. |
| Organic Certification Program | Ecocert and USDA Organic documentation unlocks price premiums from French luxury cosmetic houses. |
| Long-term Supply Agreement | Fixed offtake contracts with Hamburg refining clusters hedge against Brazilian real volatility. |
| Blockchain Traceability Platform | Geolocation verification systems satisfy EUDR mandates for Amazon-sourced botanical inputs. |
Study Parameters
A standing panel of cooperative extraction leaders, refinery procurement managers, cosmetic formulators, and ANVISA regulatory specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from Brazilian customs export records, ANVISA cosmetic ingredient filings, ECHA REACH registration databases, and EUDR implementation guidance documents. Bottom-up kernel flow estimates from Maranhão cooperatives were triangulated against top-down import volumes through Rotterdam and Hamburg.
Scenario-bracketing around EUDR compliance timelines, synthetic lauric acid cost curves, and Brazilian real volatility bands bounded the projection horizon. Segmentation modeling spanned product grade tiers, application channels, and regional regulatory clusters. CAGRs were derived from slope analysis across volume trajectories. Industry-specific inputs included cooperative capacity utilization rates and fractionation technology adoption curves among German clean beauty brands.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational chemical processors with synthetic substitution capabilities would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market