
 Industrial Phosphate Market | 2026-2036
Industrial Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Phosphate Market Intelligence
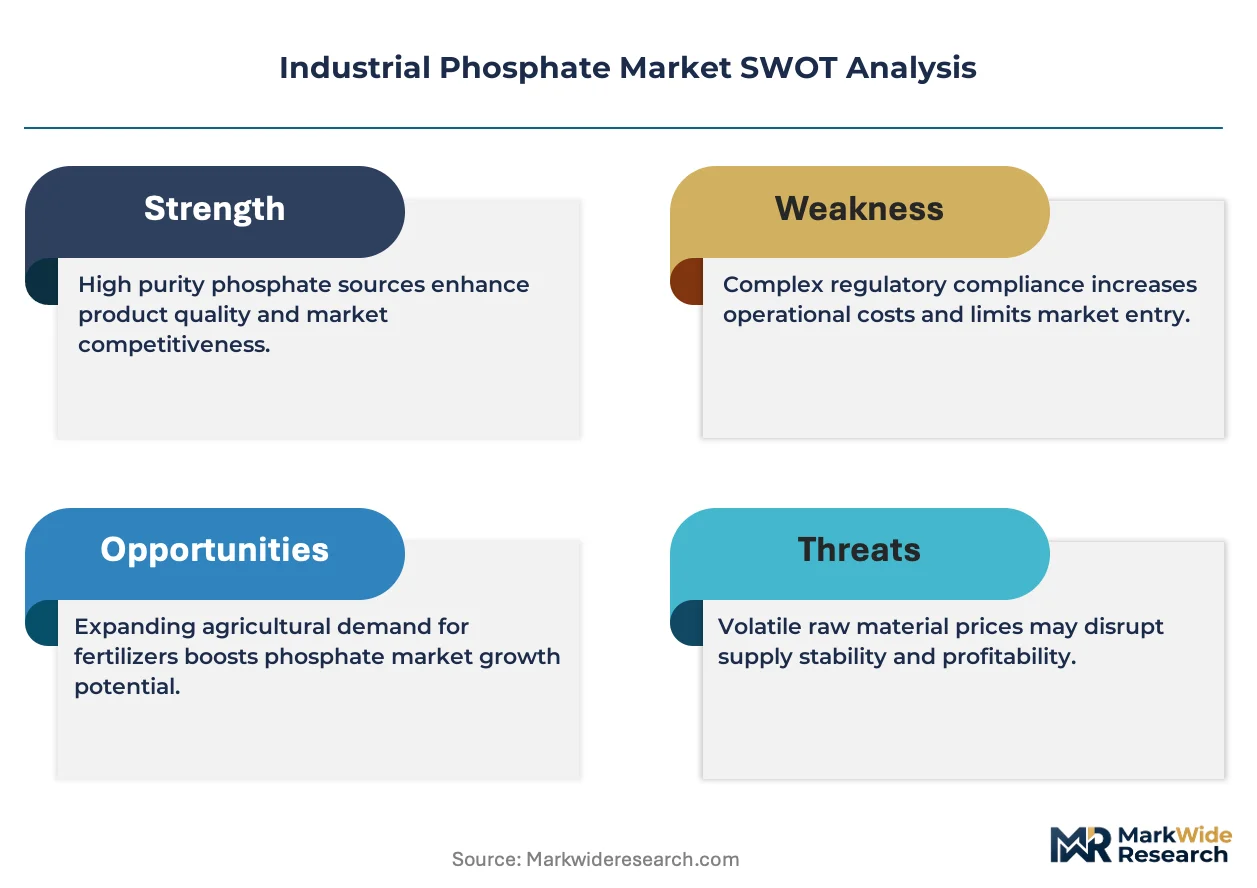
Food-grade and pharmaceutical-grade specifications are collapsing the distinction between specialty and commodity phosphate markets. The Mosaic Company leverages its large-scale mining and processing infrastructure to serve both agricultural and industrial segments. ICL Group differentiates through its focus on specialized phosphate solutions for food, agriculture, and engineered materials. OCP Group anchors its competitive position with significant rock phosphate reserves, ensuring raw material control.
Industrial phosphates are inorganic chemical salts derived from phosphoric acid, often produced via the wet process or thermal process. They function primarily as buffering agents, emulsifiers, leavening agents, and nutrient sources across various sectors. The fertilizers application continues to represent the largest volume segment, though food additives offer higher margin potential. Ammonium phosphate and dicalcium phosphate product types are foundational, with demand tied closely to the agriculture and animal feed end-user sectors respectively.
The European Union’s REACH regulation and the US FDA's GRAS (Generally Recognized as Safe) notifications govern chemical safety and food additive purity. In China, MEE directives on water pollution and soil contamination directly impact phosphate production and fertilizer application rates. Navigating these divergent regional environmental and food safety standards is the central challenge for producers seeking global market access.
Market Dynamics
The central force governing the industrial phosphate market is the regulatory-driven demand for higher purity and improved nutrient efficiency. This pressure, originating from food safety bodies and environmental agencies, compels producers to invest in advanced processing to meet divergent regional standards.
Growth Catalysts
- Animal Feed Fortification:Rising demand for high-purity dicalcium and monocalcium phosphate in animal feed to improve nutrient absorption and bone development is a significant catalyst, particularly in Asia's expanding livestock sector.
- EU Green Deal Implementation:The European Union's nutrient management protocols under the Green Deal are creating demand for specialized, low-cadmium phosphate fertilizers that minimize environmental runoff and improve soil health.
- Industrial Chemical Expansion in China:China's continued industrialization drives volume demand for technical-grade phosphates like sodium tripolyphosphate (STPP) for use in detergents, water treatment, and ceramics manufacturing.
Market Restraints
- Input Cost Volatility:Production economics are highly sensitive to price fluctuations in key inputs like sulfur and natural gas, which are essential for the dominant wet-process phosphoric acid production method.
- Divergent Regulatory Standards:The friction between Europe's REACH chemical safety framework and the US FDA's GRAS notifications for food additives creates significant compliance and testing burdens for global exporters.
- Geopolitical Supply Risk:Heavy concentration of high-quality rock phosphate reserves in a few countries, primarily in North Africa and the Middle East, exposes the global supply chain to regional instability.
Strategic Opportunities
- Battery Materials Application:The rapid growth of the electric vehicle market presents a major opportunity for high-purity phosphoric acid as a key precursor for lithium iron phosphate (LFP) cathode materials.
- Phosphorus Recovery Technologies:Circular economy mandates encourage investment in technologies to recover and recycle phosphorus from wastewater and agricultural waste, creating alternative, localized raw material sources.
- Agricultural Modernization in Southeast Asia:Nations like Vietnam and Indonesia are upgrading agricultural practices, creating new markets for efficient, water-soluble phosphate fertilizers beyond traditional commodity products.
Industry Challenges
- High Capital Expenditure:The construction of new, world-scale phosphoric acid plants or thermal process facilities requires immense upfront capital investment, creating high barriers to entry and limiting capacity expansion.
- Navigating Contaminant Limits:Producers face the operational challenge of consistently meeting varied and tightening limits on heavy metals, such as cadmium, set by different authorities like EFSA in Europe and Health Canada.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Phosphate Market |
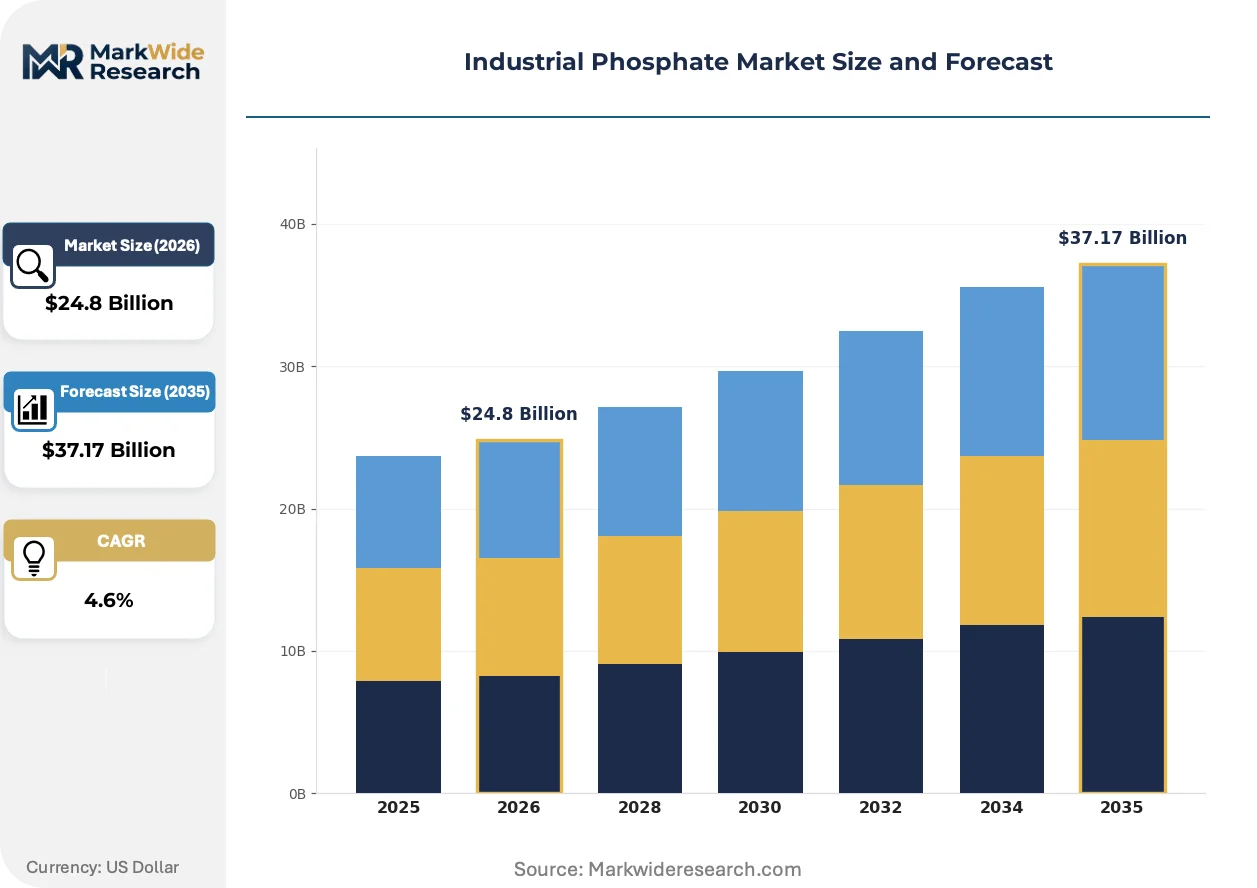
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocalcium Phosphate, Dicalcium Phosphate, Tricalcium Phosphate, Ammonium Phosphate Application: Fertilizers, Food Additives, Animal Feed, Industrial Chemicals End User: Agriculture, Food Processing, Pharmaceuticals, Manufacturing Distribution Channel: Direct Sales, Retail, E-commerce, Distribution Partners |
| Companies Covered | Nutrien Ltd, EuroChem Group, OCP Group, CF Industries, ICL Group, The Mosaic Company, PhosAgro, Jordan Phosphate Mines, Yara International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Phosphate Market Strategic Shifts & Innovations
The pursuit of higher purity and sustainable sourcing is reshaping the industrial phosphate value chain. Innovations in purification and circular recovery methods are creating new value streams, separating specialty products from their commodity origins and altering traditional supply dynamics.
Advanced purification methods, including solvent extraction and multi-stage crystallization, are gaining traction. Food, beverage, and pharmaceutical end-users are the primary adopters, requiring technical and food-grade phosphates with exceptionally low levels of impurities. This technological capability is fragmenting the market by creating a distinct, high-margin segment for specialty phosphates that is decoupled from bulk agricultural grade pricing.
In China, MEE directives targeting phosphorus runoff into waterways are a powerful regulatory driver. This policy directly compels fertilizer manufacturers to innovate and commercialize controlled-release and enhanced-efficiency phosphate products that improve nutrient uptake by crops. The domestic agricultural sector is the most affected, with procurement patterns shifting from basic ammonium phosphates toward these value-added formulations.
A distinct behavioral shift is visible in buyer preference for phosphates with certified low heavy metal content. This criterion disrupts supply chains traditionally based on raw material source alone, giving an advantage to producers with superior purification technology. This trend is most pronounced within the European Union, where food and feed safety regulations on contaminants are exceptionally stringent.
Industrial Phosphate Market Segmentation
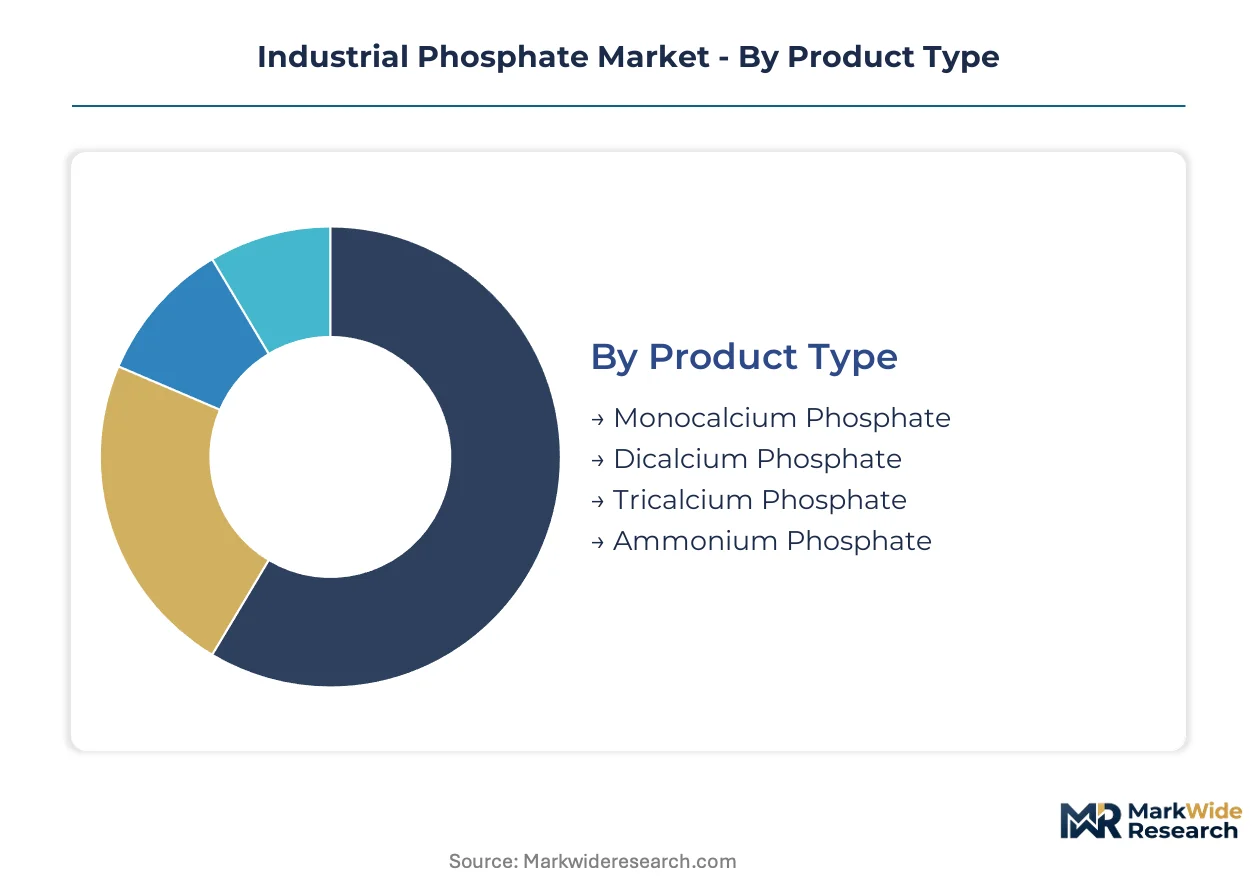
Market segmentation provides a granular view of the industrial phosphate landscape, revealing distinct demand drivers, purity requirements, and supply chain dynamics across various product types, applications, end-users, and distribution channels. Understanding these segments is crucial for producers to align product offerings with specific customer needs and regulatory mandates.
Product Type:
Margin pools within the industrial phosphate product type category largely concentrate in specialized, high-purity formulations demanded by sensitive end-user sectors.
- Monocalcium Phosphate:Monocalcium phosphate (MCP) is an inorganic compound, typically a fine white powder, used as a leavening agent in baked goods and as a mineral supplement. Demand for MCP is strong in the food processing sector, driven by consumer preference for convenience foods and the need for consistent dough performance.
- Dicalcium Phosphate:Dicalcium phosphate (DCP) exists as an anhydrous or dihydrate form, functioning as a feed additive for livestock and poultry, providing essential calcium and phosphorus. Asia's expanding livestock sector drives significant demand for high-purity DCP to enhance animal bone development and overall health.
- Tricalcium Phosphate:Tricalcium phosphate (TCP) serves as an anti-caking agent in powdered foods and as a calcium supplement in various dietary products, particularly in the US.
- Ammonium Phosphate:Ammonium phosphate compounds, such as monoammonium phosphate (MAP) and diammonium phosphate (DAP), are fundamental components of compound fertilizers, delivering nitrogen and phosphorus to crops globally.
The dominant share belongs to Ammonium Phosphate, while Dicalcium Phosphate is closing the gap fastest.
Application:
Volume dynamics across industrial phosphate applications are primarily dictated by agricultural requirements, though specialty uses command higher price points.
- Fertilizers:Fertilizers represent the largest volume application for industrial phosphates, supplying essential phosphorus nutrients for crop growth and soil enrichment. The EU Green Deal implementation drives demand for low-cadmium phosphate fertilizers, minimizing environmental runoff across Europe.
- Food Additives:Food additives utilize phosphates as emulsifiers, leavening agents, and pH buffers in processed foods, beverages, and dairy products. Stringent US FDA GRAS notifications and EU food safety regulations compel producers to offer high-purity, contaminant-free grades.
- Animal Feed:Animal feed applications leverage phosphates like DCP and MCP to fortify animal diets, supporting bone health and nutrient absorption in livestock across continents.
- Industrial Chemicals:Industrial chemicals employ technical-grade phosphates in detergents, water treatment, and ceramic manufacturing, particularly in rapidly industrializing economies like China.
Demand for Fertilizers continues to drive overall market volume, with Food Additives showing significant expansion.
End User:
Customer type segmentation reveals distinct procurement patterns and purity requirements for industrial phosphates, influencing product specifications.
- Agriculture:The agriculture sector is the primary end-user, consuming phosphates as essential fertilizers to boost crop yields and improve soil fertility. Modernization efforts in Southeast Asian agriculture, notably in Vietnam and Indonesia, are creating new markets for efficient, water-soluble phosphate fertilizers.
- Food Processing:Food processing companies integrate phosphates into a wide range of products for texture, preservation, and leavening functions. Buyer preference for phosphates with certified low heavy metal content is most pronounced within this segment, particularly in the European Union.
- Pharmaceuticals:The pharmaceuticals industry uses high-purity phosphates as excipients, buffering agents, and active pharmaceutical ingredients in various drug formulations, adhering to strict regulatory standards like those from the US FDA.
- Manufacturing:Manufacturing industries, including ceramics and metal treatment, utilize technical-grade phosphates for their binding, cleaning, and corrosion inhibition properties, with China being a major consumer.
The Agriculture sector remains the largest consumer, while Pharmaceuticals presents high-value opportunities.
Distribution Channel:
Supply concentration within industrial phosphate distribution channels reflects the bulk nature of many phosphate products, alongside the need for specialized delivery.
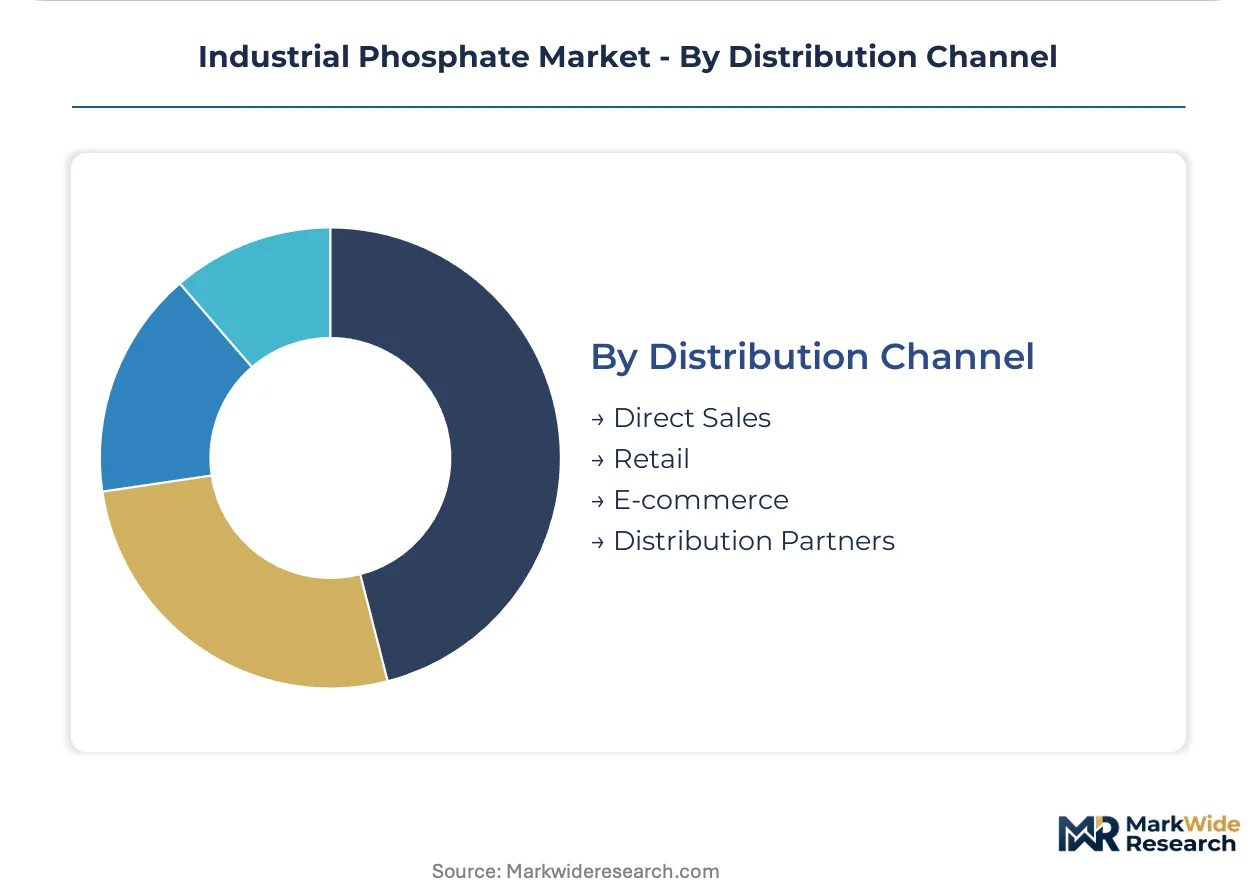
- Direct Sales:Direct sales channels involve producers supplying large-volume customers, such as major fertilizer blenders or industrial chemical manufacturers, often through long-term contracts. This channel optimizes logistics for high-tonnage shipments and ensures consistent supply for key accounts.
- Distribution Partners:Distribution partners, including regional chemical distributors and agricultural cooperatives, serve smaller customers and provide localized inventory management and technical support. This network is crucial for reaching diverse end-users across varied geographic regions, particularly for specialty grades.
- Retail:Retail channels, primarily agricultural supply stores, cater to individual farmers and small-scale operations for packaged fertilizer and feed additive products in local markets.
- E-commerce:E-commerce platforms are emerging for specialized phosphate products, offering convenience and broader access for niche industrial or laboratory-scale requirements globally.
Traditional Direct Sales channels handle the bulk of industrial phosphate delivery, with E-commerce gaining traction for specialized orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial phosphate market exhibits a concentrated supply chain, primarily stemming from regions rich in high-quality rock phosphate reserves. This geographic concentration influences global raw material availability and shapes downstream processing investments. Demand centers are diversifying, driven by agricultural modernization and industrial expansion in various economies.
China
China's industrial chemical expansion drives substantial volume demand for technical-grade phosphates in manufacturing applications. MEE directives on water pollution and soil contamination compel fertilizer manufacturers to innovate advanced products. The Yangtze River Delta, a major industrial hub, sees significant consumption of phosphates for detergents and water treatment.
Germany
Germany's market for industrial phosphates focuses on high-purity grades, influenced by the EU Green Deal's nutrient management protocols. REACH regulations dictate stringent chemical safety standards for food and feed additives. The Rhine-Ruhr chemical industry cluster requires specialized phosphates for diverse industrial applications.
Morocco
Morocco anchors global supply with its vast high-quality rock phosphate reserves, ensuring raw material control for major producers. National resource management policies support the extraction and initial processing of these critical minerals. The Khouribourg mining basin represents a primary global source of rock phosphate for the industry.
Vietnam
Vietnam's agricultural modernization initiatives are creating new markets for efficient, water-soluble phosphate fertilizers. The national government promotes enhanced-efficiency products to improve crop nutrient uptake. The Mekong Delta region, a key agricultural zone, drives demand for advanced phosphate formulations.
United States
The United States sees strong demand for dicalcium phosphate in animal feed and for high-purity food additives under US FDA GRAS notifications. The agriculture sector remains a significant consumer of phosphate fertilizers. The Gulf Coast region hosts major phosphoric acid production facilities, serving both domestic and export markets.
Industrial Phosphate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the industrial phosphate market. The industry exhibits a tiered structure, with global integrated producers operating alongside specialized solution providers. Key strategic moves include raw material control and significant investment in advanced processing capabilities.
OCP Group anchors its competitive position through extensive rock phosphate reserves, providing critical raw material control. The Mosaic Company exemplifies a global integrated producer, leveraging its large-scale mining and processing infrastructure to serve diverse segments. ICL Group sits within the specialized solution provider archetype, differentiating through its focus on food, agriculture, and engineered materials.
| Leading Market Players |
|---|
| Nutrien Ltd |
| EuroChem Group |
| OCP Group | CF Industries |
| ICL Group |
| The Mosaic Company |
| PhosAgro |
| Jordan Phosphate Mines |
| Yara International |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for rock phosphate and phosphoric acid lock in supply access for integrated producers and provide price visibility for major agricultural and industrial buyers. This structure mitigates volatility in critical raw material sourcing.
Pricing Analysis
REACH regulations in Europe dictate the pricing tier structure for industrial phosphates, driving demand for high-purity, low-cadmium grades. The dominant pricing model combines contract-based long-term offtake for bulk products with spot market transactions for specialized formulations. Price differentiation stems from purity grade requirements, such as US FDA GRAS certification, and regional delivery costs. Pricing pressure originates from volatility in sulfur and natural gas input costs, making the agriculture sector most price-sensitive, while pharmaceutical end-users prioritize quality.
Supply Chain Analysis
Strategic stockpile preferences for critical rock phosphate reserves characterize the industrial phosphate supply chain, balancing raw material security against inventory costs. Geographic supply concentrates heavily in Morocco, with significant processing capabilities in China and the United States, relying on rock phosphate, sulfur, and natural gas as primary inputs. Geopolitical instability in North Africa presents a structural risk to global raw material availability. Downstream distribution runs predominantly through direct sales for bulk and specialized distribution partners for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial phosphate market necessitates a robust substitution defense as incumbents navigate the threat from alternative LFP cathode materials in the electric vehicle sector. Producers must proactively address this evolving demand landscape.
For Market Incumbents: Secure upstream control over rock phosphate reserves through long-term contracts to mitigate geopolitical supply risk. Invest in advanced purification technologies to consistently meet tightening heavy metal limits set by EFSA and Health Canada. Diversify raw material sourcing by exploring phosphorus recovery technologies from wastewater. This defends against margin pressure from volatile input costs and stringent regulatory demands.
For New Entrants and Emerging Players: Service-layer gaps exist in providing high-purity phosphoric acid for lithium iron phosphate (LFP) cathode materials, a growing battery market segment. Target under-served agricultural modernization initiatives in Southeast Asia with efficient, water-soluble fertilizers. Develop specialized phosphorus recovery technologies to create alternative, localized raw material sources. A focused go-to-market angle involves technology licensing to established chemical producers.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with significant rock phosphate reserves or specialized solution providers focused on high-purity applications. The market demonstrates long-term viability through its shift towards specialty products and circular economy mandates. Target acquisition archetypes include advanced purification technology firms and phosphorus recovery specialists. A critical signal to watch is the acceleration of lithium iron phosphate (LFP) demand in the electric vehicle battery market.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Purification | Increases output of high-purity grades required by EU food safety regulations and pharmaceutical end-users. |
| Backward Integration into Rock Phosphate Mining | Secures raw material supply and mitigates geopolitical risk from concentrated North African reserves. |
| Investment in Phosphorus Recovery Technologies | Creates alternative, localized raw material sources, aligning with circular economy mandates. |
| Joint Venture for LFP Precursor Production | Accelerates market entry into the rapidly growing electric vehicle battery materials sector. |
| Certification for Low Heavy Metal Content | Gains competitive advantage in stringent markets like the European Union for food and feed applications. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary insights came from R&D directors, procurement leads at downstream OEMs, plant managers, and regulatory affairs specialists. Secondary validation involved customs and trade data, SEC 10-K filings, China's MEE directives, and EU REACH documents. This approach ensured robust bottom-up and top-down triangulation for market sizing.
The forecast modeling period utilized a comprehensive analytical framework to project market trajectories across the analysis window. Segmentation dimensions modeled included product type, application, end-user, distribution channel, and purity grade. Compound annual growth rates were derived from historical trends and future demand projections. Key industry-specific inputs included anticipated rock phosphate price fluctuations and accelerating lithium iron phosphate (LFP) demand.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material supply disruptions. Forecasts reflect these assumptions, though significant shifts in environmental policies or commodity prices could alter market dynamics. Revision becomes warranted when geopolitical instability or major regulatory changes cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Butadiene Extraction Market