
 Europe Modified Bitumen Market | 2026-2036
Europe Modified Bitumen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Modified Bitumen Market Foresight
Poland's bitumen modification capacity is reshaping supply dynamics across Central Europe. TotalEnergies leverages integrated refinery-polymer operations to sustain feedstock cost advantages. Nynas AB anchors specialty naphthenic base oil supply for high-performance SBS formulations. Shell PLC competes through controlled distribution networks spanning North Sea logistics corridors.
Modified bitumen denotes asphalt binder engineered with elastomers, plastomers, or reactive polymers to enhance temperature susceptibility, elastic recovery, and fatigue resistance. SBS modification achieves softening points above 100°C while maintaining flexibility below -20°C, enabling single-ply roofing membranes and bridge deck waterproofing systems. The SBS product type leads European volume due to superior low-temperature performance in Nordic climates, while membrane technology commands premium positioning in commercial roofing. Cold mix technology grows fastest in urban maintenance applications where hot-work restrictions and emissions controls limit traditional paving methods.
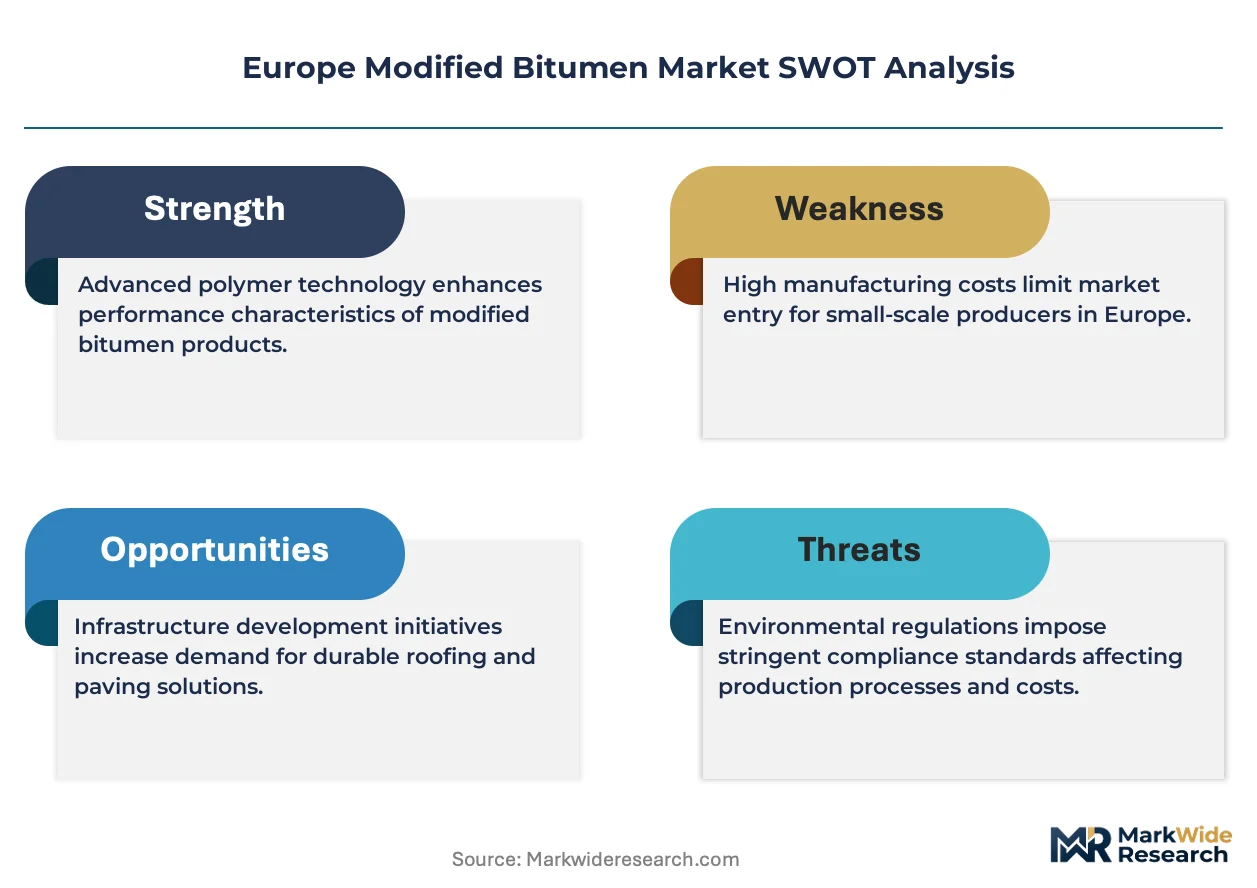
REACH compliance governs polymer additive registration and chemical safety documentation across EU member states. The EU Green Deal's building renovation targets and F-Gas Regulation phase-down indirectly steer specification toward durable bituminous barriers with extended service life. ECHA's ongoing substance evaluations for polycyclic aromatic hydrocarbons in bitumen streams may tighten product standards. Stakeholders must monitor polymer supply diversification and national transposition of Construction Products Regulation amendments to anticipate specification shifts.
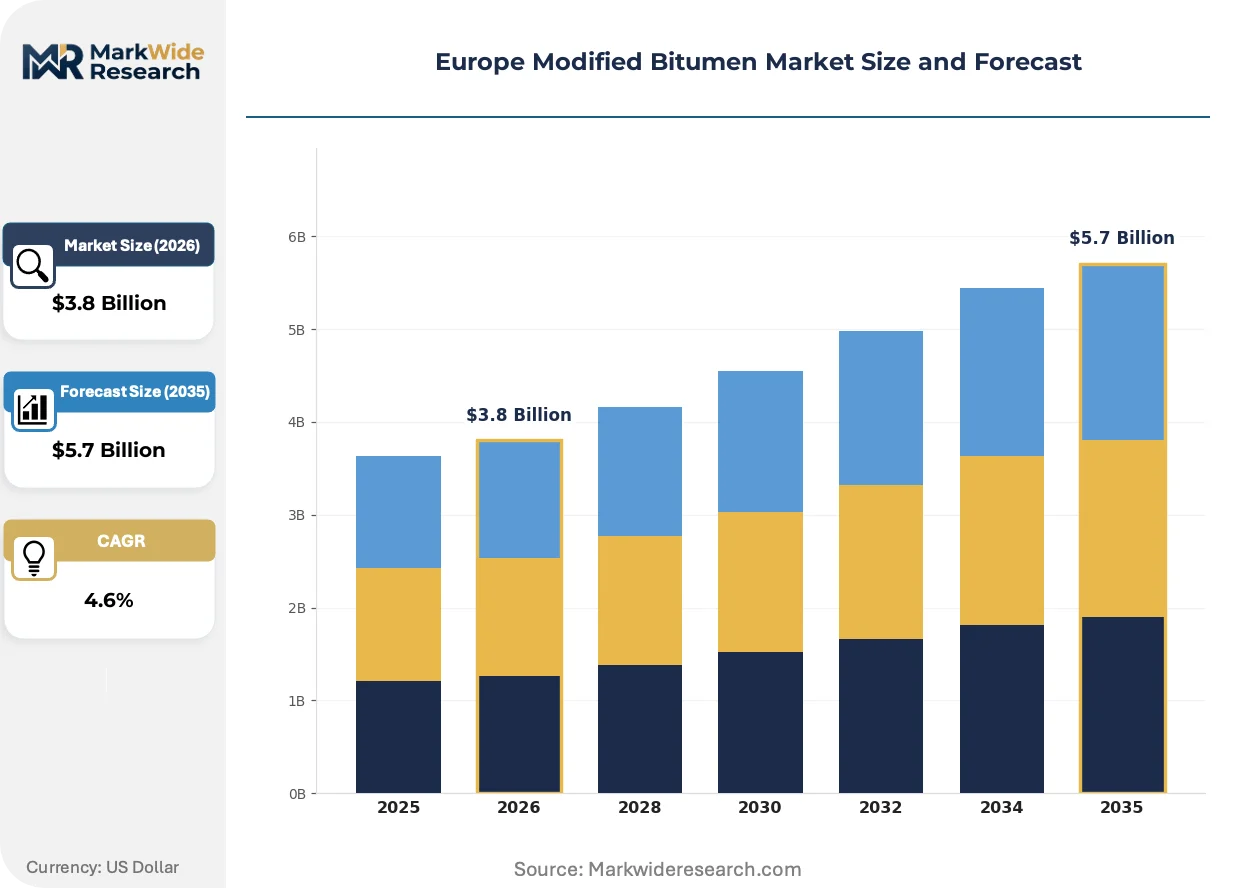
Market Dynamics
The EU Green Deal's building renovation targets are compressing specification cycles across European construction markets, forcing polymer selection decisions upstream into engineering procurement workflows.
Growth Catalysts
- Energy Performance of Buildings Directive:Tightened thermal efficiency mandates in Germany and France are expanding waterproofing membrane specifications for commercial retrofits.
- Crumb rubber modification:Circular economy incentives are accelerating end-of-life tire utilization in asphalt binders for municipal road maintenance contracts.
- Nordic climate severity:Extended freeze-thaw cycles in Sweden and Finland are mandating SBS-modified binders for bridge deck applications.
Market Restraints
- Styrene-butadiene supply concentration:European SBS polymer production clusters in Belgium and the Netherlands create feedstock vulnerability for compounders.
- PAH evaluation timelines:ECHA's ongoing substance assessments for polycyclic aromatic hydrocarbons are extending product registration uncertainty.
- Cold mix performance gaps:Storage stability limitations of emulsion-based systems restrict adoption in heavy-traffic highway rehabilitation.
Strategic Opportunities
- Polish infrastructure acceleration:EU cohesion fund disbursements are expanding expressway construction budgets beyond domestic modification capacity.
- Recycled polymer integration:Post-consumer plastic pyrolysis oils are emerging as partial SBS extenders for cost-sensitive membrane formulations.
- Carbon border adjustment mechanism:CBAM phase-in is creating first-mover advantage for low-emission binder production with verified supply chain data.
Industry Challenges
- Polymer formulation chemistry expertise:Crosslinking kinetics optimization for high-temperature storage requires specialized rheology competency scarce outside major compounders.
- Multi-jurisdictional certification:Divergent national transpositions of Construction Products Regulation amendments fragment testing protocols across member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Modified Bitumen Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: APP, SBS, PE, Others Application: Roofing, Waterproofing, Paving, Insulation Technology: Hot Mix, Cold Mix, Membrane, Coating End User: Construction, Infrastructure, Automotive, Industrial |
| Companies Covered | TotalEnergies, Nynas AB, ROSNEFT, Colas SA, ORLEN Asfalt Sp ZOO, Gazprom Neft PJSC, Shell PLC, Eni S.p.A., Repsol, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Modified Bitumen Market Shifts & Advancements
Warm-mix additive chemistry and bio-based binder extenders are converging to reshape European specification standards, compressing the performance gap between conventional and reduced-temperature paving systems.
Polyphosphoric acid modification is collapsing the cost-performance tradeoff for high-stiffness binders in heavy-duty pavements. German autobahn maintenance authorities are specifying PPA-dosed base binders for rutting resistance in freight corridors. The technology is collapsing premium pricing for SBS-heavy formulations in structural layer applications.
REACH polymer registration requirements are forcing additive suppliers to consolidate product portfolios ahead of 2026 dossier deadlines. Specialty chemical distributors are dropping unregistered elastomer grades from roofing membrane formulations. Small compounders in Southern Europe are accelerating partnerships with registered polymer importers to maintain formulation continuity.
Engineering firms are bundling waterproofing specifications into design-build contracts, displacing traditional merchant distribution for commercial roofing membranes. General contractors in France and Benelux are sourcing modified bitumen directly from compounders with project-specific certification support. The shift is most visible in healthcare and logistics facility construction where single-source accountability reduces interface risk.
Europe Modified Bitumen Market Segmentation
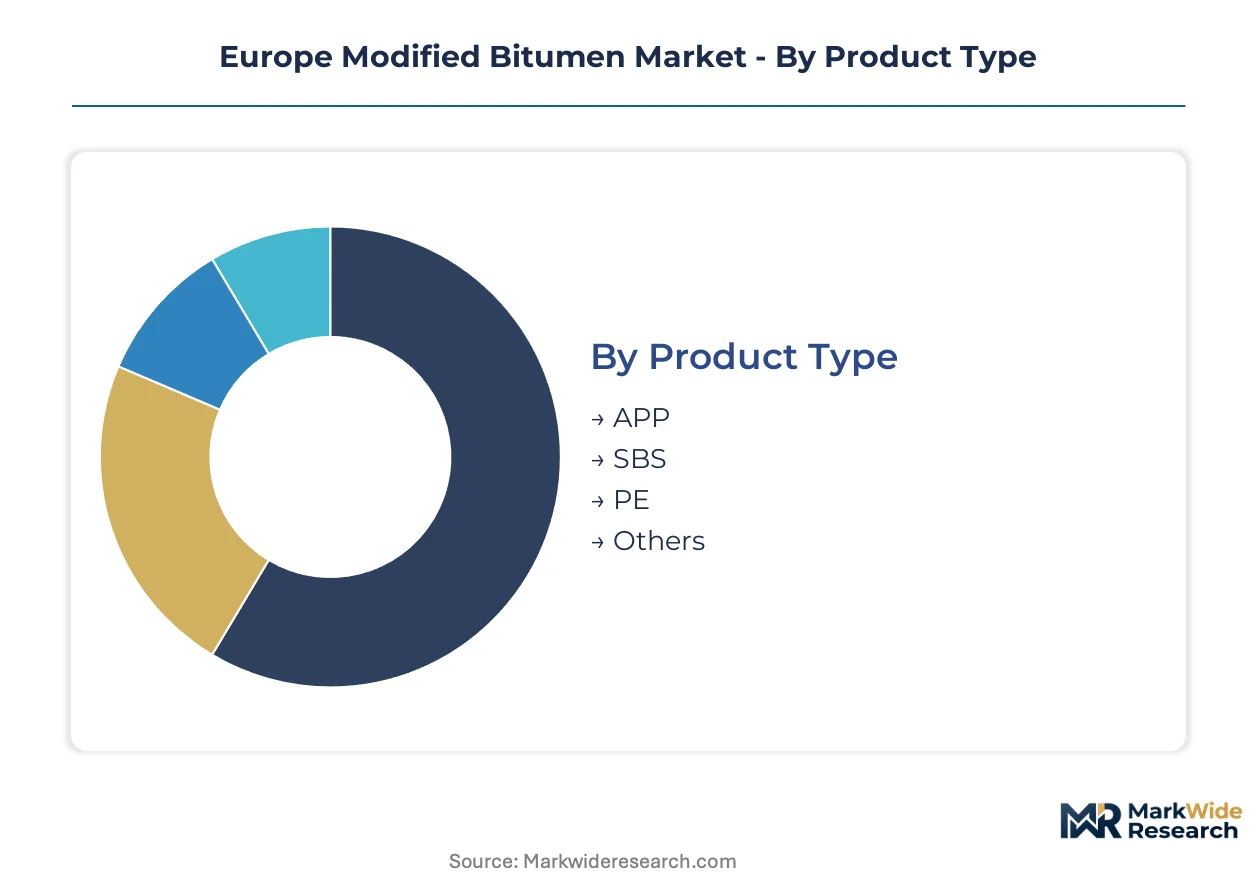
Segmentation in the Europe Modified Bitumen Market reveals distinct procurement rhythms across polymer chemistries and construction applications. Specification cycles compress where energy efficiency mandates intersect with infrastructure renewal timelines.
Product Type:
SBS modification cycles stretch across decade-long infrastructure contracts while APP formulations turn over faster in commercial roofing maintenance schedules.
- SBS:Styrene-butadiene-styrene block copolymers deliver elastic recovery above 90% and softening points exceeding 100°C. German federal highway authorities specify SBS-modified binders for autobahn surface courses where heavy freight traffic demands fatigue resistance. Nordic bridge deck applications in Sweden and Finland mandate SBS grades for freeze-thaw durability.
- APP:Atactic polypropylene modification creates plastomeric binders with superior UV stability and oxidation resistance. French commercial roofing contractors favor APP-modified membranes for flat roof installations in Mediterranean climates where thermal aging accelerates.
- PE:Polyethylene-modified bitumens offer cost positioning for municipal road maintenance contracts in Poland and Czechia.
- Others:Crumb rubber and bio-based modifiers serve circular economy procurement criteria in Dutch and Belgian public tenders.
SBS anchors the volume base while cold-processed rubber modification gains share at the steepest rate.
Application:
Waterproofing commands premium formulation complexity whereas paving volumes scale through standardized binder specifications.
- Waterproofing:Below-grade and bridge deck membrane systems require multilayer SBS formulations with polyester reinforcement. German railway platform renovations and French hospital construction drive specification intensity where leak liability exceeds material cost premiums.
- Roofing:Single-ply membrane demand concentrates in Benelux logistics facilities and German industrial parks where accelerated depreciation schedules favor 25-year warranted systems.
- Paving:Surface and binder course applications in Polish expressway construction consume volume polymer-modified grades.
- Insulation:Bituminous vapor barriers pair with rigid foam systems in Scandinavian passive house construction.
Paving generates the largest absolute tonnage while waterproofing commands the highest value per metric ton.
Technology:
Hot-mix production dominates capital-intensive infrastructure awards as cold-mix systems penetrate urban maintenance with restricted emissions windows.
- Hot Mix:Conventional plant production at 160-180°C remains mandatory for structural pavement layers in German and Austrian heavy-duty corridors. Polymer incorporation at elevated temperatures ensures homogeneous dispersion critical to performance grading.
- Membrane:Factory-manufactured SBS and APP sheets with factory-applied adhesives or torch-applied surfaces serve commercial roofing and civil engineering waterproofing. French design-build contractors increasingly specify membrane systems with project-specific CE marking documentation.
- Cold Mix:Emulsion-based and cutback systems enable pothole repair and utility reinstatement where hot-work permits are impractical.
- Coating:Liquid-applied seamless membranes protect complex geometries in heritage building renovation across Italy and Spain.
Hot-mix technology retains the installed base while membrane systems expand most quickly through bundled design-build procurement.
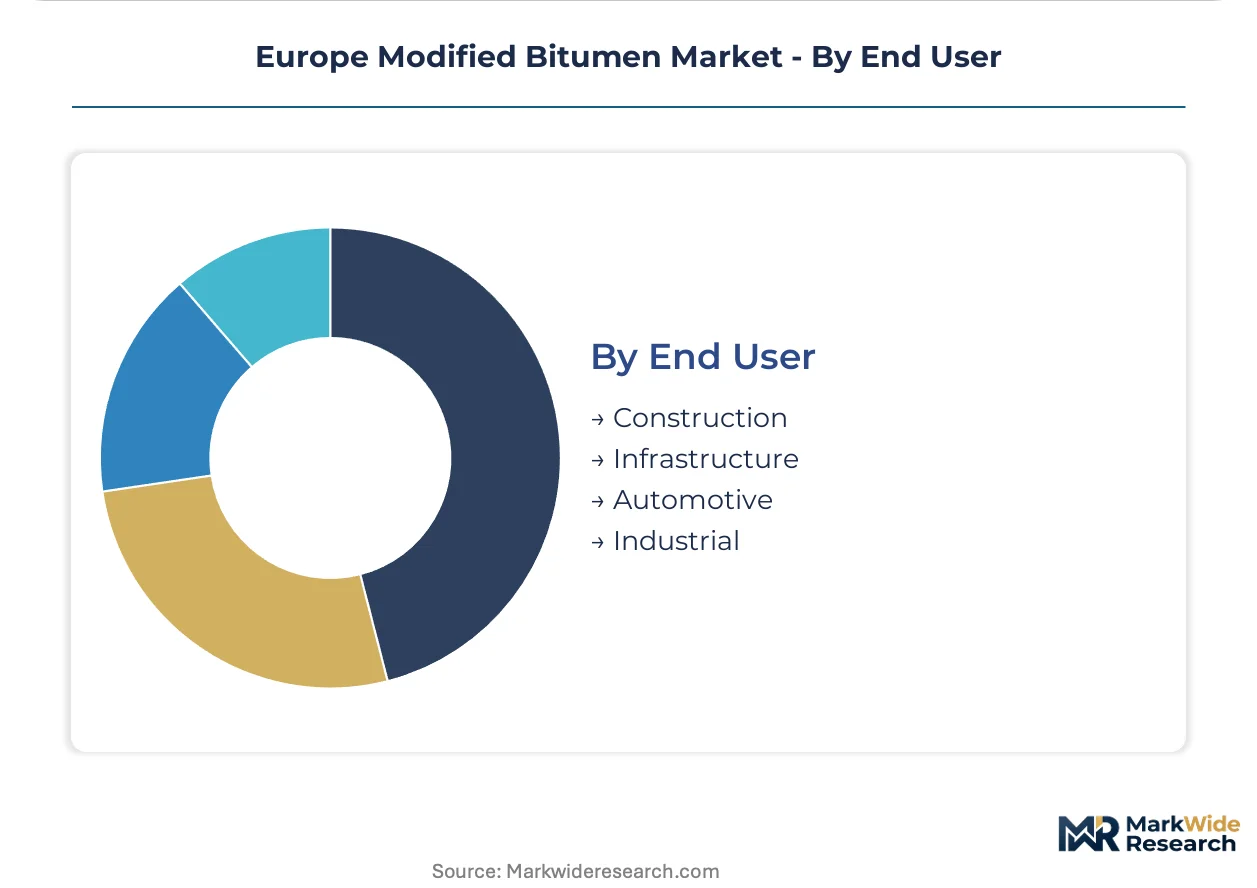
End User:
Infrastructure procurement operates on multi-year framework agreements as construction end-users fragment across project-specific spot purchasing.
- Construction:General contractors and roofing specialists in France, Germany, and Benelux source modified bitumen through merchant distribution or direct compounder relationships depending on project scale and warranty requirements.
- Infrastructure:National road agencies and municipal authorities in Poland, Czechia, and Romania specify polymer-modified binders for EU cohesion fund-backed expressway segments.
- Automotive:Underbody coatings and sound-deadening applications serve German and Czech vehicle assembly plants.
- Industrial:Tank farm linings and pipe coatings protect chemical processing assets in the Port of Rotterdam cluster and Antwerp refining corridor.
Construction channels the widest product variety while infrastructure concentrates the largest single-source contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery-polymer integration clusters in Belgium and the Netherlands concentrate feedstock supply for European compounders. National road agencies in Poland, Germany, France, and the Nordic states drive specification intensity through infrastructure procurement frameworks. Each market exhibits distinct regulatory drivers and industrial concentrations.
Germany
Federal transport investment prioritizes polymer-modified binders for autobahn durability under the Energy Performance of Buildings Directive. The Federal Highway Research Institute mandates fatigue-resistant surface courses for heavy freight corridors. Industrial concentration centers on the Rhine-Ruhr refining cluster where integrated bitumen-polymer operations serve domestic highway maintenance contracts.
Poland
EU cohesion fund disbursements are expanding expressway construction budgets beyond domestic modification capacity. The General Directorate for National Roads and Motorways specifies polymer grades for EU-backed infrastructure segments. Industrial activity clusters around Płock and Gdańsk refining corridors where ORLEN Asfalt anchors Central European supply.
France
Commercial roofing retrofits accelerate under tightened thermal efficiency mandates in the EU Green Deal building renovation targets. The Ministry of Ecological Transition enforces durability standards for public construction tenders. Design-build contractors in the Île-de-France and Auvergne-Rhône-Alpes regions increasingly source modified membranes directly from compounders.
Sweden
Extended freeze-thaw cycles mandate SBS-modified binders for bridge deck applications across the Nordic climate zone. The Swedish Transport Administration requires low-temperature performance grading for structural pavement layers. Production concentrates in Gothenburg and Stockholm corridors where naphthenic base oil availability supports high-performance formulations.
Netherlands
Circular economy procurement criteria in municipal tenders accelerate crumb rubber modification for road maintenance. The National Institute for Public Health and the Environment evaluates polycyclic aromatic hydrocarbon thresholds under REACH substance assessments. Rotterdam-Antwerp refining corridor operations supply specialty binders for Benelux waterproofing specifications.
Europe Modified Bitumen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and polymer supply. The European modified bitumen market structures around three archetypes: integrated energy majors with captive refinery-polymer operations, specialty base oil refiners focused on naphthenic grades, and regional compounders serving national infrastructure frameworks. Consolidation pressures concentrate among mid-scale compounders facing REACH registration deadlines and polymer supply vulnerabilities.
Among integrated energy majors, TotalEnergies and Shell PLC exemplify platform-scale positioning through controlled distribution networks and refinery-polymer integration. Nynas AB occupies the specialty tier as a dedicated naphthenic base oil refiner anchoring high-performance SBS formulations. These three entities represent distinct competitive vectors: vertical scope, feedstock specialization, and logistics control respectively.
| Leading Market Players |
|---|
| TotalEnergies |
| Nynas AB |
| ROSNEFT |
| Colas SA |
| ORLEN Asfalt Sp ZOO |
| Gazprom Neft PJSC |
| Shell PLC |
| Eni S.p.A. |
| Repsol |
| Others |
Supply & Pricing Matrix
Undercapacity in Central European polymer compounding is driving supplier consolidation and pricing power concentration among integrated refiners. Belgian and Dutch production clusters exploit captive feedstock access to sustain margin premiums while regional compounders absorb volatility through long-term offtake commitments.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European modified bitumen markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked membrane formulations from commodity paving grades and unregistered import alternatives. Price differentiation hinges on certification grade and polymer loading percentage, with waterproofing specifications commanding substantial premiums over municipal road contracts. Cost compression in standard-tier paving binders is intensifying because Polish infrastructure acceleration is drawing supply from domestic modification capacity. Municipal road agencies exhibit highest price sensitivity, while German federal highway authorities prioritize performance grading over unit economics.
Supply Chain Analysis
Feedstock vulnerability between Belgian SBS polymer production and Central European compounders dominates supply chain risk assessment. Geographic supply concentrates in Belgium, the Netherlands, and Germany's Rhine-Ruhr corridor. Raw material dependencies rest on naphthenic base oils, styrene-butadiene block copolymers, and crumb rubber from end-of-life tire processing. Single-source vulnerability persists for specialty polymer grades subject to REACH registration deadlines. Distribution runs through integrated refinery-direct channels for national infrastructure contracts and merchant distribution networks for commercial roofing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national specification regimes is creating niche opportunities for specialized compounders. The EU Green Deal's divergent national transpositions are multiplying certification requirements faster than integrated majors can standardize offerings.
For Market Incumbents: Pre-empt margin erosion in commodity paving grades by securing backward integration into crumb rubber processing and bio-based binder extenders. Lock in multi-year framework agreements with Polish and Romanian road agencies before EU cohesion fund disbursement peaks. Prioritize REACH-registered polymer inventories to outlast smaller compounders facing registration deadline pressure. For New Entrants and Emerging Players: Southeast European infrastructure markets remain underpenetrated by specialty waterproofing compounders. Target cold-mix technology gaps in urban maintenance contracts where hot-work restrictions limit incumbent hot-mix dominance. Enter through design-build contractor partnerships in French healthcare and logistics construction, displacing traditional merchant distribution with project-specific certification support. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane manufacturing as warm-mix additive chemistry reduces energy input requirements. Five-to-ten year viability favors compounders with verified low-emission supply chains positioned for CBAM advantage. Acquisition target archetype: mid-scale regional compounders with national infrastructure framework relationships and pending REACH registration assets. Monitor ECHA substance evaluation timelines as inflection indicator for product standard tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crumb Rubber Processing | Circular economy procurement criteria in Dutch and Belgian tenders favor tire-derived feedstock. |
| REACH Registration Portfolio Completion | ECHA deadlines are eliminating unregistered elastomer grades from roofing membrane formulations. |
| Warm-Mix Additive Technology Licensing | German autobahn authorities specify reduced-temperature paving for emissions-controlled corridors. |
| Design-Build Contractor Direct Relationships | French general contractors source modified membranes directly to reduce interface risk in healthcare construction. |
| Low-Emission Supply Chain Verification | CBAM phase-in creates first-mover advantage for compounders with carbon-border-compliant production data. |
Research Methodology
A standing panel of refinery operations managers, polymer procurement leads at roofing membrane manufacturers, national road agency specification engineers, and specialty chemical distributors provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from customs trade data, Cefic industry reports, SEC filings of integrated energy majors, and ECHA substance registration databases. Bottom-up volume modeling across polymer grades and applications triangulated against top-down infrastructure spending forecasts.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning polymer chemistry type, application category, technology format, and end-user procurement channel. CAGRs derived from polynomial trend fitting to historical volume data, adjusted for regulatory inflection points including EU Green Deal building renovation targets and REACH registration deadlines. Forecast inputs incorporated EU cohesion fund disbursement schedules and national highway maintenance budget allocations.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, crude oil price volatility, and polymer feedstock costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline adherence and infrastructure procurement continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Adblue Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Global Foundry Chemicals Market