
 Thermally Stable Antiscalant Market | 2026-2036
Thermally Stable Antiscalant Market Size, Share, and Industry Trends Forecast 2026-2036
Thermally Stable Antiscalant Market Analytics
Saudi Arabia is rewriting regional supply dynamics through petrochemical complex expansions and integrated water-energy project pipelines. BASF leverages its phosphonate and polyacrylate R&D infrastructure to sustain formulation leadership across high-temperature oilfield applications. Halliburton anchors North American market presence through direct field-service integration with shale operators. Dow Chemical Company differentiates via proprietary polymer architectures that tolerate thermal stress above 150°C in thermal desalination plants.
Thermally stable antiscalants comprise synthetic organic compounds—primarily phosphonates, polycarboxylates, and maleic acid derivatives—engineered to inhibit mineral scale precipitation at temperatures exceeding 120°C in aqueous systems. These formulations function by threshold inhibition, crystal distortion, and dispersion mechanisms that maintain heat-transfer efficiency and prevent flow-restriction in pressurized equipment. Liquid antiscalants dominate volume consumption due to ease of continuous injection in oilfield and cooling tower operations, while specialty antiscalants command premium positioning where extreme thermal cycling and complex brine chemistries demand customized molecular architectures. Powder antiscalants retain relevance in remote desalination installations where shipping weight and shelf stability outweigh handling inconvenience.
EPA effluent limitation guidelines under the Clean Water Act constrain phosphorus discharge loads from cooling systems and produced water treatment, directly shaping antiscalant biodegradability specifications. REACH registration requirements in Europe enforce full toxicological dossiers for phosphonate chemistries, elevating compliance costs for non-European suppliers while creating market access barriers. Saudi Arabia's national water regulator and the Gulf Standardization Organization collectively mandate thermal performance certification for desalination chemicals, aligning procurement with Vision 2030 localization targets. Stakeholders must monitor evolving polymer substitution trends as jurisdictions tighten phosphorus-based discharge limits without compromising scale inhibition at superheated operating conditions.
Market Dynamics
High-temperature extraction economics are forcing antiscalant reformulation as operators push thermal recovery beyond 150°C in shale formations and thermal desalination corridors. This thermal ceiling escalation compresses the performance window for conventional phosphonates while elevating polymer architecture complexity.
Growth Catalysts
- EPA effluent limitation guidelines:The Clean Water Act phosphorus discharge constraints are compelling cooling tower operators and produced water treatment facilities to specify biodegradable phosphonate alternatives, expanding the addressable market for thermally stable polymer chemistries.
- Permian Basin thermal EOR expansion:Steam-assisted gravity drainage and cyclic steam injection operations are consuming specialized antiscalants at rates that outpace conventional scale inhibitor demand in conventional extraction.
- Red Sea desalination corridor buildout:Multi-effect distillation and multi-stage flash facilities operating above 120°C are mandating thermal certification for all chemical inputs, locking in premium formulation procurement.
Market Restraints
- Phosphonate feedstock concentration:Specialty phosphonate precursors concentrate among German and Chinese chemical intermediates suppliers, exposing formulation houses to input cost volatility and force majeure risk.
- REACH registration dossier costs:Full toxicological testing requirements for phosphonate chemistries under ECHA mandates create six-figure compliance barriers for non-European suppliers seeking EU market access.
- Polymer thermal degradation ceiling:Polycarboxylate molecular architectures lose inhibition efficacy above 180°C, creating a hard technical boundary that phosphonate-sulfonate hybrids have not yet reliably breached.
Strategic Opportunities
- Vision 2030 localization mandates:Saudi Arabia's procurement rules for desalination chemicals are creating captive demand for in-country formulation and blending capacity, rewarding early manufacturing commitments.
- Geothermal brine management:Binary cycle and flash steam geothermal plants operating in Turkey and Indonesia present untapped demand for antiscalants that tolerate silica-saturated brines at 200°C-plus conditions.
- AI-driven dosage optimization:Machine learning platforms that predict scaling propensity from real-time water chemistry are enabling precision injection systems that reduce chemical consumption per barrel treated.
Industry Challenges
- Formulation chemist scarcity:The intersection of polymer science, high-temperature kinetics, and oilfield brine geochemistry demands specialized expertise that university programs are not producing at replacement rates.
- Multi-jurisdiction certification timelines:Parallel thermal performance validation requirements from Saudi Arabia's national water regulator, the Gulf Standardization Organization, and plant-level engineering specifications extend sales cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermally Stable Antiscalant Market |
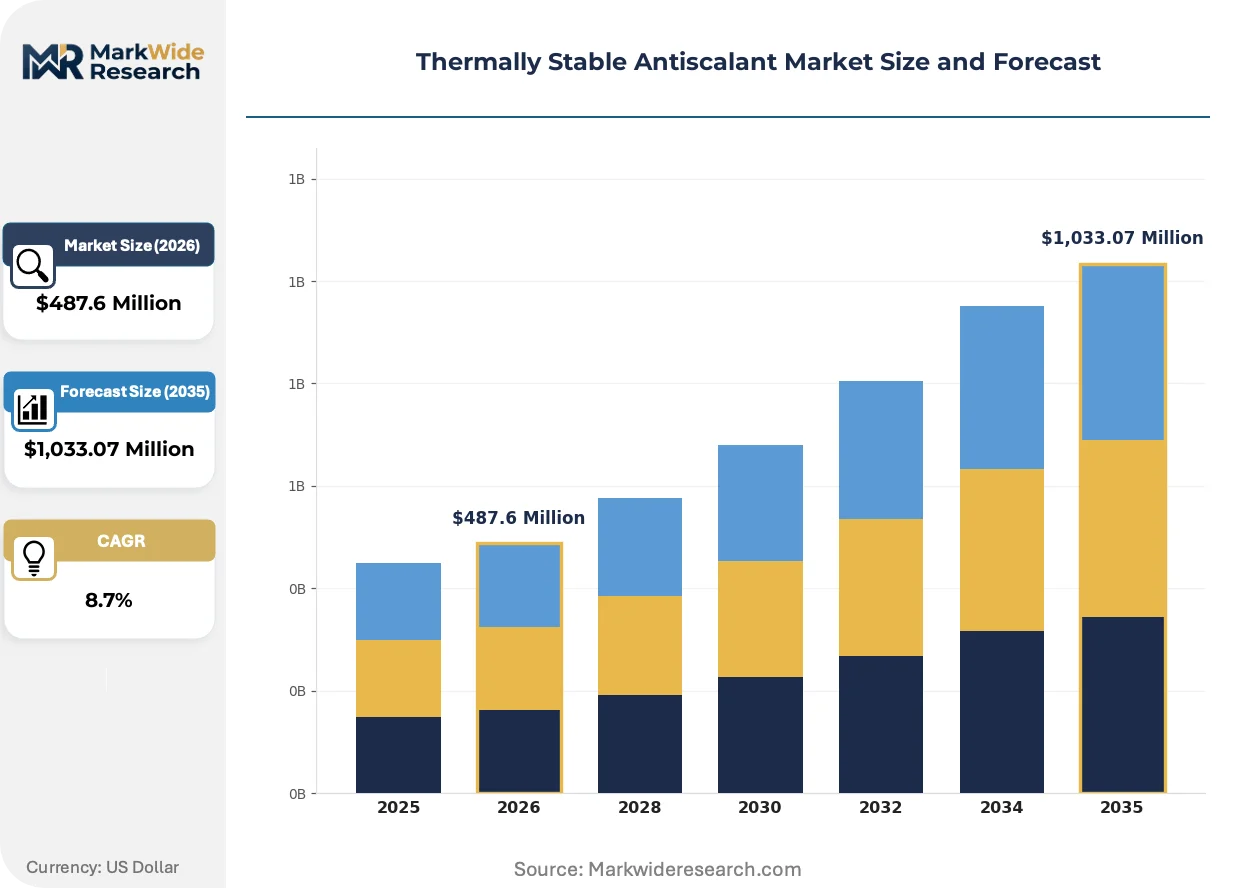
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Antiscalants, Powder Antiscalants, Solid Antiscalants, Specialty Antiscalants Application: Oil & Gas Production, Water Treatment, Desalination, Cooling Systems End User: Industrial Plants, Municipal Utilities, Energy Sector, Chemical Process Industry Distribution Channel: Direct Sales, Online Retail, Distributors, Third-Party Resellers |
| Companies Covered | BASF, Halliburton, Schlumberger, Dow Chemical Company, Nalco (Ecolab), Solenis, Kemira, Kurita Water Industries, Italmatch Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermally Stable Antiscalant Market Evolving Landscape
Formulation chemistry is pivoting toward molecular architectures that sacrifice phosphorus content for thermal resilience without compromising threshold inhibition. This shift is compressing the traditional phosphonate-dominated product hierarchy.
Phosphonobutane tricarboxylic acid and its derivatives are migrating from niche geothermal applications into mainstream thermal desalination and heavy oil extraction. Saudi Aramco's Marjan and Zuluf developments are specifying these chemistries for continuous injection at 165°C operating conditions. The technology is migrating from specialty additive status toward volume commodity positioning as procurement specifications harden around thermal certification thresholds.
REACH registration requirements under ECHA are forcing full substance dossiers for phosphonate active ingredients entering the European Economic Area. This regulatory friction is elevating compliance costs for Asian formulation houses while creating market access premiums for incumbent European suppliers with existing registrations. Thermal desalination chemical procurement in Spain and Italy is increasingly contingent upon REACH-compliant supply chain documentation.
Operator procurement teams are consolidating chemical vendor relationships around integrated field-service providers rather than standalone product suppliers. Shale operators in the Permian Basin are bundling antiscalant supply with scale monitoring, laboratory analysis, and injection equipment maintenance under multi-year performance contracts. This bundling is most pronounced in Texas and New Mexico, where direct field-service integration now determines vendor selection more than unit pricing.
Thermally Stable Antiscalant Market Segmentation
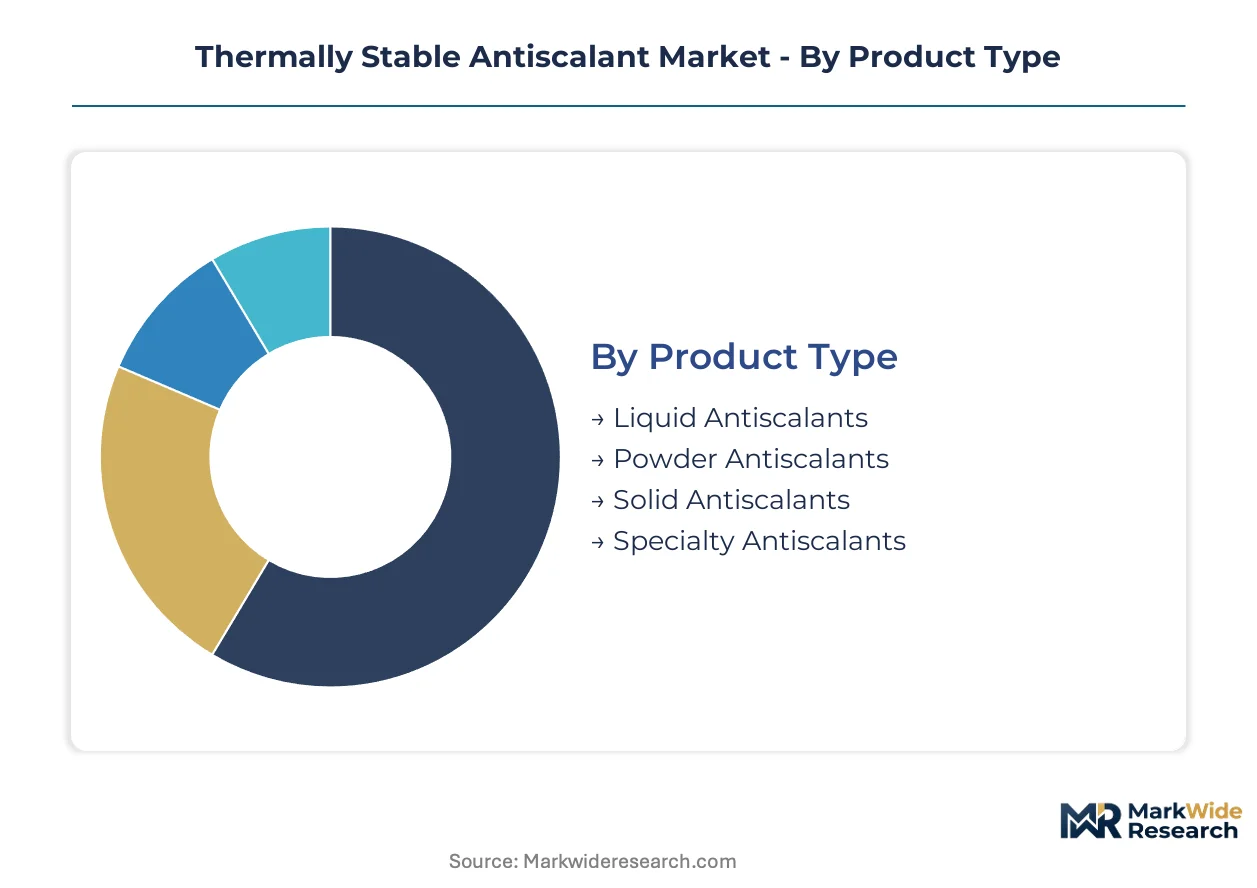
Thermally stable antiscalant procurement patterns diverge sharply across product forms and end-use environments. Each segment carries distinct formulation requirements, certification burdens, and margin structures that reshape competitive positioning.
Product Type:
Cost tier stratification separates commodity formulations from engineered specialty grades, with thermal certification thresholds acting as the primary price escalator.
- Liquid Antiscalants:These aqueous formulations—typically phosphonate or polycarboxylate concentrates at 40-60% active content—enable continuous injection via metering pumps in oilfield and cooling tower operations. Demand concentrates in the Permian Basin and Saudi Arabia's Marjan development, where field-service integration favors pump-ready delivery over on-site dilution.
- Specialty Antiscalants:Custom molecular architectures incorporating phosphonobutane tricarboxylic acid or maleic acid derivatives tolerate thermal cycling above 165°C in multi-effect distillation plants. Red Sea desalination corridors are specifying these chemistries for silica-saturated brines where conventional phosphonates degrade.
- Powder Antiscalants:Spray-dried formulations reduce shipping weight for remote desalination installations in Indonesia and Turkey, though handling complexity limits adoption outside captive industrial sites.
- Solid Antiscalants:Tablet and briquette forms serve geothermal binary cycle plants in Iceland and Kenya where automated feed systems require solid-phase delivery.
Liquid antiscalants hold installed capacity. Specialty antiscalants are rotating up the share rankings.
Application:
Application-driven specification intensity ranges from standardized cooling tower protocols to bespoke thermal desalination chemistries demanding plant-level validation.
- Desalination:Multi-stage flash and multi-effect distillation facilities operating at 120-180°C mandate thermal performance certification from Saudi Arabia's national water regulator and the Gulf Standardization Organization. Persian Gulf procurement specifications now lock in premium formulation tiers.
- Oil & Gas Production:Steam-assisted gravity drainage and cyclic steam injection in Canada's oil sands and California's Kern County consume phosphonate-sulfonate hybrids at continuous injection rates. Operators specify real-time scale monitoring integration.
- Water Treatment:Municipal and industrial reverse osmosis plants deploy standard phosphonate thresholds at sub-100°C operating windows, with EPA phosphorus discharge limits shaping biodegradable polymer substitution.
- Cooling Systems:Power plant and refinery cooling towers specify antiscalants for hardness control, though thermal stress remains moderate compared to desalination or thermal EOR.
Desalination holds installed capacity. Oil & gas production is rotating up the share rankings.
End User:
Customer type determines procurement sophistication, with energy sector buyers demanding integrated field-service bundles while municipal utilities prioritize lowest-unit-cost bidding.
- Energy Sector:Integrated oil companies and independent shale operators in Texas and New Mexico bundle antiscalant supply with laboratory analysis, scale prediction modeling, and injection equipment maintenance under multi-year performance contracts.
- Industrial Plants:Petrochemical complexes in Jubail and Yanbu specify antiscalants for process water and cooling systems, with Saudi Aramco's downstream procurement rules favoring in-country formulation capacity.
- Municipal Utilities:Spanish and Italian desalination operators under Acuamed and CAP Group procurement frameworks require REACH-compliant supply chain documentation, elevating European supplier premiums.
- Chemical Process Industry:Fertilizer and chlor-alkali producers in India and China consume antiscalants for boiler feedwater and evaporator protection, with BIS certification requirements shaping local sourcing.
Energy sector holds installed capacity. Industrial plants are rotating up the share rankings.
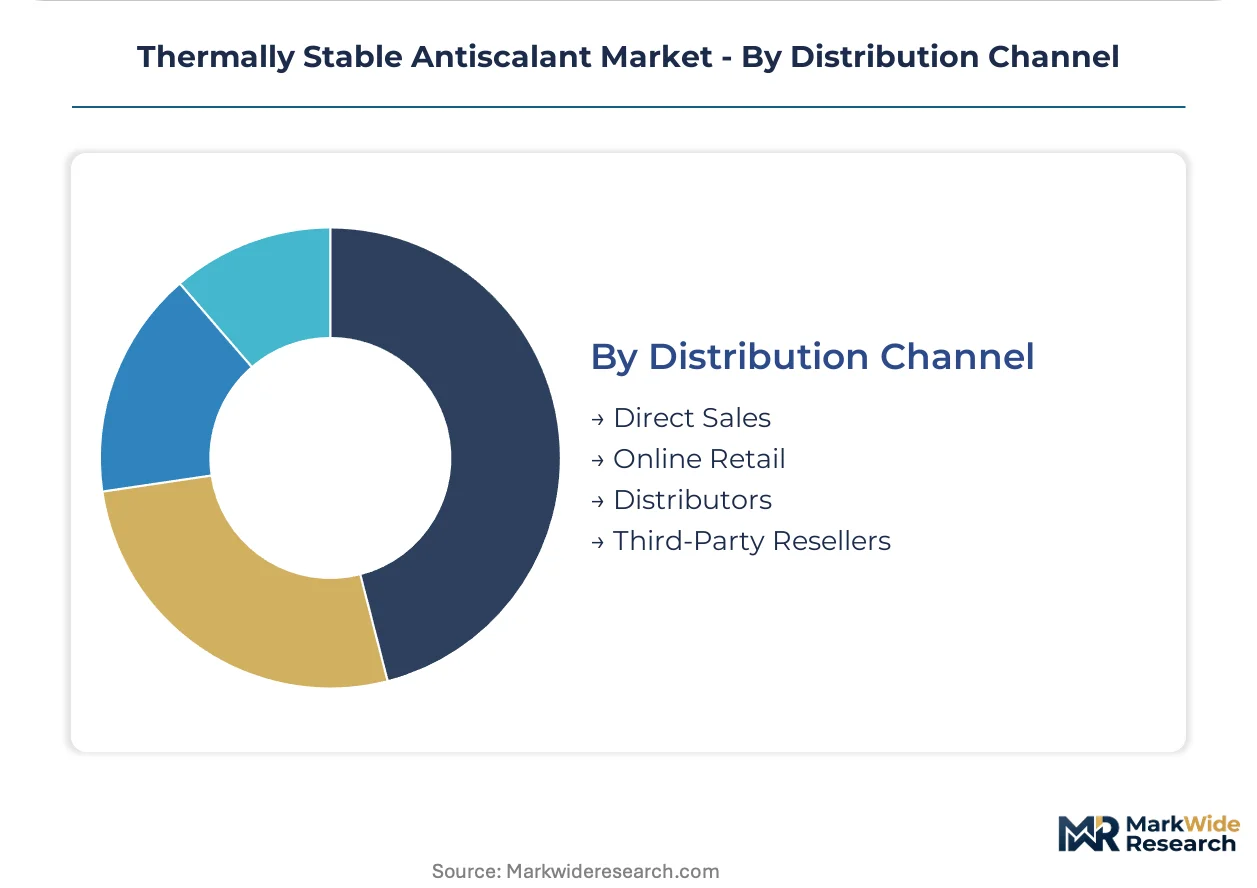
Distribution Channel:
Channel selection reflects geographic concentration of demand clusters and the technical service intensity required for high-temperature applications.
- Direct Sales:BASF, Halliburton, and Dow Chemical Company deploy technical sales engineers to anchor multi-year supply agreements with major desalination developers and shale operators, embedding dosage optimization and real-time monitoring services.
- Distributors:Regional chemical distributors in the UAE, Singapore, and Rotterdam serve mid-scale industrial accounts with standardized phosphonate formulations and local inventory positioning.
- Third-Party Resellers:Specialized oilfield service companies in Midland, Texas and Dammam, Saudi Arabia repackage bulk antiscalants for small independents lacking direct supplier relationships.
- Online Retail:E-commerce penetration remains marginal for thermally certified grades, though commodity phosphonates for sub-100°C cooling systems move through industrial chemical marketplaces.
Direct sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty phosphonate and polycarboxylate formulation capacity clusters in Germany, Saudi Arabia, and the United States, with each jurisdiction imposing distinct thermal certification and discharge compliance burdens on suppliers.
United States
Permian Basin steam-assisted gravity drainage operations consume phosphonate-sulfonate hybrids at rates outpacing conventional extraction. EPA effluent limitation guidelines under the Clean Water Act constrain phosphorus discharge from cooling towers and produced water treatment. Midland, Texas anchors North American demand through bundled field-service contracts tying antiscalant supply to real-time scale monitoring.
Saudi Arabia
Multi-effect distillation and multi-stage flash facilities along the Persian Gulf mandate thermal performance certification from the national water regulator and Gulf Standardization Organization. Vision 2030 localization rules create captive demand for in-country formulation capacity. Jubail and Yanbu petrochemical complexes specify antiscalants for process water systems exceeding 150°C operating windows.
Germany
REACH registration requirements under ECHA enforce full toxicological dossiers for phosphonate chemistries entering the European Economic Area. Specialty phosphonate precursor production concentrates among German chemical intermediates suppliers. Ludwigshafen and Leverkusen host formulation R&D infrastructure serving thermal desalination procurement in Spain and Italy.
China
Shale operators in Sichuan and Xinjiang deploy thermally stable antiscalants for high-temperature extraction trials. GB standards and MEE discharge regulations shape biodegradable polymer substitution in industrial cooling systems. Yangtze River Delta chemical complexes produce phosphonate concentrates for domestic oilfield service companies.
United Arab Emirates
Dubai and Abu Dhabi desalination operators procure REACH-compliant specialty grades for multi-stage flash plants operating above 120°C. MOHAP chemical registration requirements align procurement documentation with EU supply chain standards. Jebel Ali industrial zones concentrate blending capacity serving Red Sea corridor demand.
Thermally Stable Antiscalant Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between integrated oilfield service providers bundling antiscalant supply with field monitoring, and standalone formulation houses selling certified concentrates through distributors. Three archetypes dominate: phosphonate-centric European incumbents with REACH registrations, polymer-focused North American suppliers with Permian field-service integration, and Gulf-based blenders capitalizing on localization mandates. Competitive moves center on backward integration into phosphonate precursor production and captive supply of thermal certification laboratory services.
Within the integrated service tier, Halliburton and Schlumberger exemplify platform players embedding antiscalant supply within multi-year performance contracts. BASF occupies a position as the archetypal European formulation incumbent leveraging existing REACH dossiers for phosphonate chemistries. Dow Chemical Company represents the polymer architecture specialist, with proprietary molecular designs tolerating thermal stress above 150°C in desalination applications.
| Leading Market Players |
|---|
| BASF |
| Halliburton |
| Schlumberger |
| Dow Chemical Company |
| Nalco (Ecolab) |
| Solenis |
| Kemira |
| Kurita Water Industries |
| Italmatch Chemicals |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's specialty phosphonate precursor concentration anchors European formulation pricing power, with REACH-registered suppliers commanding premiums over Asian competitors lacking ECHA dossiers. This geographic concentration of certified active ingredient production creates tiered procurement access where thermal certification status outweighs unit cost considerations for Red Sea desalination operators.
Pricing Analysis
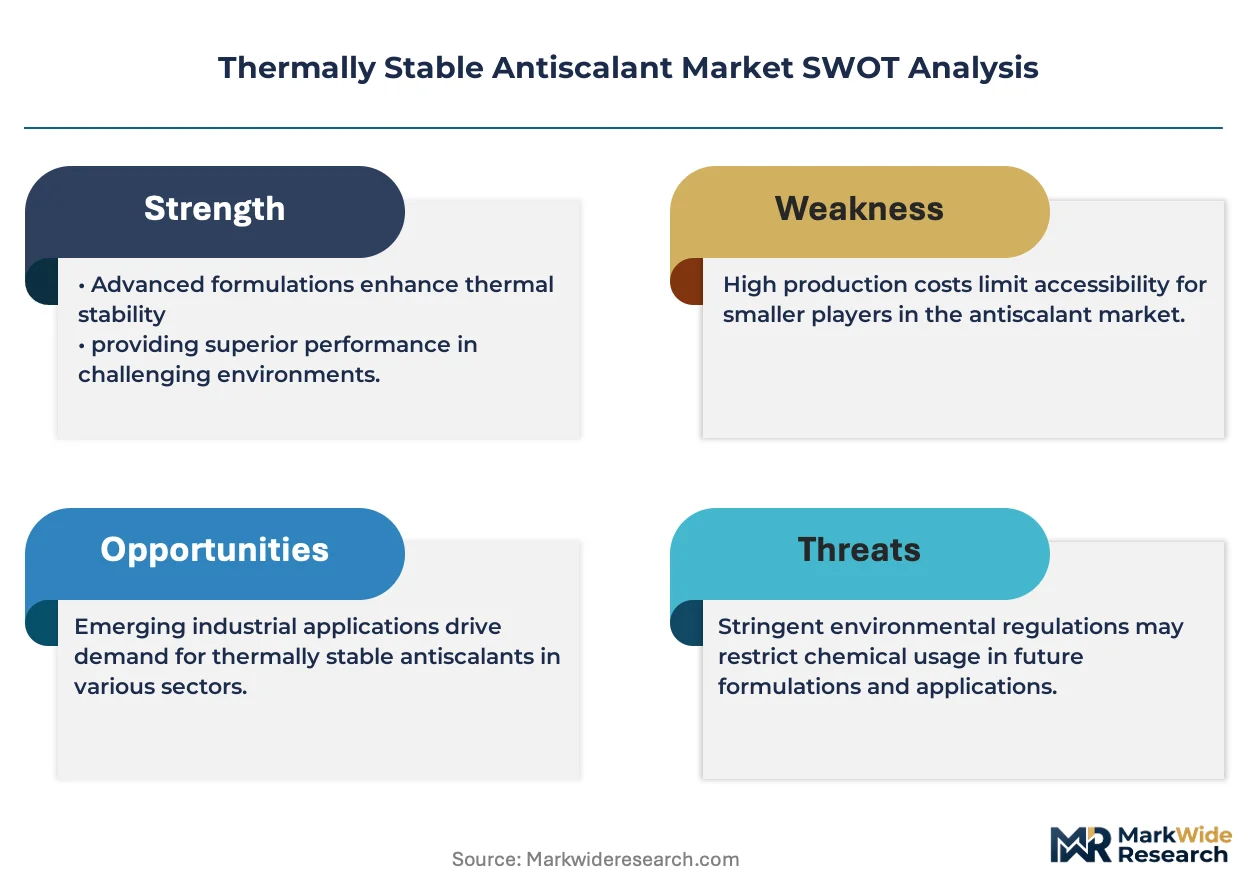
EPA effluent limitation guidelines dictate the pricing tier structure across North American procurement, separating biodegradable polymer formulations from phosphorus-heavy legacy chemistries. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels reflects thermal performance validation costs rather than raw material differentials. Pricing pressure stems from phosphonate feedstock volatility among German and Chinese intermediates suppliers. Municipal utilities exhibit highest price sensitivity through lowest-unit-cost bidding frameworks, while integrated oilfield service contracts prioritize performance guarantees over per-kilogram rates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for phosphonate concentrate imports serving Permian Basin operators. Formulation capacity concentrates in Germany, Saudi Arabia, and the United States, with specialty phosphonate precursors drawing from Yangtze River Delta chemical complexes and Ludwigshafen intermediates plants. Single-source vulnerability persists for phosphonobutane tricarboxylic acid derivatives where patent-protected synthesis routes limit supplier alternatives. Distribution runs through direct technical sales for major desalination developers and shale operators, with regional distributors serving mid-scale industrial accounts in Rotterdam and Singapore hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through procurement consolidation among Saudi Aramco's integrated water-energy developments and Permian Basin shale operators bundling chemical supply under multi-year performance contracts. This consolidation elevates vendor qualification barriers while compressing margins for standalone formulation houses lacking field-service integration.
For Market Incumbents: Pre-empt polymer substitution threats by accelerating biodegradable phosphonate alternatives through Saudi Arabia's thermal certification pipeline before REACH phosphorus discharge limits tighten across European Economic Area markets. Anchor backward integration into phosphonate precursor production to offset feedstock volatility from German and Chinese intermediates suppliers. Defend positioning through captive laboratory services offering real-time scale prediction and dosage optimization. For New Entrants and Emerging Players: Pursue geothermal brine management applications in Turkey and Indonesia where silica-saturated conditions at 200°C-plus operating windows exceed conventional phosphonate thermal ceilings. Target desalination chemical blending capacity within Saudi Arabia's Jubail and Yanbu industrial zones to capture Vision 2030 localization procurement preferences. Establish go-to-market positioning through AI-driven dosage optimization platforms that reduce chemical consumption per barrel treated. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation houses with existing REACH registrations and thermal certification laboratory infrastructure over capital-intensive backward integration plays. Long-term viability hinges on molecular architecture capabilities spanning phosphonate-sulfonate hybrids and maleic acid derivatives rather than single-chemistry dependence. Acquisition targets should demonstrate validated performance above 165°C in Saudi Aramco or Red Sea desalination reference installations. The signal to watch is procurement specification migration toward biodegradable thresholds without thermal performance compromise.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphonate Precursors | Captive supply of active ingredients insulates margins from German and Chinese intermediates volatility. |
| Thermal Certification Laboratory Investment | In-house validation capability accelerates Saudi Arabia and Gulf Standardization Organization approval timelines. |
| AI-Driven Dosage Optimization Platform | Machine learning integration reduces chemical consumption per barrel while locking in multi-year performance contracts. |
| Saudi Arabia In-Country Blending Capacity | Vision 2030 localization mandates create captive demand for domestic formulation infrastructure. |
| Biodegradable Polymer R&D Partnership | Collaboration with European universities addresses REACH phosphorus discharge limits without thermal ceiling sacrifice. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with desalination plant engineers, oilfield chemical procurement leads, thermal certification laboratory directors, and polymer formulation R&D heads; and secondary validation through customs and trade flow databases, SEC filings of listed chemical companies, ECHA REACH registration dossiers, and Gulf Standardization Organization technical specifications. Bottom-up triangulation across product form, application, and end-user segments was cross-checked against top-down market sizing from regional production capacity and consumption intensity benchmarks.
Forecast inputs incorporated thermal performance certification adoption curves, EPA effluent limitation guideline enforcement timelines, and Vision 2030 localization procurement rule implementation across the projection horizon. Segmentation modeling spanned product type, application environment, end-user procurement sophistication, and distribution channel technical service intensity. CAGRs were derived from elasticity-adjusted demand projections for high-temperature extraction and thermal desalination capacity additions, with phosphonate-polymer substitution rates and REACH compliance cost pass-through as industry-specific modifiers.
Sensitivities concentrate around regulatory enforcement acceleration in phosphorus discharge limits, force majeure events in German phosphonate precursor supply, and thermal certification timeline compression by Saudi Arabia's national water regulator. Forecasts reflect assumptions on polymer thermal degradation ceiling advancement and geothermal brine management market development. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Global Dodecanedioic Acid Market