
 Industrial Closures Market | 2026-2036
Industrial Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Closures Market Analytics
Capital-intensity divergence between large-format injection molders and precision metal-stamping specialists is bifurcating competitive tiers in industrial closures. Closure Systems International leverages captive blow-molding capacity to anchor its position in beverage and pharmaceutical packaging. Silgan Holdings sustains margin pools through backward integration into steel and aluminum substrate production. Crown Holdings competes on geographic density, operating continental-scale manufacturing networks that reduce logistics costs for multinational CPG buyers.
Industrial closures encompass mechanical and adhesive sealing devices engineered to maintain containment, pressure, or environmental isolation across packaging and equipment interfaces, typically specified by torque retention values, permeation coefficients, and material compatibility with contained substances. Polypropylene and HDPE dominate material selection for chemical-resistant snap-fit designs, while aluminum roll-on formats retain preference in carbonated beverage and aerosol applications. Plastic closures lead volume shipments across food processing and consumer goods applications, yet composite material formats represent the fastest-expanding segment as pharmaceutical brands pursue multi-layer barrier performance. Magnetic seal closures occupy concentrated margin pools in aerospace and safety systems where failure-tolerance thresholds approach zero defects.
FDA 21 CFR Part 211 and EU MDR traceability requirements shape pharmaceutical closure specifications, forcing molders to validate lot-level identification and tamper-evidence performance. EPA and REACH frameworks restrict certain phthalate plasticizers and heavy-metal stabilizers, redirecting formulation R&D toward bio-based polyesters and recycled-content resins. Stakeholders must monitor evolving extended-producer-responsibility legislation in North America and Europe, as post-consumer content mandates will restructure material sourcing decisions and capital allocation across the supply base.
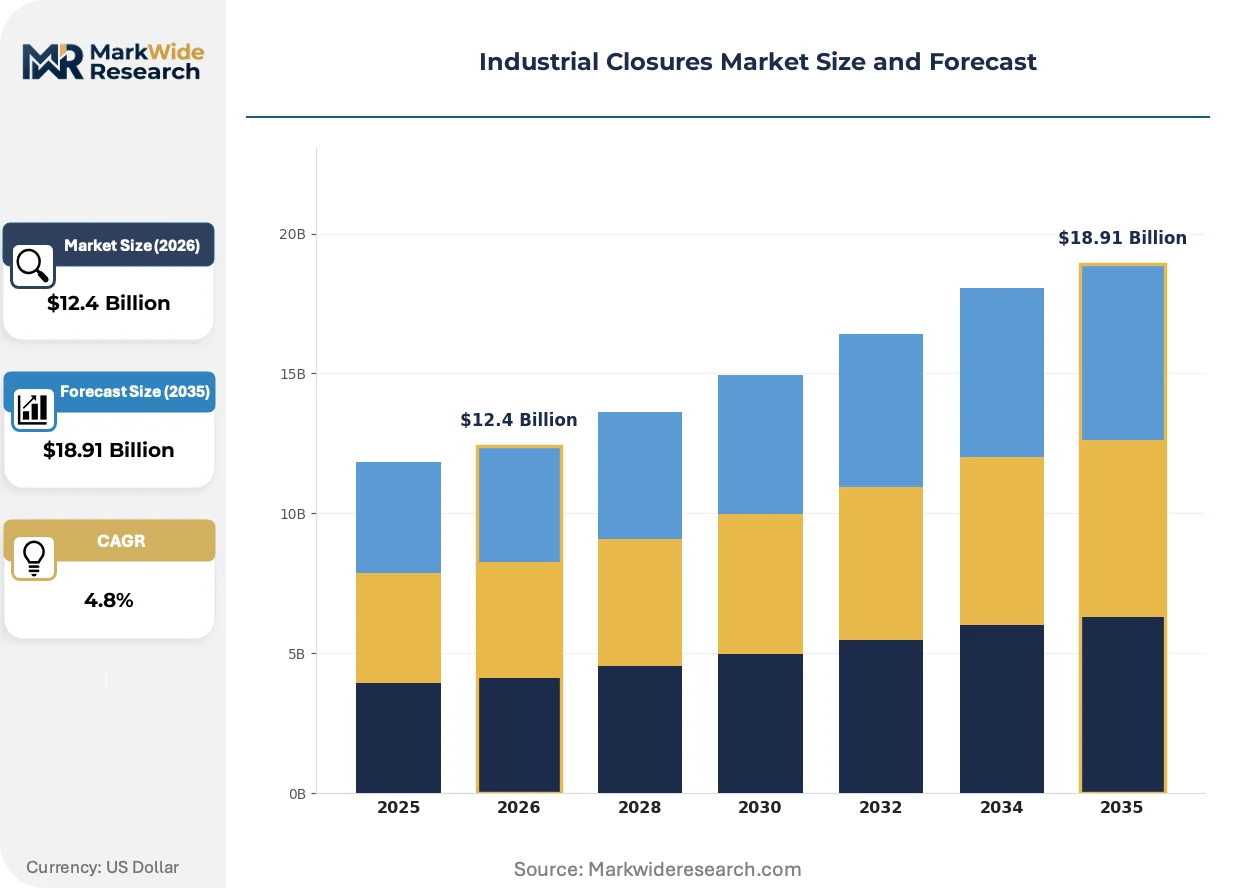
Market Dynamics
Pharmaceutical serialization mandates and Europe's F-Gas Regulation are compressing closure specification cycles while elevating integrity requirements across supply chains.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and Switzerland now require lot-level identification on every closure, forcing molders to upgrade tamper-evidence validation systems.
- India's pharmaceutical manufacturing expansion:CDSCO compliance requirements are driving procurement of high-integrity aluminum roll-on formats across Mumbai and Hyderabad packaging corridors.
- Polypropylene barrier innovations:Multi-layer co-injection molding is enabling snap-fit designs that meet carbonated beverage permeation thresholds without metal substrates.
Market Restraints
- Aluminum substrate volatility:LME price swings for rolled aluminum sheet compress margin pools for beverage closure specialists dependent on metal formats.
- German automotive corridor concentration:Magnetic seal procurement for safety-critical applications clusters around Stuttgart and Wolfsburg, creating single-source vulnerability.
- REACH phthalate restrictions:ECHA framework bans on certain plasticizers force reformulation of flexible PVC closure gaskets at 18-month validation cycles.
Strategic Opportunities
- Bio-based polyester penetration:India's PLI scheme incentives for sustainable packaging are opening procurement channels for closures with 30%+ post-consumer recycled content.
- Aerospace magnetic seal retrofit:FAA airworthiness directive cycles for aging commercial fleets are generating replacement demand for zero-defect sealing systems in Atlanta and Seattle maintenance hubs.
- Extended producer responsibility mandates:EU Green Deal packaging regulations will require closed-loop material flows, rewarding molders with captive recycling infrastructure.
Industry Challenges
- Serialization engineering talent scarcity:FDA 21 CFR Part 211 validation protocols require specialists in track-and-trace integration that command premium compensation in Boston and Basel clusters.
- Legacy equipment retrofit complexity:Pharmaceutical lines running 1990s-era injection systems face 14-month certification timelines to meet EU MDR tamper-evidence standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Closures Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Mechanical Locks, Magnetic Seals, Snap-fit Closures, Adhesive Seals Material: Plastic, Metal, Glass, Composite End User: Aerospace, Automotive, Food Processing, Pharmaceutical Application: Packaging, Industrial Equipment, Consumer Goods, Safety Systems |
| Companies Covered | Closure Systems International, Silgan Holdings, Crown Holdings, AptarGroup, Berry Global, Amcor, BERICAP, Guala Closures Group, ALPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Closures Market Evolving Landscape
Closure engineering is pivoting from commodity containment toward functional integration, with smart sealing and sustainable materials commanding specification priority across pharmaceutical and beverage procurement desks.
Smart closure systems embedding NFC chips and temperature-logging sensors are fragmenting traditional price structures in cold-chain pharmaceutical distribution. Biologics shippers in Germany and Massachusetts now specify active closures that transmit breach alerts to ERP systems. This sensor integration is fragmenting procurement relationships, as IT-fluent packaging engineers displace conventional purchasing managers in supplier selection.
REACH framework amendments restricting per- and polyfluoroalkyl substances are forcing fluoropolymer gasket substitutions in chemical processing closures. ECHA's 2023 restriction proposal targets PTFE linings used in aggressive solvent containment. German chemical processors are accelerating validation of ceramic-coated metal alternatives ahead of enforcement deadlines.
CPG buying consortiums are consolidating closure procurement across multinational brand portfolios, compressing supplier rosters from twelve vendors to three approved partners. Nestlé and Unilever's joint tender processes in 2024 established unified torque-retention specifications across European bottling networks. This concentration is most visible in France and Italy, where regional co-packers must now certify against buyer-mandated performance matrices rather than national standards.
Industrial Closures Market Segmentation
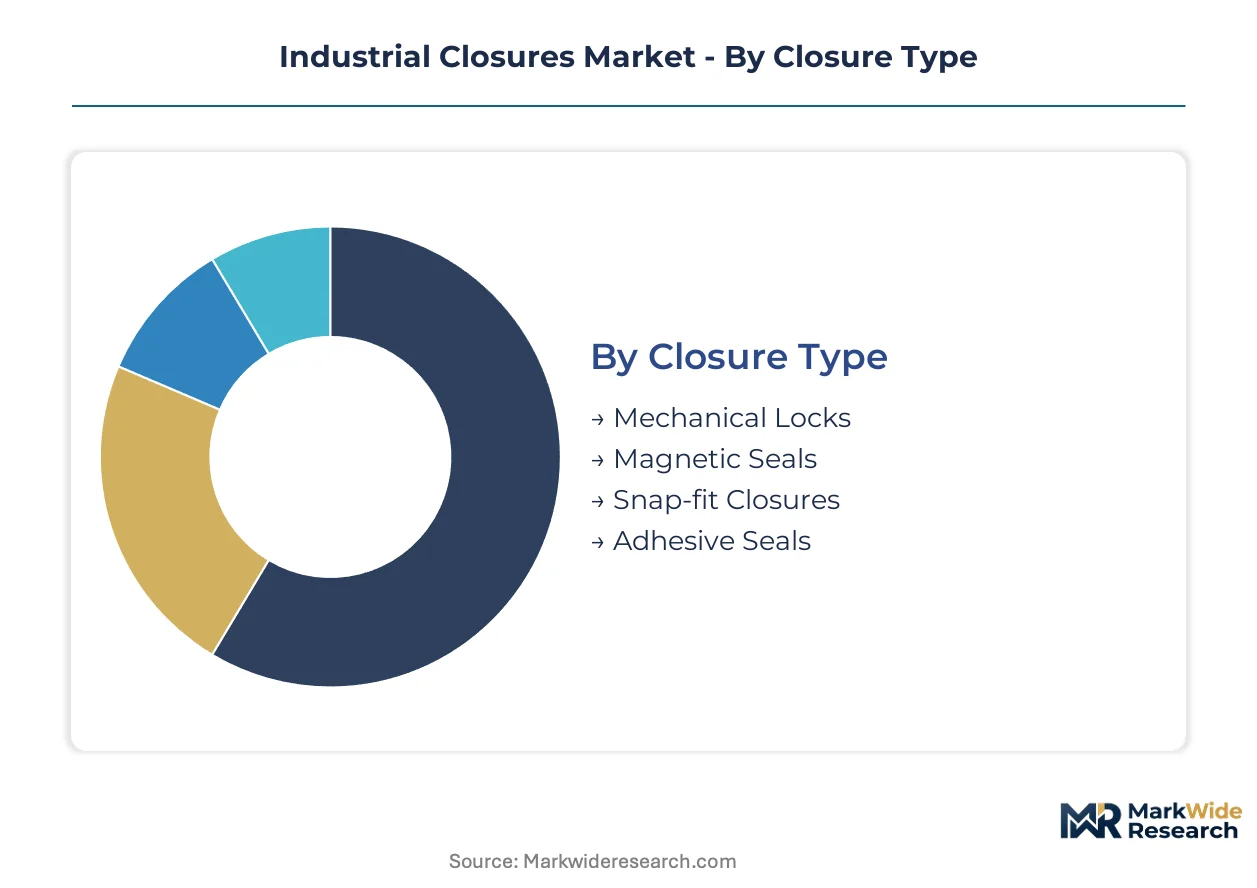
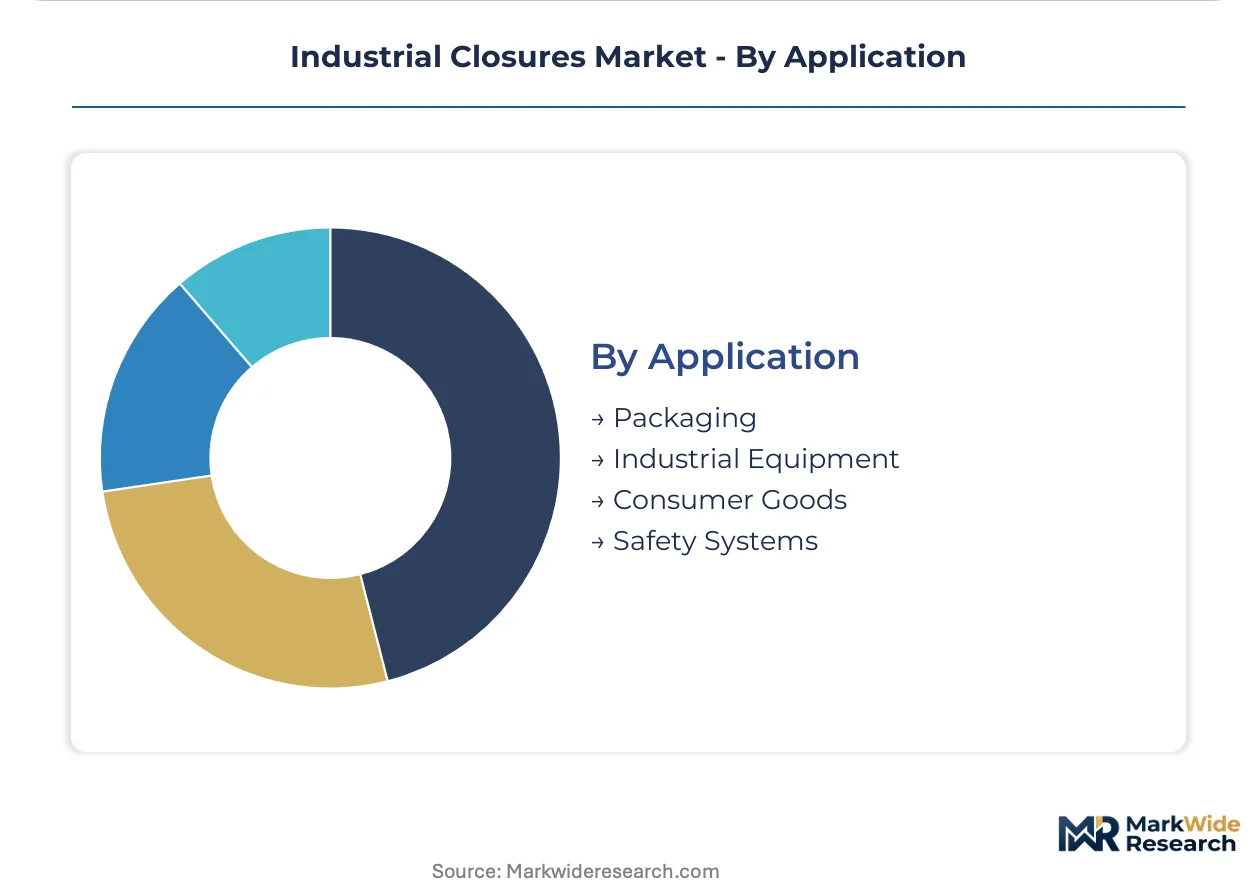
Closure specification varies dramatically across torque retention, permeation resistance, and regulatory compliance requirements. Procurement desks segment suppliers by failure-tolerance thresholds rather than commodity pricing alone.
Closure Type:
Margin pools concentrate in zero-defect formats where aerospace and pharmaceutical buyers accept premium positioning for validated performance.
- Magnetic Seals:Rare-earth alloy formulations bonded to ferrous substrates deliver hermetic sealing under vibration and thermal cycling. Stuttgart automotive safety systems and Seattle aerospace maintenance hubs specify these for failure-intolerant applications where single-defect liability exceeds component cost by orders of magnitude. FAA airworthiness directives and EASA certification cycles sustain replacement demand at contracted price premiums.
- Snap-fit Closures:Polypropylene and HDPE injection-molded designs with integral living hinges enable tool-free access in high-throughput packaging. Mumbai pharmaceutical belt and German beverage corridors drive procurement volume, though REACH phthalate restrictions force 18-month reformulation cycles on flexible gasket variants. Multi-layer co-injection molding is compressing metal closure share in carbonated applications.
- Mechanical Locks:Threaded metal and polymer formats specified by torque-retention values dominate industrial equipment access panels.
- Adhesive Seals:Pressure-sensitive and heat-activated bonding systems serve single-use pharmaceutical and diagnostic packaging where resealability is not required.
The dominant share belongs to Snap-fit Closures, while Magnetic Seals are closing the gap fastest through aerospace retrofit cycles and automotive safety mandates.
Material:
Cost tiers separate by substrate volatility and recycling infrastructure access rather than performance alone.
- Plastic:Polypropylene and HDPE lead volume through snap-fit dominance in food processing and consumer goods, with bio-based polyester variants gaining specification under India's PLI scheme incentives. Post-consumer recycled content mandates across EU packaging regulations are restructuring compounder supply relationships.
- Metal:Aluminum roll-on formats retain preference in carbonated beverage and aerosol applications where permeation coefficients must approach zero. LME price volatility compresses margin pools for specialists without backward integration into substrate production.
- Composite:Multi-layer barrier constructions combining polymer substrates with metallized or ceramic coatings represent the steepest expansion trajectory as pharmaceutical brands pursue serialization-compatible tamper-evidence.
- Glass:Borosilicate and soda-lime formats serve specialized pharmaceutical and laboratory containment with chemical inertness requirements.
Plastic commands the volume base, though Composite materials are expanding most quickly through pharmaceutical multi-layer specifications.
End User:
Customer type determines validation burden and contract duration more than unit economics.
- Pharmaceutical:FDA 21 CFR Part 211 and EU MDR traceability requirements force lot-level identification and tamper-evidence validation systems. Boston and Basel clusters compete for scarce serialization engineering talent.
- Aerospace:Zero-defect magnetic seal procurement clusters around Atlanta and Seattle maintenance hubs under FAA directive cycles.
- Automotive:Stuttgart and Wolfsburg corridors concentrate magnetic seal demand for safety-critical applications with single-source vulnerability risks.
- Food Processing:High-throughput snap-fit and roll-on formats serve CPG consolidation trends where buying consortiums compress supplier rosters.
Pharmaceutical procurement carries the highest specification burden, while Aerospace is gaining specification priority through fleet retrofit mandates.
Application:
Volume concentration diverges from value concentration across containment versus functional integration use cases.
- Packaging:Beverage and pharmaceutical formats dominate shipment volume, with smart closure embedding NFC and temperature sensors fragmenting traditional price structures in cold-chain biologics distribution.
- Safety Systems:Aerospace and automotive magnetic seals occupy concentrated margin pools where failure tolerance thresholds approach zero defects.
- Industrial Equipment:Mechanical access panel closures serve capital goods manufacturers with extended validation cycles.
- Consumer Goods:Commodity snap-fit designs face procurement consolidation through multinational CPG tender processes.
Packaging generates the shipment volume base, while Safety Systems commands the premium tier through functional integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's pharmaceutical belt demonstrate acute price sensitivity on commodity snap-fit formats, while aerospace procurement in Germany and the United States accepts substantial premiums for validated zero-defect magnetic seals. This elasticity divergence shapes regional competitive positioning across material tiers and specification cycles.
Germany
Automotive safety systems in Stuttgart and Wolfsburg drive magnetic seal procurement for failure-intolerant applications. The F-Gas Regulation and EU MDR compliance requirements compress specification cycles for high-integrity sealing solutions. Bavaria's automotive corridor concentrates demand where single-source vulnerability risks elevate contract premiums.
United States
FAA airworthiness directives for aging commercial fleets generate replacement demand in Atlanta and Seattle maintenance hubs. FDA 21 CFR Part 211 validation protocols force lot-level identification systems on pharmaceutical molders. Boston's serialization engineering cluster competes for scarce talent commanding premium compensation.
India
CDSCO compliance requirements across Mumbai and Hyderabad packaging corridors drive aluminum roll-on format procurement for pharmaceutical exports. The PLI scheme incentivizes sustainable packaging with post-consumer recycled content mandates. Maharashtra's pharmaceutical manufacturing belt expands closure procurement as serialization tightens.
Switzerland
Swissmedic traceability mandates and EU MDR alignment force tamper-evidence validation upgrades across Basel's medical device manufacturers. Precision molders serving pharmaceutical multinationals face compressed certification timelines. The Basel cluster competes with Boston for serialization engineering specialists.
China
NMPA serialization requirements and dual carbon goals redirect formulation R&D toward bio-based polyesters and recycled-content resins. Yangtze River Delta packaging corridors scale multi-layer co-injection molding for carbonated beverage applications. SAMR enforcement of post-consumer content mandates restructures material sourcing decisions.
Industrial Closures Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the industrial closures landscape. Large-format injection molders with captive blow-molding capacity compete on throughput scale, while precision metal-stamping specialists command premium positioning through validated zero-defect performance. Three archetypes dominate: backward-integrated substrate producers, geographic-density network operators, and functional-integration specialists embedding smart sensors. Competitive moves concentrate on portfolio diversification into composite multi-layer formats and strategic partnerships for closed-loop recycling infrastructure.
Among North American packaging conglomerates, Closure Systems International and Crown Holdings occupy positions exemplifying scale-driven network density, while Silgan Holdings represents backward-integrated margin defense through captive steel and aluminum substrate production. These three anchors illustrate how competitive positioning diverges between throughput optimization and upstream supply control.
| Leading Market Players |
|---|
| Closure Systems International |
| Silgan Holdings |
| Crown Holdings |
| AptarGroup |
| Berry Global |
| Amcor |
| BERICAP |
| Guala Closures Group |
| ALPLA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between beverage CPG buyers and aluminum roll-on specialists lock in both substrate access and price visibility across the LME volatility cycle. These arrangements concentrate procurement power with backward-integrated molders in Germany and India while compressing margin pools for spot-market dependent specialists.
Pricing Analysis
After-sales validation services and extended tamper-evidence certification contracts drive lifetime value beyond unit shipments. Three-tier pricing structure across aerospace-grade magnetic seals, pharmaceutical composite formats, and commodity snap-fit closures separates failure-tolerance thresholds. Price differentiation hinges on FDA 21 CFR Part 211 validation tier and captive recycling infrastructure access. Cost compression in aluminum-dependent beverage closures is intensifying because LME price swings compress margin pools for non-integrated specialists. Food processing buyers demonstrate acute price sensitivity on polypropylene snap-fit formats, while aerospace procurement in Germany and the United States accepts substantial premiums for zero-defect magnetic seals.
Supply Chain Analysis
Germany and India anchor high-integrity closure manufacturing for automotive safety systems and pharmaceutical exports respectively. Raw material flows draw from LME-traded aluminum sheet, bio-based polyester compounds, and rare-earth magnetic alloys. Single-source vulnerability clusters around Stuttgart automotive corridors where magnetic seal procurement concentrates. Distribution runs through continental-scale manufacturing networks that reduce logistics costs for multinational CPG buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart closure sensor integration and serialization validation services represent a service-attach opportunity expanding faster than hardware unit growth. Recurring revenue from temperature-logging subscriptions and ERP system integration contracts is displacing transactional procurement relationships.
For Market Incumbents: Consolidate captive recycling infrastructure to meet EU Green Deal packaging regulations and defend margin pools against bio-based polyester entrants. Backward integration into aluminum substrate production shields against LME volatility while certification investment in EU MDR traceability systems locks in pharmaceutical contract renewals.
For New Entrants and Emerging Players: Serialization engineering talent scarcity in Boston and Basel clusters offers a service-layer gap where incumbents under-serve pharmaceutical molders needing FDA 21 CFR Part 211 validation support. Target India's PLI scheme incentives for sustainable packaging with post-consumer recycled content closures. Partner with CDSCO-registered pharmaceutical exporters in Mumbai and Hyderabad corridors as the go-to-market anchor.
For Investors and Strategic Acquirers: Capital is best deployed toward precision metal-stamping specialists with validated zero-defect performance in aerospace magnetic seals. Long-term viability rests on FAA airworthiness directive replacement cycles and automotive safety mandate expansion. Watch for ECHA REACH amendments targeting fluoropolymer gasket substitutions as an inflection indicator for ceramic-coated metal alternative adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrate | Shields margin pools from LME volatility for beverage closure specialists. |
| Smart Sensor Platform Integration | Enables NFC-enabled temperature logging for cold-chain biologics distribution. |
| EU MDR Certification Pathway | Locks in pharmaceutical contract renewals through lot-level traceability validation. |
| Captive Recycling Infrastructure Buildout | Qualifies molders for EU Green Deal extended producer responsibility mandates. |
| Joint Venture for Rare-Earth Magnetic Alloys | Secures supply for aerospace zero-defect seal production in Stuttgart corridor. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with closure procurement managers at pharmaceutical multinationals, beverage CPG category buyers, and aerospace maintenance directors; and secondary validation against FDA 21 CFR filings, ECHA REACH restriction proposals, CDSCO export registrations, and SEC 10-K disclosures from substrate-integrated packaging conglomerates. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Across the projection horizon, the analytical framework segmented by closure type, material substrate, end-user industry, and regional regulatory cluster. CAGRs were derived from trend extrapolation of pharmaceutical serialization mandate adoption curves and aerospace fleet retrofit cycles. Modeled inputs included aluminum LME price trajectory assumptions and bio-based polyester compound availability under India's PLI scheme.
Forecasts assume regulatory continuity in FDA 21 CFR Part 211, EU MDR, and REACH frameworks; material policy shifts such as accelerated ECHA fluoropolymer bans or expanded F-Gas Regulation scope would require re-modeling. Recalibration cycles align with material shifts in serialization engineering talent availability and aerospace maintenance hub demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Indonesia Construction Chemicals Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Reconditioned Drums Market