
 Electrostatic Liquid Cleaner Market | 2026-2036
Electrostatic Liquid Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Liquid Cleaner Market Insights
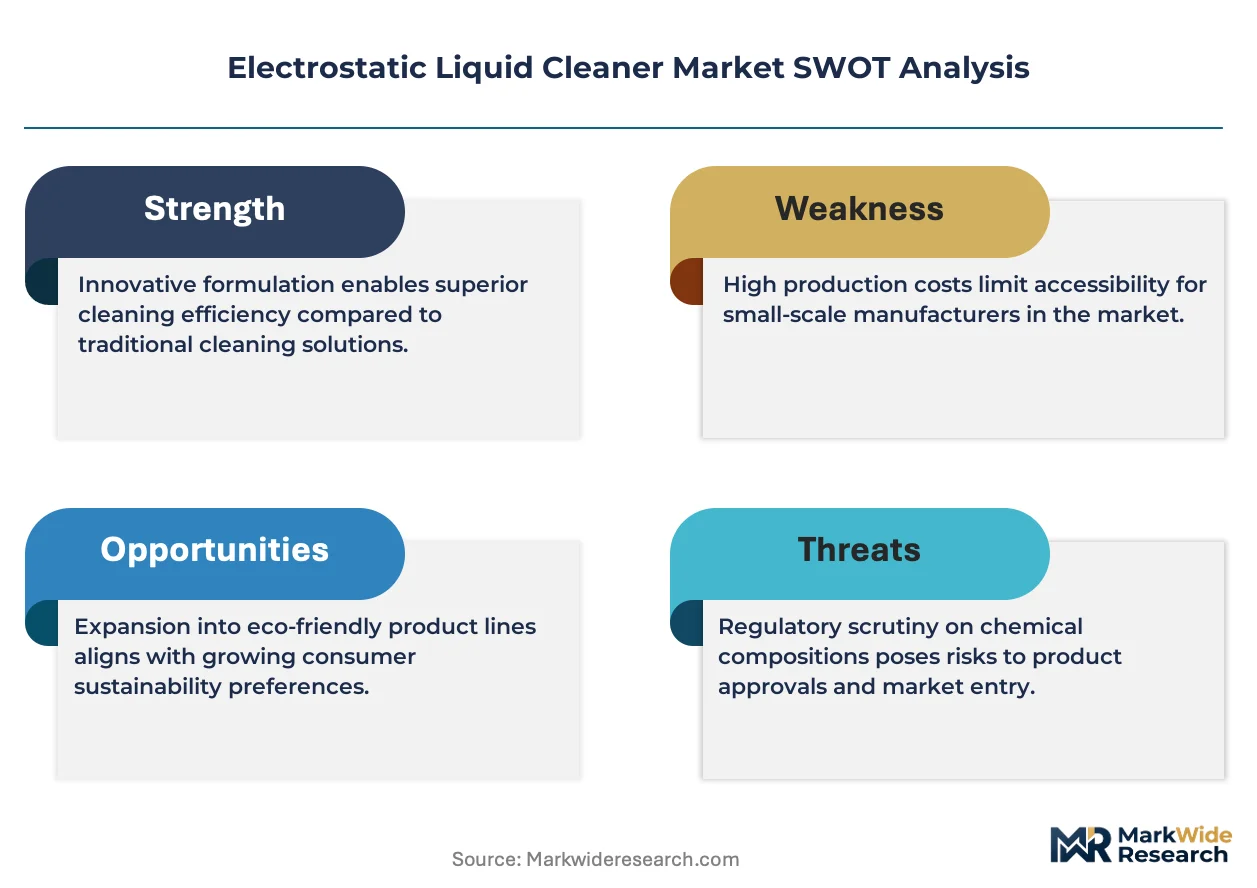
The premium stationary segment is rebalancing away from commodity portable units as semiconductor plants demand sub-micron particle capture with real-time monitoring. Kleentek leverages its induction charging expertise to anchor high-margin contracts in European automotive workshops. FRIESS competes through backward integration into corona discharge power supply manufacturing, while OILKLEEN sustains dominance in Asian electronics manufacturing corridors with localized service networks.
An electrostatic liquid cleaner employs high-voltage corona discharge or induction charging to ionize liquid droplets, creating charged mist that attracts and neutralizes airborne particulates through electrostatic precipitation; typical systems operate at 20-100 kV with liquid resistivity below 10^5 ohm-cm to ensure stable charge injection. Corona discharge technology leads in semiconductor plant installations where particle counts below ISO Class 3 demand predictable ion density, while automated configurations capture the fastest expansion as paint booths in automotive workshops replace manual handheld units to meet throughput targets. Stationary systems occupy the deepest margin pools due to captive consumables and multi-year service contracts.
EPA NESHAP standards for hazardous air pollutants in coating operations mandate particulate capture efficiency above 95%, directly elevating demand for certified electrostatic systems in US automotive workshops. REACH restrictions on volatile organic compounds in Europe push paint booth operators toward closed-loop liquid cleaning architectures that eliminate solvent-based alternatives. Semiconductor plants must align with ISO 14644 cleanroom classifications, a requirement that filters equipment procurement toward validated electrostatic mist systems. Stakeholders should track how dual carbon goals in China and the EU Green Deal reshape energy consumption benchmarks for high-voltage cleaning equipment.
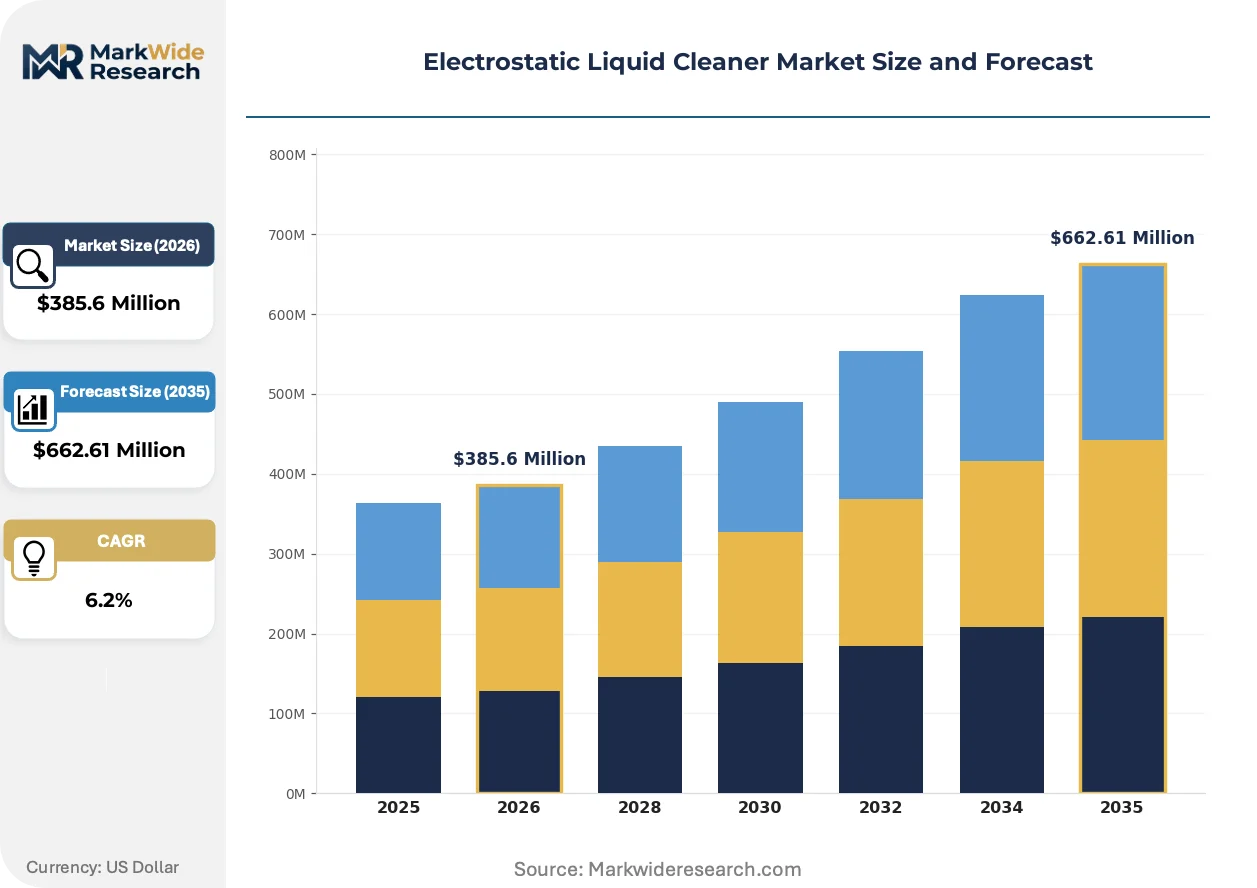
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are consolidating procurement around automated electrostatic systems with integrated real-time particle monitoring, compressing vendor margins on portable units while elevating multi-year service contracts for stationary installations.
Growth Catalysts
- EPA NESHAP mandates:US coating operations must achieve 95% particulate capture efficiency, forcing automotive paint booths toward certified electrostatic mist systems.
- REACH VOC restrictions:European operators face solvent elimination requirements that elevate closed-loop liquid cleaning architectures over traditional alternatives.
- ISO 14644 alignment:Semiconductor cleanroom classifications in East Asian manufacturing clusters filter equipment procurement toward validated electrostatic precipitation systems.
Market Restraints
- High-voltage power supply concentration:Corona discharge system manufacturers depend on specialized transformer suppliers concentrated in Germany and Japan.
- Liquid resistivity sensitivity:Operational stability requires feedstock below 10^5 ohm-cm, limiting deployment in regions with variable water quality.
- Electrode degradation costs:Corona wire replacement cycles every 18-24 months impose predictable but significant lifecycle expenses on continuous-operation facilities.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor and component assembly create first-mover positioning for localized electrostatic cleaning deployment.
- Battery cell coating expansion:Electrode manufacturing for electric vehicle batteries applies thin-film coating processes that demand contamination control without solvent emissions.
- EU Green Deal energy benchmarks:Efficiency standards for industrial equipment favor high-voltage cleaning systems with regenerative power recovery over compressed-air alternatives.
Industry Challenges
- Corona physics expertise shortage:System optimization requires specialists in ion density modeling and electrode geometry design that outpaces vocational training pipelines.
- Legacy paint booth retrofit complexity:Existing solvent-based infrastructure in automotive workshops demands costly reconfiguration to accommodate closed-loop liquid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Liquid Cleaner Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $662.61 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Handheld, Automated Technology: Corona Discharge, Induction Charging, Spray Charging, Needle Charging Application: Electronics Manufacturing, Paint Booths, Food Processing, Textile Treatment End User: Semiconductor Plants, Automotive Workshops, Food Packaging Units, Textile Mills |
| Companies Covered | Kleentek, FRIESS, Cee Dee Vacuum, OILKLEEN, Turbotect, PECD, Envair, Ferrocare, Rotomatik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Liquid Cleaner Market Trends and Innovations
Electrostatic liquid cleaning is pivoting from standalone hardware toward integrated contamination management platforms, with sensor fusion and predictive maintenance reshaping how fabs and workshops contract for cleanliness outcomes.
Induction charging technology is electrifying precision cleaning in European automotive workshops, replacing corona discharge in applications where electrode maintenance disrupts continuous production schedules. Tier-1 suppliers in Germany and Spain are specifying induction-based systems for new paint line installations. This shift is electrifying competitive positioning among equipment vendors, compressing margins on legacy corona units while rewarding firms with proprietary induction coil designs.
REACH restrictions on volatile organic compounds are tightening compliance windows for European coating operations, eliminating solvent-based cleaning alternatives by 2027 in several member states. Paint booth operators in France and Italy are accelerating capital commitments to closed-loop electrostatic architectures. Semiconductor packaging facilities in Ireland and the Netherlands face parallel pressure from ECHA substance restrictions, redirecting procurement toward liquid-based particle capture that avoids filtered exhaust complications.
Service contract unbundling is fragmenting traditional vendor-customer relationships in East Asian electronics corridors. Taiwanese and South Korean fabs are separating equipment procurement from consumables and maintenance, forcing suppliers to compete on discrete performance metrics rather than bundled lifecycle pricing. This pattern is most visible in Hsinchu and Pyeongtaek manufacturing clusters, where procurement teams now benchmark ion density consistency and electrode replacement response times as standalone contract variables.
Electrostatic Liquid Cleaner Market Segmentation
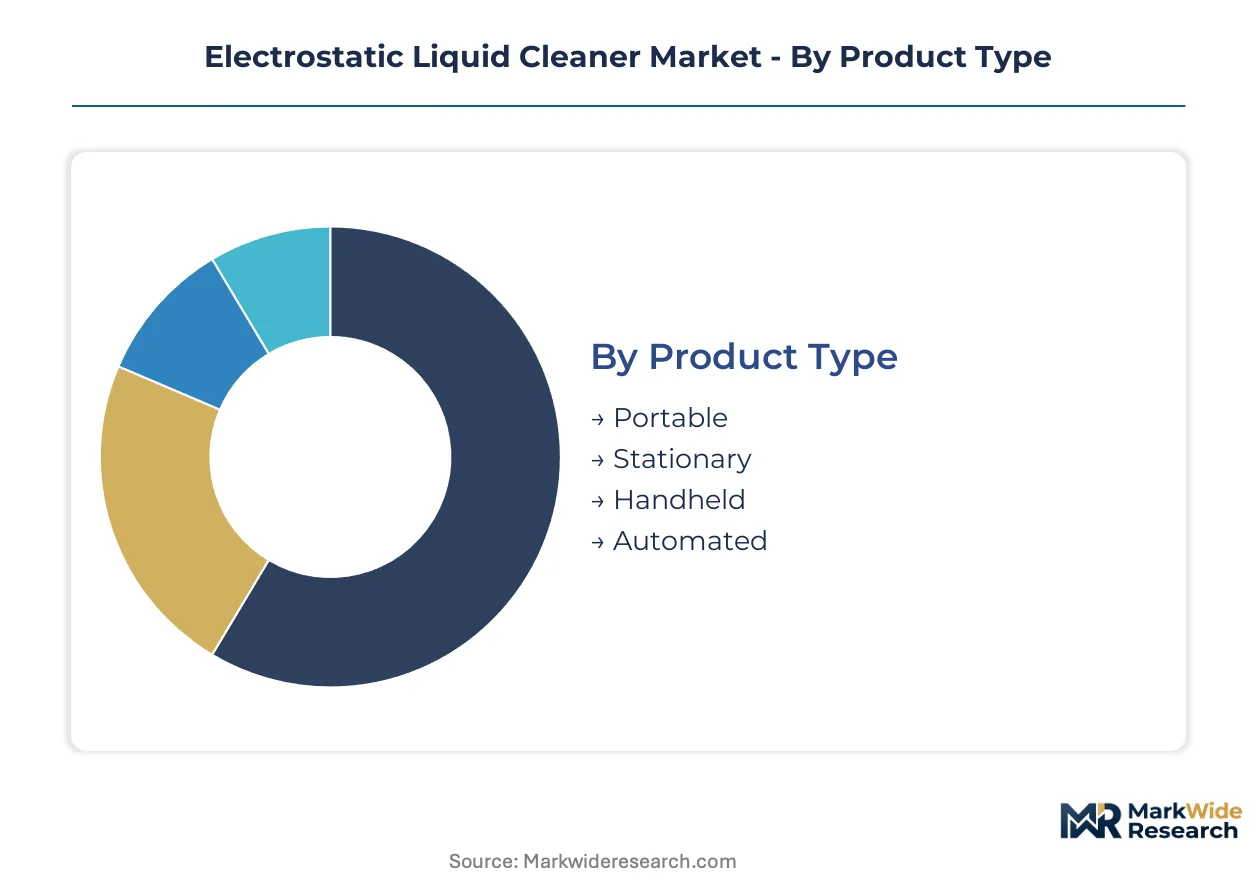
Electrostatic liquid cleaner procurement splits sharply between high-throughput stationary installations and flexible portable units, with technology choice and end-use certification requirements further stratifying vendor margins. Semiconductor fabs in Taiwan and South Korea anchor demand for automated configurations, while automotive workshops in Germany and Spain drive induction charging adoption.
Product Type:
Volume concentration sits with fixed infrastructure, yet mobility premiums persist in retrofit markets and small-batch operations.
- Stationary:Fixed-mount systems operating at 20-100 kV with integrated power supplies and closed-loop liquid recovery. Semiconductor plants in Hsinchu and Pyeongtaek specify these for ISO Class 3 compliance, locking vendors into multi-year consumables contracts.
- Automated:Conveyor-integrated configurations with real-time particle monitoring and programmable ion density profiles. Paint booths at German automotive OEMs adopt these to meet EU Green Deal energy benchmarks while eliminating manual handling variability.
- Portable:Mobile units on casters with external liquid tanks for spot cleaning and maintenance operations.
- Handheld:Pistol-grip devices for precision application in confined spaces and repair scenarios.
Today's leader: Stationary. Tomorrow's challenger: Automated.
Technology:
Corona discharge dominates where ion density predictability commands premium pricing, yet electrode maintenance burdens are redirecting specification toward contactless alternatives.
- Corona Discharge:High-voltage wire-to-cylinder geometry generating unipolar ion clouds through electron avalanche. Taiwanese fabs require this technology for sub-micron particle capture validation, though electrode replacement every 18-24 months imposes lifecycle cost concentration.
- Induction Charging:Rotating disc or centrifugal atomization with electrostatic induction at 15-30 kV. Spanish and Italian paint booth operators specify these systems to eliminate corona wire maintenance downtime in continuous production schedules.
- Spray Charging:Hydraulic atomization with concurrent charge injection through concentric electrode rings.
- Needle Charging:Multi-point emitter arrays for localized high-intensity ion generation in precision applications.
Corona discharge holds installed base dominance. Induction charging climbs fastest on maintenance cost arbitrage.
Application:
Electronics manufacturing commands specification stringency, while food processing applies electrostatic principles to novel hygiene protocols.
- Electronics Manufacturing:Cleanroom-grade particle precipitation for wafer handling and packaging operations. South Korean semiconductor corridors specify validated systems with documented ion density stability across shift changes.
- Paint Booths:Overspray capture and transfer efficiency enhancement in automotive and industrial coating. REACH VOC restrictions in France and Italy eliminate solvent-based alternatives, elevating closed-loop liquid architectures.
- Food Processing:Airborne contaminant control in packaging zones and cold storage facilities.
- Textile Treatment:Fiber conditioning and dust suppression in spinning and weaving operations.
Electronics manufacturing anchors revenue. Paint booths expand most quickly on regulatory substitution.
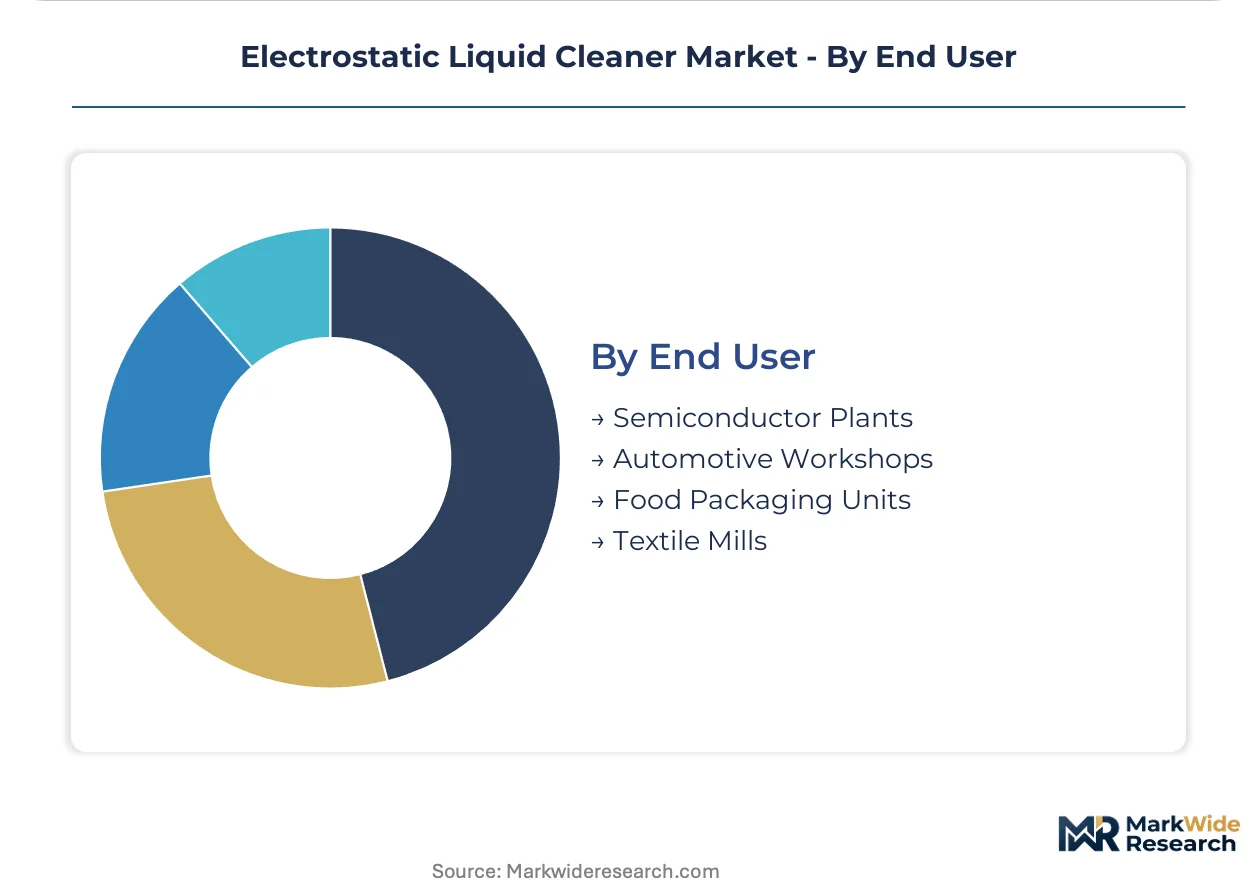
End User:
Semiconductor plants consolidate procurement power, fragmenting vendor relationships into discrete performance contracts.
- Semiconductor Plants:Fab operators in Taiwan and South Korea with ISO 14644 alignment mandates. Procurement teams in Hsinchu now unbundle equipment, consumables, and maintenance into separate competitive bids, compressing bundled pricing power.
- Automotive Workshops:OEM paint lines and tier-1 supplier facilities in Germany and Spain. EPA NESHAP mandates in US coating operations force 95% capture efficiency certification, redirecting capital toward validated electrostatic mist systems.
- Food Packaging Units:Hygiene-critical operations with FDA and EFSA compliance requirements.
- Textile Mills:Dust-intensive environments with worker exposure reduction priorities.
Semiconductor plants dictate specification. Automotive workshops scale fastest on regulatory deadline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized corona physics engineers and high-voltage systems technicians concentrate in Taiwan, South Korea, and Germany, anchoring regional capability clusters for precision electrostatic equipment.
Taiwan
Hsinchu Science Park fabs drive automated electrostatic system procurement for ISO Class 3 cleanroom compliance. The Ministry of Economic Affairs enforces industrial emissions standards that elevate closed-loop liquid architectures over solvent alternatives. Semiconductor packaging facilities in Taichung and Tainan now unbundle equipment, consumables, and maintenance into separate competitive bids.
South Korea
Pyeongtaek and Yongin semiconductor corridors validate electrostatic mist systems for sub-micron particle capture stability. MFDS alignment with ISO 14644 filters procurement toward documented ion density performance across shift changes. Samsung and SK Hynix supplier ecosystems in Suwon anchor multi-year service contract negotiations for stationary installations.
Germany
Automotive OEM paint lines in Stuttgart and Munich specify induction charging systems to eliminate corona wire maintenance downtime. REACH VOC restrictions enforced by ECHA eliminate solvent-based cleaning alternatives by 2027. Tier-1 suppliers in Wolfsburg and Ingolstadt benchmark EU Green Deal energy efficiency standards for high-voltage equipment procurement.
United States
EPA NESHAP mandates force automotive coating operations toward 95% particulate capture efficiency certification. Michigan and Ohio paint booth operators redirect capital toward validated electrostatic mist systems. Semiconductor fabs in Arizona and Texas align with FDA and OSHA cleanroom protocols for contamination control equipment.
India
PLI scheme incentives for semiconductor and component assembly create first-mover positioning for localized electrostatic cleaning deployment. Karnataka and Telangana electronics manufacturing clusters in Bangalore and Hyderabad attract equipment vendors establishing service networks. BIS standards for industrial air quality tighten specifications for imported high-voltage systems.
Electrostatic Liquid Cleaner Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the electrostatic liquid cleaner landscape. The vendor base stratifies into three tiers: integrated system houses with captive power supply manufacturing, specialized regional service providers with localized maintenance networks, and component suppliers selling corona electrodes and induction coils to third-party assemblers. Consolidation pressures concentrate in East Asian electronics corridors where procurement unbundling compresses bundled pricing power. Dominant competitive moves include backward integration into transformer and power electronics manufacturing, plus geographic expansion through distributor partnerships in emerging electronics manufacturing zones.
Among the integrated system houses, Kleentek anchors European automotive workshop positioning through induction charging expertise, while FRIESS exemplifies backward integration into corona discharge power supply manufacturing. OILKLEEN occupies a position within Asian electronics manufacturing corridors, sustaining presence through localized service network density. These three represent distinct archetypes: technology specialization, vertical manufacturing control, and geographic service intensity.
| Leading Market Players |
|---|
| Kleentek |
| FRIESS |
| Cee Dee Vacuum |
| OILKLEEN |
| Turbotect |
| PECD |
| Envair |
| Ferrocare |
| Rotomatik |
| Others |
Pricing and Supply Chain Analysis
Copper price volatility on the London Metal Exchange cascades through electrostatic liquid cleaner manufacturing, elevating power supply costs for corona discharge systems and compressing margins on economy-tier portable units while semiconductor fabs absorb premium pricing for validated stationary installations.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-validated semiconductor systems from automotive workshop induction units and maintenance-portable alternatives. Price differentiation rests on certification grade and localized service network density. Pricing pressure stems from procurement unbundling in Taiwanese and South Korean fabs, where separate bidding for equipment, consumables, and maintenance erodes bundled lifecycle premiums. Automotive workshops exhibit highest price sensitivity due to REACH compliance cost absorption, while semiconductor plants prioritize ion density stability over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Yokohama, and Dallas anchor hub-and-spoke patterns for high-voltage transformer and corona electrode replenishment. Manufacturing concentration in Germany, Japan, and Taiwan feeds from specialized copper winding facilities, epoxy resin formulators, and precision-machined electrode suppliers. Single-source vulnerability concentrates in German and Japanese transformer manufacturers, where limited qualified suppliers create chokepoint exposure. Distribution runs through authorized service networks rather than open distribution, with multi-year consumables contracts locking in downstream revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage positioning between European REACH compliance premiums and Asian manufacturing scale economies, with regulatory cost differentials creating margin expansion opportunities for cross-regional operators.
For Market Incumbents: Extend induction charging technology portfolios to capture automotive workshop substitution away from corona maintenance burdens. Deepen backward integration into power electronics manufacturing to defend margin position against procurement unbundling in East Asian electronics corridors. Lock multi-year consumables contracts through predictive maintenance platform deployment before competitor service networks mature. For New Entrants and Emerging Players: Launch via localized service partnerships in Indian electronics manufacturing clusters under PLI scheme incentives, where first-mover positioning remains unclaimed. Target battery cell coating applications for electric vehicle electrode manufacturing, a white-space segment with contamination control requirements but limited incumbent penetration. Pursue certified system validation for ISO 14644 alignment as the primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service specialists possessing dense maintenance networks in high-growth electronics manufacturing corridors. Long-term viability favors acquisition targets with captive consumables revenue streams and documented ion density performance validation. Watch for procurement unbundling acceleration in Taiwanese and South Korean fabs as the inflection signal for service contract fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Supply Manufacturing | FRIESS exemplifies this archetype through captive corona discharge transformer production in European facilities. |
| Induction Charging Technology Migration | Kleentek anchors European automotive positioning by eliminating electrode maintenance downtime in continuous paint lines. |
| Localized Service Network Expansion | OILKLEEN sustains Asian electronics corridor dominance through rapid electrode replacement response times in Hsinchu and Pyeongtaek. |
| Predictive Maintenance Platform Deployment | Sensor fusion and ion density monitoring reshape vendor-customer relationships toward outcome-based cleanliness contracts. |
| Regulatory Certification Pre-Positioning | EPA NESHAP and REACH VOC alignment filters procurement toward validated electrostatic mist systems with documented capture efficiency. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab procurement directors, automotive paint line engineers, high-voltage systems technicians, and aftermarket service managers with secondary validation against EPA NESHAP filings, ECHA REACH substance restrictions, ISO 14644 cleanroom standards, and semiconductor industry capital expenditure disclosures. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates were triangulated to anchor market sizing.
Segment-weighting approaches modeled technology choice, product configuration, application intensity, and end-user procurement sophistication across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, regulatory deadline compression effects, and regional manufacturing capacity expansion trajectories. Forecast inputs incorporated transformer supply lead times, electrode degradation curves, and liquid resistivity operational constraints specific to electrostatic precipitation physics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material price spikes or transformer supply disruptions. Outputs reflect documented assumptions around regulatory enforcement timelines and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Global Metal Cleaning Chemicals Market
Cleaning Chemicals
Concentrated Laundry Powder Market