
 Europe and Middle East Lime Market | 2026-2036
Europe and Middle East Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and Middle East Lime Market Intelligence
The split between premium high-calcium lime and standard commodity grades is realigning procurement patterns across the Europe and Middle East Lime Market. Graymont Limited leverages its vertical integration from quarry to hydrated product to sustain margin capture in Nordic steel contracts. Lhoist Group anchors its position through specialized dolomitic lime for European environmental services, while Saudi Lime Industries Co. dominates supply to GCC construction and water treatment infrastructure.
Europe and Middle East lime encompasses calcium oxide and calcium hydroxide products derived from limestone calcination at temperatures exceeding 900 degrees Celsius, serving primarily as fluxing agents, pH regulators, and stabilizers across heavy industry. Quicklime retains the largest volume share due to its irreplaceable role in steel slag formation, though hydrated lime is gaining share in water treatment applications where handling safety and precision dosing matter. Specialty lime commands disproportionate margins from chemical industry end users seeking ultra-low silica or controlled reactivity grades.
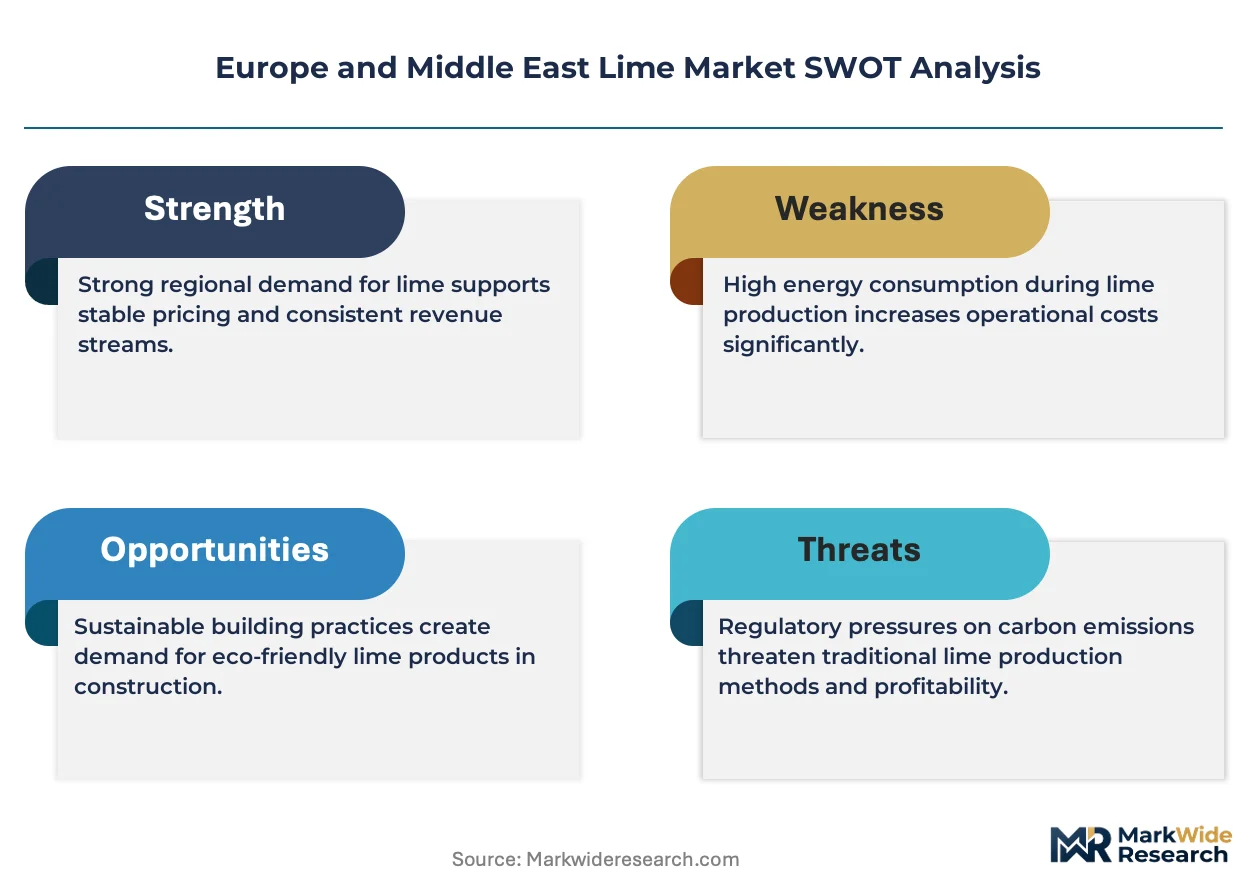
The EU Emissions Trading System and REACH chemical registrations shape product standards and kiln investment decisions for European producers, while Saudi Arabia's SASO quality marks and the UAE's MOCCAE environmental permits govern Middle East market access. Compliance costs diverge sharply between these frameworks, forcing multi-regional operators to maintain parallel certification pathways. Stakeholders must weigh carbon capture retrofits against regional fuel cost spreads when committing capital to new calcination capacity.
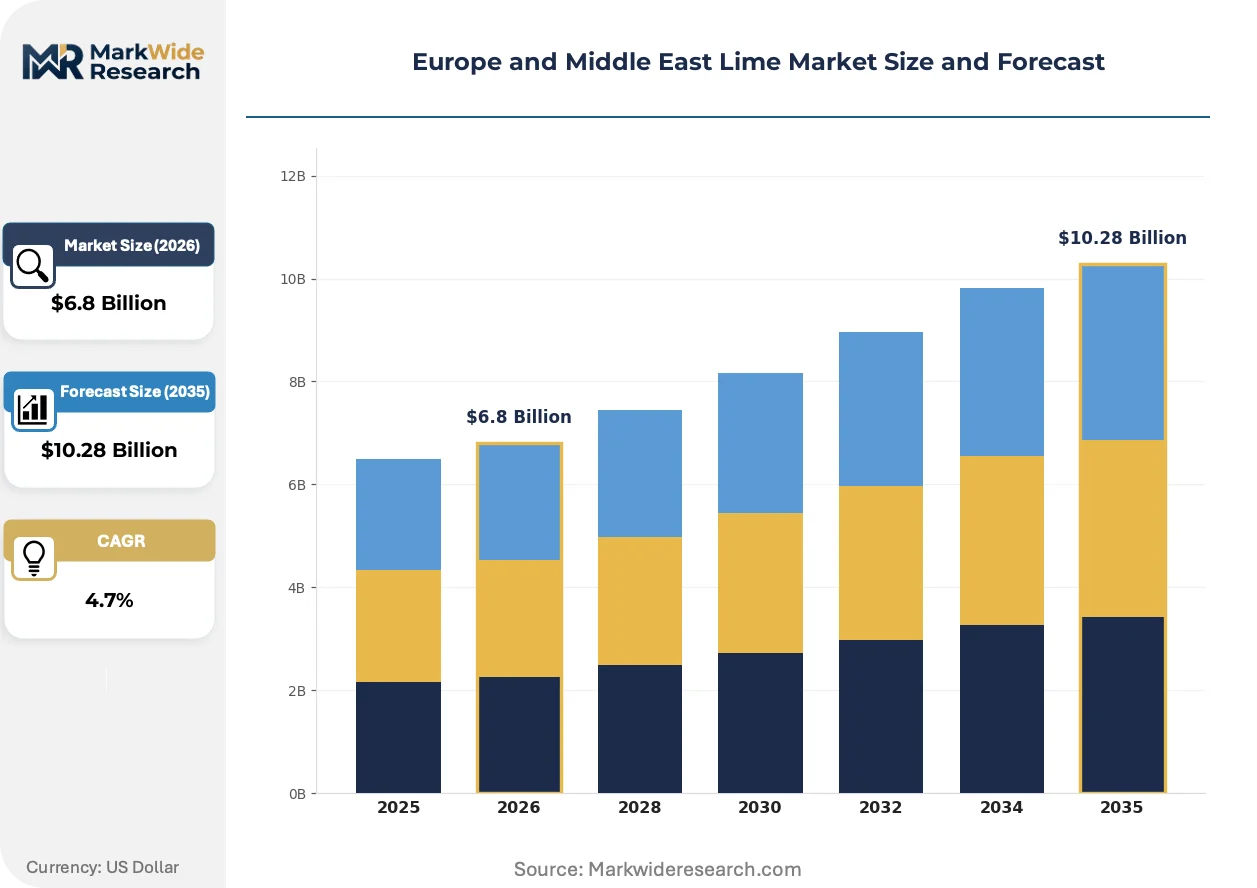
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing lime producers across Europe and the Middle East to accelerate kiln electrification and alternative fuel adoption, fundamentally restructuring capital allocation toward decarbonization compliance.
Growth Catalysts
- EU Emissions Trading System:Rising carbon prices are pulling investment into carbon capture retrofits at German and Polish calcination facilities, expanding capacity for low-carbon lime grades.
- Steel desulfurization demand:Turkish and Saudi Arabian steelmakers are expanding lime procurement volumes to meet tightening sulfur emission standards in construction-grade steel output.
- Water treatment infrastructure:GCC municipal water authorities are specifying hydrated lime for pH regulation in desalination brine neutralization, creating dedicated supply contracts.
Market Restraints
- Natural gas price volatility:European lime kilns remain dependent on natural gas feedstock, exposing margin structures to Nord Stream supply disruptions and LNG spot market swings.
- Quarry permitting delays:Environmental impact assessments under the EU Habitats Directive are extending limestone extraction licensing timelines in France and Italy by 18-36 months.
- Alternative flux materials:Electric arc furnace operators are testing synthetic slag formulators and recycled steel slag as partial lime substitutes in secondary steelmaking.
Strategic Opportunities
- Egyptian industrial corridor expansion:The Suez Canal Economic Zone is attracting lime-hungry cement and steel investments underserved by existing calcination capacity.
- Waste-to-fuel kiln integration:RDF and biomass co-firing technologies are opening fuel cost arbitrage for producers with access to municipal solid waste streams.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in from 2026 creates first-mover advantage for Middle Eastern exporters with verified low-carbon production pathways.
Industry Challenges
- Kiln engineering talent scarcity:Experienced refractory specialists and process engineers for Maerz and PFR kiln operations are concentrated among retiring workforce cohorts in Germany and Austria.
- REACH registration timelines:Chemical substance dossier preparation for specialty lime derivatives is consuming 24-30 months, delaying product launches for pharmaceutical and food-grade applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and Middle East Lime Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quicklime, Hydrated Lime, Pulverized Lime, Specialty Lime Application: Water Treatment, Steel Manufacturing, Construction, Soil Stabilization End User: Agriculture, Chemical Industry, Power Plants, Environmental Services Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Graymont Limited, Nordkalk Corporation, Lhoist Group, Saudi Lime Industries Co., Emirates Lime Factory, Carmeuse Group, Minerals Technologies Inc., Calcis Warstein GmbH & Co. KG, Omya AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and Middle East Lime Market Strategic Shifts & Innovations
Electrification of calcination processes and digital kiln control systems are compressing the technology gap between European environmental compliance and Middle Eastern cost efficiency. These shifts are redrawing competitive boundaries across the value chain.
Maerz vertical shaft kilns equipped with oxyfuel combustion systems are integrating carbon capture readiness into new capacity installations. German steel-service lime suppliers are adopting these configurations to secure offtake agreements with automotive OEMs sourcing green steel. The technology is integrating post-combustion capture infrastructure into standard kiln engineering specifications, raising capital intensity thresholds for market entry.
The EU Carbon Border Adjustment Mechanism is restructuring export economics for Turkish and Egyptian lime producers serving European construction and chemical buyers. Compliance documentation requirements for embedded emissions verification are diverting administrative resources toward third-party certification partnerships. Steel flux lime shipments from the Middle East face the steepest compliance cost escalation, pushing producers toward mass-balance accounting systems.
Long-term offtake contracting is displacing spot market purchasing among water treatment and environmental services buyers in the Netherlands and Belgium. Municipal procurement departments are consolidating annual lime volumes into three-to-five-year framework agreements with fixed-price escalators tied to natural gas indices. This pattern is most visible in Flemish wastewater treatment consortia, where handling safety and supply security outweigh unit cost minimization.
Europe and Middle East Lime Market Segmentation
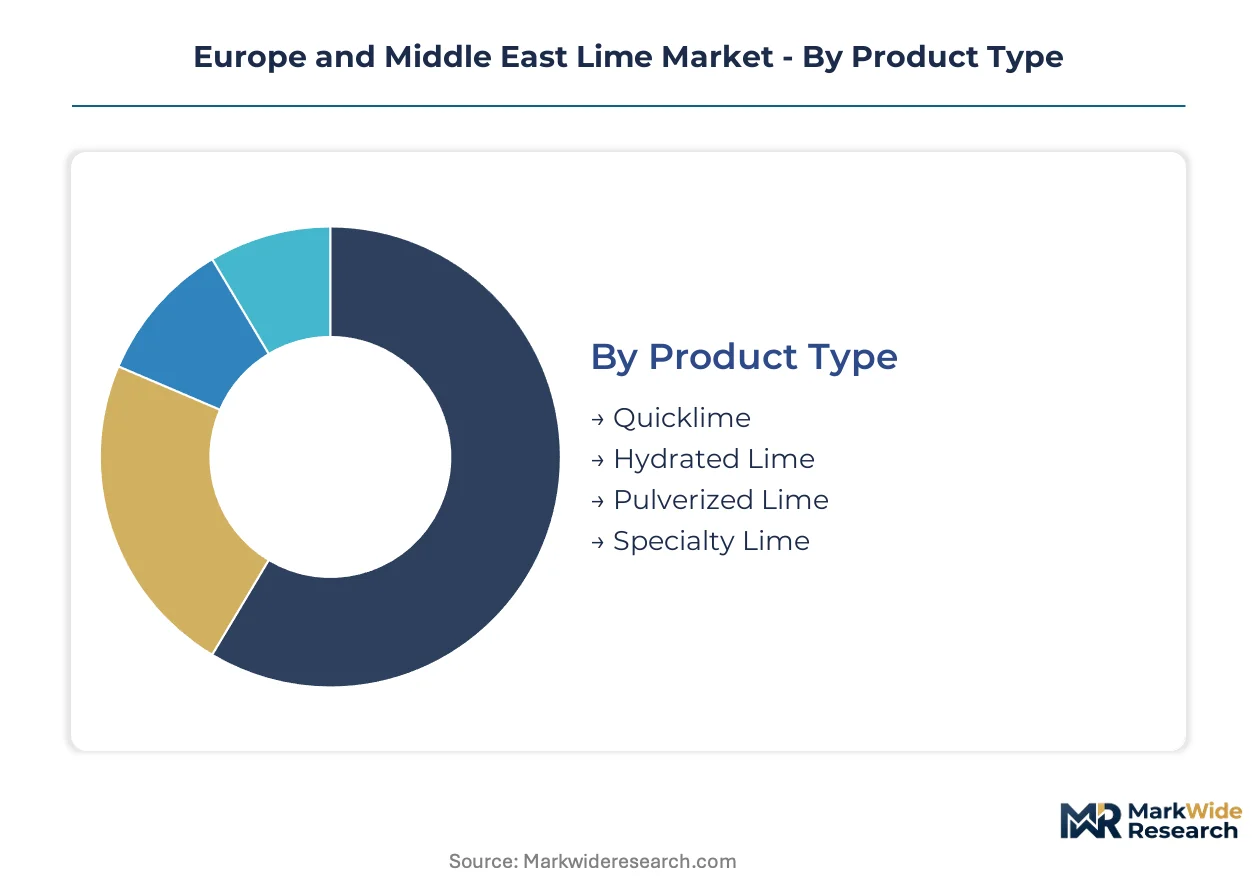
Capital allocation across the Europe and Middle East lime market diverges sharply by segment. Kiln technology choices, fuel switching requirements, and carbon compliance burdens reshape where producers commit expansion capital.
Product Type:
Calcination intensity and kiln configuration requirements determine upfront investment thresholds across product categories. Maerz vertical shaft kilns command premium capital commitments for high-calcium quicklime output.
- Quicklime:Calcium oxide produced at temperatures exceeding 900°C retains irreplaceable function in steel slag formation across Turkey's Iskenderun Bay steel cluster. German steel-service suppliers anchor capacity expansion here to secure automotive OEM offtake agreements.
- Hydrated Lime:Calcium hydroxide derived from controlled quicklime slaking offers superior handling safety for GCC municipal water authorities specifying pH regulation in desalination brine neutralization. The product commands dedicated supply contracts from Flemish wastewater treatment consortia.
- Pulverized Lime:Finely ground quicklime serves soil stabilization contractors across Saudi Arabia's NEOM infrastructure corridor with rapid reactivity profiles.
- Specialty Lime:Ultra-low silica and controlled reactivity grades target pharmaceutical and food-grade applications facing REACH registration timelines.
Most installed capacity flows through Quicklime. Expansion is steepest in Hydrated Lime.
Application:
End-use demand concentration varies by carbon intensity exposure and regulatory enforcement stringency across the region.
- Water Treatment:Municipal procurement departments in the Netherlands and Belgium are consolidating annual volumes into three-to-five-year framework agreements with fixed-price escalators tied to natural gas indices.
- Steel Manufacturing:Turkish and Saudi Arabian steelmakers are expanding procurement volumes to meet tightening sulfur emission standards in construction-grade steel output.
- Construction:GCC infrastructure spending drives hydrated lime demand for masonry mortar and plaster applications across the UAE's Jebel Ali processing zone.
- Soil Stabilization:Road contractors in Egypt's Suez Canal Economic Zone specify quicklime for clay modification in desert highway construction.
Steel Manufacturing absorbs the largest volume share. Water Treatment is climbing the fastest.
End User:
Procurement sophistication and contract duration differentiate customer segments across the value chain.
- Agriculture:Soil pH correction applications in France's Champagne-Ardenne region drive seasonal demand patterns for pulverized lime grades.
- Chemical Industry:Specialty lime derivatives face 24-30 month REACH dossier preparation timelines, delaying product launches for ultra-pure grades.
- Power Plants:Flue gas desulfurization installations in Poland's Silesian coal belt specify high-reactivity quicklime for scrubber operations.
- Environmental Services:Flemish wastewater treatment consortia prioritize handling safety and supply security over unit cost minimization in long-term contracting.
Chemical Industry commands the highest margin premiums. Environmental Services is gaining share fastest.
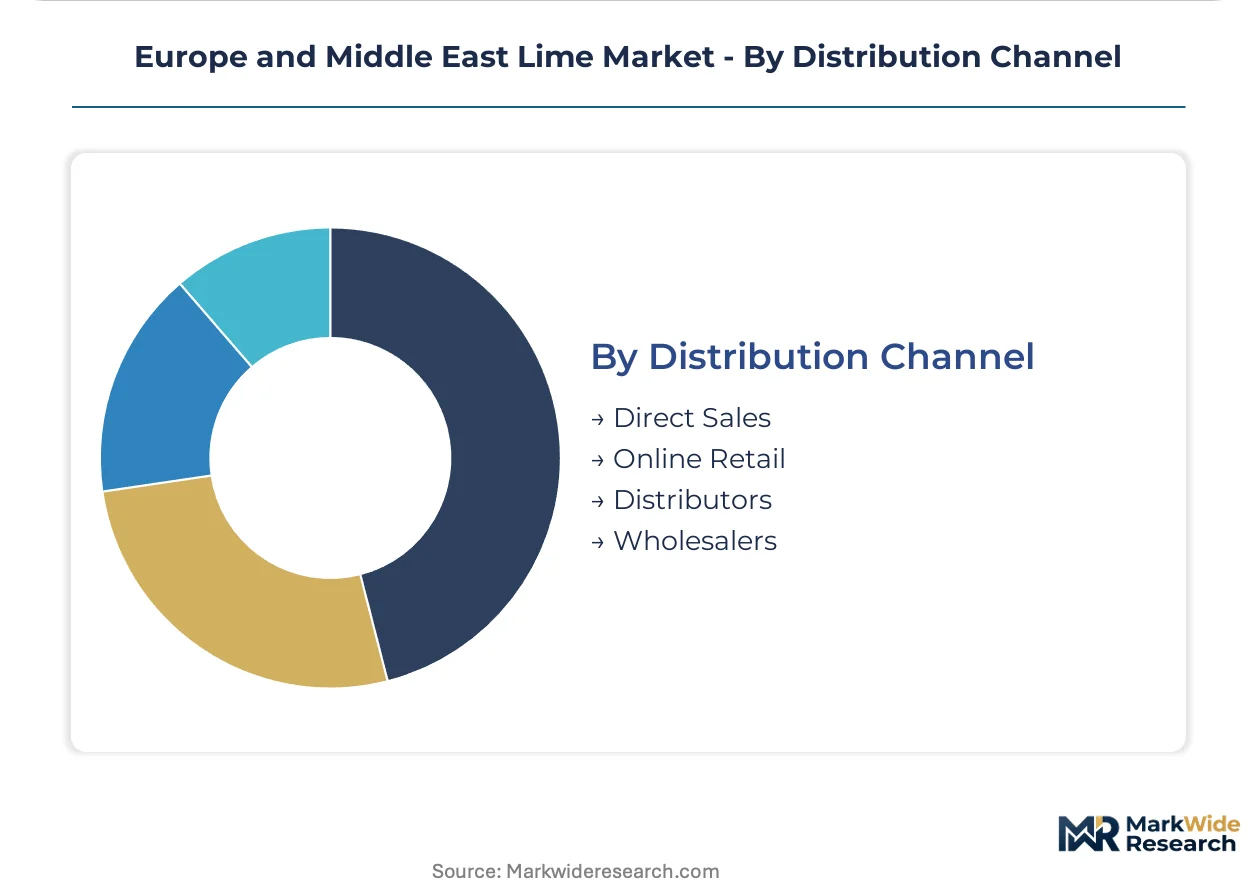
Distribution Channel:
Logistics infrastructure and handling requirements shape channel economics across geographies.
- Direct Sales:Steel mills and cement plants in Germany's Rhine-Ruhr industrial corridor negotiate volume commitments directly with calcination operators to secure supply security.
- Distributors:Regional stockists serve fragmented construction contractors across Italy's Lombardy building materials market with bagged hydrated lime products.
- Wholesalers:Bulk handling terminals at Rotterdam and Antwerp aggregate shipments for redistribution to Benelux water treatment facilities.
- Online Retail:Small-scale agricultural buyers in rural France access packaged lime products through digital procurement platforms.
Direct Sales captures the largest revenue pool. Distributors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German steel-service suppliers command premium pricing for automotive-grade flux lime, while Turkish producers leverage proximity to Black Sea shipping lanes for cost-advantaged export positioning. This divergence shapes investment allocation across the Europe and Middle East Lime Market.
Germany
Rhine-Ruhr industrial corridor steel mills anchor quicklime consumption for slag formation in automotive OEM supply chains. The EU Emissions Trading System drives carbon capture retrofits at calcination facilities in North Rhine-Westphalia. Maerz kiln operators in the region secure long-term offtake agreements with decarbonization-linked pricing.
Turkey
Iskenderun Bay steel cluster expansion fuels desulfurization-grade lime procurement volumes. The country's national environmental regulator enforces tightening sulfur emission standards for construction steel exports. Izmir-based processing terminals aggregate shipments for Mediterranean distribution to Italian and Spanish buyers.
Saudi Arabia
NEOM infrastructure corridor and GCC water treatment programs concentrate hydrated lime demand. SASO quality marks govern product certification for construction and environmental applications. Eastern Province calcination capacity serves both domestic steelmakers and Red Sea export routes to Egypt.
United Arab Emirates
Jebel Ali processing zone anchors hydrated lime distribution for GCC desalination brine neutralization contracts. MOCCAE environmental permits regulate industrial emissions from calcination operations. Dubai-based logistics hubs consolidate bulk shipments for redistribution to Kuwait and Qatar municipal water authorities.
Poland
Silesian coal belt flue gas desulfurization installations sustain high-reactivity quicklime demand for power plant scrubber operations. EU Green Deal carbon border adjustments pressure kiln fuel switching from coal to natural gas and biomass. Upper Silesian industrial zone producers face compressed margins from carbon price exposure.
Europe and Middle East Lime Market Key Industry Players
Top-tier vendors anchor integrated supply chains from quarry to hydrated product, while mid-scale regional specialists concentrate on single-country market penetration. The vendor base stratifies across three tiers: multinational calcination operators with cross-border logistics networks, national champions serving domestic steel and construction verticals, and quarry-dependent local suppliers. Two dominant competitive moves define current positioning: backward integration into captive limestone reserves and kiln electrification partnerships with technology licensors.
Within the multinational integrated tier, Graymont Limited and Lhoist Group exemplify archetypes of vertical control spanning Nordic and Western European markets. Saudi Lime Industries Co. occupies a position as a national champion serving GCC infrastructure programs. Carmeuse Group represents the European environmental services specialization vector. These three anchors demonstrate how geographic origin and corporate structure align with distinct competitive positioning: Canadian-originated Graymont leverages transatlantic logistics, Belgian-structured Lhoist emphasizes chemical industry-grade specialization, and Saudi-organized Saudi Lime Industries concentrates on water treatment and construction verticals within its home market.
| Leading Market Players |
|---|
| Graymont Limited |
| Nordkalk Corporation |
| Lhoist Group |
| Saudi Lime Industries Co. |
| Emirates Lime Factory |
| Carmeuse Group |
| Minerals Technologies Inc. |
| Calcis Warstein GmbH & Co. KG |
| Omya AG |
| Others |
Cost & Logistics Intelligence
Steel desulfurization procurement expansions in Turkey and Saudi Arabia are forcing calcination operators to secure long-term limestone reserves and lock in fuel hedges, compressing margin flexibility across standard quicklime grades.
Pricing Analysis
Capacity additions in Egypt's Suez Canal Economic Zone are reshaping price floors for construction-grade hydrated lime across Mediterranean export corridors. Three-tier pricing structure across high-calcium premium, standard desulfurization, and economy construction tiers separates automotive OEM flux contracts from municipal water treatment volumes. Pricing pressure stems from EU carbon border adjustment compliance costs for Middle Eastern exporters serving German steel mills. Municipal water authorities in the Netherlands and Belgium exhibit lowest price sensitivity due to supply security priorities, while Egyptian road contractors drive aggressive spot market negotiation.
Supply Chain Analysis
Refractory liner refurbishment flows and kiln rebuild cycles concentrate technical service demand among retiring German and Austrian engineering cohorts. Limestone extraction draws from captive quarries in France, Belgium, and Saudi Arabia, with high-calcium deposits anchored in the Jebel Ali processing zone and Rhine-Ruhr corridor. Supply chain risk centers on single-source vulnerability for Maerz vertical shaft kiln technology licensors. Distribution runs through Rotterdam and Antwerp bulk terminals for Benelux water treatment redistribution, with direct rail links serving German steel-service customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe and Middle East Lime Market functions as a stable compounder anchored by irreplaceable steel slag formation demand that resists substitution despite synthetic flux testing.
For Market Incumbents: Deepen backward integration into captive limestone reserves in France and Saudi Arabia to defend against Egyptian greenfield cost competition. Secure Maerz kiln engineering talent through apprenticeship pipelines in Germany and Austria before workforce retirement accelerates. Prioritize carbon capture retrofit certification to maintain automotive OEM offtake pricing premiums under EU Green Deal compliance. For New Entrants and Emerging Players: Enter via the Egyptian Suez Canal Economic Zone where calcination capacity lags cement and steel investment inflows. Target hydrated lime supply contracts for GCC desalination brine neutralization programs with handling safety specifications that favor new engineering approaches. Pursue waste-to-fuel kiln partnerships with municipal solid waste authorities to unlock fuel cost arbitrage against natural gas-dependent European incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional specialists holding SASO quality marks and verified low-carbon production pathways ahead of CBAM phase-in. Five-to-ten year viability favors operators with integrated quarry-to-hydrated product control and automotive steel-service relationships. Monitor EU carbon price trajectories and Turkish steel export sulfur standard enforcement as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Partnership | Maerz oxyfuel configurations secure automotive OEM green steel offtake agreements in Germany. |
| Captive Limestone Acquisition | Reserve control in Saudi Arabia's Eastern Province insulates against quarry permitting delays in France. |
| Carbon Capture Retrofit | Post-combustion readiness differentiates supply to EU Carbon Border Adjustment Mechanism-exposed buyers. |
| Waste-to-Fuel Integration | RDF and biomass co-firing unlocks cost arbitrage against Nord Stream-exposed European competitors. |
| Long-term Supply Agreement | Three-to-five-year frameworks with Flemish wastewater consortia reduce spot market price volatility exposure. |
Research Approach
Multiple input streams — kiln operator production data, steel mill procurement disclosures, and GCC municipal water authority contract awards — were reconciled across primary interviews with plant managers, procurement leads at Turkish and Saudi steelmakers, distribution channel partners in Rotterdam and Antwerp, and technical R&D directors at calcination technology licensors. Secondary validation drew from EU ETS carbon price registries, SASO quality mark certifications, REACH chemical registration databases, and customs trade flows through Mediterranean and Red Sea ports. Bottom-up capacity modeling and top-down demand segmentation were cross-referenced to establish volume and value estimates.
Historical capacity utilization patterns were cross-referenced against panel input from kiln engineering specialists and fuel procurement officers to construct projection scenarios across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry concentration, kiln technology configuration, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for carbon compliance cost pass-through assumptions and steel desulfurization intensity requirements.
Inputs from EU ETS registries and GCC municipal contract databases were available through the study window; gaps in proprietary kiln fuel consumption data introduce uncertainty bands around carbon intensity calculations for individual production facilities. Forecasts reflect assumptions regarding CBAM enforcement timelines and Turkish steel export sulfur standard implementation. Practitioners should monitor EU carbon auction price movements and Egyptian industrial zone licensing acceleration for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Foam Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Global Antifreeze/Coolant Market