
 South Africa Lime Market | 2026-2036
South Africa Lime Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Lime Market Analytics
South Africa's carbon tax is shifting the cost-of-entry calculus for new kiln investments, favoring operators with capital to deploy emissions-abatement equipment. PPC Ltd. leverages its integrated quarry-to-dispatch network across the Northern Cape and Limpopo to sustain freight advantages into inland markets. AfriSam competes through its diversified cement-and-lime portfolio, while Idwala Lime anchors the specialty-grade segment with controlled reactivity products for chemical manufacturing.
Lime comprises calcium oxide (quicklime) and calcium hydroxide (hydrated lime), produced by calcining limestone at temperatures exceeding 900°C to drive off carbon dioxide; the resulting material serves as an alkaline reagent in steelmaking flue-gas treatment, soil stabilization, and potable water softening. Quicklime commands the largest volume share in construction applications where its exothermic slaking properties accelerate masonry setting, while hydrated lime is gaining share in water treatment as municipalities upgrade aging infrastructure. The agricultural segment remains mature, with dolomitic lime occupying stable demand in acid soil correction across the Free State and Mpumalanga grain belts.
The Department of Environment, Forestry and Fisheries enforces carbon tax reporting obligations that shape kiln fuel choices and investment timelines, while SABS standards govern reactivity grades and chemical purity for construction and water treatment applications. Municipal procurement regulations under the Municipal Finance Management Act constrain pricing flexibility for suppliers serving city waterworks. Stakeholders must monitor regulatory amendments to carbon tax thresholds and SABS specification updates, as these will determine which calcination technologies and product grades retain market access across South Africa's nine provinces.
Market Dynamics
South Africa's carbon tax regime is compressing margins for calcination operators while simultaneously creating competitive separation between capitalized kiln upgraders and legacy fuel-dependent producers across the Northern Cape and Limpopo quarrying belts.
Growth Catalysts
- Municipal water infrastructure:Gauteng and KwaZulu-Natal municipalities are expanding lime procurement for pH correction in aging treatment plants, creating steady offtake for hydrated lime grades.
- Carbon tax abatement incentives:The Department of Environment, Forestry and Fisheries reporting obligations are accelerating adoption of biomass co-firing and electric calcination retrofits among integrated producers.
- Construction corridor concentration:Johannesburg, Durban, and Cape Town metropolitan buildouts are pulling quicklime volumes for soil stabilization and masonry applications.
Market Restraints
- Anthracite price volatility:Input energy costs for rotary kiln operation fluctuate with Richards Bay Coal Terminal export parity pricing, squeezing margin predictability for inland producers.
- Quarry concentration risk:High-calcium limestone deposits cluster in the Northern Cape and Limpopo, forcing freight disadvantage on coastal market access for non-integrated operators.
- Cement sector substitution:Portland cement blends incorporating pozzolanic materials are displacing traditional lime mortar in select residential applications.
Strategic Opportunities
- Specialty chemical grade expansion:Controlled reactivity quicklime for downstream chemical manufacturing remains undersupplied relative to Free State and Mpumalanga agrochemical demand.
- Biogenic carbon capture integration:Kiln operators pairing calcination with biomass feedstock can generate carbon credits under the national tax offset framework.
- Direct-to-farmer channels:Dolomitic lime distributors are bypassing cooperative aggregators to capture margin in acid soil correction across the grain belt.
Industry Challenges
- Kiln engineering talent scarcity:Skilled operators for modern preheater-retort systems are concentrated among retiring cohorts at established producers.
- SABS certification timelines:Reactivity grade approvals for water treatment applications face extended testing queues at accredited laboratories.
- Legacy fuel system integration:Converting long-rotary kilns from coal to dual-fuel biomass firing requires substantial mechanical retrofit complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Lime Market |
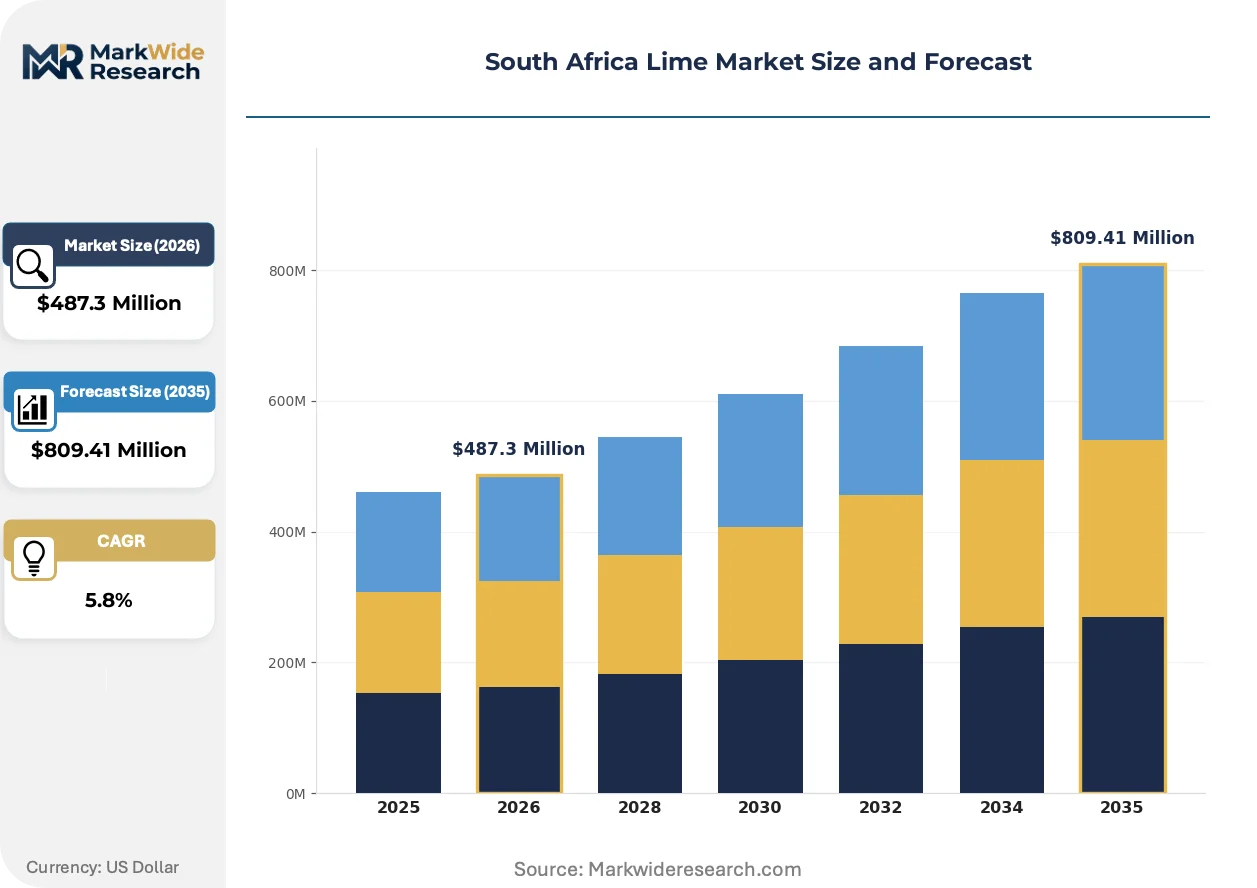
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydrated Lime, Quicklime, Limestone, Dolomitic Lime Application: Construction, Agriculture, Water Treatment, Chemical Manufacturing End User: Manufacturers, Farmers, Municipalities, Industrial Plants Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | PPC Ltd., AfriSam, Idwala Lime, Afrimat Limited, Lime Distributors (Pty) Ltd., Bontebok Lime Works, Cape Lime (Pty) Ltd., Lithon Lime, Northern Lime Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Lime Market Evolving Landscape
Calcination technology and procurement patterns are diverging across South Africa's lime value chain, with digitized kiln control systems and carbon-accounting transparency emerging as competitive differentiators.
Advanced process control systems using real-time thermal imaging and predictive algorithms are unifying combustion efficiency with emissions monitoring. PPC Ltd. and Idwala Lime have deployed these platforms at flagship operations, enabling fuel switching without quality drift. This convergence is compressing the cost gap between traditional coal firing and lower-carbon alternatives, forcing mid-tier operators toward equipment alliances or contract tolling arrangements.
The Department of Environment, Forestry and Fisheries carbon tax reporting obligations are tightening fuel documentation requirements for all calcination facilities above threshold emissions. Industrial consequence includes mandatory third-party verification of fuel-source declarations and penalty structures for underreporting. Large integrated producers with captive quarry-to-kiln logistics are absorbing compliance costs more readily than toll processors serving spot chemical markets.
Buyer consolidation among water treatment municipalities is compressing supplier rosters and lengthening contract durations under Municipal Finance Management Act procurement frameworks. Johannesburg Water and eThekwini Municipality have shifted from annual spot purchasing to multi-year framework agreements with pre-qualified lime suppliers. This pattern is most visible in Gauteng and KwaZulu-Natal, where municipal engineering departments prioritize supply security over unit cost minimization.
South Africa Lime Market Segmentation
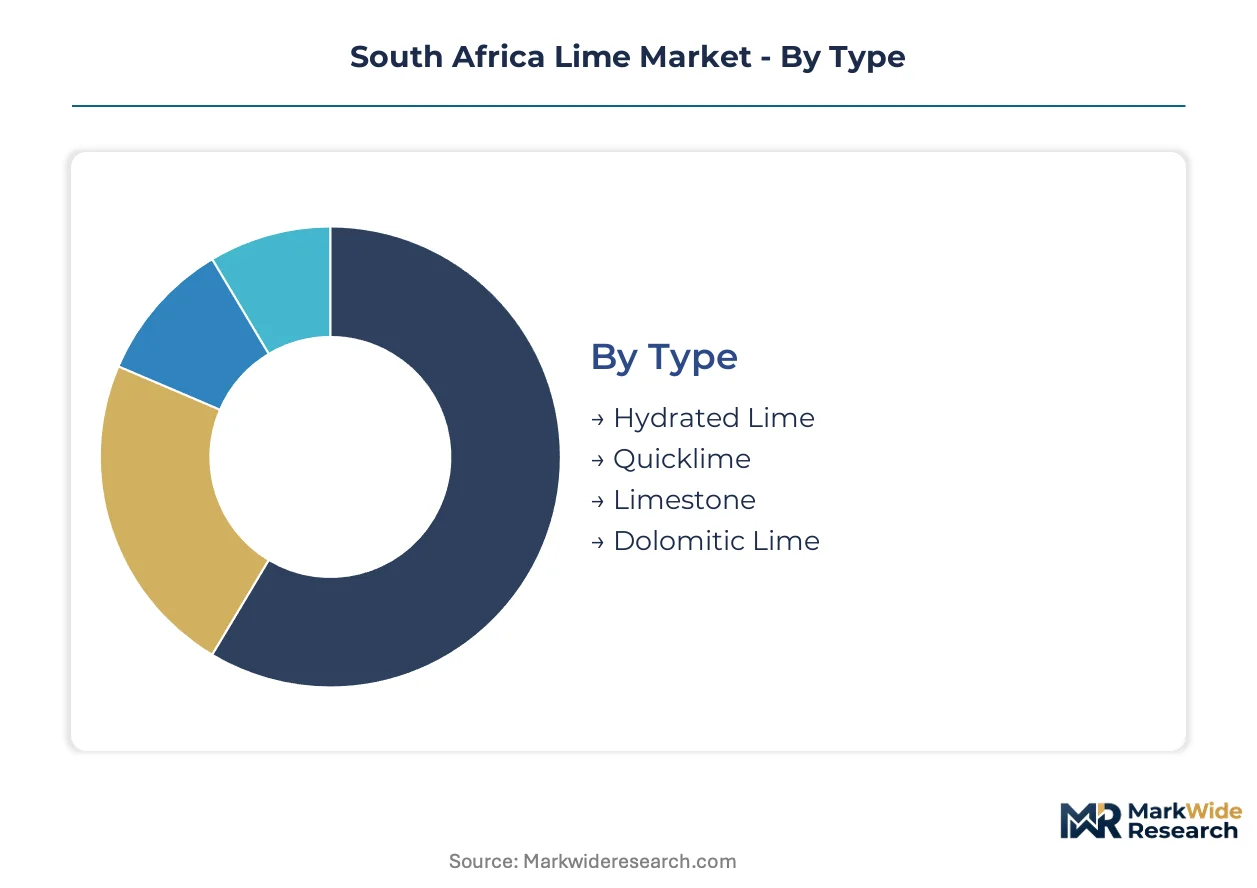
South Africa's lime market fragments across chemical reactivity grades, industrial applications, and procurement channels. Understanding these divisions reveals where carbon tax pressures and infrastructure spending reshape competitive positioning.
Type:
Buyers differentiate by reactivity specification and handling requirements rather than price alone.
- Quicklime:Calcium oxide produced at temperatures exceeding 900°C generates intense exothermic heat upon slaking. Demand concentrates in Johannesburg and Durban construction corridors where masonry setting acceleration commands premium pricing.
- Hydrated Lime:Calcium hydroxide derived from controlled slaking offers safer handling and precise pH control. Gauteng and KwaZulu-Natal municipalities specify this grade for aging water treatment plant retrofits.
- Limestone:Unprocessed calcium carbonate serves as kiln feedstock and agricultural filler. PPC Ltd. and AfriSam capture margin through captive quarry-to-kiln integration.
- Dolomitic Lime:Magnesium-calcium blend addresses acid soil correction across Free State and Mpumalanga grain belts. Direct-to-farmer distribution channels are expanding here.
Quicklime leads volumes today; hydrated lime is gaining share fastest.
Application:
Volume concentration follows public infrastructure spending cycles and industrial emissions compliance deadlines.
- Construction:Soil stabilization and mortar applications pull quicklime volumes across metropolitan buildouts. SABS reactivity standards govern municipal project specifications.
- Water Treatment:pH correction and softening processes drive hydrated lime procurement. Johannesburg Water and eThekwini Municipality have shifted to multi-year framework agreements.
- Agriculture:Acid soil correction maintains steady dolomitic lime demand. The segment shows limited pricing flexibility due to cooperative aggregator structures.
- Chemical Manufacturing:Controlled reactivity quicklime for downstream processing remains undersupplied relative to Free State agrochemical demand.
Construction anchors current volumes; water treatment shows the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between municipal tender processes and spot industrial purchasing.
- Municipalities:Gauteng and KwaZulu-Natal water departments prioritize supply security under Municipal Finance Management Act frameworks. Contract durations are lengthening.
- Industrial Plants:Steelmaking and flue-gas treatment operators demand consistent reactivity grades. Carbon tax reporting obligations tighten fuel documentation requirements.
- Manufacturers:Chemical and construction material producers balance spot purchasing against toll processing arrangements.
- Farmers:Grain belt operators in Free State and Mpumalanga source dolomitic lime through cooperative channels or direct distributor relationships.
Municipalities dominate contract value; industrial plants are expanding procurement fastest.
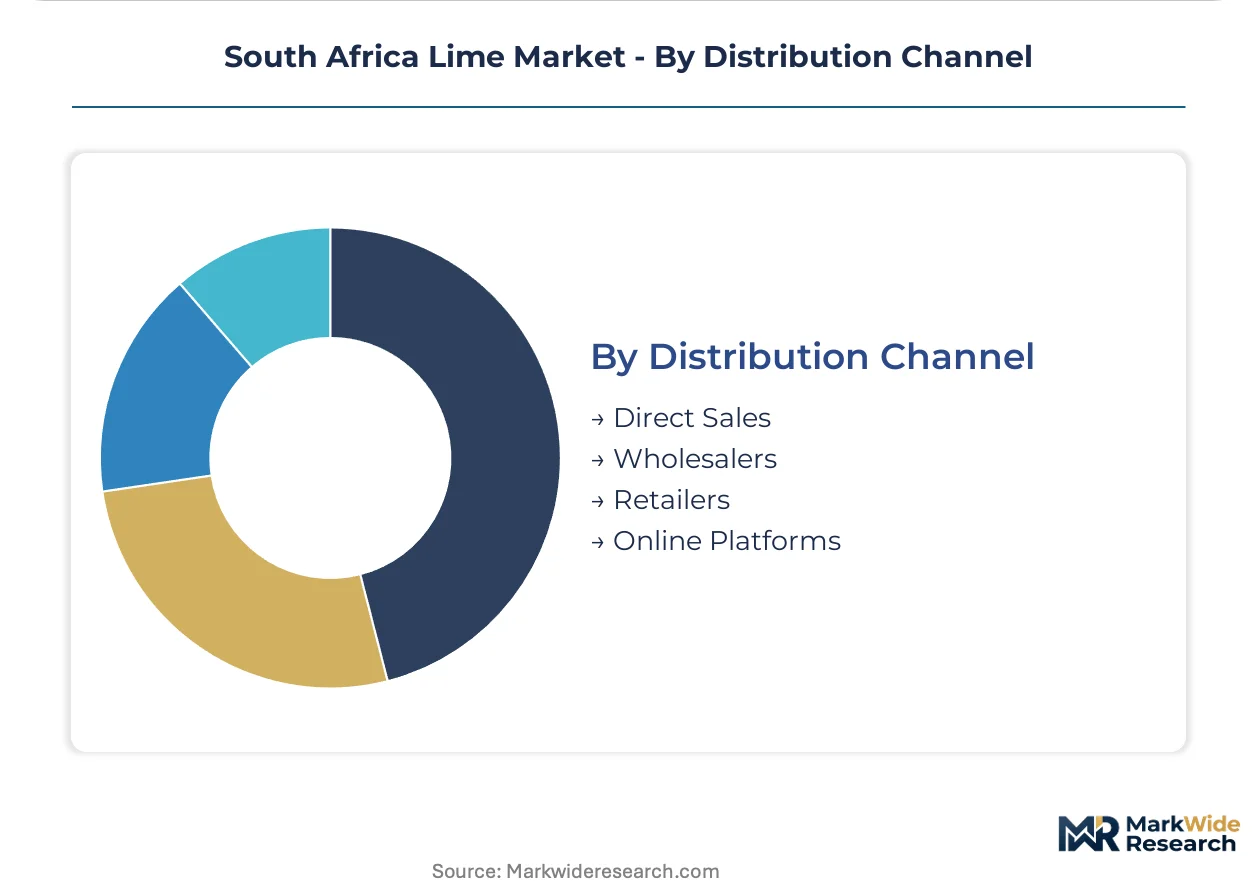
Distribution Channel:
Logistics integration determines margin capture in a market where quarry concentration forces freight disadvantage on non-integrated operators.
- Direct Sales:PPC Ltd. and Idwala Lime leverage captive quarry-to-dispatch networks across Northern Cape and Limpopo. This channel captures premium pricing for specialty grades.
- Wholesalers:Regional distributors aggregate volumes for construction and agricultural segments. Coastal market access depends on rail and road freight economics.
- Retailers:Agricultural supply cooperatives serve Free State and Mpumalanga grain belts with dolomitic lime. Direct-to-farmer channels are bypassing traditional aggregators.
- Online Platforms:Emerging digital procurement for standardized hydrated lime grades. Municipal buyers remain anchored to formal tender processes.
Direct sales command margin leadership; wholesaler volumes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kiln engineering talent concentrates in the Northern Cape and Limpopo quarrying belts, anchoring production capacity near high-calcium limestone deposits. This workforce distribution shapes regional competitive dynamics.
Gauteng
Johannesburg Water drives hydrated lime procurement for pH correction in aging treatment infrastructure. The Municipal Finance Management Act constrains supplier pricing flexibility through formal tender frameworks. The metropolitan construction corridor pulls quicklime volumes for soil stabilization and masonry applications.
KwaZulu-Natal
eThekwini Municipality has shifted from annual spot purchasing to multi-year framework agreements with pre-qualified suppliers. The Department of Environment, Forestry and Fisheries carbon tax reporting obligations tighten fuel documentation for coastal processors. Durban metropolitan buildouts sustain construction-grade quicklime demand.
Northern Cape
High-calcium limestone deposits cluster here, forcing freight economics to dominate market access calculations. SABS reactivity standards govern product grades leaving regional kilns. Integrated quarry-to-dispatch networks capture margin through captive logistics into inland markets.
Limpopo
Anthracite price volatility from Richards Bay Coal Terminal export parity pricing squeezes margin predictability for rotary kiln operators. Biomass co-firing retrofits are accelerating among capitalized producers seeking carbon tax abatement. Skilled operators for modern preheater-retort systems remain concentrated among retiring cohorts.
Western Cape
Cape Town metropolitan construction sustains hydrated lime demand for mortar and plaster specifications. Coastal freight disadvantage affects non-integrated operators sourcing from Northern Cape and Limpopo quarries. Direct-to-farmer distribution channels for dolomitic lime are expanding into adjacent agricultural zones.
South Africa Lime Market Competitive Landscape
The competitive structure tilts toward integrated quarry-to-kiln operators with captive limestone reserves and inland logistics networks. Three archetypes dominate: vertically integrated cement-lime conglomerates, specialty-grade chemical lime specialists, and regional toll processors serving spot construction markets. M&A activity concentrates on quarry reserve consolidation, while capacity expansion favors emissions-abatement retrofits over greenfield kiln construction.
Among South Africa-based integrated producers, PPC Ltd., AfriSam, and Idwala Lime occupy distinct archetype positions. PPC Ltd. represents the scale-driven integrated model with quarry-to-dispatch network coverage. AfriSam exemplifies the diversified cement-and-lime portfolio approach. Idwala Lime anchors the specialty-grade segment with controlled reactivity products. These three collectively illustrate how capital access, reserve position, and product grade focus segment competitive terrain.
| Leading Market Players |
|---|
| PPC Ltd. |
| AfriSam |
| Idwala Lime |
| Afrimat Limited |
| Lime Distributors (Pty) Ltd. |
| Bontebok Lime Works |
| Cape Lime (Pty) Ltd. |
| Lithon Lime |
| Northern Lime Company |
| Others |
Value Network & Pricing Analysis
Department of Environment, Forestry and Fisheries carbon tax reporting obligations gate qualified supply access and premium-tier pricing power, as only kiln operators with verified emissions abatement documentation can bid into municipal water treatment frameworks or command construction-grade premiums.
Pricing Analysis
Product-plus-logistics bundling separates spot chemical purchasers from construction contractors receiving delivered-duty-included terms. Three-tier pricing structure across specialty chemical, standard construction, and bulk agricultural grades reflects SABS reactivity certification and captive quarry access. Cost compression in standard construction grades is intensifying because cement substitution and import parity pressure from Richards Bay export pricing erode margin buffers. Municipal water departments show least price sensitivity due to Municipal Finance Management Act supply security mandates, while grain belt farmers remain most price-sensitive given cooperative aggregator structures.
Supply Chain Analysis
Anthracite supply rests on Richards Bay Coal Terminal export parity dynamics and domestic mine output from Mpumalanga. High-calcium limestone draws from Northern Cape and Limpopo quarry belts, with dolomitic feedstock sourcing from Free State agricultural zones. Single-source vulnerability concentrates in skilled kiln engineering talent retiring from established producers. Distribution runs through integrated quarry-to-dispatch networks for specialty grades, regional wholesalers for construction volumes, and cooperative channels for agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where inland freight economics from Northern Cape and Limpopo production belts create cost advantages against coastal import competition, amplified by carbon tax compliance differentials between capitalized upgraders and legacy operators.
For Market Incumbents: Anchor defensive positioning through captive limestone reserve consolidation in Northern Cape and Limpopo belts, blocking entrant access to high-calcium feedstock. Accelerate preheater-retort kiln retrofits to secure carbon tax abatement credentials ahead of tightening Department of Environment, Forestry and Fisheries thresholds, cementing municipal water treatment contract eligibility.
For New Entrants and Emerging Players: Begin with specialty chemical grade toll processing arrangements serving Free State and Mpumalanga agrochemical demand, where controlled reactivity quicklime remains undersupplied. Target direct-to-farmer dolomitic lime distribution in grain belt cooperatives bypassing traditional aggregator markups, leveraging digital procurement platforms for standardized hydrated lime grades.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier quarry operators with stranded limestone reserves because carbon tax compliance costs force distressed sales from legacy fuel-dependent producers unable to fund kiln retrofits. Monitor Department of Environment, Forestry and Fisheries carbon tax threshold amendments as the inflection signal determining which calcination assets retain market access across South Africa's nine provinces.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Co-firing Retrofit | Enables carbon tax offset generation under national abatement frameworks for Limpopo kiln operators. |
| Captive Quarry Acquisition | Secures high-calcium limestone reserves in Northern Cape, blocking competitor feedstock access. |
| Municipal Framework Agreement | Locks multi-year hydrated lime offtake with Johannesburg Water and eThekwini Municipality under supply security priorities. |
| Specialty Chemical Grade Expansion | Addresses controlled reactivity undersupply for Free State agrochemical manufacturing demand. |
| Direct-to-Farmer Channel Buildout | Bypasses cooperative aggregator structures in Mpumalanga grain belt, capturing agricultural margin. |
Research Methodology
Direct dialogue with kiln operations managers, municipal water treatment procurement officers, agricultural cooperative aggregators, and construction materials distributors grounded qualitative findings, cross-referenced with South African Revenue Service carbon tax filings, SABS certification records, Municipal Finance Management Act tender documentation, and industry association production statistics. Bottom-up volume estimates triangulated against top-down sectoral consumption models.
Top-down sectoral allocation anchored the analytical lens, disaggregating national construction, water treatment, agriculture, and chemical manufacturing demand across reactivity grades, end-use applications, and provincial distribution channels. CAGRs derived from regression analysis of historical production data and infrastructure spending trajectories, incorporating Department of Environment, Forestry and Fisheries regulatory compliance timelines and Richards Bay Coal Terminal fuel price volatility assumptions.
Caveats apply where Department of Environment, Forestry and Fisheries carbon tax threshold amendments or SABS specification updates could materially shift the outlook for kiln technology investment and product grade market access. A small set of named triggers—anthracite export parity spikes, municipal procurement framework revisions, and preheater-retort engineering talent availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Enzymes for Laundry Detergent Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market