
 1,3-Propanediol (PDO) Market | 2026-2036
1,3-Propanediol (PDO) Market Size, Share, and Industry Trends Forecast 2026-2036
1,3-Propanediol (PDO) Market Analysis
A shift from petroleum-based single-source supply toward multi-source bio-based procurement is repositioning how downstream PTT and cosmetics formulators secure 1,3-Propanediol. Shell plc dominates conventional PDO production through its petroleum-derived propylene oxide route, leveraging global refining infrastructure to sustain cost-competitive supply. DuPont Tate & Lyle Bio Products specializes in fermentative bio-PDO from corn sugar, differentiating through ISO-certified renewable content for European and North American brand owners. METabolic Explorer SA anchors French biotechnology leadership, operating pilot-scale continuous fermentation systems that compete on carbon intensity metrics rather than volume scale.
1,3-Propanediol is a three-carbon diol with the molecular formula C₃H₈O₂, produced industrially via petrochemical hydration of acrolein or microbial fermentation of glycerol and glucose substrates, serving primarily as a polyester monomer precursor and formulation intermediate. Bio-Based PDO commands structural attention as the fastest-growing product type, with margin pools concentrating in pharmaceutical-grade specifications where purity thresholds exceed 99.5% and regulatory documentation burdens exclude commodity entrants. The solvent application segment leads volume consumption due to PTT polymerization demand, while humectant uses in cosmetics represent a higher-value, lower-tonnage outlet where formulators prioritize hygroscopic stability and skin compatibility.
The EPA governs PDO manufacturing emissions under Clean Air Act provisions, while REACH registration requirements in Europe enforce comprehensive toxicity dossiers that shape bio-based pathway commercialization timelines. China's MEE implements dual carbon goals through provincial emissions trading schemes, pressuring Zhangjiagang Glory Biomaterial and domestic producers to document lifecycle carbon footprints for market access. Stakeholders must monitor fermentation yield improvements and feedstock cost volatility as the decisive variables determining whether bio-based routes achieve wholesale displacement of petroleum-derived supply.
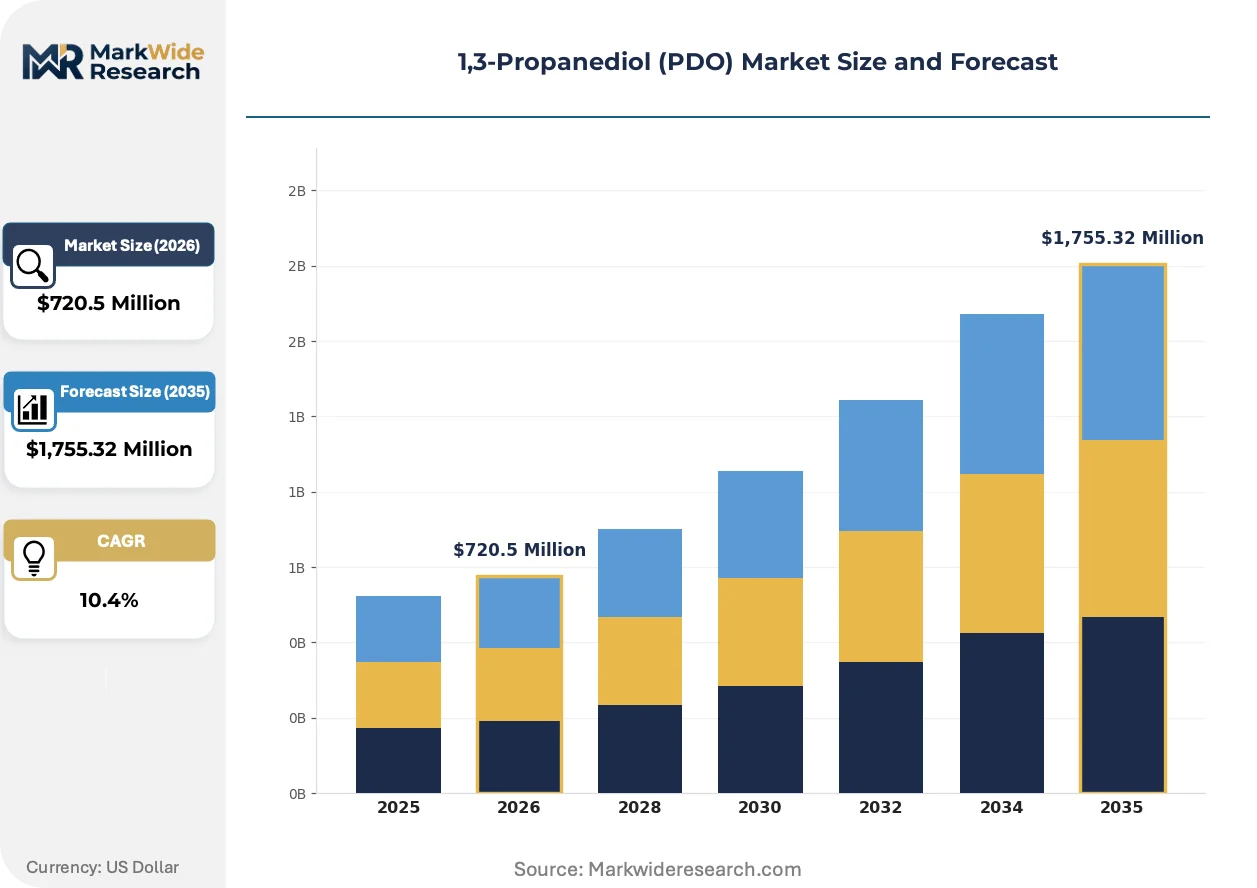
Market Dynamics
Fermentation yield improvements and feedstock cost volatility are the decisive variables determining whether bio-based 1,3-Propanediol routes achieve wholesale displacement of petroleum-derived supply across polyester and cosmetics value chains.
Growth Catalysts
- EU Green Deal sustainability mandates:REACH registration pathways for bio-based PDO are accelerating qualification timelines for European PTT fiber producers seeking lower-carbon feedstock credentials.
- Polytrimethylene terephthalate polymerization demand:Textile brands are requalifying supply chains around bio-based monomers to meet Scope 3 emissions reduction commitments.
- China:Shenghong Group Holdings' integrated PTA-PTT-PDO complexes are concentrating domestic polyester capacity and creating captive demand for fermentation-derived feedstocks.
Market Restraints
- Corn sugar price volatility:Fermentation-based PDO production faces margin compression when agricultural feedstock costs spike, undermining cost parity with propylene oxide routes.
- Shell plc's refining infrastructure dominance:Petroleum-derived supply concentration in global refining hubs creates procurement dependency for buyers lacking multi-source qualification.
- Pharmaceutical-grade purity thresholds:Specifications exceeding 99.5% purity with full regulatory documentation exclude commodity fermentation entrants from high-margin segments.
Strategic Opportunities
- Cosmetics humectant applications:Formulators are prioritizing hygroscopic stability and skin compatibility in premium skincare, creating pull for certified bio-based PDO at price premiums over industrial grades.
- Provincial emissions trading schemes:China's MEE dual carbon goals are pressuring domestic producers to document lifecycle carbon footprints, favoring entrants with ISO-certified renewable content.
- Continuous fermentation technology:Pilot-scale systems competing on carbon intensity metrics rather than volume scale are opening qualification pathways for boutique bio-based suppliers.
Industry Challenges
- Fermentation scale-up engineering talent:Continuous bioprocessing expertise remains concentrated in pharmaceutical biotechnology, creating recruitment friction for industrial biochemical ventures.
- REACH toxicity dossier compilation:Comprehensive regulatory documentation burdens for novel bio-based pathways extend commercialization timelines by 18-36 months.
- Legacy petrochemical customer specifications:PTT polymerization protocols optimized for petroleum-derived PDO create technical validation hurdles for fermentation-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1,3-Propanediol (PDO) Market |
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,755.32 Million |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Based PDO, Petroleum-Based PDO, Industrial-Grade PDO, Pharmaceutical-Grade PDO End Use Industry: Cosmetics, Food & Beverage, Pharmaceuticals, Textiles Form: Liquid, Powder, Concentrate, Solution Application: Solvent, Humectant, Antifreeze, Plasticizer |
| Companies Covered | METabolic Explorer SA, Shenghong Group Holdings, DuPont Tate & Lyle Bio Products, Haihang Industry Co., Ltd., Tokyo Chemical Industry Co., Ltd., Zhangjiagang Glory Biomaterial, Shell plc, Primient, Zouping Mingxing Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,3-Propanediol (PDO) Market Emerging Trajectories
Process intensification in microbial fermentation and regulatory carbon accounting are compressing the commercialization timeline for bio-based 1,3-Propanediol while reshaping how downstream buyers evaluate feedstock provenance.
Continuous fermentation technology is unifying yield stability with reduced capital intensity. PTT fiber producers in textiles are piloting supply agreements with continuous bioprocessing operators at pilot scale. The technology is enabling smaller fermentation footprints to compete on carbon intensity metrics rather than economies of volume alone.
REACH registration requirements in Europe are enforcing comprehensive toxicity dossiers that shape bio-based pathway commercialization timelines. ECHA's substance evaluation protocols now explicitly weight lifecycle carbon footprint in registration prioritization. Bio-PDO suppliers with ISO-certified renewable content are securing faster regulatory approval for European market access.
Brand-owner Scope 3 accounting is reconfiguring procurement evaluation criteria. PTT polymerization customers are unbundling feedstock certification from volume commitments, creating spot-market liquidity for qualified bio-based PDO. Cosmetics formulators in North America and Europe are leading this preference shift, paying structural premiums for documented renewable content.
1,3-Propanediol (PDO) Market Segmentation
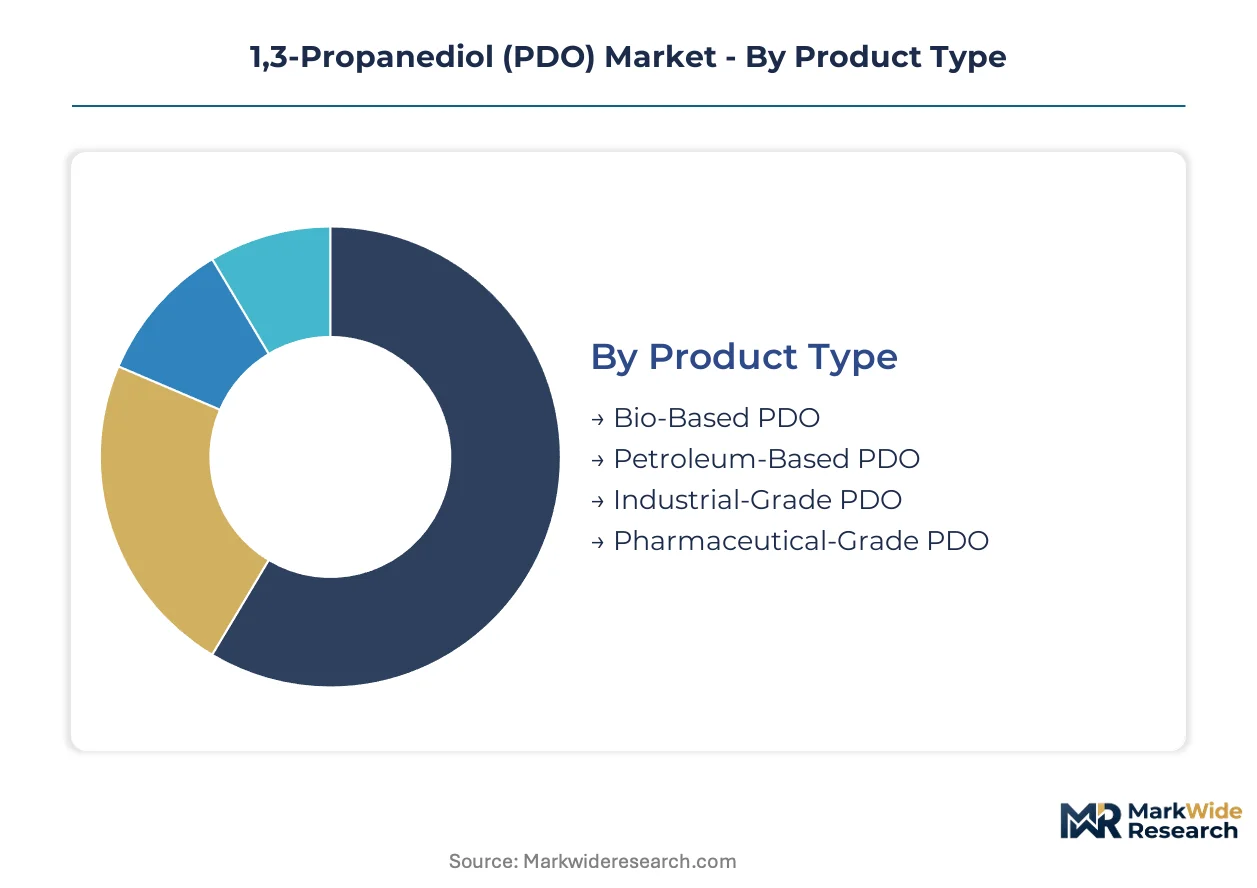
Segmentation in the 1,3-Propanediol market determines qualification pathways and margin capture. Certification burdens vary sharply across product grades and end-use industries, shaping which producers can access premium revenue pools.
Product Type:
Bio-Based PDO carries ISO 14040 lifecycle documentation requirements, while Pharmaceutical-Grade PDO demands FDA Drug Master File or EMA CEP submissions that extend commercialization timelines.
- Bio-Based PDO:Fermentation-derived from corn sugar or glycerol substrates with certified renewable content. Textile brands in Europe and North America are requalifying supply chains around this grade to meet Scope 3 emissions reduction commitments under CSRD and SEC climate disclosure rules.
- Pharmaceutical-Grade PDO:Purification to 99.5%+ purity with full regulatory documentation including ICH Q3C residual solvent guidelines compliance. EMA and FDA submission burdens exclude commodity fermentation entrants, concentrating margin pools with established API-grade suppliers.
- Petroleum-Based PDO:Propylene oxide hydration route leveraging Shell plc's global refining infrastructure.
- Industrial-Grade PDO:Standard purity specifications for polyester polymerization without pharmaceutical dossier requirements.
Petroleum-Based PDO sits at the top of the volume ranking, with Bio-Based PDO climbing the fastest.
End Use Industry:
Cost tier stratification separates pharmaceutical applications commanding 3-5x industrial grade pricing from commodity textile consumption.
- Textiles:PTT fiber polymerization consumes the largest volume share. Shenghong Group Holdings' integrated PTA-PTT-PDO complexes in China are concentrating domestic polyester capacity and creating captive demand for fermentation-derived feedstocks.
- Cosmetics:Humectant applications in premium skincare command structural premiums for documented renewable content. Formulators prioritize hygroscopic stability and skin compatibility, with ISO 16128 natural origin certification becoming a procurement gate.
- Pharmaceuticals:Excipient and API intermediate uses with stringent pharmacopeial compliance.
- Food & Beverage:Limited food additive applications under FEMA GRAS and JECFA evaluations.
Textiles anchor volume consumption, while Cosmetics generates the steepest margin expansion trajectory.
Form:
Application requirements dictate physical state selection, with liquid form dominating continuous polymerization processes.
- Liquid:Standard delivery state for industrial polymerization and formulation. Direct pumpability into PTT esterification reactors eliminates solid dissolution steps, reducing energy intensity in Shenghong Group and DuPont Tate & Lyle processing lines.
- Concentrate:Reduced water content for long-haul logistics efficiency. Bulk tanker shipments from Zhangjiagang Glory Biomaterial to coastal polyester clusters exploit this form for freight cost optimization.
- Powder:Solid-state handling for specific pharmaceutical tableting applications.
- Solution:Pre-diluted formulations for cosmetics compounding.
Liquid form maintains volume leadership, with Concentrate gaining share fastest in coastal China logistics corridors.
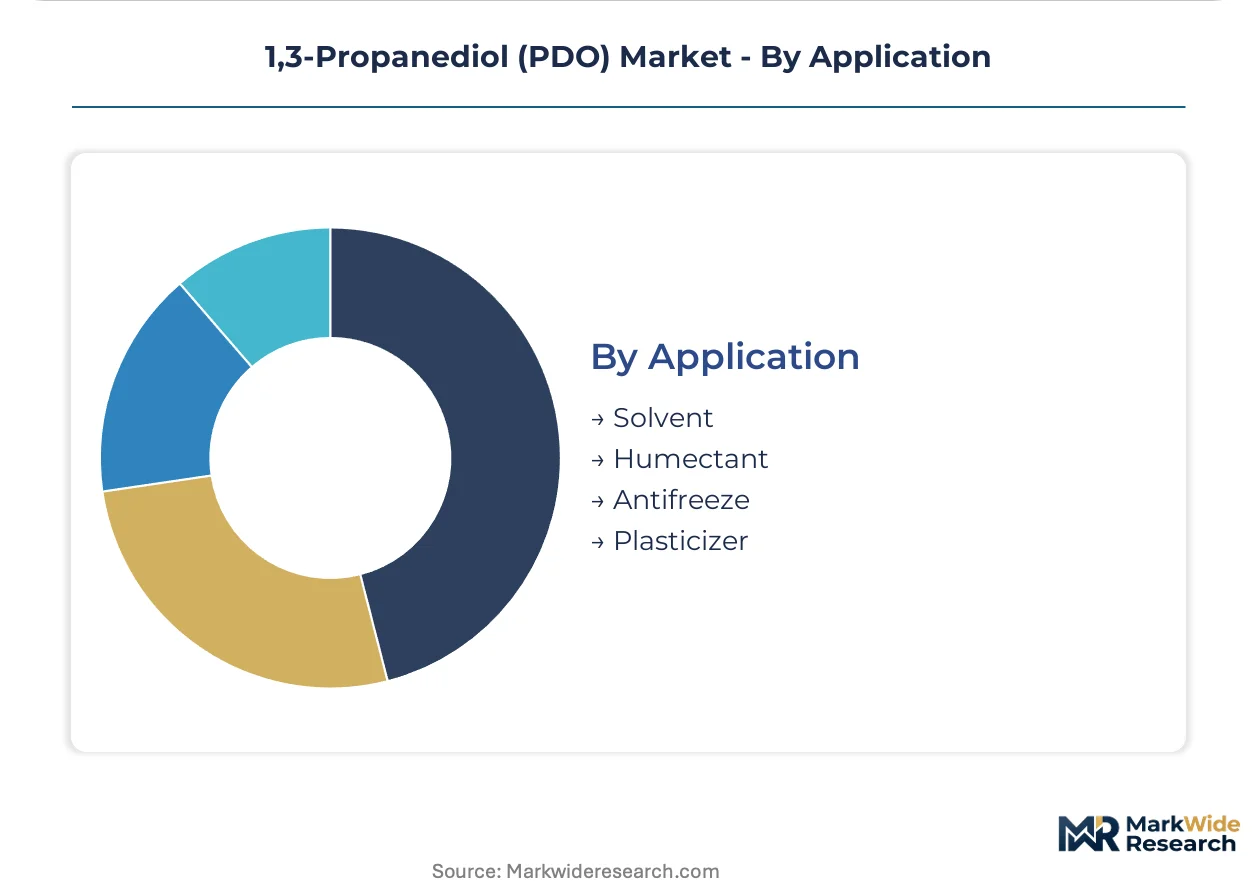
Application:
Margin structure inverts between commodity solvent uses and specialized humectant formulations.
- Solvent:PTT polymerization demand drives baseline volume. The application requires consistent monomer-grade purity but tolerates petroleum-derived supply, limiting premium capture for bio-based alternatives.
- Humectant:Cosmetics formulators in North America and Europe pay structural premiums for certified bio-based PDO. Hygroscopic stability and skin compatibility testing under ISO 24444 in vivo methods create qualification barriers that sustain margin pools.
- Antifreeze:De-icing and thermal transfer fluid applications with lower purity thresholds.
- Plasticizer:Polymer modification uses competing with established phthalate and bio-based alternatives.
Solvent applications dominate tonnage, with Humectant delivering the fastest value-per-kilogram expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenghong Group Holdings' integrated PTA-PTT-PDO complexes in Zhangjiagang anchor production gravity for polyester-grade supply. Fermentation-derived capacity expansion in coastal China contrasts with European qualification timelines shaped by REACH dossier requirements. The United States sustains petroleum-derived supply dominance through Gulf Coast refining infrastructure.
China
Shenghong Group Holdings and Zhangjiagang Glory Biomaterial concentrate polyester-grade PDO capacity in Jiangsu province. MEE dual carbon goals pressure domestic producers to document lifecycle footprints for market access. Coastal clusters from Ningbo to Shanghai integrate fermentation-derived feedstocks into captive PTT polymerization lines.
United States
DuPont Tate & Lyle Bio Products supplies corn sugar-derived PDO to cosmetics formulators seeking ISO-certified renewable content. EPA Clean Air Act provisions govern manufacturing emissions from Iowa fermentation facilities. The Gulf Coast petrochemical corridor sustains cost-competitive propylene oxide routes for industrial-grade supply.
Germany
ECHA substance evaluation protocols weight lifecycle carbon footprint in bio-PDO registration prioritization. REACH toxicity dossier requirements extend commercialization timelines for novel fermentation pathways. Industrial biotechnology clusters in North Rhine-Westphalia host pilot-scale continuous fermentation operators competing on carbon intensity metrics.
France
METabolic Explorer SA anchors French biotechnology leadership through pilot-scale continuous fermentation systems. ANSM pharmaceutical-grade specifications create qualification barriers for excipient applications exceeding 99.5% purity thresholds. The Lyon-Grenoble biotech corridor concentrates process intensification expertise for microbial production platforms.
Japan
Tokyo Chemical Industry Co., Ltd. distributes specialty-grade PDO to pharmaceutical and electronics formulation customers. METI industrial biotechnology initiatives support fermentation yield improvement programs at national research institutes. Osaka-Kobe chemical clusters import both petroleum-derived and bio-based grades for PTT polymerization and cosmetics compounding.
1,3-Propanediol (PDO) Market Vendor Landscape
Global majors compete with regional champions across feedstock sourcing and certification depth. Shell plc's petroleum-derived supply leverages global refining infrastructure for cost-competitive industrial-grade volumes. Three strategic archetypes populate the competitive landscape: integrated petrochemical majors with propylene oxide routes, fermentation specialists with ISO-certified renewable content, and pilot-scale biotech operators competing on carbon intensity. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure downstream offtake agreements.
Within the fermentation specialist tier, DuPont Tate & Lyle Bio Products and METabolic Explorer SA exemplify divergent scale strategies. Shenghong Group Holdings occupies a position as the anchor for integrated polyester value chain control. Shell plc represents the petroleum-derived incumbent defending volume leadership through refining infrastructure. Zhangjiagang Glory Biomaterial and Haihang Industry Co., Ltd. sit within the regional Chinese supplier archetype, serving domestic PTT polymerization demand.
| Leading Market Players |
|---|
| METabolic Explorer SA |
| Shenghong Group Holdings |
| DuPont Tate & Lyle Bio Products |
| Haihang Industry Co., Ltd. |
| Tokyo Chemical Industry Co., Ltd. |
| Zhangjiagang Glory Biomaterial |
| Shell plc |
| Primient |
| Zouping Mingxing Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Corn sugar futures volatility on the Chicago Board of Trade cascades through fermentation-based PDO production into three-tier pricing stratification across pharmaceutical-grade, industrial-grade, and commodity solvent tiers. Shell plc's propylene oxide route maintains cost floors in industrial segments while bio-based suppliers capture premiums through ISO-certified renewable content documentation.
Pricing Analysis
Input-cost pass-through from agricultural feedstock markets governs bio-based PDO pricing, with corn sugar spikes compressing fermentation margins against petroleum-derived benchmarks. Price differentiation rests on certification depth—pharmaceutical-grade specifications with FDA Drug Master File documentation command 3-5x industrial-grade levels, while cosmetics formulators pay structural premiums for ISO 16128 natural origin verification. Pricing pressure stems from Shenghong Group Holdings' integrated PTA-PTT-PDO complexes in China, which concentrate polyester-grade supply and force spot-market liquidity adjustments. Textile polymerization customers exhibit highest price sensitivity due to commodity PTT fiber economics, whereas pharmaceutical excipient buyers prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for PTT polymerization customers, with textile brands unbundling feedstock certification from volume commitments to reduce procurement dependency. Geographic supply concentrates in China, the United States, and Germany—Shenghong Group and Zhangjiagang Glory Biomaterial anchor Jiangsu province fermentation capacity, DuPont Tate & Lyle Bio Products sustains Iowa corn sugar processing, and METabolic Explorer SA operates pilot-scale systems in France. Raw material dependencies center on corn sugar, glycerol substrates, and propylene oxide feedstocks. Single-source vulnerability persists in pharmaceutical-grade purification, where 99.5% purity thresholds with full regulatory documentation exclude commodity entrants. Distribution runs through coastal polyester clusters in China, bulk tanker networks to European cosmetics formulators, and direct pump delivery into captive PTT polymerization lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through fermentation yield improvements that compress bio-based production costs toward petroleum-derived parity while premium-tier shifts in cosmetics and pharmaceuticals sustain pricing power.
For Market Incumbents: Extend certification depth to defend position against emerging continuous fermentation operators. Shell plc should deepen backward integration into propylene oxide supply while accelerating bio-based pathway pilot investments to hedge regulatory carbon pricing. DuPont Tate & Lyle Bio Products must reinforce ISO 14040 documentation moats as ECHA registration protocols increasingly weight lifecycle carbon footprint in prioritization decisions.
For New Entrants and Emerging Players: The 3-5x price-point gap between pharmaceutical-grade and industrial-grade specifications creates white-space opportunity for mid-purity fermentation entrants with targeted regulatory dossiers. Cosmetics humectant applications in North America represent the most penetrable segment, with ISO 16128 certification serving as the primary go-to-market gate. Continuous fermentation technology at pilot scale enables carbon intensity-based competition without volume-scale capital requirements.
For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation specialists possessing validated continuous bioprocessing platforms and established regulatory approval pathways. Long-term viability over the next decade hinges on feedstock cost volatility management and yield curve positioning relative to petroleum-derived benchmarks. The signal to watch is Shenghong Group Holdings' captive demand absorption rates, which indicate whether integrated Chinese polyester capacity crowds out independent bio-based suppliers or creates qualification pathways for boutique operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Pilot-scale systems from METabolic Explorer SA compete on carbon intensity metrics rather than volume economies alone. |
| REACH Registration Acceleration | ECHA substance evaluation protocols now weight lifecycle carbon footprint, favoring ISO-certified bio-based pathway submissions. |
| Backward Integration into Feedstock | Shenghong Group Holdings' integrated PTA-PTT-PDO complexes concentrate polyester-grade supply and captive demand. |
| Pharmaceutical-Grade Purification Investment | 99.5% purity thresholds with FDA Drug Master File documentation exclude commodity fermentation entrants from margin pools. |
| Cosmetics Certification Partnerships | ISO 16128 natural origin verification creates procurement gates for premium skincare formulators in Europe and North America. |
Methodological Framework
Multiple input streams—primary interviews with plant managers at fermentation facilities, procurement leads at PTT polymerization operations, and technical R&D directors in industrial biotechnology—were reconciled against secondary validation from customs/trade data, SEC 10-K filings, ECHA registration databases, and Cefic chemical industry reports. Bottom-up capacity modeling across bio-based and petroleum-derived production routes was triangulated with top-down demand segmentation from textile, cosmetics, and pharmaceutical end-use industries.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product grade tier, end-use industry, and regional production hub. CAGRs were derived from supply-demand balance modeling incorporating fermentation yield improvement curves and feedstock cost volatility scenarios. Industry-specific forecast inputs included Shenghong Group Holdings' integrated complex ramp schedules and ECHA registration timeline assumptions for novel bio-based pathways.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation scale-up would alter the outlook if yield stability proves elusive at commercial volumes. Deviation in corn sugar price volatility or propylene oxide refining margins would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Continuous Reactors Market