
 Non-PVC Waterstop Market | 2026-2036
Non-PVC Waterstop Market Size, Share, and Industry Trends Forecast 2026-2036
Non-PVC Waterstop Market Insights
EPDM rubber is broadening its addressable market in waterstop applications as contractors seek elastomeric alternatives with superior chemical resistance and extended service life. Sika AG leverages its global formulation expertise to supply hydrophilic and polyurethane waterstops across European infrastructure corridors. Fosroc International Limited anchors its position through specialized construction chemicals distribution in Middle Eastern and Asian markets. Trelleborg AB competes with advanced polymer engineering capabilities drawn from its industrial sealing heritage.
Non-PVC waterstops are engineered sealing devices manufactured from elastomeric or hydrophilic compounds such as EPDM, bentonite, or polyurethane, designed to prevent water ingress through concrete joints in submerged or pressurized structures. These products typically accommodate joint movement of 20-50% while maintaining watertight integrity across temperature ranges from -40°C to 80°C, serving critical functions in tunnels, dams, and wastewater containment facilities. Hydrophilic waterstop variants command premium positioning due to their self-sealing expansion upon water contact, while bentonite-based systems occupy cost-sensitive segments in below-grade construction. Polyurethane waterstops are gaining fastest in tunneling applications where chemical resistance and flexibility under dynamic loading prove essential.
EPA construction runoff standards and REACH substance restrictions are reshaping material specifications, pushing specification engineers toward certified non-PVC alternatives in federally funded and European public works. ISO 9001 quality management and ASTM D2000 classification systems govern product certification, creating compliance barriers for uncertified suppliers while rewarding documented traceability. China GB standards and MEE environmental enforcement are tightening domestic production requirements, altering export competitiveness for regional manufacturers. Stakeholders must monitor evolving chemical substance inventories and procurement mandates to align product portfolios with jurisdiction-specific compliance trajectories.
Market Dynamics
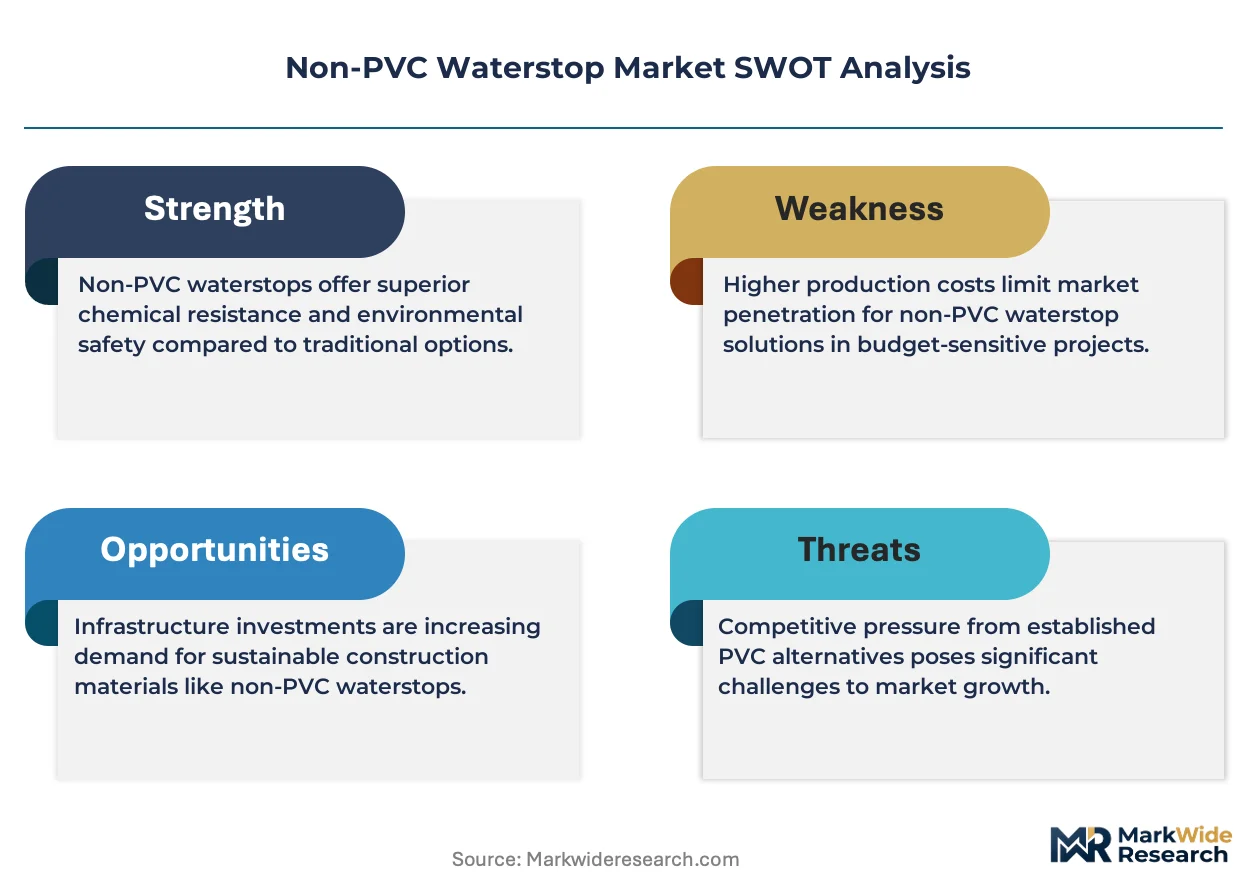
REACH substance restrictions and EPA construction runoff standards are forcing specification engineers toward certified non-PVC alternatives, while infrastructure developers in Germany, China, and Brazil phase out legacy PVC-based sealing solutions in favor of hydrophilic and bentonite formulations.
Growth Catalysts
- EPA Guidelines:United States federally funded projects now mandate non-PVC waterstops in wastewater containment facilities, creating specification pull across public works procurement.
- Tunneling Applications:Polyurethane waterstops are displacing conventional alternatives in high-pressure tunnel segments where dynamic loading resistance proves critical.
- Brazil Infrastructure:National infrastructure programs and green building certifications favor elastomeric sealing solutions in large-scale civil engineering corridors.
Market Restraints
- Raw Material Volatility:EPDM rubber and specialized polyurethane feedstock prices fluctuate with petrochemical supply chain disruptions, compressing formulation margins.
- Technical Limitations:Bentonite-based systems exhibit reduced performance in saline or chemically aggressive environments, restricting deployment in coastal industrial facilities.
- Regulatory Friction:China's GB standards and MEE environmental enforcement impose domestic production requirements that alter export competitiveness for regional manufacturers.
Strategic Opportunities
- India Infrastructure:Underpenetrated dam and irrigation project markets present white space as national water security programs expand concrete-intensive construction.
- EU Green Deal:Carbon footprint disclosure requirements and circular economy procurement mandates favor domestically produced hydrophilic formulations with certified supply chain traceability.
- Digital Specification Platforms:Engineering procurement networks are compressing distributor layers, enabling direct manufacturer engagement with specification engineers in Middle Eastern markets.
Industry Challenges
- Certification Timeline Compression:ISO 9001 quality management and ASTM D2000 classification documentation requirements extend product qualification cycles, delaying market entry for reformulated compounds.
- Integration Complexity:Hydrophilic waterstop installation demands specialized joint preparation protocols that conflict with legacy contractor training programs, creating field execution gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-PVC Waterstop Market |
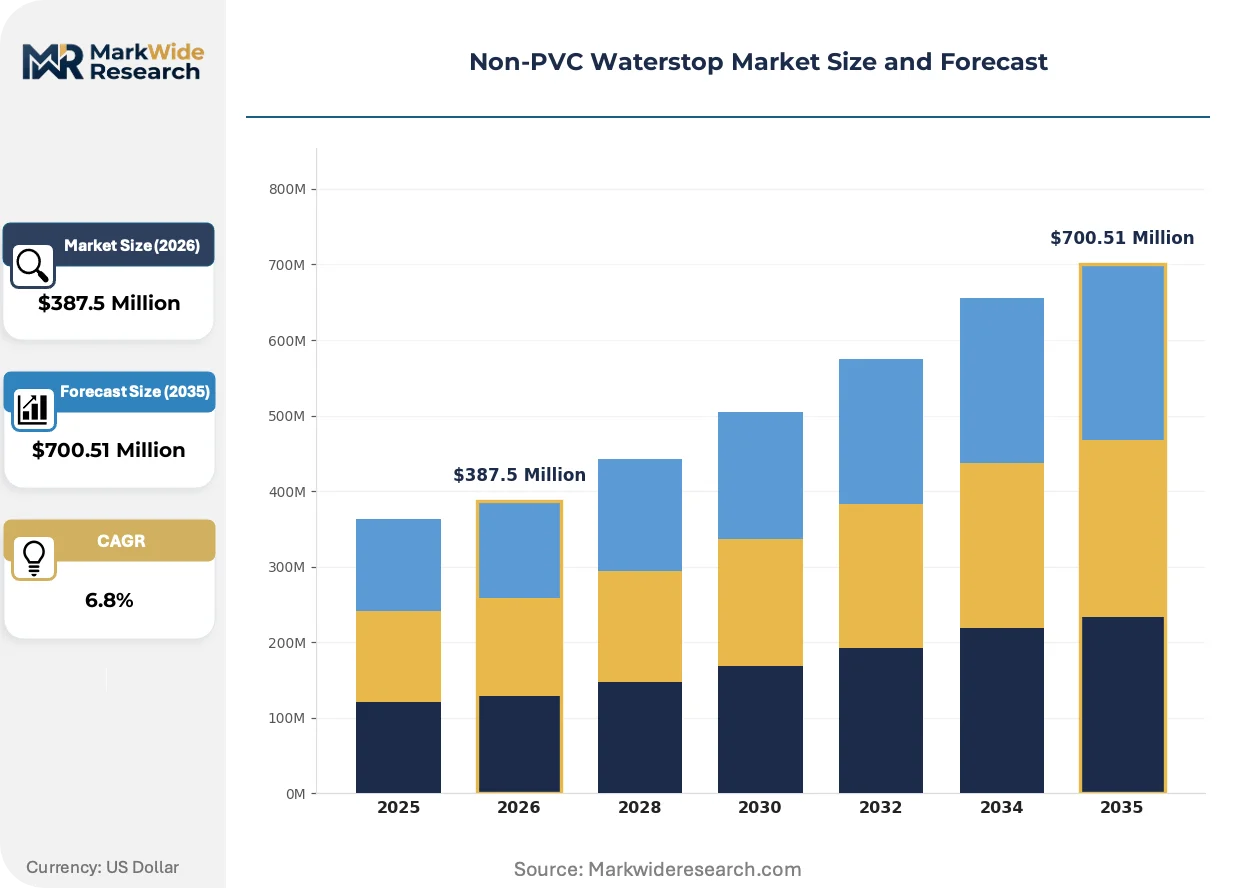
| Market Size in 2026 | $387.5 Million |
| Market Size in 2035 | $700.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Waterstop, Bentonite Waterstop, Polyurethane Waterstop, PVC Waterstop Application: Construction, Tunneling, Water Retention Structures, Wastewater Treatment End User: Contractors, Infrastructure Developers, Government Projects, Residential Builders Form: Sheet, Roll, Preformed, Liquid |
| Companies Covered | BASF SE, Fosroc International Limited, Sika AG, Emagineered Solutions, Inc., Krystol Group, Trelleborg AB, GCP Applied Technologies Inc., Parchem Construction Supplies Pty Ltd, Henry Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-PVC Waterstop Market Trends and Innovations
Material science advances and regulatory chemistry inventories are converging to reshape product portfolios, with formulation houses racing to document traceability ahead of procurement mandate deadlines.
Advanced polyurethane waterstop compounds with tailored hydrophilic additives are absorbing specification share in tunneling and pressurized structure applications. Contractors in German and Swiss alpine tunnel projects specify these formulations for their self-sealing expansion under water contact combined with chemical resistance. This technology is absorbing premium positioning previously held by conventional EPDM systems in dynamic joint movement scenarios.
REACH substance restrictions in Europe are eliminating certain plasticizer chemistries from construction materials specifications. ECHA candidate list updates now trigger automatic substitution reviews in public procurement frameworks across German federal states. Hydrophilic and bentonite waterstop categories are capturing displaced volume as specification engineers pre-empt compliance risk.
Buyer concentration among major infrastructure consortia is consolidating procurement authority, compressing supplier qualification to tier-one certified manufacturers. Engineering-procurement-construction firms in Chinese state-owned enterprise structures now mandate documented ASTM D2000 classification and ISO 9001 traceability as baseline entry requirements. This pattern concentrates specification influence among vertically integrated formulation specialists with captive testing laboratories.
Non-PVC Waterstop Market Segmentation
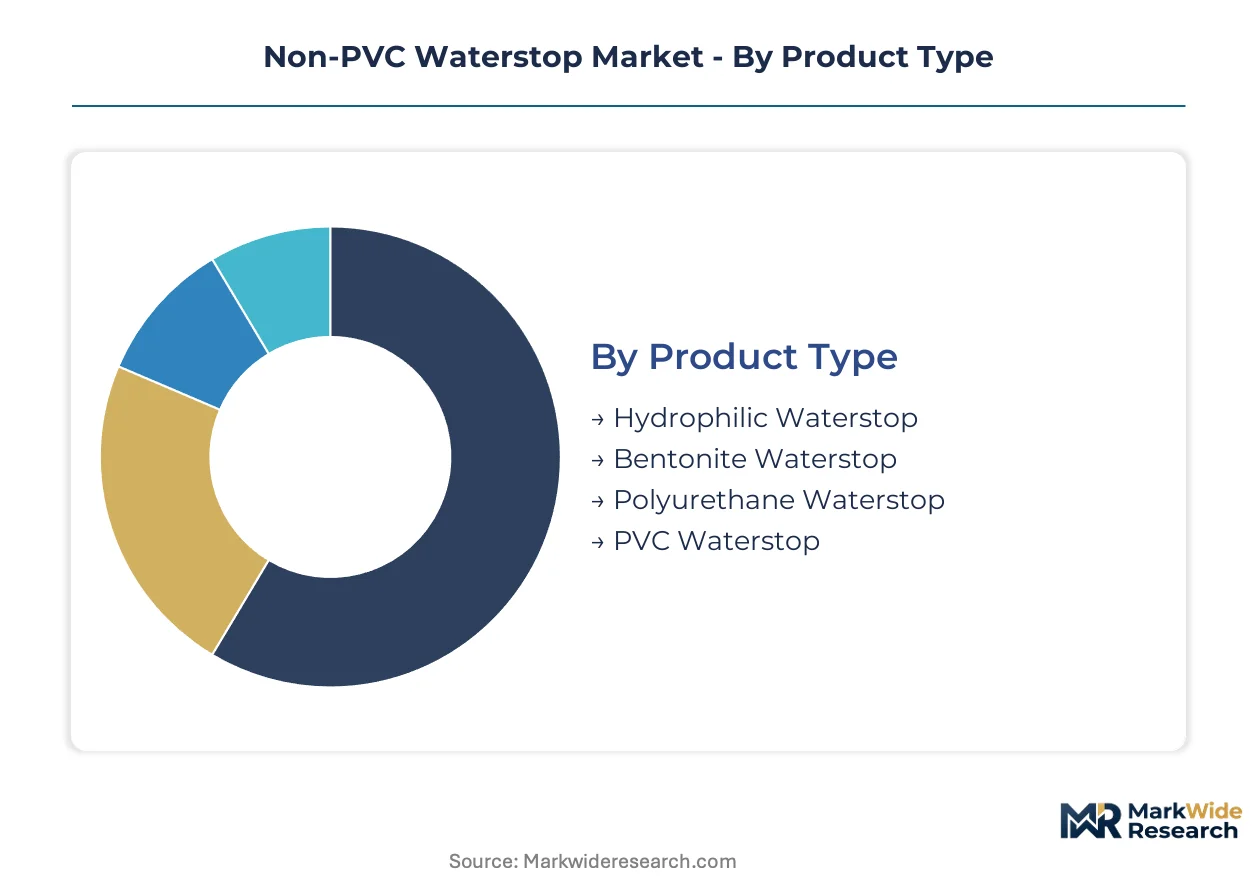
Non-PVC waterstop specification hinges on joint movement tolerance, chemical exposure profiles, and installation logistics. Engineers select formulations based on concrete cure conditions, hydrostatic pressure ratings, and contractor capability matrices. Each segmentation dimension carries distinct procurement workflows and margin structures.
Product Type:
Contractors upgrading from legacy PVC systems evaluate hydrophilic and bentonite alternatives against polyurethane formulations for chemical resistance and self-sealing performance.
- Hydrophilic Waterstop:These rubber-based compounds expand upon water contact to create self-sealing barriers within concrete joints. German alpine tunnel contractors specify hydrophilic variants for dynamic joint movement scenarios where passive sealing proves inadequate.
- Polyurethane Waterstop:Advanced elastomeric formulations deliver chemical resistance and flexibility under cyclic loading. Chinese state-owned infrastructure consortia favor polyurethane for high-pressure water retention structures requiring extended service life.
- Bentonite Waterstop:Sodium bentonite clay strips swell upon hydration to fill joint voids. Below-grade construction in cost-sensitive Brazilian markets deploys bentonite for foundation waterproofing where chemical exposure remains minimal.
- PVC Waterstop:Legacy chlorinated formulations face phased replacement under REACH and EPA procurement mandates. Remaining specification volume concentrates in maintenance contracts and developing markets with delayed regulatory adoption.
Volume placements concentrate in bentonite systems; the faster expansion belongs to polyurethane formulations.
Application:
End-use selection tracks hydrostatic pressure differentials, joint movement magnitude, and regulatory exposure severity across project types.
- Tunneling:High-pressure segments with dynamic ground loads demand hydrophilic or polyurethane formulations. Swiss and Austrian alpine projects specify premium elastomeric systems for watertight integrity across freeze-thaw cycles.
- Wastewater Treatment:Aggressive chemical environments in municipal and industrial containment facilities require corrosion-resistant sealing. EPA construction runoff standards now mandate non-PVC alternatives in US federally funded treatment infrastructure.
- Water Retention Structures:Dams, reservoirs, and irrigation canals deploy bentonite and hydrophilic systems for static joint conditions. India's national water security programs are expanding concrete-intensive construction in this category.
- Construction:General building foundations and below-grade walls represent high-volume, price-sensitive deployment. Residential and commercial builders in Brazil favor bentonite rolls for standard foundation waterproofing.
Construction absorbs the greatest unit volume; tunneling applications are climbing the fastest as infrastructure investment intensifies.
End User:
Procurement authority and technical specification competence vary sharply across buyer categories, fragmenting pricing power and service requirements.
- Infrastructure Developers:Large consortia with in-house engineering capabilities specify certified formulations directly. German federal state procurement frameworks now trigger automatic substitution reviews for REACH-listed chemistries.
- Government Projects:Public works procurement mandates ISO 9001 traceability and ASTM D2000 classification as baseline entry requirements. Chinese state-owned enterprise structures concentrate specification influence among tier-one certified manufacturers.
- Contractors:Field execution responsibility creates demand for installation-friendly formats and technical support. Hydrophilic waterstop protocols conflict with legacy training programs, creating qualification gaps.
- Residential Builders:Price-sensitive volume buyers prioritize standard bentonite sheet and roll formats. Green building certification programs in Brazil and Germany are shifting specification toward documented non-PVC alternatives.
Government procurement commands the strictest certification requirements; infrastructure developers are gaining share fastest as consortia consolidate authority.
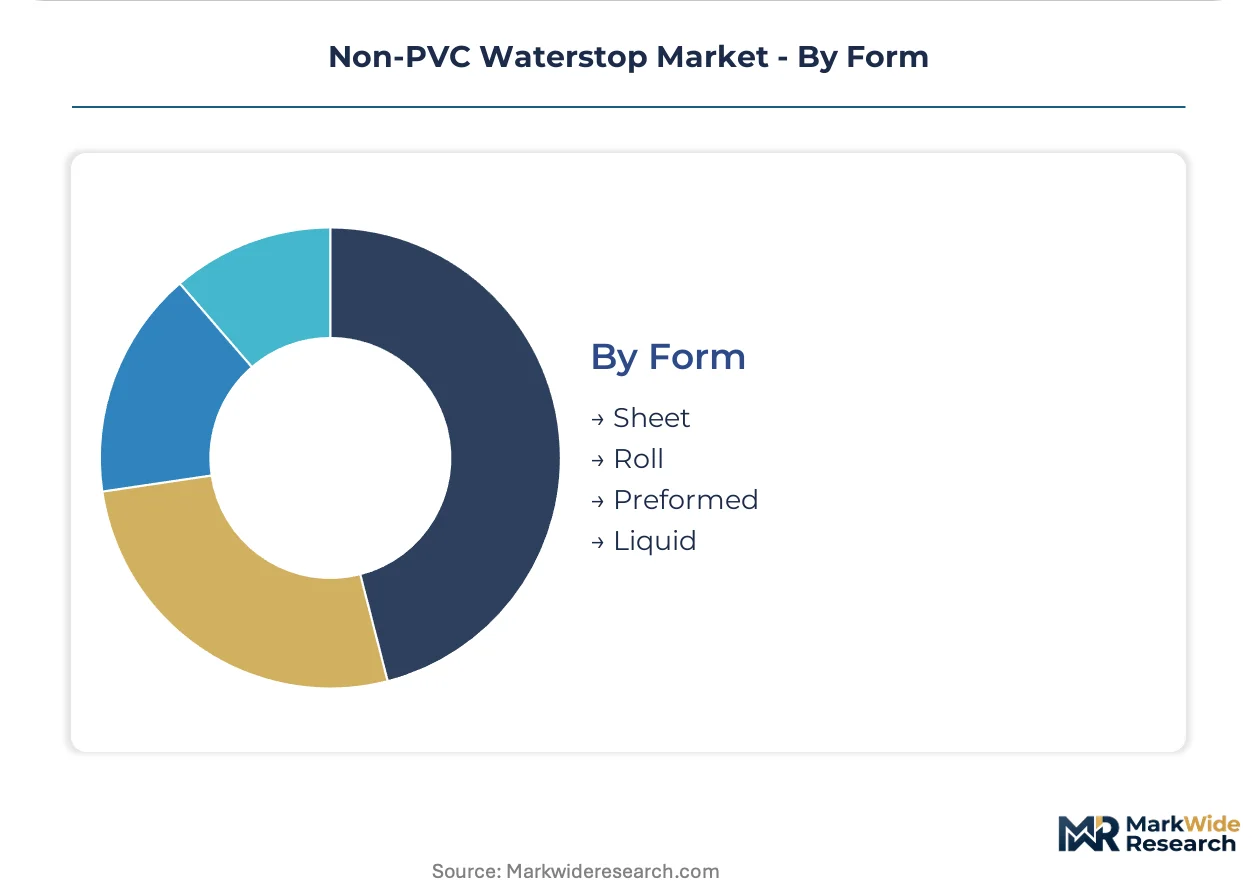
Form:
Physical configuration determines installation labor content, field adaptability, and logistics complexity across project scales.
- Preformed:Factory-molded profiles with integrated ribs or bulbs ensure consistent placement in critical joints. Tunneling contractors in Switzerland and Germany specify preformed hydrophilic and polyurethane sections for high-reliability segments.
- Sheet:Flat stock allows field cutting and custom shaping for irregular geometries. Water retention structures in India and Brazil deploy bentonite sheets for large-area foundation waterproofing.
- Roll:Continuous coil formats reduce field joints and accelerate installation on linear projects. Below-grade construction contractors favor bentonite rolls for standard foundation perimeter sealing.
- Liquid:Spray or pour-applied polyurethane creates monolithic barriers without physical seams. Complex geometries in retrofit wastewater treatment facilities specify liquid systems where preformed profiles prove impractical.
Sheet and roll formats dominate unit placements; liquid application is expanding most quickly in retrofit and complex geometry scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and Brazil where infrastructure investment and regulatory substitution mandates converge. Federal procurement standards and green building certifications are phasing out legacy PVC sealing solutions across these markets.
Germany
Alpine tunnel construction and wastewater infrastructure renewal drive specification of hydrophilic and polyurethane formulations. ECHA REACH substance restrictions trigger automatic substitution reviews in federal state procurement frameworks. Bavarian and Baden-Württemberg engineering consortia specify certified elastomeric systems for high-pressure water retention structures.
China
State-owned enterprise infrastructure programs and national water security initiatives expand concrete-intensive construction. GB standards and MEE environmental enforcement tighten domestic production requirements for construction materials. Yangtze River Delta and Pearl River Delta manufacturing clusters supply hydrophilic and bentonite formulations for dam and irrigation projects.
Brazil
National infrastructure programs and green building certifications favor elastomeric sealing solutions in civil engineering corridors. ANVISA chemical substance monitoring and federal environmental licensing shape material specifications for public works. São Paulo and Rio de Janeiro construction markets deploy bentonite systems for cost-sensitive foundation waterproofing.
United States
EPA construction runoff standards now mandate non-PVC waterstops in federally funded wastewater containment facilities. Infrastructure Investment and Jobs Act disbursements accelerate specification pull across public works procurement. Texas and California water districts specify polyurethane formulations for high-pressure tunnel segments and treatment plant upgrades.
India
National water security programs and dam rehabilitation initiatives expand concrete-intensive construction in underpenetrated markets. Bureau of Indian Standards certification requirements and central environmental clearance protocols govern material selection. Maharashtra and Gujarat infrastructure corridors represent white space for hydrophilic and bentonite system deployment.
Non-PVC Waterstop Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise concentrating among vertically integrated European and Asian suppliers. The vendor base organizes around three strategic archetypes: multinational construction chemical houses with captive testing laboratories, regional elastomer specialists serving infrastructure consortia, and commodity bentonite processors competing on logistics proximity. Consolidation pressures favor M&A activity among mid-cap specialists seeking ASTM D2000 certification capabilities, while technology licensing agreements accelerate polyurethane formulation access for regional compounders.
Among multinational construction chemical houses, Sika AG exemplifies the vertically integrated archetype with documented ISO 9001 traceability, while Fosroc International Limited occupies a position within specialized distribution networks. Trelleborg AB represents advanced polymer engineering heritage translated into industrial sealing applications. These three anchors illustrate how certification depth and formulation breadth stratify competitive position across procurement frameworks.
| Leading Market Players |
|---|
| BASF SE |
| Fosroc International Limited |
| Sika AG |
| Emagineered Solutions, Inc. |
| Krystol Group |
| Trelleborg AB |
| GCP Applied Technologies Inc. |
| Parchem Construction Supplies Pty Ltd |
| Henry Company |
| Others |
Pricing and Supply Chain Analysis
Government procurement consortia in Germany, China, and Brazil concentrate buying power and enforce certification-tier pricing that stratifies suppliers by ASTM D2000 classification and ISO 9001 traceability documentation. This buyer concentration rewards vertically integrated formulation houses with captive testing laboratories while compressing margins for regional compounders lacking documented quality systems.
Pricing Analysis
High-volume bentonite sheet and roll formats trade at commodity-adjacent levels with thin margins, while hydrophilic and polyurethane formulations capture premium positioning through performance differentiation. Three-tier pricing structure separates certified elastomeric systems for tunneling applications from standard hydrophilic grades and economy bentonite rolls. Cost compression in the bentonite segment is intensifying as Brazilian and Indian infrastructure programs drive volume procurement. Residential builders and small contractors exhibit the greatest price sensitivity, whereas German alpine tunnel consortia and Chinese state-owned enterprises prioritize certified performance over unit cost.
Supply Chain Analysis
China's GB standards and MEE environmental enforcement, alongside Brazil's ANVISA chemical substance monitoring, are reshaping sourcing patterns toward domestic production or joint-venture structures. Manufacturing gravity centers on Germany for advanced polyurethane formulations, China for hydrophilic and bentonite volume production, and the United States for EPA-compliant specialty compounds. Feedstock supply rests on EPDM rubber from petrochemical complexes, sodium bentonite from Wyoming and Turkey deposits, and specialized polyurethane prepolymers. Single-source vulnerability concentrates in certified elastomeric compound supply for tunneling specifications. Distribution runs through construction chemical distributors and direct engagement with engineering-procurement-construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as formulation houses pursue backward integration into certified raw material supply to secure ASTM D2000 documentation and compress qualification timelines.
For Market Incumbents: Lock in specification engineer relationships through embedded technical service teams and expand captive testing laboratory capacity to accelerate reformulation cycles ahead of REACH substance list updates. Hydrophilic waterstop installation protocol complexity creates field execution gaps that threaten brand equity if contractor training lags. Prioritize direct engagement with Chinese state-owned enterprise procurement frameworks to consolidate tier-one supplier status. For New Entrants and Emerging Players: Specialty distributors in Middle Eastern markets offer the most accessible channel for building specification track records without confronting entrenched European and Asian incumbents head-on. India's underpenetrated dam and irrigation project markets present white space as national water security programs expand concrete-intensive construction. Pursue technology licensing agreements with established polyurethane formulators to bypass multi-year certification timelines. For Investors and Strategic Acquirers: The window for entry favors mid-cap regional specialists possessing ASTM D2000 classification capabilities but lacking global distribution infrastructure. Long-term viability hinges on regulatory chemistry inventory management and documented supply chain traceability as procurement mandates tighten. Watch for ECHA candidate list updates triggering automatic substitution reviews as the inflection indicator for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Raw Materials | Secures ASTM D2000 documentation and insulates margin from EPDM price volatility. |
| Capacity Expansion in Indian Manufacturing | Positions suppliers for national water security program disbursements and BIS certification proximity. |
| Joint Venture with Chinese State-Owned Enterprises | Navigates GB standards compliance and MEE enforcement while accessing Yangtze River Delta infrastructure corridors. |
| Green Manufacturing Transition | Aligns product portfolios with EU Green Deal carbon footprint disclosure and circular economy procurement mandates. |
| Long-term Supply Agreement with Tunneling Consortia | Locks in premium polyurethane volume through German and Swiss alpine project pipelines. |
Research Methodology
Independent corroboration across specification engineer interviews, construction chemical distributor discussions, and regulatory affairs consultations underwrites the qualitative findings in this study. Primary fieldwork engaged plant managers at polyurethane formulation facilities, procurement leads at German infrastructure consortia, technical R&D directors at elastomer specialists, and channel partners in Middle Eastern distribution networks. Secondary validation drew from ECHA substance inventory updates, EPA construction runoff guidance documents, China GB standards filings, and customs trade data for EPDM and bentonite feedstock flows. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts.
Rate-of-change decomposition across product type, application, end user, and form dimensions structures the analytical framework over the projection horizon. Modeled segmentation captures hydrophilic versus polyurethane versus bentonite formulation splits, tunneling versus wastewater treatment versus water retention structure applications, and government versus infrastructure developer versus contractor procurement authority. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory substitution mandates and infrastructure disbursement schedules. Industry-specific inputs include REACH substance restriction timelines and national water security program capital commitments.
Caveats apply where ECHA candidate list revisions, EPA procurement mandate enforcement intensity, or China MEE environmental inspection schedules could materially shift the outlook. Forecasts reflect assumptions regarding certification timeline compression and contractor training adoption rates for hydrophilic installation protocols. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
FCCL Coating Machine Market