
 Asia Pacific Rotomoulding Powder Market | 2026-2036
Asia Pacific Rotomoulding Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Rotomoulding Powder Market Analysis
Distributor networks across Southeast Asia is fragmenting as regional compounders build direct-to-molder relationships. SCG Chemicals Co., Ltd leverages its Thai petrochemical base to sustain captive resin supply for rotomoulding customers. Reliance Industries Limited anchors India's domestic polyethylene capacity with backward-integrated refinery outputs. LyondellBasell competes through differentiated metallocene-grade powders targeting thin-wall tank applications.
Asia Pacific rotomoulding powder comprises thermoplastic resins—primarily linear low-density and cross-linked polyethylene with melt indices between 3 and 8 g/10min—formulated for hollow-part manufacture via biaxial mold rotation at 250-400°C. These powders produce seamless, stress-free containers, vehicle fuel tanks, and medical housings with uniform wall thickness and corrosion immunity. Polyethylene dominates formulation volumes across the region given its processability balance and cost structure, while PVC retains niche positions in chemical-resistant industrial tanks where flame-retardant specifications apply. The containers application leads value generation due to water storage and agricultural chemical tank demand, whereas medical devices represent a faster-growing margin pool as sterilizable grades gain traction in India's expanding hospital supply chain.
BIS certification requirements for potable water contact materials and China's GB standards for plastic chemical resistance are elevating barrier-property specifications across the region. India's PLI scheme for specialty chemicals and Thailand's Board of Investment incentives for downstream plastic processing are redirecting capital toward localized compounding capacity. Stakeholders must monitor how evolving ESG disclosure rules under CSRD-aligned supplier mandates from European OEMs reshape material traceability requirements for Asia Pacific powder exporters.
Market Dynamics
Direct-to-molder procurement models are fragmenting established distributor networks across Southeast Asia, while China's GB standards and India's BIS certification tighten material specifications for chemical resistance and food-contact applications.
Growth Catalysts
- Urban infrastructure expansion:Water tank manufacturers in Thailand, Vietnam, and Indonesia are scaling procurement of rotomoulding-grade polyethylene as municipal budgets widen for storage systems.
- India's PLI scheme for specialty chemicals:Capital incentives redirect investment toward localized compounding capacity, reducing import dependence for formulated powders.
- Metallocene-grade powder adoption:Thin-wall tank applications in automotive fuel systems and medical housings drive specification upgrades for uniform wall thickness performance.
Market Restraints
- Feedstock volatility:Ethylene price swings tied to naphtha-cracking economics compress compounding margins across integrated and non-integrated producers.
- Supply concentration in Thai petrochemical bases:Captive resin supply advantages for regional incumbents create barriers for new compounders seeking scale.
- Cross-linked polyethylene processing limitations:Higher melt viscosity restricts thin-wall capability compared to linear low-density alternatives, constraining medical device penetration.
Strategic Opportunities
- Vietnam's underpenetrated rotomoulding cluster:Northern industrial zones near Haiphong lack localized powder supply, creating white space for compounding investment.
- CSRD-aligned supplier mandates:European OEM traceability requirements for Asia Pacific exporters create premium positioning for ESG-disclosure-ready compounders.
- Sterilizable medical-grade formulations:India's expanding hospital supply chain demands gamma-stable polyethylene powders for device housings and surgical equipment.
Industry Challenges
- Rotational molding technician scarcity:Vietnam and Indonesia lack trained operators for biaxial mold rotation at 250-400°C process windows, slowing cluster development.
- BIS certification timeline compression:Potable water contact approvals require 12-18 month testing cycles, delaying product launches for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Rotomoulding Powder Market |
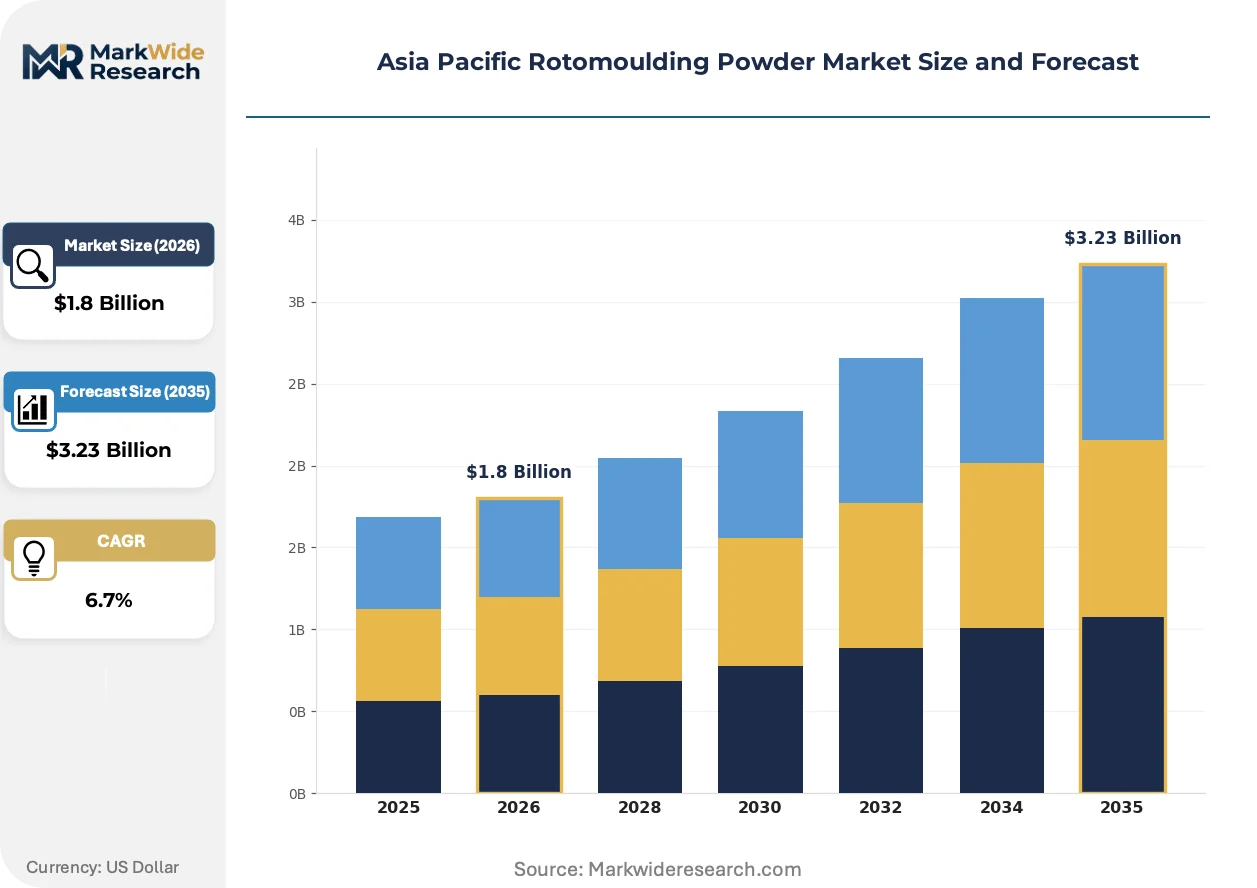
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Nylon Application: Containers, Automotive Parts, Toys, Medical Devices End User: Manufacturers, Distributors, Retailers, OEMs Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | SCG Chemicals Co., Ltd, Reliance Industries Limited, LyondellBasell, Dalian Bona Biological Technology Co., Ltd, Asahi Kasei, BASF SE, Dow Inc., Formosa Plastics Corporation, SABIC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Rotomoulding Powder Market Emerging Trajectories
Formulation technology is converging with regulatory pressure to reshape competitive positioning, as regional compounders invest in differentiated grades and traceability systems.
Metallocene-catalyzed polyethylene is hybridizing conventional Ziegler-Natta powder properties with enhanced melt strength and optical clarity. Medical device manufacturers in India's western corridor are specifying these grades for sterilizable housings at accelerating rates. The technology is hybridizing barrier-property benchmarks across food-contact and chemical-storage segments previously served by standard linear low-density formulations.
China's GB standards for plastic chemical resistance are elevating barrier-property specifications for industrial tank applications. Compounders must reformulate with enhanced ESCR (environmental stress crack resistance) to meet immersion-test protocols for agricultural chemicals. Southeast Asian exporters targeting Chinese OEMs are investing in certified testing capacity to maintain specification compliance.
Direct procurement relationships are displacing traditional distributor intermediaries across Thailand and Vietnam. Regional compounders with captive resin supply are building technical service teams to support molders directly, bypassing 15-20% distributor margins. This channel compression is most visible in automotive fuel tank supply chains, where Japanese OEMs demand formulation-to-mold technical collaboration.
Asia Pacific Rotomoulding Powder Market Segmentation
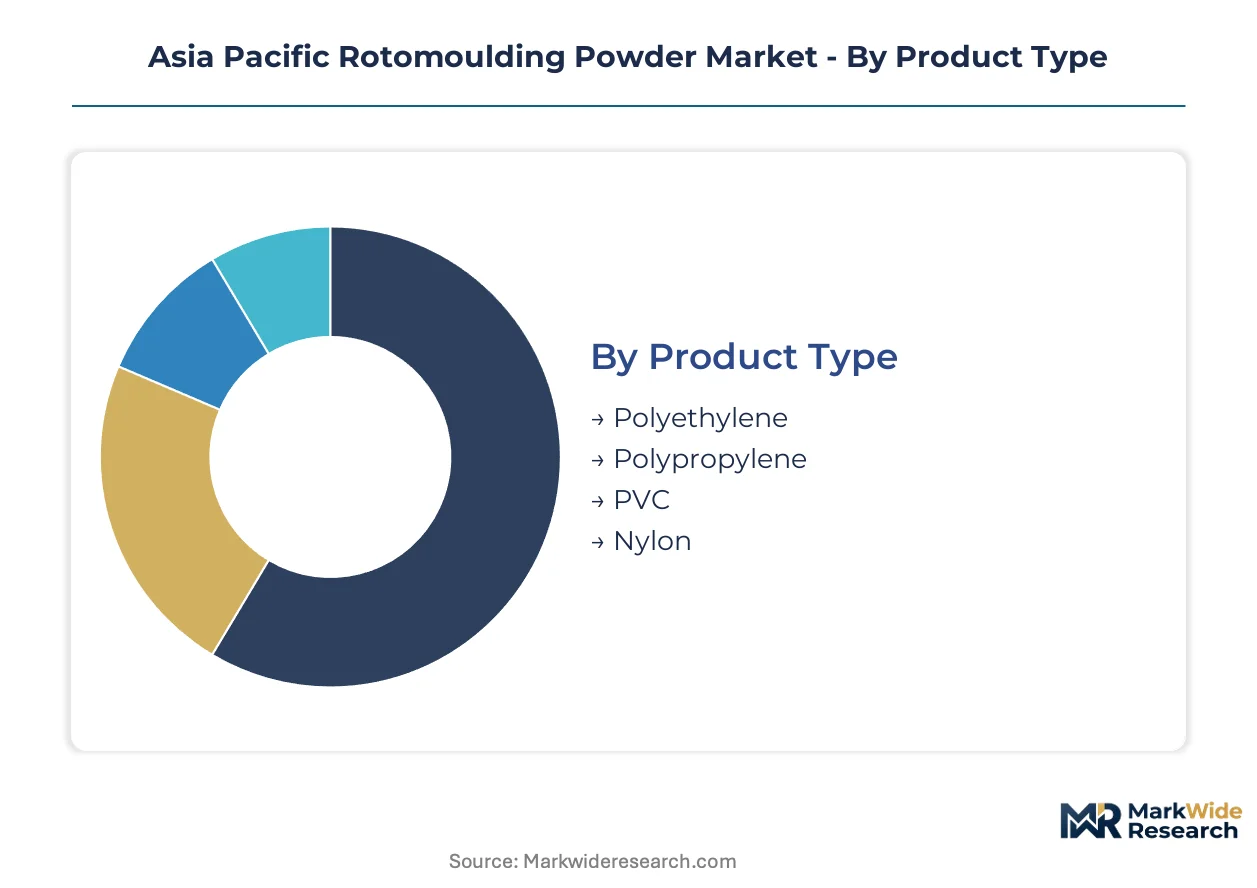
Rotomoulding powder procurement patterns diverge sharply across material grades, end-use specifications, and channel structures. Understanding these fault lines reveals where formulation premiums concentrate and which customer relationships command technical service investment.
Product Type:
Material chemistry determines melt-flow windows, cross-linking requirements, and barrier-property thresholds for hollow-part manufacture.
- Polyethylene:Linear low-density and cross-linked grades dominate regional volumes, with melt indices between 3 and 8 g/10min optimized for biaxial rotation at 250-400°C. India's western industrial corridor from Gujarat through Maharashtra sources these grades for agricultural tanks and automotive fuel systems where uniform wall thickness is non-negotiable.
- Polypropylene:Higher stiffness and chemical resistance position this resin for industrial chemical storage and battery housings in Thailand's automotive supplier parks. Molders specify PP where dimensional stability under thermal cycling outweighs polyethylene's processability advantages.
- PVC:Flame-retardant specifications in chemical-resistant industrial tanks sustain niche demand despite processing complexity and environmental scrutiny.
- Nylon:High-temperature resistance and mechanical strength serve specialized aerospace and industrial gear applications with limited regional compounding capacity.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
Application:
End-use performance requirements stratify formulation specifications across durability, sterilizability, and regulatory compliance dimensions.
- Containers:Water storage tanks and agricultural chemical vessels generate the largest value pool, with BIS certification for potable water contact and China's GB standards for chemical resistance elevating barrier-property specifications. Southeast Asian municipal infrastructure budgets are widening procurement volumes for rotomoulding-grade polyethylene in Thailand, Vietnam, and Indonesia.
- Medical Devices:Sterilizable grades for device housings and surgical equipment represent the steepest expansion trajectory as India's hospital supply chain scales. Gamma-stable polyethylene powders with metallocene-catalyzed melt strength are gaining specification share in the western industrial corridor.
- Automotive Parts:Fuel tanks and fluid reservoirs demand thin-wall capability and permeation resistance, with Japanese OEMs requiring direct formulation-to-mold technical collaboration.
- Toys:Recreational and playground equipment sustains steady demand for color-stable, UV-resistant formulations with lower regulatory burden than food-contact or medical grades.
Containers anchor current revenue. Medical devices are climbing the fastest.
End User:
Customer scale and technical sophistication determine whether procurement flows through distributor networks or direct compounding relationships.
- Manufacturers:Rotational molding operations with captive design capabilities source formulated powders with technical service support, particularly in India's automotive and agricultural tank clusters.
- OEMs:Original equipment manufacturers in automotive and medical supply chains specify resin grades directly, bypassing intermediaries to secure traceability documentation for CSRD-aligned European supplier mandates.
- Distributors:Traditional intermediaries face margin compression as regional compounders build direct-to-molder relationships across Thailand and Vietnam.
- Retailers:Limited role in powder procurement; primarily relevant for finished rotomoulded goods in consumer-facing segments.
Manufacturers command formulation partnerships. OEMs are consolidating specification authority.
Distribution Channel:
Channel economics are restructuring around technical service intensity and lot-size flexibility.
- Direct Sales:SCG Chemicals and integrated compounders leverage captive resin supply to serve molders directly, eliminating 15-20% distributor margins and embedding technical teams for process optimization.
- Wholesale:Bulk powder movements for standardized polyethylene grades continue through established distributors in markets where compounders lack localized presence.
- Online Retail:Limited penetration for rotomoulding powders given technical specification requirements and batch consistency needs; emerging for small-lot specialty grades.
- Specialty Stores:Niche channel serving hobbyist and small-scale molders with limited relevance to industrial volume flows.
Direct sales holds relationship density. Wholesale is ceding share to technical-service-embedded channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Map Ta Phut deepwater port complex underwrites Thailand's dominance in Asia Pacific rotomoulding powder supply, anchoring ethylene import and captive compounding capacity for Southeast Asian distribution.
China
Rotomoulding-grade polyethylene demand concentrates in Shandong and Jiangsu provinces where agricultural tank manufacturers serve the North China Plain. GB standards for plastic chemical resistance mandate enhanced ESCR testing for chemical storage applications. The Yangtze River Delta cluster around Shanghai hosts the region's largest concentration of certified testing laboratories.
India
Water tank procurement from Gujarat through Maharashtra drives polyethylene powder volumes as urban infrastructure budgets widen. BIS certification for potable water contact materials requires 12-18 month approval cycles, compressing launch timelines for new formulations. The western industrial corridor rotational molding clusters supply agricultural and automotive OEMs with direct technical service relationships.
Thailand
SCG Chemicals leverages its Map Ta Phut petrochemical base to sustain captive resin supply for rotomoulding customers across ASEAN. Board of Investment incentives for downstream plastic processing redirect capital toward localized compounding capacity. Bangkok-based technical service teams support molders directly, bypassing traditional distributor margins.
Vietnam
Northern industrial zones near Haiphong lack localized powder supply, creating white space for compounding investment as municipal water storage procurement scales. The country's national standards body is developing chemical resistance protocols aligned with regional benchmarks. Rotational molding technician scarcity for biaxial mold rotation processes slows cluster development around the Red River Delta.
Indonesia
Java-based water tank manufacturers are expanding procurement as urban infrastructure budgets widen for storage systems. The national industrial ministry's downstream chemical processing incentives attract regional compounder interest. Surabaya and Jakarta industrial corridors concentrate demand, though technical service coverage remains thinner than in Thailand or Malaysia.
Asia Pacific Rotomoulding Powder Market Vendor Landscape
On the supply side, the industry is consolidating around petrochemical-integrated compounders with captive resin access and technical service capabilities. Regional distributors face margin compression as direct-to-molder procurement models fragment traditional channel structures. Three archetypes dominate: integrated petrochemical producers with backward-integrated refinery outputs, specialized compounders with metallocene-grade formulation expertise, and regional distributors pivoting toward technical service partnerships. Competitive moves center on capacity expansion in Vietnam and Indonesia, plus certification investments for BIS and GB standard compliance.
Among Asia Pacific-based integrated producers, SCG Chemicals Co., Ltd and Reliance Industries Limited anchor the supply base through petrochemical-integrated positions. LyondellBasell occupies a position within the differentiated-grade tier, exemplifying the metallocene-catalyzed formulation specialist archetype for thin-wall applications. These three companies represent the dominant competitive vectors: Thai captive supply, Indian domestic capacity, and multinational specialty-grade technology.
| Leading Market Players |
|---|
| SCG Chemicals Co., Ltd |
| Reliance Industries Limited |
| LyondellBasell |
| Dalian Bona Biological Technology Co., Ltd |
| Asahi Kasei |
| BASF SE |
| Dow Inc. |
| Formosa Plastics Corporation |
| SABIC |
| Others |
Supply Flow & Price Mechanics
The Map Ta Phut deepwater port complex channels ethylene import costs through Thai petrochemical bases, concentrating supply-side pricing power among integrated compounders while forcing non-integrated molders to absorb distributor markups or absorb freight premiums from distant powder sources.
Pricing Analysis
Volume-discount tiering structures separate captive-resin compounders from import-dependent molders across Southeast Asia. Pricing stratifies across BIS-certified potable water grades, metallocene-enhanced thin-wall formulations, and standard linear low-density polyethylene for agricultural tanks. Cost compression in standard-grade polyethylene is intensifying because Vietnamese and Indonesian molders are consolidating procurement volumes to bypass distributor margins. Small-scale rotational molding operations in northern Vietnam exhibit the highest price sensitivity, while Japanese automotive OEMs purchasing fuel tank specifications demonstrate minimal elasticity given technical collaboration requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with SCG Chemicals' Map Ta Phut operations, Reliance Industries' Jamnagar refinery-integrated compounding, and LyondellBasell's differentiated-grade formulation facilities. Geographic supply concentration centers on Thailand, India, and China, with Vietnam and Indonesia dependent on cross-border powder movements. Raw material dependencies draw from naphtha-cracking ethylene, metallocene catalyst systems, and cross-linking peroxide additives. Single-source vulnerability from Thai petrochemical bases creates structural risk for ASEAN molders lacking alternative qualified suppliers. Distribution runs through direct technical-service relationships for automotive and medical OEMs, with wholesale channels persisting for standardized agricultural tank grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific rotomoulding powder market functions as a service-attach opportunity where formulation-to-mold technical collaboration and BIS certification support generate recurring revenue streams expanding faster than commodity powder sales.
For Market Incumbents: Harden direct-to-molder relationships by embedding technical service teams in Vietnam's northern industrial zones before regional compounders establish localized compounding capacity. Defend against metallocene-grade specialists by securing backward integration into catalyst supply partnerships that lock in formulation differentiation. Prioritize BIS certification investment for potable water contact grades to compress competitor launch timelines. For New Entrants and Emerging Players: Northern Vietnam's Haiphong industrial corridor represents the most penetrable entry point, lacking localized powder supply while municipal water storage procurement scales rapidly. India's sterilizable medical-grade segment offers secondary white-space as hospital supply chain expansion outpaces domestic compounding capacity. A go-to-market angle anchored to CSRD-aligned traceability documentation captures premium positioning among European OEM supplier mandates. For Investors and Strategic Acquirers: Specialized compounders with metallocene-catalyzed formulation expertise and existing BIS or GB standard certifications present the most attractive acquisition archetype for medium-term consolidation plays. Long-term viability hinges on regulatory compliance capabilities rather than commodity scale. Monitor BIS approval timeline compression and Vietnam's national standards body chemical resistance protocol development as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive resin access eliminates distributor margins for Thai and Indian compounders serving ASEAN molders. |
| Metallocene-Grade Capacity Expansion | Thin-wall tank specifications for automotive fuel systems command formulation premiums from Japanese OEMs. |
| BIS Certification Fast-Track Investment | Compressed 12-18 month potable water contact approval cycles accelerate product launch timelines for new entrants. |
| Direct Technical Service Deployment | Embedded formulation support in Vietnam bypasses traditional distributor channels capturing 15-20% margins. |
| CSRD-Aligned Traceability Systems | ESG disclosure-ready documentation secures premium supplier status with European OEM procurement mandates. |
Methodological Framework
Cross-validation between primary interviews with rotational molding plant managers, polyethylene procurement leads at automotive OEMs, BIS certification laboratory directors, and technical R&D directors at regional compounders anchors the qualitative findings. Secondary validation draws from customs and trade data tracking ethylene and formulated powder movements, SEC 10-K filings of petrochemical-integrated producers, ACC and Cefic regional chemical industry reports, and BIS certification registry databases. Bottom-up demand modeling from molder procurement patterns and top-down supply assessment from refinery-integrated capacity triangulate volume estimates.
Calibration against historical polyethylene price volatility and regional infrastructure budget cycles ensures forecast robustness across the analysis window. Segmentation dimensions include material chemistry grade, end-use application, regulatory certification tier, and distribution channel structure. CAGRs derive from elasticity-adjusted demand projections incorporating melt-index specification shifts and thin-wall adoption trajectories. Industry-specific inputs capture PLI scheme capital flow redirection and CSRD-aligned supplier mandate penetration rates.
Practitioners should monitor ethylene-naphtha spread compression, BIS certification queue lengths, and Vietnam national standards body protocol finalization for early signals of forecast revision. Quarterly review of regional infrastructure budget allocations, metallocene catalyst patent expirations, and European OEM ESG disclosure enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Heat Transfer Fluids Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Global Antifreeze Market