
 Global Industrial Air Chiller Market | 2026-2036
Global Industrial Air Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Air Chiller Market Intelligence
The shift toward equipment-as-a-service and long-term leasing models is reconfiguring competitive positioning for industrial air chiller manufacturers. This asset-light approach allows end-users to avoid large capital outlays. Johnson Controls International plc leverages its extensive service network to support these models. Daikin Industries, Ltd. differentiates through its in-house refrigerant and compressor technology, while Ingersoll Rand Inc. specializes in highly reliable systems for critical industrial processes.
An industrial air chiller is a system that removes heat from a liquid via a vapor-compression or absorption refrigeration cycle before dissipating it into the air. These units are engineered for continuous operation in demanding industrial environments. Scroll and screw compressor types are seeing increased use in mid-capacity applications like food processing. Centrifugal chillers, however, continue to dominate large-scale deployments in power generation and chemical manufacturing facilities due to their superior efficiency at high loads.
Regulatory frameworks are a primary influence on product design and market access. The US EPA's refrigerant management programs and the EU's F-Gas Regulation both mandate a phase-down of high global warming potential substances. Concurrently, ISO 50001 standards for energy management push for more efficient chiller designs. Navigating the evolving landscape of refrigerant availability and energy efficiency standards is a critical strategic challenge for all manufacturers.
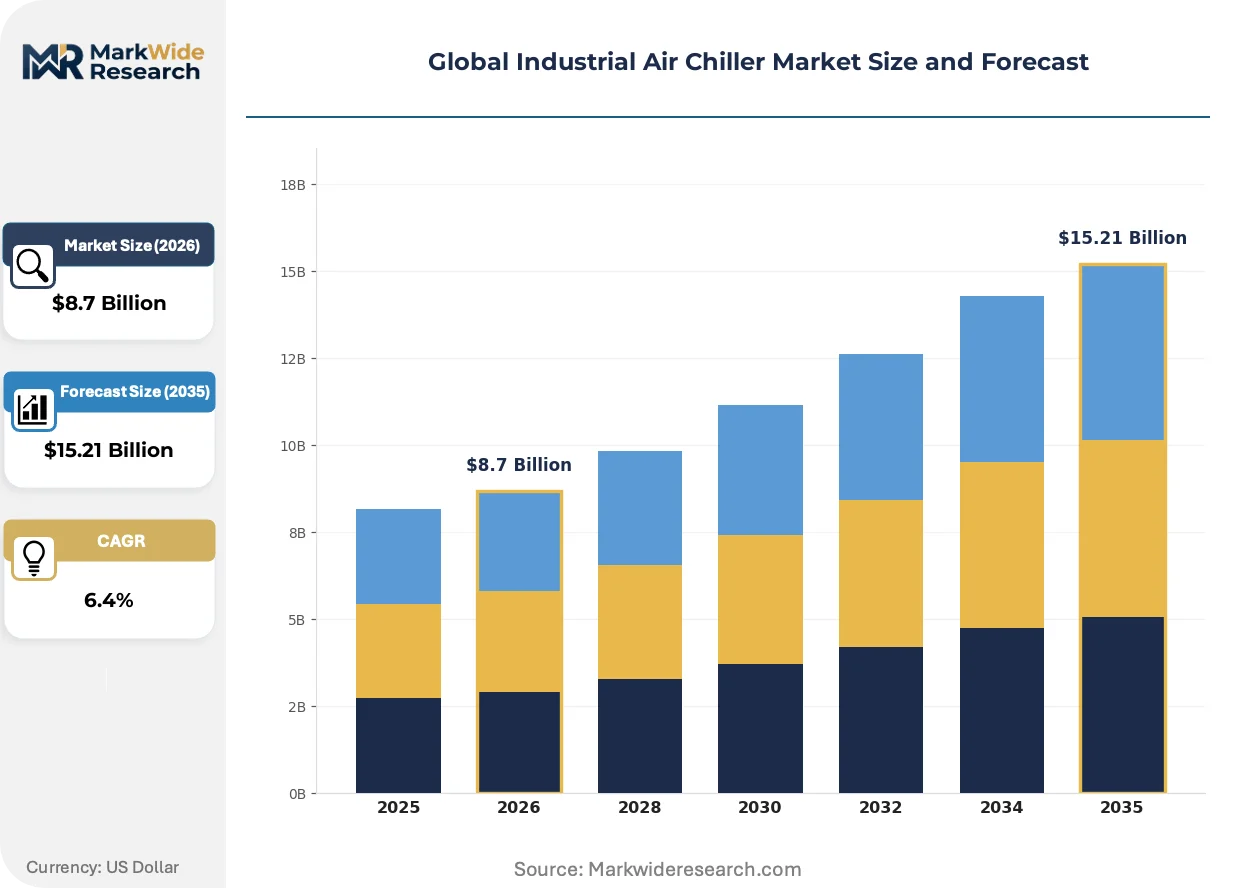
Market Dynamics
The market's structure is defined by the need to balance escalating energy efficiency mandates, such as ISO 50001, with the rising demand for high-capacity cooling from heat-intensive sectors like data centers and advanced manufacturing.
Growth Catalysts
- Data Center Expansion:The proliferation of hyperscale data centers requires precise, high-capacity air chillers to maintain stable operating temperatures for sensitive electronic hardware, driving significant volume demand.
- F-Gas Regulation:The European Union's F-Gas Regulation compels a transition to chillers using low global warming potential refrigerants, accelerating the product replacement cycle across the continent.
- Compressor Technology:Advances in scroll and screw compressors are improving the efficiency and cost-effectiveness of mid-capacity systems, expanding their application in food processing and plastics manufacturing.
Market Restraints
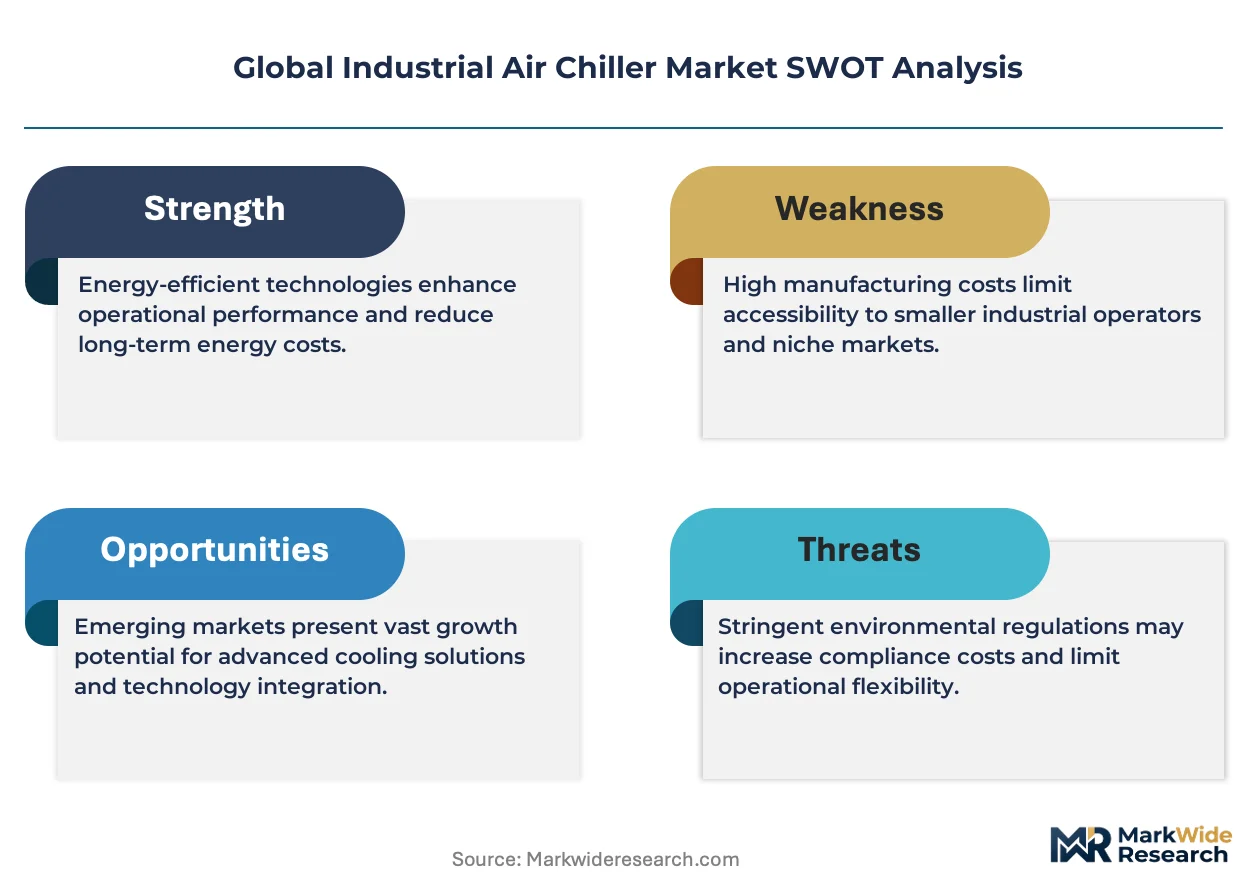
- High Capital Outlay:The substantial initial investment required for large-scale centrifugal chiller systems remains a significant barrier for new projects or facility upgrades in capital-intensive industries.
- Refrigerant Phase-Down:The mandated global phase-down of HFC refrigerants creates supply chain uncertainty and increases compliance costs for both manufacturers and end-users during retrofits.
- Performance Trade-Offs:Specific chiller technologies exhibit reduced efficiency under partial load conditions or in high ambient temperature environments, limiting their suitability for certain climates and applications.
Strategic Opportunities
- Battery Manufacturing:The rapid expansion of electric vehicle battery gigafactories presents a new, large-scale opportunity, as these facilities require stringent temperature and humidity control during production.
- Service Model Innovation:Developing comprehensive equipment-as-a-service offerings allows manufacturers to capture recurring revenue streams while lowering the adoption barrier for end-users.
- Emerging Industrial Hubs:Industrialization in Southeast Asian nations like Vietnam and Indonesia creates greenfield demand for industrial chillers in manufacturing, food processing, and chemical plants.
Industry Challenges
- Specialized Technician Shortage:A skills gap exists for technicians qualified to service and maintain modern chillers that use new low-GWP refrigerants and integrated digital control systems.
- System Integration Complexity:Integrating new, highly efficient chiller units with older, legacy building automation systems and industrial process controls presents significant technical and software compatibility hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Air Chiller Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Screw, Centrifugal, Scroll, Absorption Technology: Magnetic Bearing, Air-Cooled, Water-Cooled, Evaporative, VFD Application: Power Generation, Chemicals Manufacturing, Food Processing, Data Centers, Textile Production End User: Manufacturing Plants, Refineries, Pharmaceutical Facilities, Semiconductor Plants, HVAC Contractors |
| Companies Covered | Carrier Corporation, Daikin Industries, Ltd., Johnson Controls International plc, Mitsubishi Electric Corporation, Ingersoll Rand Inc., Trane Technologies plc, Midea Group, Thermax Inc., Blue Star Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Air Chiller Market Strategic Shifts & Innovations
A convergence of digital intelligence with mechanical engineering is defining the next generation of industrial air chillers. This integration aims to transform operational efficiency, maintenance protocols, and compliance with increasingly stringent environmental standards.
Digital twin technology creates a real-time, data-driven model of a chiller's operational state and thermal performance. It is being adopted by operators of critical facilities like data centers and pharmaceutical plants to predict maintenance needs and optimize energy use. This technology is virtualizing the traditional break-fix maintenance cycle, replacing it with predictive, condition-based servicing.
Regulatory pressure from the US EPA, via the AIM Act, mandates a steep phasedown of hydrofluorocarbons. This forces manufacturers to accelerate the redesign of chiller systems for alternative, lower-GWP refrigerants like HFOs. The chemical processing sector, a user of large-capacity systems, is particularly affected due to the scale of refrigerant charge and redesign costs.
End-users are increasingly adopting equipment-as-a-service and long-term leasing models, shifting the financial burden from capital to operational expenditure. This change disrupts the traditional transactional sale, favoring suppliers who can guarantee uptime and efficiency metrics through comprehensive service contracts. This model is gaining traction fastest in North America’s food and beverage sector.
Global Industrial Air Chiller Market Segmentation
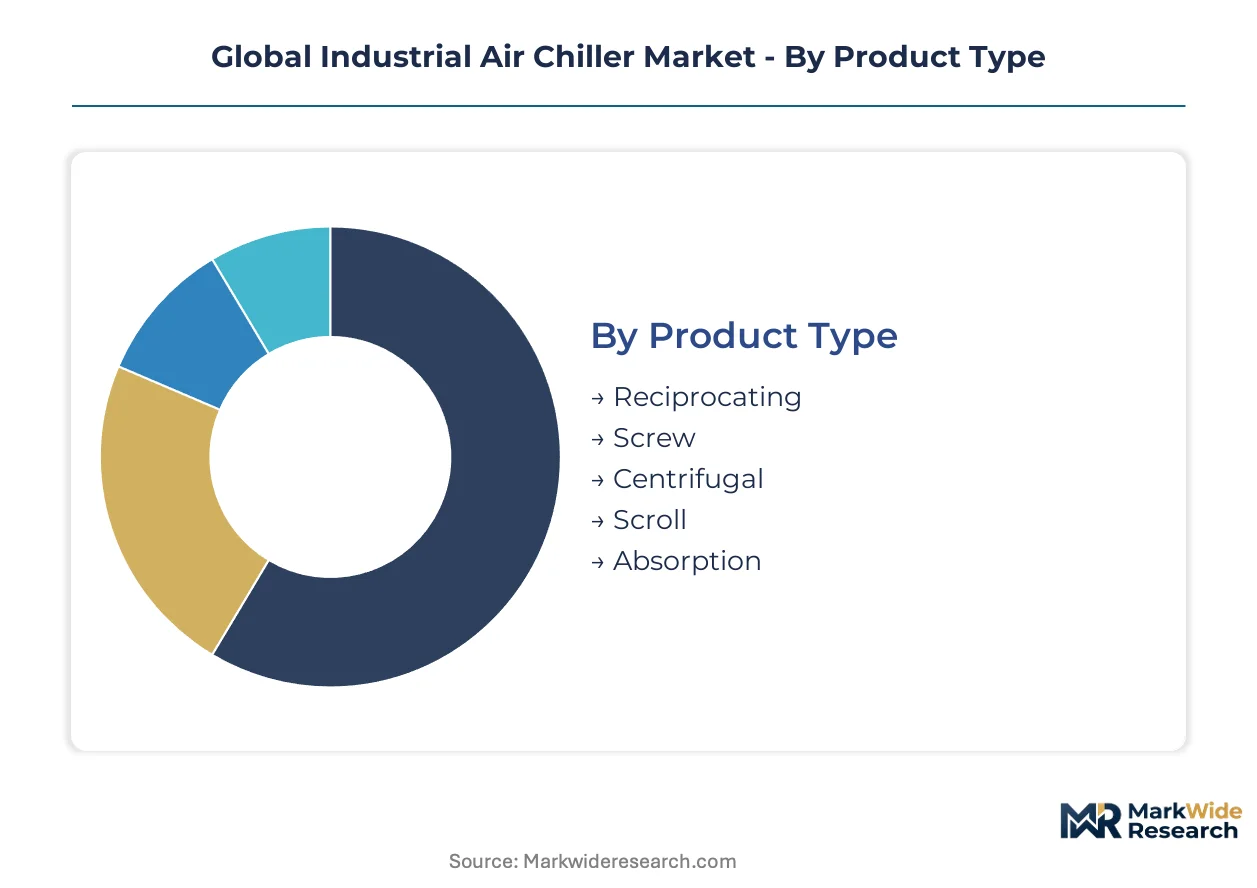
The industrial air chiller market's intricate structure reflects diverse cooling requirements across global industries. Understanding these segments is critical for manufacturers to align product development with specific end-user demands and regulatory pressures. This granular analysis reveals where technological innovation and investment are most impactful.
Product Type:
The maturity spectrum of chiller product types ranges from long-established designs to newer, more efficient iterations. Each type offers distinct advantages for specific operational scales and environmental conditions, influencing purchasing decisions.
- Centrifugal:These chillers utilize centrifugal compressors to generate high-capacity cooling suitable for very large-scale industrial applications. Demand concentrates in power generation facilities and chemical manufacturing clusters due to their superior efficiency at high loads.
- Screw:Screw chillers employ positive displacement rotary screw compressors, offering robust performance in mid-to-large capacity ranges. Advanced manufacturing hubs in China drive demand for these systems, benefiting from their reliability and energy efficiency improvements.
- Reciprocating:Reciprocating chillers use piston-driven compressors, serving smaller to medium-sized cooling needs with proven technology. Food processing plants in North America frequently deploy these units for their consistent performance.
- Scroll:Scroll chillers feature two interleaved spiral scrolls for compression, providing quiet and efficient operation for mid-capacity applications. Plastics manufacturing facilities globally increasingly adopt these compact units.
- Absorption:Absorption chillers use a heat source, like waste heat, to drive the refrigeration cycle, offering an environmentally friendly option. Industrial sites with abundant waste heat, such as refineries, seek these chillers for sustainability benefits.
Centrifugal chillers handle the majority of throughput; Screw chillers are the fastest mover on share.
Technology:
The application scope for chiller technologies varies widely, from enhancing energy efficiency to enabling precise environmental control in critical processes. Innovation in these technologies directly impacts operational costs and system reliability for industrial users.
- Water-Cooled:These systems use water circulated through a cooling tower to dissipate heat, providing high efficiency and stable performance for large-scale operations. Data centers in Europe prioritize water-cooled chillers for their superior thermal management capabilities.
- VFD (Variable Frequency Drive):VFD technology allows chiller compressors to operate at variable speeds, precisely matching cooling load demands and significantly reducing energy consumption. Manufacturing plants across Southeast Asia adopt VFD-equipped chillers to meet stringent energy efficiency standards.
- Magnetic Bearing:Magnetic bearing chillers eliminate friction by levitating the compressor shaft, resulting in extremely high efficiency, reduced maintenance, and quieter operation. Pharmaceutical facilities in the US deploy these for their critical process cooling needs.
- Air-Cooled:Air-cooled chillers reject heat directly to the ambient air, simplifying installation by eliminating the need for a cooling tower. Food processing operations in regions with water scarcity often select these systems.
- Evaporative:Evaporative chillers combine air and water cooling, offering better efficiency than air-cooled units in dry climates. Industrial facilities in arid regions, like the Middle East, utilize these for optimized performance.
Efficiency gains are most pronounced in VFD technology; Magnetic Bearing technology is rapidly expanding its footprint.
Application:
Demand volume for industrial air chillers is heavily influenced by the specific cooling needs of diverse industrial applications. Each sector presents unique challenges and opportunities for chiller manufacturers, driving specialized product development.
- Data Centers:Hyperscale data centers require continuous, high-capacity cooling for sensitive electronic hardware, ensuring operational stability and preventing thermal shutdowns. The expansion of cloud infrastructure globally drives significant demand in this sector.
- Power Generation:Large-scale power plants, including nuclear and thermal facilities, utilize industrial chillers for cooling critical equipment and processes. China's energy infrastructure projects represent a substantial demand pool for these robust systems.
- Food Processing:The food and beverage industry relies on chillers for precise temperature control during processing, storage, and packaging to maintain product quality and safety. North American food manufacturers prioritize chillers meeting strict hygiene standards.
- Chemicals Manufacturing:Chemical production processes often generate significant heat, requiring industrial chillers for reaction cooling and condensation. European chemical clusters demand chillers compatible with low global warming potential refrigerants.
- Textile Production:Textile manufacturing uses chillers to control temperature and humidity in dyeing, weaving, and spinning processes, impacting product quality and machine efficiency. Factories in India utilize chillers for consistent climate control.
High-volume cooling needs define Data Centers; Food Processing presents the steepest expansion trajectory.
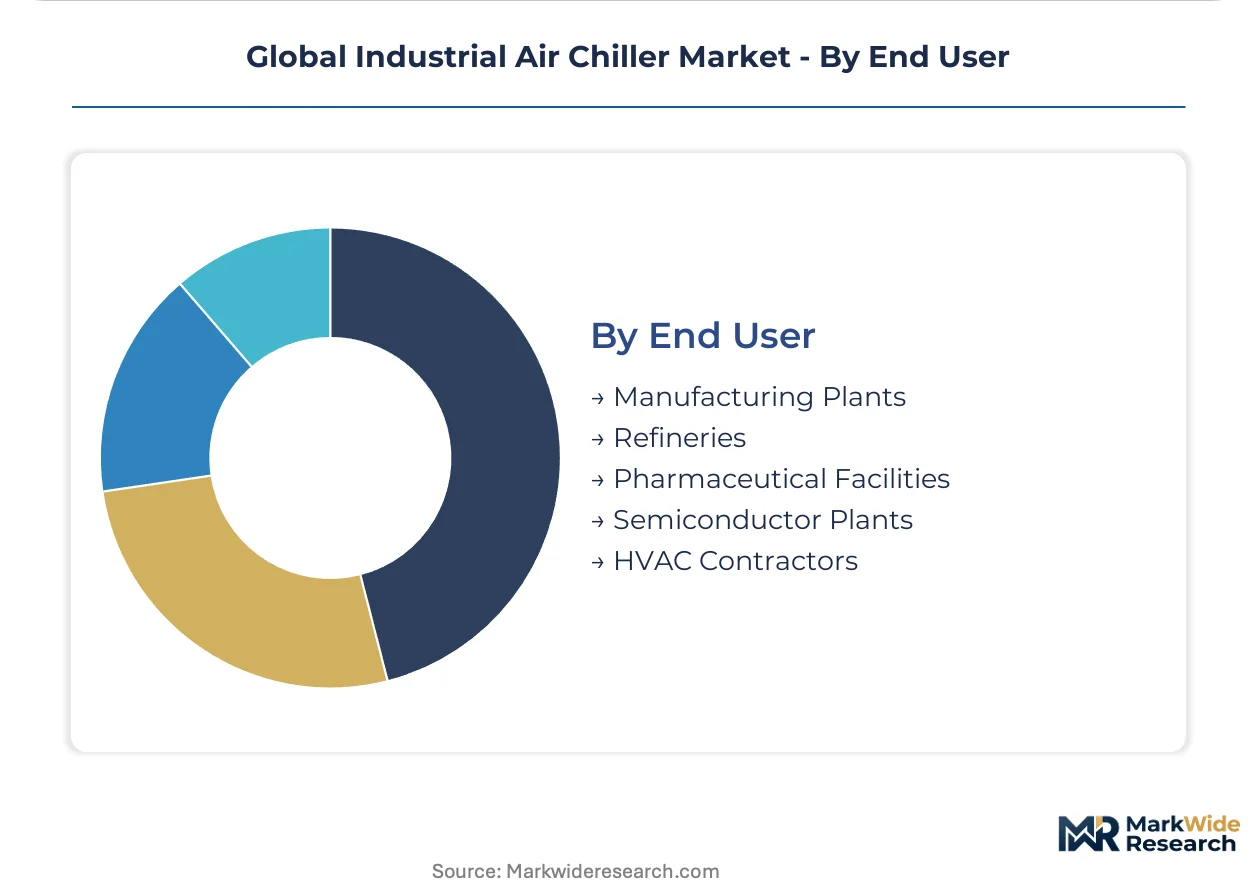
End User:
The customer type significantly impacts the selection and deployment of industrial air chillers, reflecting varying priorities such as operational continuity, regulatory compliance, and energy efficiency. Each end-user group has distinct purchasing criteria.
- Manufacturing Plants:General manufacturing facilities across various sectors use chillers for process cooling, machine temperature control, and comfort cooling. Vietnam's expanding manufacturing base represents a growing customer segment.
- Pharmaceutical Facilities:These facilities require highly precise and reliable temperature control for drug manufacturing, storage, and cleanroom environments, often under stringent regulatory oversight. Global pharmaceutical companies prioritize validated chiller solutions.
- Refineries:Oil and gas refineries utilize robust chillers for cooling process streams, gas liquefaction, and HVAC systems in hazardous environments. Middle Eastern refineries demand chillers built for extreme ambient temperatures.
- Semiconductor Plants:Semiconductor fabrication requires ultra-precise temperature and humidity control to prevent contamination and ensure product quality. South Korean semiconductor manufacturers invest in advanced chiller systems.
- HVAC Contractors:These professionals purchase chillers for installation in commercial and industrial buildings, often serving as intermediaries for various end-use applications. US HVAC contractors seek versatile and energy-efficient models.
Operational continuity is paramount for Pharmaceutical Facilities; Semiconductor Plants are climbing fastest in market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global industrial air chiller market exhibits a varied export-import balance, with some regions acting as net exporters of advanced cooling solutions. This dynamic influences local manufacturing capabilities and technology adoption. Regulatory frameworks also shape regional market characteristics.
China
China's advanced manufacturing clusters drive demand for high-capacity screw chillers, particularly for semiconductor fabrication and EV battery production. The nation's dual carbon goals, like those from the MEE, push for energy-efficient designs and low-GWP refrigerants. Industrial parks in the Yangtze River Delta actively deploy VFD-equipped centrifugal chillers.
United States
Data center expansion across the United States creates significant demand for water-cooled and magnetic bearing chillers, ensuring precise temperature control for sensitive electronics. The US EPA's AIM Act mandates a phasedown of HFC refrigerants, accelerating product redesigns. Pharmaceutical facilities in the Northeast Corridor prioritize validated chiller solutions for critical process cooling.
Germany
Germany's chemical manufacturing and automotive sectors require robust industrial chillers for process cooling and climate control within production facilities. The EU's F-Gas Regulation compels a transition to low global warming potential refrigerants, impacting chiller design. Bavarian industrial hubs widely implement absorption chillers, leveraging waste heat from local industrial processes.
Vietnam
Vietnam's expanding manufacturing base, particularly in electronics and textiles, fuels greenfield demand for industrial air chillers across new factory builds. Government initiatives promoting foreign direct investment attract manufacturers requiring modern cooling infrastructure. Industrial zones around Ho Chi Minh City increasingly adopt VFD-equipped chillers.
United Arab Emirates
The United Arab Emirates' energy sector, including oil and gas refineries, necessitates robust chillers built for extreme ambient temperatures and continuous operation. Regulations from the Ministry of Energy and Infrastructure promote energy efficiency in large industrial installations. Industrial complexes in Jebel Ali Free Zone utilize evaporative chillers for optimized performance.
Global Industrial Air Chiller Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical technologies like compressors and refrigerants. The market exhibits a tiered structure, with global conglomerates competing against regional specialists and niche technology providers. Strategic archetypes include full-service providers offering comprehensive lifecycle support and technology innovators focusing on efficiency gains. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Among established players, Daikin Industries, Ltd. exemplifies a manufacturer leveraging in-house refrigerant and compressor technology for product differentiation, spanning various chiller types. Johnson Controls International plc, a US-based company, occupies a position as a full-service provider, utilizing its extensive service network to support equipment-as-a-service models for diverse industrial clients. Ingersoll Rand Inc. represents a specialist in highly reliable systems for critical industrial processes, anchoring solutions for demanding applications such as power generation and chemical manufacturing.
| Leading Market Players |
|---|
| Carrier Corporation |
| Daikin Industries, Ltd. |
| Johnson Controls International plc |
| Mitsubishi Electric Corporation |
| Ingersoll Rand Inc. |
| Trane Technologies plc |
| Midea Group |
| Thermax Inc. |
| Blue Star Limited |
| Others |
Cost & Logistics Intelligence
Rapid industrial expansion in Southeast Asia drives new capacity requirements, influencing supplier investment decisions and shaping long-term pricing agreements for industrial air chillers. This dynamic creates a complex interplay between regional demand spikes and the global availability of critical components.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing, especially for large-scale centrifugal chiller systems. Price differentiation stems from the chiller's energy efficiency ratings and the comprehensiveness of after-sales service contracts. Pricing pressure stems from the increasing availability of mid-capacity scroll and screw chillers, offering cost-effective alternatives. End-users seeking to avoid large capital outlays exhibit the highest price sensitivity, while pharmaceutical facilities prioritize validated solutions over initial cost.
Supply Chain Analysis
Upstream refrigerant and compressor manufacturing forms the backbone of the industrial air chiller supply chain. Supply concentration for advanced compressors centers in Japan and Germany, while low-GWP refrigerant production is expanding in China. The mandated global phase-down of HFC refrigerants creates supply chain uncertainty, posing a structural risk for manufacturers. Distribution runs through a dual model, combining direct sales for large industrial projects with indirect channels via HVAC contractors for commercial and mid-sized industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection, driven by the integration of digital twin technology with chiller control systems to create a unified operational ecosystem.
For Market Incumbents: Harden core service capabilities by expanding specialized technician training programs for low-GWP refrigerants and integrated digital controls. Invest in modular chiller designs to reduce system integration complexity, a key threat to new project deployments. Deepen vertical integration into advanced compressor and refrigerant technologies to mitigate supply chain uncertainties. Focus R&D on next-generation, high-efficiency components.
For New Entrants and Emerging Players: Build out comprehensive equipment-as-a-service offerings that bundle digital twin capabilities with guaranteed uptime metrics. Target the rapidly expanding battery manufacturing sector, which has greenfield demand for precise temperature control. Southeast Asian industrial hubs like Vietnam present the most penetrable geography for new, energy-efficient mid-capacity chiller solutions. A go-to-market angle focusing on total cost of ownership reduction through predictive maintenance offers strong differentiation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers leveraging extensive service networks and digital integration. Long-term viability hinges on companies that can navigate the transition to low-GWP refrigerants while delivering superior energy efficiency. Acquisition targets should include technology innovators specializing in magnetic bearing or VFD chillers, or regional service providers with strong digital integration capabilities. The adoption rate of outcome-based service contracts is a specific signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Model Innovation | Capturing recurring revenue streams while lowering adoption barriers for end-users. |
| Low-GWP Refrigerant R&D | Ensuring regulatory compliance and future-proofing product lines against phase-downs. |
| Digital Twin Integration | Optimizing operational efficiency and enabling predictive maintenance for critical facilities. |
| Geographic Manufacturing Footprint Expansion | Addressing greenfield demand in emerging industrial hubs like Southeast Asia. |
| Specialized Technician Training Programs | Bridging the skills gap for modern chiller systems using new refrigerants and controls. |
Research Approach
A standing panel of plant managers, HVAC contractors, R&D engineers, and procurement leads provided ongoing calibration for primary insights into market dynamics. These direct consultations were rigorously cross-referenced with secondary data sources, including US EPA reports, EU F-Gas Regulation documents, and ISO standards. This approach facilitated a robust bottom-up and top-down triangulation of market data.
Scenario-bracketing framed the analytical approach across the modeling period, accounting for various market trajectories. The forecast framework modeled segmentation dimensions including product type, technology, application, end user, and regional regulatory impact. Compound annual growth rates were derived from historical performance and projected growth drivers, such as data center buildout rates and refrigerant phase-down schedules.
Sensitivities concentrate around regulatory shifts in refrigerant policy and volatility in raw material prices. Forecasts reflect assumptions documented through extensive primary and secondary research. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Kitchen Hood System Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Hydro Chillers Market