
 US HVAC Systems Market | 2026-2036
US HVAC Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US HVAC Systems Market Intelligence
Data center cooling demand is realigning the US HVAC Systems Market's end-use vertical mix, pulling capacity toward high-precision institutional installations. Carrier leverages its chiller technology leadership to anchor positions in hyperscale server farm contracts. Trane Technologies competes through integrated building automation platforms that extend control over lifecycle energy consumption. Daikin Industries Ltd. differentiates via ductless and variable refrigerant flow systems designed for modular data hall expansion.
US HVAC systems encompass heating, ventilation, air conditioning, and refrigeration equipment engineered to maintain indoor thermal comfort and air quality across commercial, residential, and industrial environments, typically operating through vapor-compression cycles with refrigerants subject to evolving phase-down protocols. These systems serve the primary purpose of climate control, energy management, and regulatory compliance in enclosed built spaces. The product type dimension shows air conditioning commanding the largest installed base while smart HVAC technology captures the fastest upgrade cycle as building operators prioritize connected diagnostics and predictive maintenance. The installation type dimension reveals replacement and retrofit activity outpacing new construction in mature urban corridors where aging equipment faces efficiency mandates.
The EPA enforces hydrofluorocarbon phasedown timelines under the AIM Act, directly constraining refrigerant choices and accelerating equipment turnover cycles. The Department of Energy maintains minimum efficiency standards through SEER and EER metrics that manufacturers must satisfy for market access. State-level codes, particularly California's Title 24 and New York's Clean Heat standards, layer additional performance requirements that shape regional product configurations. Stakeholders must monitor refrigerant transition readiness, efficiency tier positioning, and state incentive program alignment to capture replacement cycle volume.
Market Dynamics
The US HVAC Systems Market is reconfiguring around refrigerant chemistry transitions mandated by the EPA's AIM Act, forcing equipment replacement cycles and supplier retooling commitments.
Growth Catalysts
- AIM Act HFC Phasedown:The EPA's staged reduction in hydrofluorocarbon allowances accelerates equipment turnover as contractors and building operators face supply constraints on legacy refrigerants.
- Data Center Thermal Loads:Hyperscale server farm construction across Texas, Arizona, and Virginia is pulling chiller and precision cooling capacity toward institutional-grade specifications.
- Sun Belt Construction Velocity:Cooling-dominated climates in Florida, Georgia, and Nevada sustain residential and commercial equipment pull through sustained housing starts and commercial development.
Market Restraints
- Copper and Aluminum Input Volatility:Raw material price swings for heat exchanger metals compress OEM margins and complicate long-term contract pricing.
- Refrigerant Supply Concentration:Domestic production of next-generation low-GWP alternatives remains limited, creating dependency on import pathways for R-454B and R-32.
- SEER 2 Compliance Friction:The Department of Energy's revised testing procedures raise minimum efficiency floors, disqualifying legacy product lines and requiring R&D recertification.
Strategic Opportunities
- Heat Pump Electrification Mandates:New York's Clean Heat standard and similar state-level building decarbonization rules create subsidized replacement demand in the Northeast corridor.
- Smart Diagnostics Convergence:Integration of IoT sensors with predictive maintenance software enables service revenue models beyond equipment sales.
- Modular Data Hall Expansion:Variable refrigerant flow and ductless systems designed for rapid deployment capture share in edge computing facility buildouts.
Industry Challenges
- EPA Section 608 Technician Certification:The credentialing pipeline for refrigerant handling lags equipment transition timelines, constraining installation capacity.
- Legacy Control System Integration:BACnet and proprietary building automation protocols create interoperability friction when upgrading to connected HVAC platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US HVAC Systems Market |
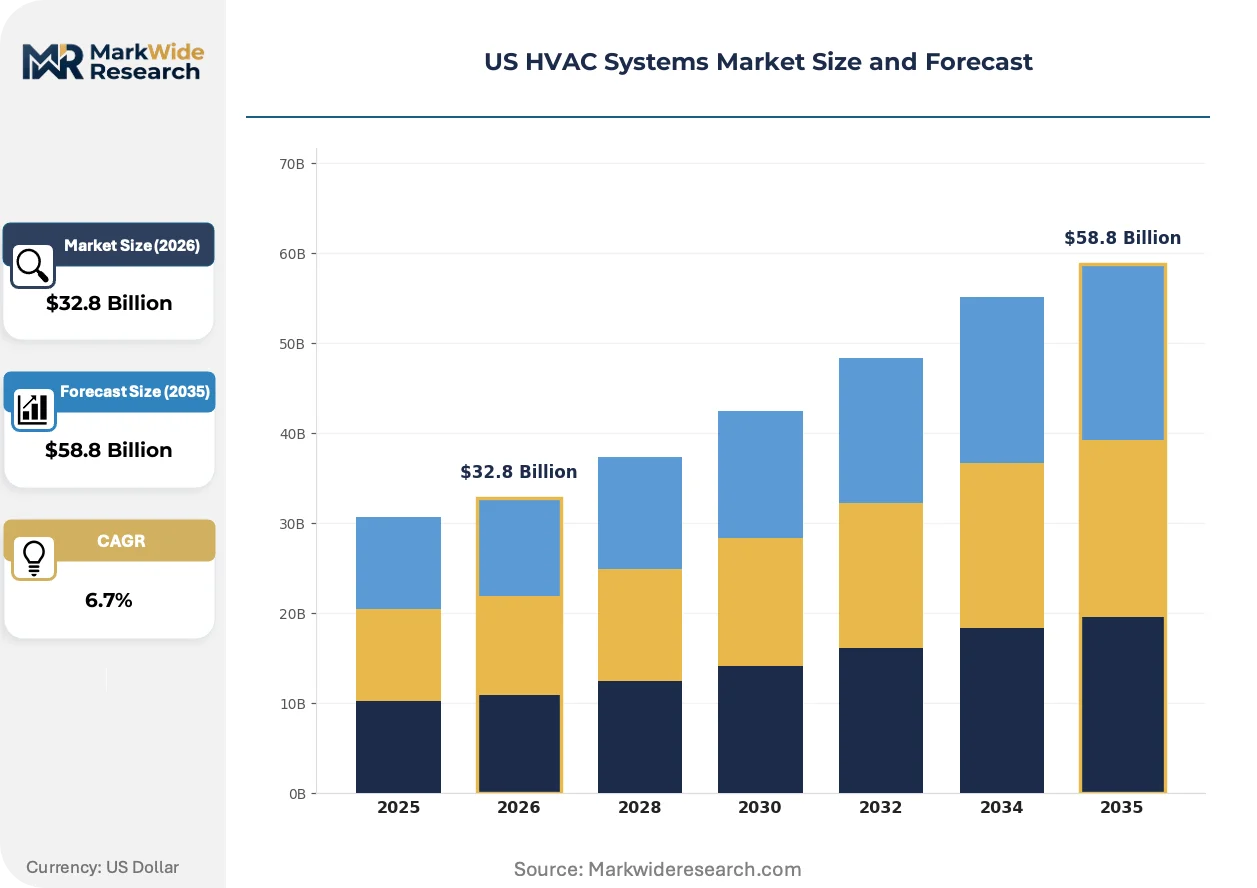
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating, Ventilation, Air Conditioning, Refrigeration End User: Residential, Commercial, Industrial, Institutional Technology: Smart HVAC, Geothermal, Ductless, Centralized Installation Type: New Construction, Retrofit, Replacement, Upgrading |
| Companies Covered | Carrier, Lennox International Inc., Trane Technologies, Johnson Controls, Daikin Industries Ltd., Rheem Manufacturing Company, Nortek Global HVAC, AAON Inc., Ingersoll Rand, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US HVAC Systems Market Strategic Shifts & Innovations
Refrigerant chemistry, building connectivity, and procurement logic are simultaneously resetting technical and commercial baselines for equipment specification and lifecycle management.
Variable refrigerant flow technology is unifying heating and cooling distribution through a single refrigerant circuit, eliminating separate ductwork for thermal zones. Multi-family developers in California and Texas are specifying VRF for mid-rise construction to reduce mechanical footprint and enable individual unit metering. The technology is unifying equipment procurement decisions across residential and light-commercial segments previously served by split-system silos.
The EPA's Technology Transitions Program under the AIM Act restricts high-GWP refrigerants in specific end-use categories on fixed phase-down schedules. Chiller manufacturers must reformulate equipment lines for R-1234ze or R-515B ahead of 2025-2028 deadlines. Institutional buyers in healthcare and education verticals face compressed capital planning cycles to replace R-134a and R-410A systems before supply constraints tighten.
Building operators are unbundling equipment purchase from long-term service performance, shifting toward energy-as-a-service contracts where HVAC outcomes are guaranteed rather than specified. Third-party energy service companies are capturing decision authority previously held by mechanical contractors in the commercial real estate sector. This model concentrates most visibly in Class A office retrofits in Manhattan and Chicago where landlords face carbon emission disclosure mandates.
US HVAC Systems Market Segmentation
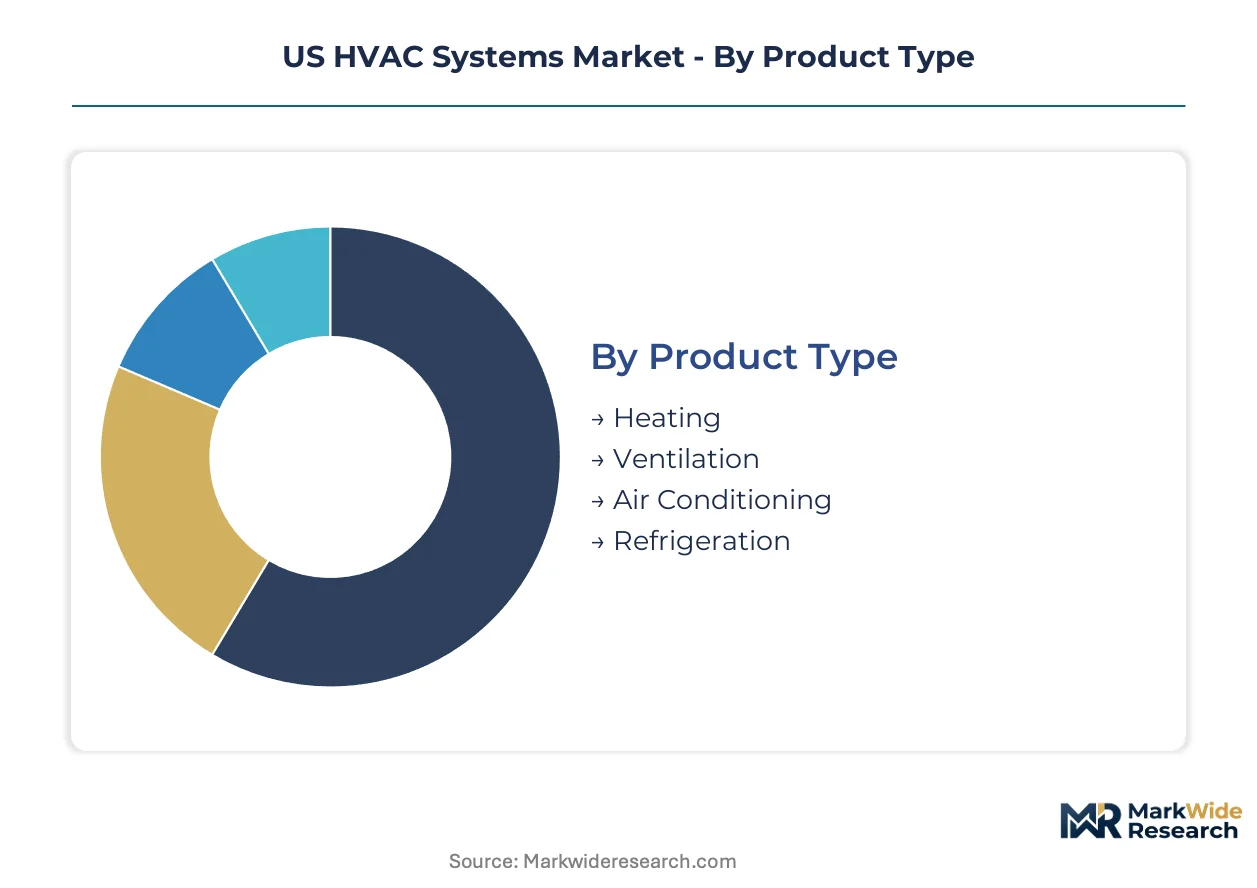
Equipment upgrade cycles and refrigerant transitions are fragmenting demand across distinct technical and customer profiles. Procurement patterns diverge sharply between replacement-driven urban corridors and new construction in Sun Belt expansion zones.
Product Type:
Replacement urgency varies by equipment category as efficiency mandates and refrigerant phase-downs force staggered capital commitments.
- Air Conditioning:Split-system and packaged units dominate the installed base across cooling-dominated climates. Demand concentrates in Texas, Florida, and Arizona residential subdivisions where SEER 2 compliance deadlines accelerate turnover of pre-2023 equipment.
- Heating:Furnaces and heat pumps face divergent regulatory pressure as states like New York mandate electrification through Clean Heat standards. Northeast corridor utilities are subsidizing cold-climate heat pump conversions to displace natural gas combustion.
- Ventilation:Energy recovery ventilators and demand-controlled systems address post-pandemic indoor air quality codes in California and Washington commercial buildings.
- Refrigeration:Walk-in coolers and display cases serve food retail and cold chain logistics with ammonia and CO2 systems gaining share in industrial-scale installations.
Volume placements concentrate in Air Conditioning; the faster expansion belongs to Heating as electrification mandates reshape equipment specification.
End User:
Customer type determines service intensity, contract structure, and sensitivity to operating cost guarantees.
- Residential:Single-family and multi-family housing drives unitary system demand through replacement cycles and new construction. Sun Belt metro areas including Atlanta, Phoenix, and Orlando sustain the highest equipment pull per capita.
- Commercial:Retail, hospitality, and office buildings prioritize rooftop units with building automation integration. Energy-as-a-service contracts are displacing traditional capital purchase in Class A office properties.
- Industrial:Process cooling and warehouse climate control require heavy-duty chillers and specialized ventilation. Food processing facilities in the Midwest and chemical plants along the Gulf Coast anchor demand.
- Institutional:Healthcare, education, and government facilities specify precision equipment with extended service agreements. Hyperscale data centers in Northern Virginia and Dallas-Fort Worth are pulling chiller capacity toward high-reliability specifications.
Residential captures the largest unit volume; institutional applications are climbing the fastest as data center thermal loads expand.
Technology:
Connectivity and thermal source differentiation are splitting procurement between efficiency-focused retrofits and new-build specifications.
- Smart HVAC:IoT-enabled diagnostics and predictive maintenance platforms command premium positioning in commercial retrofits. Building operators in Manhattan and Chicago are unbundling equipment purchase from guaranteed performance outcomes.
- Ductless:Mini-split and multi-zone systems reduce mechanical footprint in mid-rise multi-family construction. California developers specify variable refrigerant flow to enable individual unit metering and Title 24 compliance.
- Geothermal:Ground-source heat pumps deliver efficiency advantages in heating-dominated climates with suitable geology. Upfront drilling costs limit deployment to subsidized institutional projects and high-end residential.
- Centralized:Chiller-based systems with air- and water-cooled configurations serve large commercial and industrial footprints. EPA AIM Act refrigerant deadlines are forcing R-1234ze and R-515B conversions ahead of equipment replacement cycles.
Centralized systems retain the highest aggregate value; smart HVAC platforms are gaining share fastest through service revenue attachment.
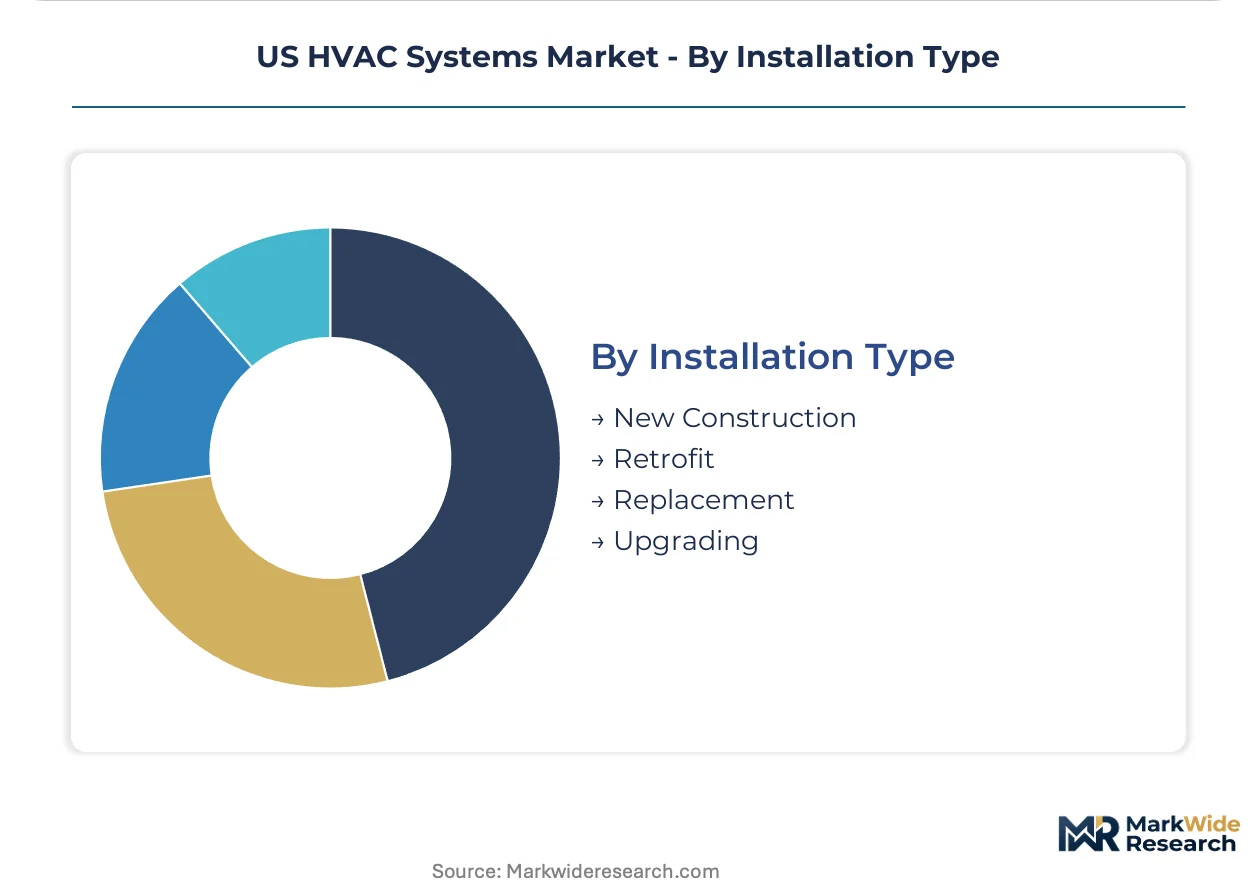
Installation Type:
Project origin determines margin structure, timeline pressure, and contractor specialization requirements.
- Replacement:End-of-life equipment swaps dominate mature urban markets where aging stock faces efficiency mandates. SEER 2 compliance friction is disqualifying legacy product lines and compressing installation windows.
- Retrofit:Building envelope improvements and control system upgrades extend equipment life without full replacement. Third-party energy service companies are capturing decision authority in commercial real estate through performance contracting.
- New Construction:Housing starts and commercial development in Sun Belt states pull equipment through mechanical contractor channels. Refrigerant transition timelines are forcing builders to specify next-generation systems ahead of code mandates.
- Upgrading:Partial system enhancements address specific performance gaps without full replacement. Smart thermostat and sensor integration enables diagnostic capabilities on legacy mechanical infrastructure.
Replacement commands the highest share of current activity; new construction offers the steepest expansion trajectory as Sun Belt development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level clean energy incentives are concentrating HVAC investment in designated development corridors across the Sun Belt and Northeast. Federal tax credits under the Inflation Reduction Act amplify these localized programs. State building codes and utility decarbonization mandates create divergent equipment specifications by geography.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin pulls chiller capacity toward institutional-grade specifications. ERCOT grid instability accelerates demand for resilient cooling systems with on-site power integration. Houston's petrochemical corridor sustains heavy industrial HVAC demand for process cooling and hazardous environment ventilation.
California
Title 24 building energy codes mandate heat pump readiness and refrigerant phase-down compliance in new construction. The California Public Utilities Commission subsidizes cold-climate heat pump retrofits through technology-specific rebate programs. Silicon Valley data centers and Central Valley food processing facilities anchor precision cooling demand.
Florida
Cooling-dominated climate and sustained residential construction in Orlando-Tampa and Miami-Dade sustain split-system equipment pull. The Florida Building Commission enforces stringent wind-load requirements for outdoor condensing units in hurricane zones. Jacksonville's logistics hub drives refrigerated warehouse construction with ammonia-based industrial systems.
New York
The Clean Heat standard mandates building electrification timelines that displace natural gas combustion in heating applications. NYSERDA administers subsidized heat pump installation programs targeting multi-family housing stock. New York City Local Law 97 carbon emission caps force Class A office retrofits with energy-as-a-service contracting models.
Arizona
Extreme cooling loads in Phoenix-Tucson metro areas accelerate equipment replacement cycles and efficiency tier upgrades. Arizona Corporation Commission renewable energy standards drive solar-thermal HVAC integration in commercial developments. Northern Arizona's semiconductor fabrication expansion pulls cleanroom-grade precision air handling capacity.
US HVAC Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding institutional specifications and regional fabricators capturing replacement volume. The market exhibits tiered concentration: national brands anchor new construction specifications, while independent distributors and local contractors control retrofit decision authority. Two strategic archetypes dominate: full-stack building automation providers and refrigerant-transition specialists. Competitive intensity centers on M&A activity consolidating regional service networks and vertical integration into compressor and heat exchanger manufacturing.
Among the integrated OEM tier, Carrier, Trane Technologies, and Daikin Industries Ltd. occupy positions defined by chiller technology leadership, building automation platforms, and variable refrigerant flow specialization respectively. These entities represent divergent bets on data center thermal management, electrification mandates, and modular deployment architectures. Their geographic origins—US-based Carrier and Trane Technologies alongside Japanese Daikin—exemplify how regulatory familiarity with EPA AIM Act timelines versus EMEA F-Gas Regulation experience shapes refrigerant transition pacing.
| Leading Market Players |
|---|
| Carrier |
| Lennox International Inc. |
| Trane Technologies |
| Johnson Controls |
| Daikin Industries Ltd. |
| Rheem Manufacturing Company |
| Nortek Global HVAC |
| AAON Inc. |
| Ingersoll Rand |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EPA AIM Act-compliant equipment and legacy refrigerant systems manifests in both pricing premiums and supply chain reconfiguration. Tiered pricing separates certified low-GWP systems from stranded-asset inventory, while OEMs retool compressor and heat exchanger sourcing to accommodate R-454B and R-1234ze chemistry requirements.
Pricing Analysis
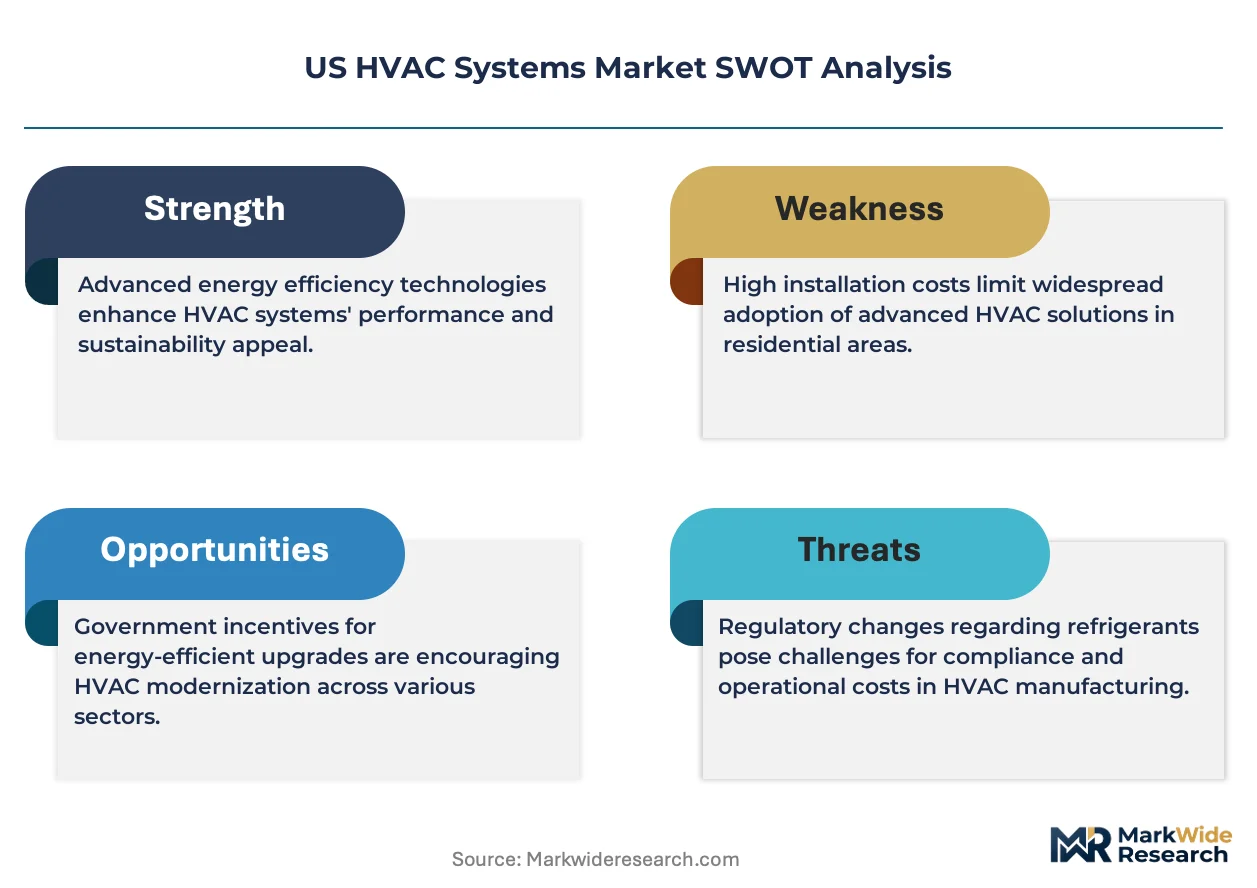
Short lead-time premiums dominate contractor procurement as SEER 2 compliance deadlines compress installation windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with UL-listed and EPA-compliant equipment commanding margin expansion. Cost compression in economy-tier legacy inventory is intensifying because refrigerant supply constraints strand pre-2023 product lines. Residential replacement buyers exhibit highest price sensitivity; institutional data center operators demonstrate lowest sensitivity given thermal uptime requirements.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific compressor manufacturing centers is reshaping domestic inventory positioning strategies. Heat exchanger fabrication draws from China, Mexico, and domestic US facilities; copper and aluminum sourcing rests on Chilean and Australian mining outputs. Single-source vulnerability concentrates in next-generation refrigerant production, where limited domestic R-454B and R-32 capacity creates import dependency. Distribution runs through mechanical contractor networks and independent HVAC distributors serving replacement and new construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US HVAC Systems Market operates as a cost-of-compliance story where EPA AIM Act refrigerant phasedown timelines erect barrier-to-entry moats for OEMs with certified low-GWP product portfolios.
For Market Incumbents: Anchor market position through backward integration into compressor manufacturing and captive heat exchanger production to offset raw material volatility. Secure EPA Section 608 technician certification pipeline partnerships to constrain installation capacity for non-compliant competitors. Defend against emerging VRF specialists by accelerating building automation platform convergence. For New Entrants and Emerging Players: New York's Clean Heat standard and similar state-level electrification mandates in the Northeast corridor open a window for cold-climate heat pump specialization. Target subsidized multi-family retrofit segments where incumbent coverage remains thin. Pursue energy-as-a-service contracting models to bypass traditional mechanical contractor gatekeeping in Class A commercial properties. For Investors and Strategic Acquirers: Re-rating potential sits with refrigerant-transition-ready OEMs given EPA AIM Act enforcement acceleration. Long-term viability centers on 5-10 year compliance runway visibility and service revenue attachment rates. Monitor NYSERDA and California CPUC rebate program expansion as inflection indicators for electrification-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | EPA AIM Act compliance deadlines force R-454B and R-1234ze equipment line conversions ahead of supply constraints. |
| Building Automation Platform Integration | IoT-enabled predictive maintenance extends service revenue models beyond unitary equipment sales in commercial segments. |
| Cold-Climate Heat Pump Capacity Expansion | New York Clean Heat subsidies and similar state mandates create subsidized demand corridors in electrification-focused geographies. |
| Data Center Chiller Specialization | Hyperscale server farm construction in Texas and Virginia pulls institutional-grade precision cooling specifications. |
| Technician Certification Pipeline Investment | EPA Section 608 credentialing capacity constraints limit installation throughput for compliant equipment deployment. |
Research Approach
EPA enforcement documentation, DOE efficiency standard filings, and state utility commission rebate program records formed the secondary backbone of this analysis. Primary interviews with HVAC OEM product managers, mechanical contractor purchasing directors, and commercial real estate facility managers combined with secondary validation across regulatory databases. Bottom-up equipment shipment analysis and top-down construction spending triangulation anchored market sizing.
Historical trendline analysis of replacement cycles, refrigerant transition timelines, and efficiency standard adoption patterns informed projection modeling. Segmentation dimensions span product type, installation category, end-use vertical, and technology tier across the projection horizon. CAGRs were derived from equipment stock turnover rates and regulatory compliance deadline clustering. Forecast inputs include Sun Belt construction permit velocity and data center power allocation announcements.
The model assumes a particular technology adoption path; alternative pathways for low-GWP refrigerant chemistry would alter the outlook if domestic production scale-up accelerates or EPA timelines shift. Forecasts reflect assumptions regarding state-level electrification mandate enforcement and utility rebate program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
HVAC Services Market
HVAC Equipment
Europe Industrial Heat Pump Market