
 HVAC Louvers Market | 2026-2036
HVAC Louvers Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Louvers Market Insights
The gap between premium engineered louvers and commodity-grade products is pivoting on thermal performance certification and wind-load engineering. TROX leverages its European manufacturing footprint to sustain specification-grade positioning in healthcare and data center projects. Greenheck anchors North American distribution through extensive representative networks and quick-ship fabrication capabilities. Ruskin competes on severe-duty industrial applications where AMCA-certified performance differentiates bidding outcomes.
HVAC louvers are architectural airflow control devices, typically fabricated from extruded aluminum or galvanized steel with blade depths ranging from two to six inches, designed to manage intake and exhaust while blocking rain intrusion and debris. Their primary commercial purpose is to protect mechanical equipment and optimize ventilation efficiency across building envelopes. Adjustable louvers command premium positioning in variable-air-volume systems where modulating free area reduces fan energy consumption. Aluminum dominates material selection for coastal and corrosive environments, while steel retains cost advantages in standard commercial construction. Gravity louvers represent a mature segment with limited innovation headroom but steady replacement demand across aging infrastructure.
ASHRAE standards, AMCA certification protocols, and the International Energy Conservation Code collectively dictate minimum performance thresholds for air leakage and thermal transmittance in louver specifications. The EU Green Deal and F-Gas Regulation are accelerating demand for thermally broken frames and low-leakage blade designs across European commercial construction. Stakeholders must monitor evolving code cycles that increasingly integrate louvers into whole-building energy modeling rather than treating them as passive envelope commodities.
Market Dynamics
The EU F-Gas Regulation is compressing replacement cycles across European commercial building stock while thermally broken aluminum framing displaces conventional extruded profiles in specification-grade projects.
Growth Catalysts
- Commercial Retrofit Mandates:Germany's Building Energy Act (GEG) and similar national frameworks across the Netherlands and France are accelerating HVAC infrastructure replacement in aging office and institutional buildings.
- Data Center Thermal Management:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore are specifying high-performance louvers with AMCA-certified wind-load ratings to protect critical cooling equipment.
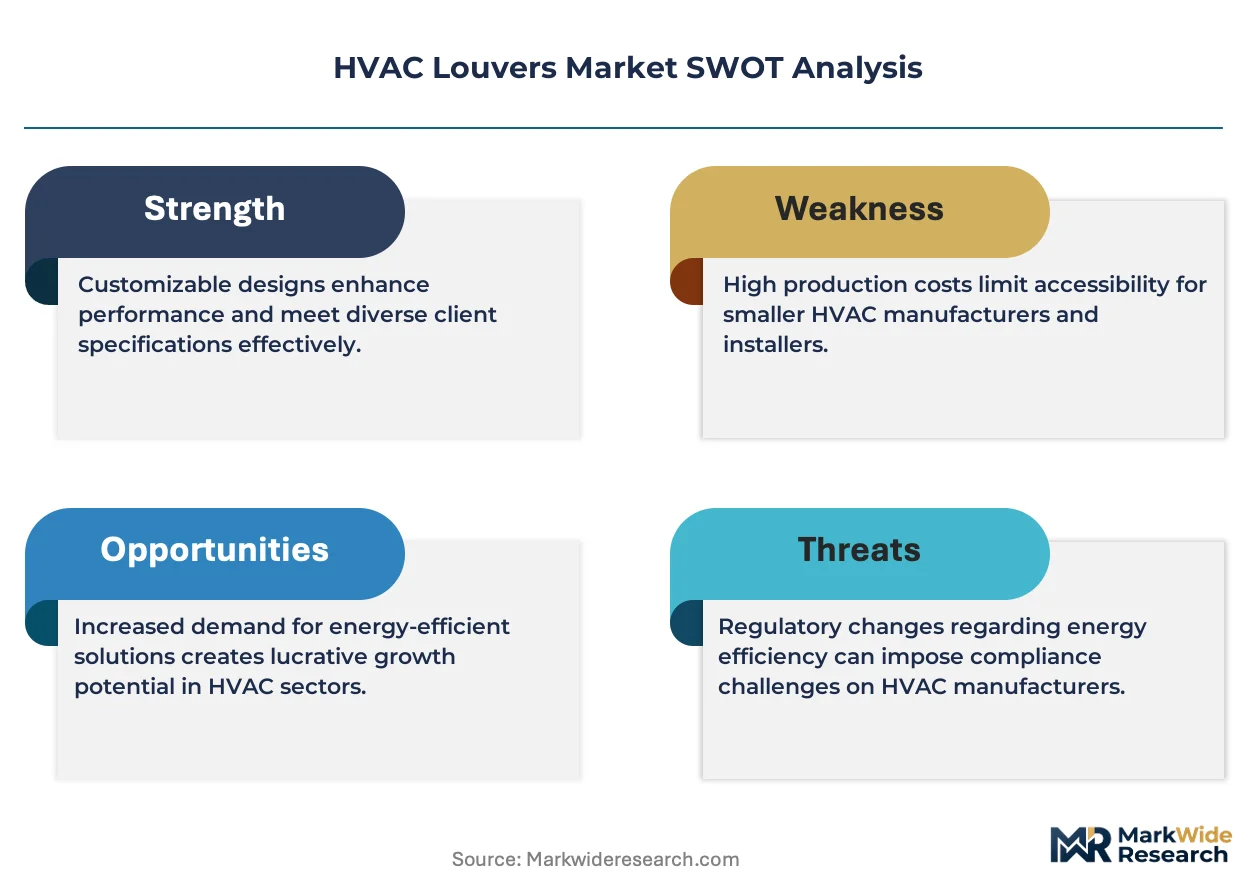
- Coastal Corrosion Standards:Marine-grade anodized aluminum alloys meeting ASTM B117 salt-spray protocols are capturing specification share in Miami, Rotterdam, and Sydney harbor-adjacent developments.
Market Restraints
- Aluminum Price Volatility:LME aluminum futures and regional Midwest premiums create margin compression for fabricators holding inventory across 60-90 day production cycles.
- Chinese Extrusion Capacity Concentration:Shandong and Guangdong provinces control approximately 60% of global aluminum extrusion feedstock, creating single-source dependency risks for European and North American louver manufacturers.
- Steel-Alternative Performance Ceiling:Galvanized steel louvers face inherent thermal bridging limitations that disqualify them from Passive House-certified envelope assemblies regardless of cost advantages.
Strategic Opportunities
- Indian Commercial Construction:Bureau of Indian Standards (BIS) adoption of EN 13030 louver performance standards is opening specification-grade market entry as Mumbai and Bangalore high-rise development accelerates.
- Smart Building Integration:BACnet-enabled adjustable louver actuators are converging with building management systems to enable demand-controlled ventilation in mixed-use developments.
- US Inflation Reduction Act:Section 179D commercial building energy efficiency tax deductions are expanding project budgets for envelope upgrades including thermally broken louver replacements.
Industry Challenges
- AMCA Certification Backlogs:Extended laboratory queue times for air leakage and wind-driven rain testing are delaying product launches and contract bidding eligibility.
- Specification-to-Procurement Leakage:Value engineering processes in commercial construction frequently substitute specified performance-grade louvers with non-certified alternatives, eroding manufacturer margin capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Louvers Market |
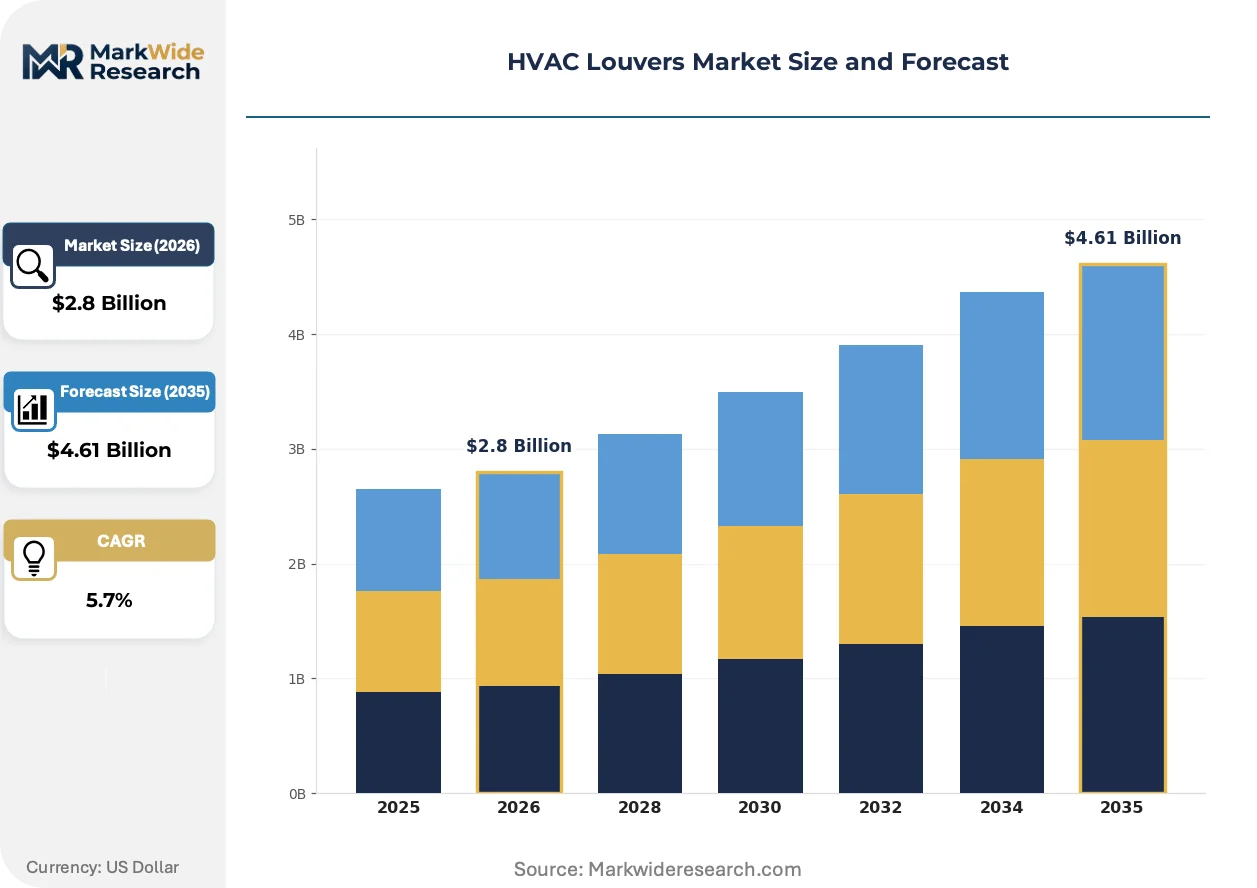
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Louvers, Adjustable Louvers, Gravity Louvers, Industrial Louvers Application: Commercial Buildings, Industrial Facilities, Residential Spaces, HVAC Systems Material: Aluminum, Steel, Plastic, Fiberglass End User: Contractors, Engineers, HVAC Manufacturers, Building Owners |
| Companies Covered | FLAKT WOODS, HALTON, TROX, Lloyd Industries, Nailor, Ruskin, Actionair, Pottorff, Greenheck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Louvers Market Trends and Innovations
Active louver systems are displacing static architectural metalwork as building envelopes become instrumented thermal barriers rather than passive weather protection.
Thermally broken aluminum blade assemblies with polyamide thermal struts are converging with aerodynamic computational fluid dynamics modeling to achieve sub-1.0 W/m²K frame U-values. Healthcare and laboratory facility designers in Switzerland and the Netherlands are specifying these systems for infection control zones requiring precise pressure differentials. The convergence is compressing the performance gap between louver manufacturers and curtain wall system suppliers.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is indirectly tightening envelope thermal performance requirements as HVAC systems shift to lower-global-warming-potential alternatives with reduced capacity margins. Commercial building energy modeling under the Energy Performance of Buildings Directive now treats louvers as thermal bridge elements rather than negligible losses. German industrial developers are responding by mandating thermally broken frames in all new construction specifications.
Specification-grade buyers are consolidating vendor relationships around single-source accountability for envelope performance warranties. General contractors on US federal and institutional projects are shifting from fragmented commodity purchasing to negotiated frame agreements with certified manufacturers who carry AMCA-certified product ranges and in-house thermal modeling capabilities. This consolidation is most visible in GSA-schedule procurement and military construction programs.
HVAC Louvers Market Segmentation
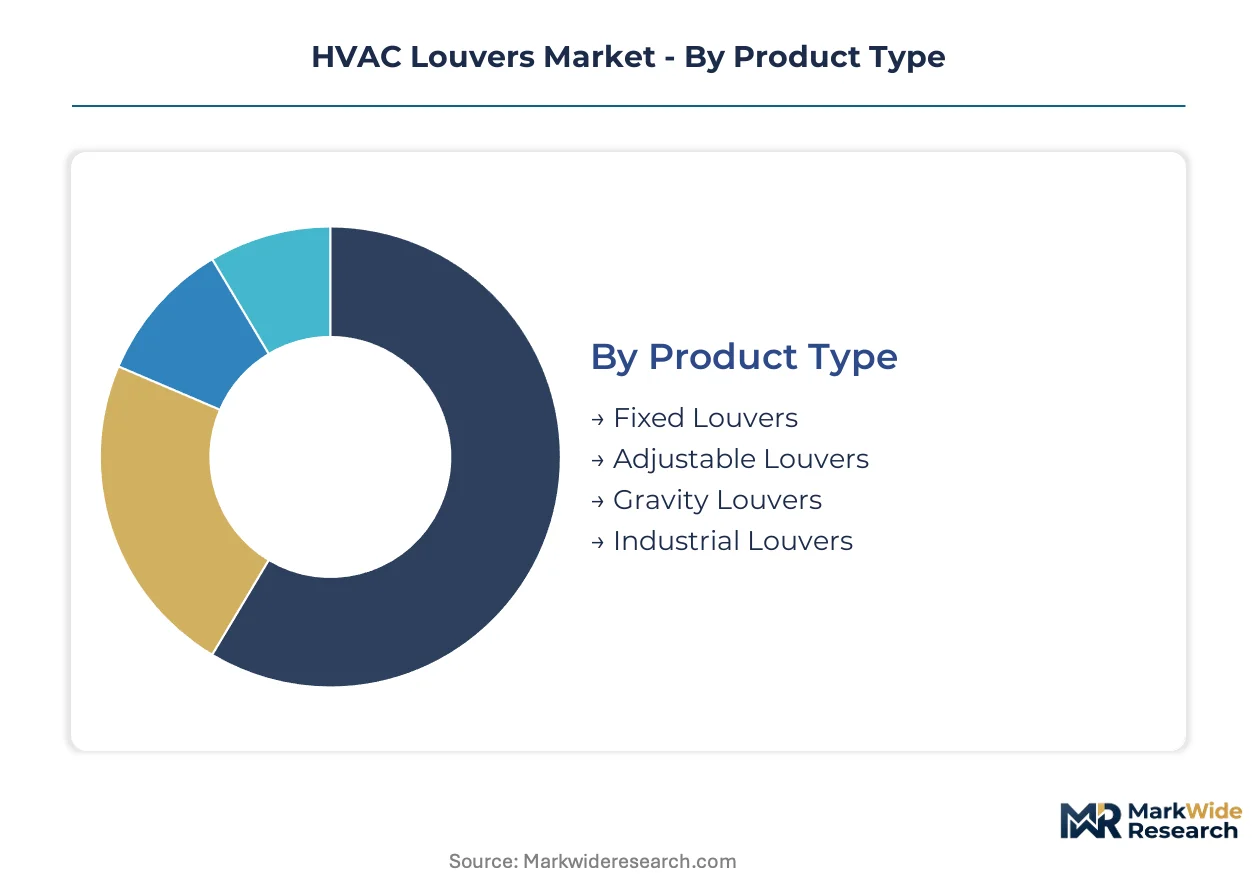
HVAC louver segmentation reveals how supply-side capabilities and specification requirements fragment across product architectures, building applications, and procurement channels. Understanding these divisions clarifies where thermal performance certification and material sourcing advantages concentrate.
Product Type:
Supply concentration tilts toward adjustable and industrial variants where AMCA-certified fabrication capabilities limit vendor participation.
- Fixed Louvers:Static blade assemblies with two-to-four-inch depths dominate standard commercial envelope applications. Demand concentrates in North American retail and office construction where first-cost sensitivity overrides modulating airflow requirements.
- Adjustable Louvers:Motorized or pneumatic blade actuation enables variable free-area control for demand-responsive ventilation systems. Data center and healthcare projects in Northern Virginia and Frankfurt specify these for precision thermal management and pressure differential maintenance.
- Gravity Louvers:Counterweighted blade mechanisms for passive exhaust applications in parking garages and utility spaces.
- Industrial Louvers:Heavy-gauge steel or reinforced aluminum constructions rated for severe wind loads and particulate exposure.
Fixed louvers absorb the bulk of installed capacity; adjustable louvers are expanding most quickly.
Application:
Cost tier differentiation separates specification-grade projects with thermal modeling requirements from commodity replacements driven by maintenance budgets.
- Commercial Buildings:Office towers, retail centers, and institutional facilities requiring AMCA-certified wind-driven rain resistance. Germany's Building Energy Act retrofits and US Section 179D tax deductions are accelerating thermally broken louver adoption in aging stock.
- Industrial Facilities:Manufacturing plants, warehouses, and process buildings with high air-change requirements and corrosion exposure. Demand clusters in Germany's industrial corridor where HVAC infrastructure upgrades dominate capital allocation.
- Residential Spaces:Multi-family and high-rise housing with limited louver exposure, typically gravity or fixed configurations.
- HVAC Systems:Dedicated mechanical equipment protection for chillers, cooling towers, and air handling units.
Commercial buildings command premium specification rates; industrial facilities represent the steepest expansion trajectory.
Material:
Volume concentration in aluminum extrusion reflects coastal specification requirements and thermal break compatibility, while steel retains cost-driven commercial share.
- Aluminum:Extruded 6063-T5 or 6061-T6 alloys with anodized or fluoropolymer finishes. Coastal developments in Miami, Rotterdam, and Sydney specify marine-grade variants meeting ASTM B117 salt-spray protocols.
- Steel:Galvanized or painted carbon steel for standard commercial construction where thermal bridging limitations exclude Passive House certification.
- Plastic:PVC or composite formulations for corrosive chemical environments and budget-constrained applications.
- Fiberglass:Pultruded profiles for extreme chemical resistance and electromagnetic transparency in specialized industrial settings.
Aluminum dominates specification-grade revenue; fiberglass is gaining share fastest in niche corrosion applications.
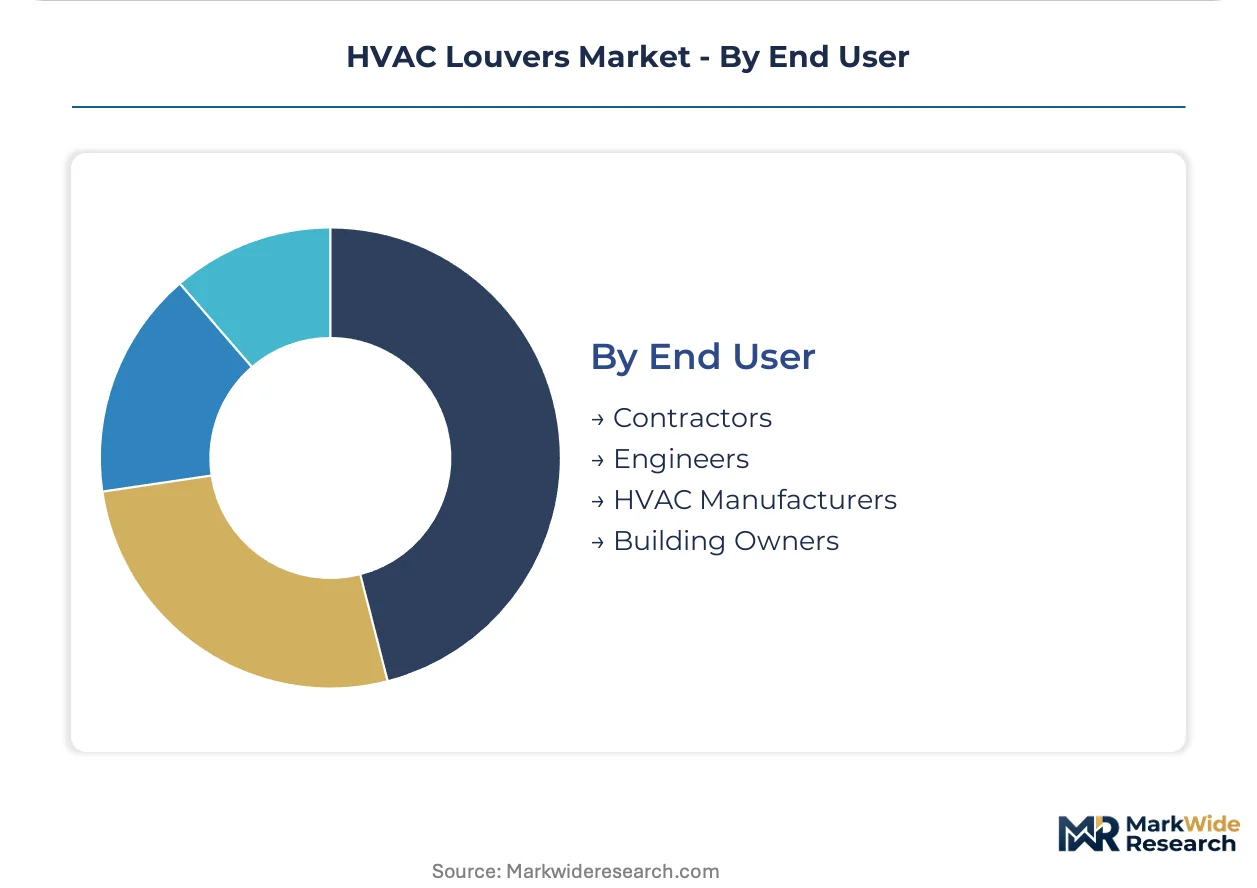
End User:
Customer type determines procurement channel structure, with engineers controlling upstream specification and contractors driving downstream purchasing volume.
- Contractors:General and mechanical contractors executing value-engineered procurement on commercial and institutional projects. Substitution pressure frequently displaces specified performance-grade products with non-certified alternatives.
- Engineers:MEP consultants and envelope specialists who embed thermal performance requirements and AMCA certification into construction documents. Their specifications determine bidding eligibility for federal and healthcare projects.
- HVAC Manufacturers:Original equipment builders integrating louvers into packaged air handling units and cooling towers.
- Building Owners:Facility managers and developers with direct procurement authority in retrofit and maintenance scenarios.
Contractors absorb the bulk of transaction volume; engineers are consolidating influence fastest through performance-based specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European demand concentration for high-performance louvers serving hyperscale data center thermal management requirements.
United States
Retrofit mandates under the Inflation Reduction Act's Section 179D provisions accelerate thermally broken louver replacements across aging commercial stock. The EPA and Department of Energy coordinate envelope efficiency standards that elevate AMCA certification requirements in federal procurement. Northern Virginia's data center corridor specifies wind-load-rated adjustable louvers for critical cooling infrastructure protection.
Germany
The Building Energy Act (GEG) compresses HVAC infrastructure replacement cycles in office and institutional buildings nationwide. EU F-Gas Regulation enforcement tightens thermal performance specifications for envelope components in commercial retrofits. The industrial corridor spanning North Rhine-Westphalia dominates capital allocation toward HVAC upgrades in manufacturing facilities.
China
Dual carbon goals and GB standards for building energy efficiency reshape specification requirements in commercial construction. The Ministry of Ecology and Environment enforces envelope thermal performance codes that displace conventional louver designs in high-rise development. Shandong and Guangdong provinces concentrate aluminum extrusion feedstock capacity serving domestic and export fabrication demand.
India
Bureau of Indian Standards adoption of EN 13030 louver performance protocols opens specification-grade market entry for international manufacturers. The Bureau of Energy Efficiency mandates commercial building envelope upgrades under the Energy Conservation Building Code. Mumbai and Bangalore high-rise construction clusters drive demand for AMCA-certified wind-driven rain protection systems.
Netherlands
Healthcare and laboratory facility designers specify thermally broken louvers with sub-1.0 W/m²K frame U-values for infection control zone pressure management. The Energy Performance of Buildings Directive integration treats louvers as thermal bridge elements in whole-building energy modeling. The Randstad metropolitan concentration anchors specification-grade procurement for institutional and mixed-use developments.
HVAC Louvers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure where fabrication scale separates specification-grade from commodity supply. Three to four integrated manufacturers anchor premium positioning through captive thermal break assembly and in-house AMCA certification testing. Mid-scale regional fabricators compete on quick-ship responsiveness and representative network density. Dominant competitive moves include backward integration into aluminum extrusion supply and strategic partnerships with MEP engineering firms to secure upstream specification control.
Among European-headquartered specialists, TROX and HALTON occupy positions within the specification-grade tier for healthcare and data center applications. FLAKT WOODS anchors Scandinavian-origin positioning in industrial ventilation systems. Greenheck exemplifies North American scale-driven fabrication with extensive distribution infrastructure. Ruskin represents severe-duty industrial specialization where AMCA-certified performance documentation differentiates bidding outcomes. These archetypes illustrate how geographic manufacturing footprint and certification depth stratify competitive positioning across procurement channels.
| Leading Market Players |
|---|
| FLAKT WOODS |
| HALTON |
| TROX |
| Lloyd Industries |
| Nailor |
| Ruskin |
| Actionair |
| Pottorff |
| Greenheck |
| Others |
Pricing and Supply Chain Analysis
Federal procurement officers and GSA-schedule buyers anchor specification-grade louver demand, concentrating purchasing power around AMCA-certified manufacturers who command project-based pricing premiums tied to thermal performance documentation. This buyer concentration feeds into a tiered pricing structure where certification depth and wind-load engineering separate premium bids from commodity alternatives.
Pricing Analysis
Value-based pricing anchored to energy performance outcomes dominates specification-grade segments, with thermally broken aluminum assemblies commanding premiums tied to whole-building energy modeling credits. Price differentiation rests on AMCA certification tier and thermal break assembly complexity, not raw material grades alone. Cost compression in standard commercial construction intensifies as galvanized steel alternatives face disqualification from Passive House-certified projects. General contractors exhibit highest price sensitivity in value-engineering phases, while MEP consultants show lowest sensitivity when thermal performance warranties are at stake.
Supply Chain Analysis
Dual-sourcing mandates from European and North American fabricators require qualification of secondary aluminum extrusion suppliers beyond dominant Shandong and Guangdong province capacity. Raw material dependencies center on 6063-T5 aluminum billet, polyamide thermal struts, and marine-grade anodizing chemistries. Single-source vulnerability in Chinese extrusion feedstock creates structural risk for specification-grade manufacturers holding 60-90 day inventory cycles. Distribution runs through manufacturer representative networks and direct specification selling to MEP engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC louvers market reads as a cost-of-compliance story where the EU F-Gas Regulation and ASHRAE 90.1 code cycles erect certification barriers that protect incumbent positions while raising capital requirements for new entrants.
For Market Incumbents: Anchor specification control through captive in-house AMCA testing capabilities and thermal modeling services that general contractors cannot replicate. Deepen backward integration into aluminum extrusion supply to offset LME price volatility exposure. Defend against value-engineering substitution by embedding performance warranties into construction documents. For New Entrants and Emerging Players: MEP engineering boutiques in India's high-rise construction clusters represent the most penetrable channel for specification-grade entry under newly adopted EN 13030 standards. Target Mumbai and Bangalore commercial developments where international certification is newly mandatory but local fabrication capacity remains limited. Pursue joint specification development with European-certified manufacturers seeking geographic extension. For Investors and Strategic Acquirers: The window for entry favors vertically integrated regional fabricators with captive thermal break assembly and existing AMCA laboratory relationships. Mid-scale North American and European specialists with healthcare and data center specification track records present viable acquisition profiles. Watch for inflection when AMCA certification backlogs exceed six-month queue times, signaling pricing power accumulation among tested incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| AMCA Certification Investment | In-house testing capacity secures bidding eligibility for federal and healthcare projects. |
| Thermal Break Assembly Integration | Captive polyamide strut production insulates margin from component supply disruption. |
| Engineering Partnership Program | Upstream specification embedding with MEP consultants reduces value-engineering leakage. |
| Quick-Ship Fabrication Scale-Up | Regional inventory positioning captures retrofit replacement cycles under compressed timelines. |
| Smart Building Actuator Development | BACnet-enabled controls integration opens demand-responsive ventilation specification channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving MEP specification engineers, commercial general contractors, AMCA laboratory directors, aluminum extrusion procurement managers, and federal facilities energy officers. Primary fieldwork combined structured interviews with facility audits across Northern Virginia data centers, Germany's North Rhine-Westphalia industrial corridor, and Mumbai high-rise construction sites. Secondary sources included ASHRAE standards documentation, EU F-Gas Regulation implementation reports, Bureau of Indian Standards adoption filings, and SEC 10-K disclosures from publicly traded building products manufacturers. Bottom-up project pipeline tracking and top-down construction spend estimates were reconciled through iterative triangulation.
Data-stream reconciliation across shipment volumes, specification frequency databases, and installed cost surveys informed the analytical framework. Segmentation modeling incorporated product architecture, application vertical, material grade, thermal performance tier, and procurement channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical replacement cycles and projected retrofit mandates. Industry-specific inputs included AMCA certification queue times, LME aluminum forward curves, and commercial building energy code adoption schedules.
Caveats apply where aluminum price volatility, Chinese export restriction policies, or AMCA laboratory capacity constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and construction labor availability. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down schedules or US Section 179D tax deduction renewal status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Blowers Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
South Korea HVAC Market