
 Commercial HVAC Market | 2026-2036
Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial HVAC Market Analysis
Asian compressor and coil manufacturing clusters are restructuring capacity allocation toward higher-efficiency refrigerant architectures. Carrier leverages backward integration into compressor design to sustain margin control across chiller and rooftop unit lines. Daikin Industries anchors its position through captive supply of inverter-driven components for variable refrigerant flow systems. Trane Technologies competes on building automation integration, extending its offer beyond hardware into energy management services.
Commercial HVAC encompasses climate control systems engineered to regulate temperature, humidity, and air quality within non-residential built environments, typically operating at capacities from five tons to thousands of tons for centralized plant configurations. These systems employ vapor-compression or absorption refrigeration cycles, often paired with hydronic distribution networks, to maintain indoor environmental conditions for occupant comfort and process-critical operations. Chillers represent the most capital-intensive product category, with margin pools concentrated in magnetic-bearing and oil-free centrifugal designs. Variable refrigerant flow technology leads technology growth due to zoning flexibility and reduced ductwork requirements in retrofits. Office buildings remain the largest application segment, though warehouses are gaining share as e-commerce fulfillment drives cold-chain-adjacent climate specifications.
The EPA enforces refrigerant transition timelines under the AIM Act, while the Department of Energy imposes minimum efficiency standards through Federal Register rulemakings that reset equipment cost baselines. ASHRAE Standard 90.1 shapes building code adoptions across municipalities, filtering equipment specifications through state-level enforcement variations. Stakeholders must monitor refrigerant supply chain readiness for A2L-class alternatives and calibrate R&D portfolios against pending DOE efficiency tier resets.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing equipment replacement cycles while forcing manufacturers to reconfigure compressor architectures and supply chains around lower-global-warming-potential alternatives.
Growth Catalysts
- AIM Act Refrigerant Mandates:The EPA's phasedown schedule under the American Innovation and Manufacturing Act accelerates replacement of R-410A and R-134a systems, pulling forward demand for A2L-compatible equipment across hospital and data center end-uses.
- Data Center Thermal Loads:Hyperscale computing facilities in Northern Virginia and Dallas-Fort Worth are specifying chilled-water plants above 2,000 tons, expanding the addressable market for magnetic-bearing centrifugal compressors.
- Heat Pump Technology:Cold-climate heat pumps capable of operating at sub-zero ambient temperatures are penetrating K-12 school retrofits in Minnesota and Wisconsin, displacing gas-fired boilers in districts pursuing electrification.
Market Restraints
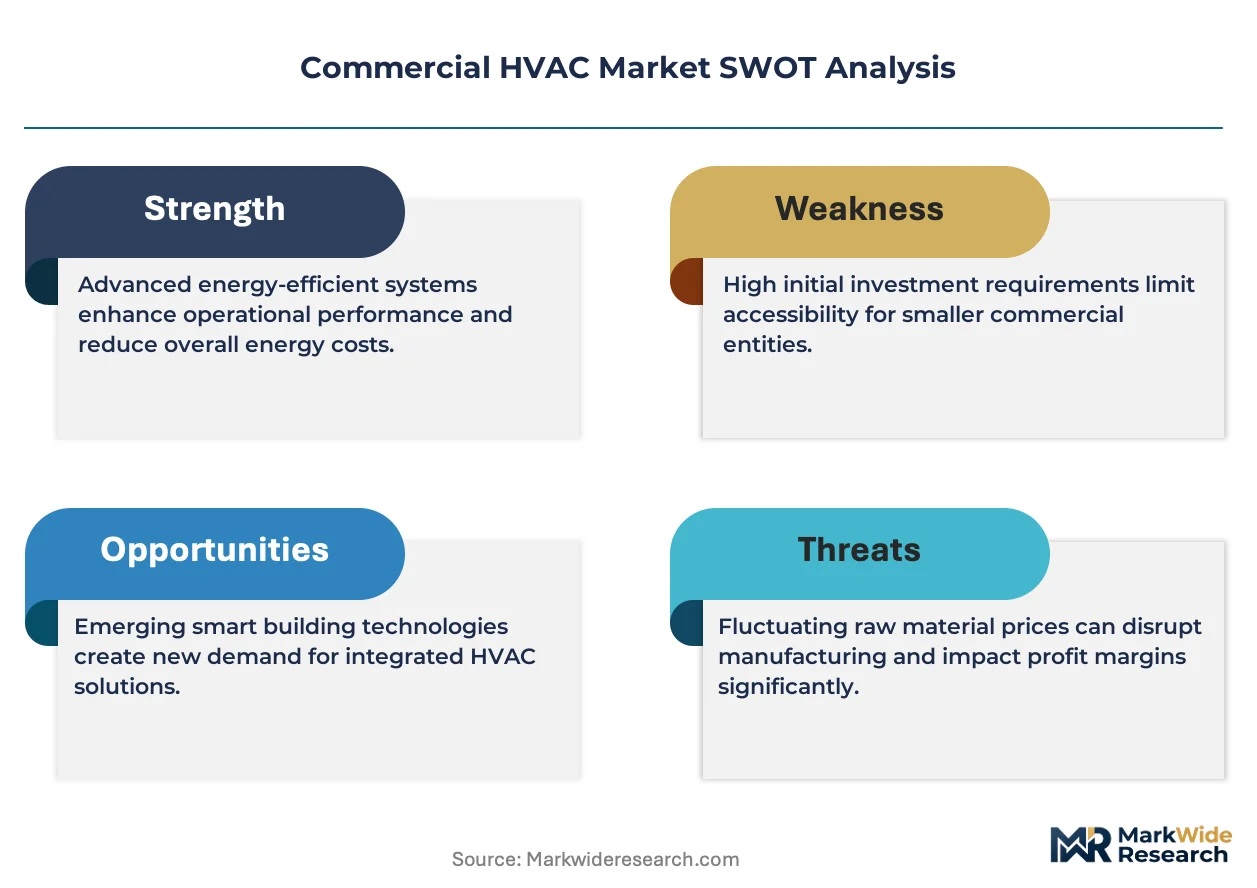
- Copper and Aluminum Input Volatility:Coil manufacturing costs fluctuate with London Metal Exchange pricing for copper tubing and aluminum finstock, compressing margins on standardized rooftop units where material comprises 35-40% of unit cost.
- Compressor Supply Concentration:Scroll and screw compressor production clusters in eastern China and Thailand create geographic risk for North American OEMs dependent on just-in-time component flows through Los Angeles and Vancouver ports.
- A2L Refrigerant Flammability Classification:The transition to mildly flammable R-454B and R-32 requires redesign of safety systems, electrical enclosures, and ventilation protocols, extending product development timelines by 12-18 months.
Strategic Opportunities
- Life Science Manufacturing:Cell and gene therapy facilities in Research Triangle Park and Boston require ISO Class 7 cleanrooms with tight temperature and humidity control, creating specification pull for precision chilled-beam systems.
- DOE Efficiency Tier Resets:The Department of Energy's pending Federal Register rulemakings for commercial air conditioners and heat pumps will reset minimum efficiency baselines, advantaging early movers with pre-certified equipment portfolios.
- Building Automation Convergence:Integration of HVAC controls with lighting and security systems through BACnet/IP and MQTT protocols enables subscription-based energy management services, shifting revenue from equipment to recurring software.
Industry Challenges
- Refrigerant Handling Certification:EPA Section 608 technician certification requirements for A2L refrigerants create training bottlenecks, limiting installer capacity during peak construction seasons in Sun Belt markets.
- Legacy BAS Integration:Proprietary communication protocols in 1990s-era building automation systems obstruct seamless integration with modern variable refrigerant flow controllers, requiring costly gateway hardware or full control replacements.
- Magnetic Bearing Servicing:Oil-free centrifugal chillers demand specialized vibration analysis and bearing replacement capabilities that few service contractors possess outside major metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial HVAC Market |
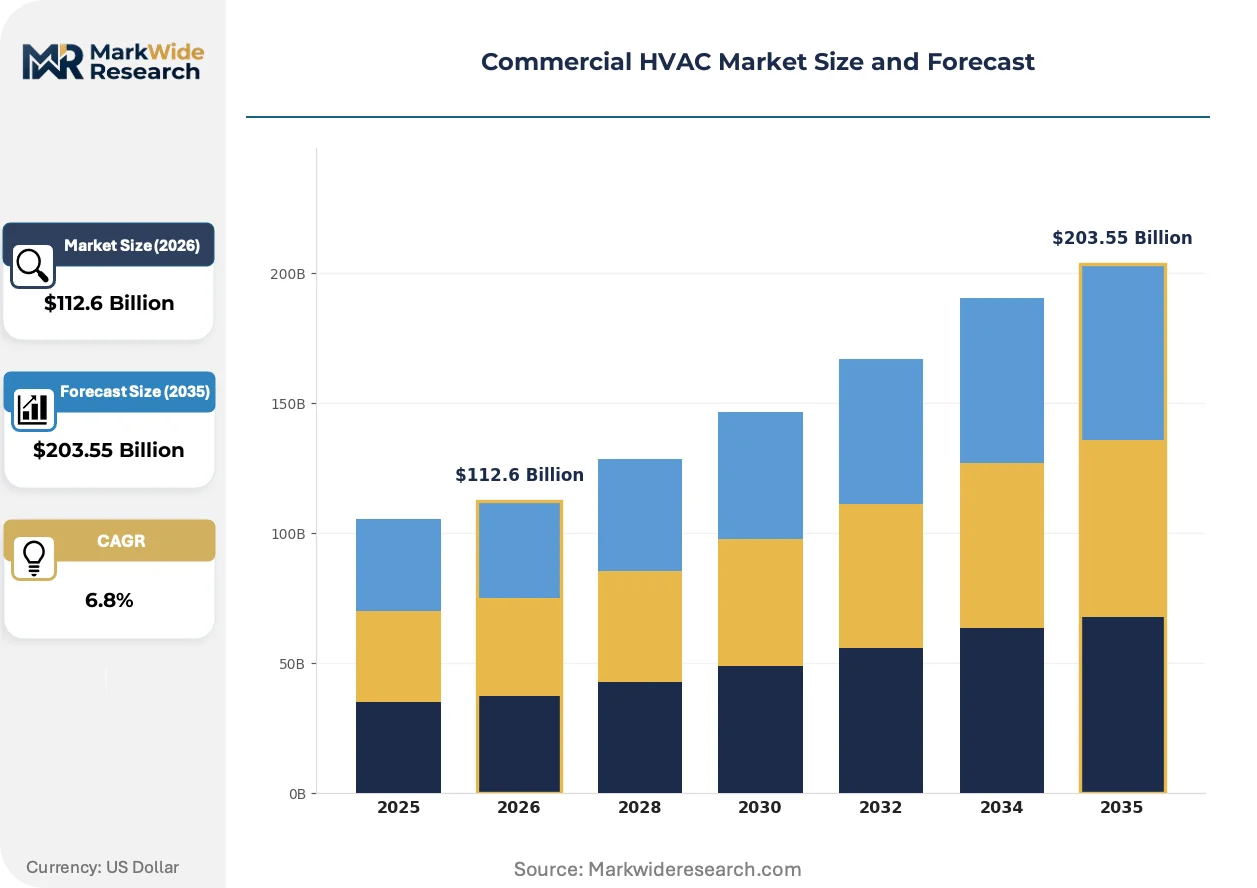
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Rooftop Units, Heat Pumps, Air Handlers Technology: Variable Refrigerant Flow, Geothermal, Hydronic, Ductless Application: Office Buildings, Retail Stores, Warehouses, Educational Institutions End User: Commercial Offices, Restaurants, Hospitals, Manufacturing Facilities |
| Companies Covered | Carrier, Daikin Industries, Trane Technologies, Johnson Controls, Lennox International, Mitsubishi Electric, Honeywell International, LG Electronics, Rheem Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial HVAC Market Emerging Trajectories
Refrigerant chemistry transitions and control system digitization are compressing product lifecycles while expanding the boundary of what HVAC equipment manufacturers must deliver beyond thermal hardware.
Magnetic-bearing centrifugal compressor technology is consolidating performance advantages in large-tonnage applications. Oil-free operation eliminates lubricant contamination risks in hospital and pharmaceutical process cooling. Healthcare systems in Cleveland Clinic and Mayo Clinic networks are specifying these systems for 24/7 critical loads. The technology is consolidating supplier margins in the 500-ton-and-above chiller segment while displacing conventional oil-lubricated designs from premium specifications.
The EPA's Technology Transitions rule under the AIM Act mandates production phaseouts of high-GWP refrigerants on fixed schedules. Equipment manufacturers must recertify product lines for A2L alternatives before January 2025 deadlines for certain categories. Rooftop unit and chiller OEMs serving the US market are responding by accelerating R-454B qualification programs and redesigning electrical compartments to meet UL 60335-2-40 safety standards.
Energy-as-a-service contracting is altering capital deployment patterns for building owners. Third-party financiers assume equipment ownership and maintenance obligations while selling thermal output on per-therm or per-square-foot bases. This model is penetrating university and municipal building portfolios in California and New York where budget constraints obstruct outright equipment purchases. Service providers capture long-term revenue streams while owners transfer performance risk and eliminate balance-sheet capitalization.
Commercial HVAC Market Segmentation
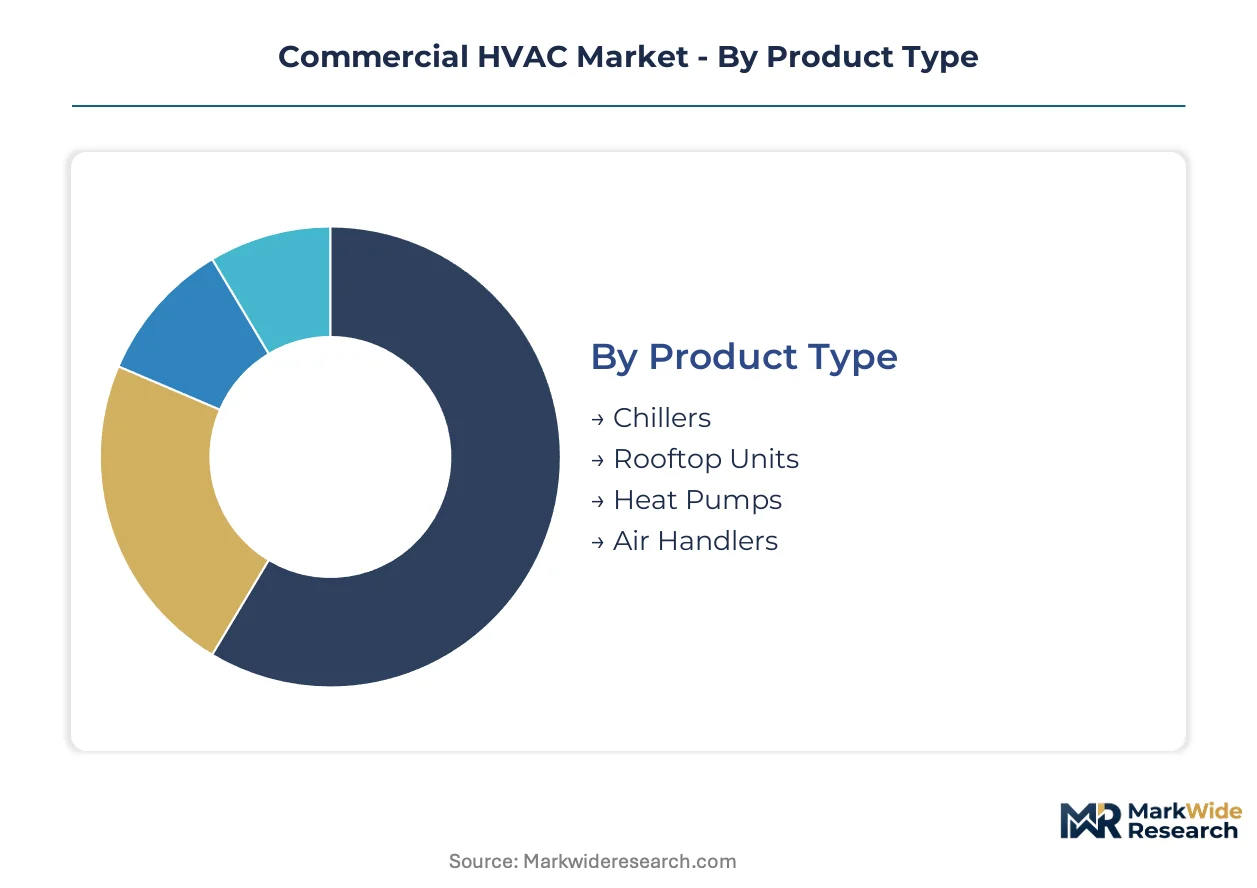
Commercial HVAC purchasing decisions split across equipment performance tiers, thermal distribution architectures, building typologies, and operational criticality levels. Each segmentation dimension carries distinct specification requirements, certification standards, and lifecycle cost structures that shape vendor positioning.
Product Type:
Volume sales concentrate in standardized rooftop units for budget-constrained retrofits, while premium margins pool in specialized chiller configurations for mission-critical cooling loads.
- Chillers:Centralized vapor-compression or absorption systems delivering chilled water to air-handling terminals across large floorplates. Magnetic-bearing centrifugal designs dominate hospital and pharmaceutical specifications in Cleveland Clinic and Mayo Clinic networks where oil-free operation eliminates contamination risks for 24/7 process cooling.
- Rooftop Units:Self-contained packaged systems integrating compressors, coils, and controls in weatherized enclosures for single-zone applications. Demand clusters in Sun Belt retail and light industrial retrofits where fast installation and minimal indoor footprint offset efficiency limitations against split systems.
- Heat Pumps:Reversible refrigeration cycles providing both heating and cooling through common distribution infrastructure. Cold-climate variants penetrating K-12 districts in Minnesota and Wisconsin displace gas-fired boilers as electrification mandates tighten.
- Air Handlers:Fan-coil assemblies distributing conditioned air through ductwork without onboard compression. Specification concentrates in mixed-use developments pairing central chiller plants with zone-level temperature control.
Mature deployment sits with rooftop units across suburban office parks. Newer deployment is concentrated in heat pumps responding to boiler displacement incentives.
Technology:
Application context determines technology selection—zoning flexibility requirements versus ground-coupled thermal stability versus hydronic distribution efficiency versus minimal infrastructure retrofits.
- Variable Refrigerant Flow:Refrigerant-based zoning systems modulating compressor speed to match simultaneous heating and cooling demands across multiple indoor units. Daikin Industries anchors category leadership through captive inverter component supply, penetrating urban office retrofits where ductwork replacement proves cost-prohibitive.
- Geothermal:Ground-source heat pumps exchanging thermal energy with subsurface formations for stable coefficient-of-performance performance. Installation concentrates in educational institutions and federal buildings with capital budgets accommodating 15-25 year payback horizons and available land for vertical bore fields.
- Hydronic:Water or glycol-based distribution networks conveying thermal energy from central plants to terminal units. Chilled-beam variants gain specification in life science manufacturing cleanrooms across Research Triangle Park requiring precise humidity control without forced air turbulence.
- Ductless:Split-system configurations eliminating air distribution infrastructure through direct refrigerant lines to wall or ceiling cassettes. Adoption accelerates in historic building renovations and hospitality additions where structural constraints obstruct duct routing.
Mature deployment sits with hydronic systems in legacy commercial cores. Newer deployment is concentrated in variable refrigerant flow as building automation integration deepens.
Application:
Building typology dictates load profiles, operating hours, and tenant-mix complexity that filter equipment specifications through different capital recovery expectations.
- Office Buildings:Multi-tenant commercial structures with variable occupancy patterns and moderate internal gains. Specifications prioritize part-load efficiency and individual zone control to accommodate lease turnover and after-hours usage fragmentation.
- Retail Stores:Single-tenant or anchor-tenant spaces with high foot traffic, significant glazing loads, and extended operating hours. Demand concentrates in packaged rooftop units with rapid commissioning timelines for tenant improvement cycles.
- Warehouses:Large-volume structures with high infiltration, minimal internal gains, and occasional conditioning requirements for inventory protection. E-commerce fulfillment specifications are expanding climate-controlled zones adjacent to cold-chain operations.
- Educational Institutions:K-12 and university buildings with intermittent occupancy, seasonal shutdowns, and public procurement constraints. Electrification mandates in California and New York are accelerating heat pump specifications for boiler replacement programs.
Mature deployment sits with office buildings across central business districts. Newer deployment is concentrated in warehouses as fulfillment center construction accelerates.
End User:
Operational criticality and regulatory exposure create divergent procurement behaviors—commoditized price competition versus engineering-intensive specification processes.
- Commercial Offices:Corporate and multi-tenant facilities prioritizing tenant comfort, energy cost management, and lease competitiveness. Procurement emphasizes lifecycle operating costs over first cost, with building automation integration increasingly valued.
- Restaurants:Food service operations with high ventilation requirements, grease-laden exhaust, and refrigeration integration needs. Specifications demand corrosion-resistant coils and makeup air systems balancing kitchen exhaust with dining comfort.
- Hospitals:Acute care facilities requiring 24/7 environmental control for patient safety, infection control, and equipment cooling. ASHRAE Standard 170 ventilation requirements and Joint Commission accreditation drive premium specifications for redundancy and monitoring.
- Manufacturing Facilities:Industrial environments with process cooling loads, air quality requirements, and equipment heat dissipation. Life science cell and gene therapy operations in Boston and Research Triangle Park require ISO Class 7 cleanrooms with precision chilled-beam conditioning.
Mature deployment sits with commercial offices in suburban markets. Newer deployment is concentrated in hospitals expanding climate-controlled infrastructure for operational resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper tubing and aluminum finstock from Chinese and Thai manufacturing clusters feed coil fabrication across major HVAC demand centers. Regional markets diverge sharply based on building stock age, electrification policy intensity, and data center construction velocity.
United States
Hospital networks in Cleveland and Rochester are specifying magnetic-bearing chillers for 24/7 critical cooling loads. The EPA's AIM Act refrigerant phasedown is accelerating R-454B equipment qualification programs ahead of January 2025 deadlines. Northern Virginia's hyperscale data center corridor is absorbing chilled-water plants above 2,000 tons.
China
Scroll and screw compressor production concentrates in eastern manufacturing zones serving domestic retrofit demand and export markets. The MIIT's dual carbon goals are tightening efficiency standards for commercial building equipment. Yangtze River Delta cities are deploying variable refrigerant flow systems in aging office stock where ductwork replacement proves cost-prohibitive.
Germany
Industrial heat pump adoption is penetrating chemical and pharmaceutical process cooling applications in the Rhine-Ruhr region. The EU F-Gas Regulation is mandating lower-GWP refrigerant transitions ahead of broader European deadlines. Bavaria's automotive supplier parks are specifying precision climate control for battery component manufacturing.
Japan
Inverter-driven compressor technology from domestic suppliers anchors variable refrigerant flow penetration in dense urban commercial cores. METI efficiency standards are resetting minimum performance baselines for commercial air conditioning equipment. Osaka-Kobe manufacturing clusters are exporting high-efficiency heat pump architectures to Southeast Asian markets.
India
IT/ITES campus construction in Bengaluru and Hyderabad is driving absorption chiller demand for large-tonnage process cooling loads. The Bureau of Energy Efficiency's commercial building codes are mandating stricter HVAC performance standards in designated smart cities. Gujarat's pharmaceutical manufacturing zones are expanding climate-controlled cleanroom infrastructure.
Commercial HVAC Market Vendor Landscape
Global majors compete with regional champions across refrigerant architecture transitions and building automation integration depth. Market structure concentrates premium chiller specifications among three dominant players while rooftop unit competition fragments across price-tiered portfolios. Strategic archetypes separate captive-component manufacturers, controls-integrated solution providers, and scale-driven packaged equipment fabricators. Consolidation momentum favors backward integration into compressor design and vertical control over inverter electronics supply.
Within the captive-component tier, Daikin Industries exemplifies inverter supply chain control, while Carrier occupies a position anchored in compressor design integration. Trane Technologies represents the controls-convergence archetype extending beyond thermal hardware into energy management services. These three firms illustrate divergent defensive positioning against refrigerant transition costs and efficiency tier resets.
| Leading Market Players |
|---|
| Carrier |
| Daikin Industries |
| Trane Technologies |
| Johnson Controls |
| Lennox International |
| Mitsubishi Electric |
| Honeywell International |
| LG Electronics |
| Rheem Manufacturing |
| Others |
Supply Flow & Price Mechanics
AIM Act refrigerant mandates are compressing equipment replacement timelines and forcing buyers to absorb redesign costs for A2L-compatible systems, which suppliers must recoup through adjusted pricing structures across chiller and rooftop unit portfolios.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium-tier OEMs from unbundled competitors in the chiller segment. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and magnetic-bearing technology inclusion. Cost compression in standardized rooftop units is intensifying because copper and aluminum input volatility erodes margins on material-heavy coil assemblies. Budget-constrained school districts exhibit highest price sensitivity, while hospital networks prioritize lifecycle operating costs over first cost.
Supply Chain Analysis
Dual-sourcing requirements for scroll and screw compressors are now standard procurement policy among North American OEMs seeking to mitigate geographic concentration risk. Manufacturing draws from eastern China, Thailand, and Japan for compressor production, with coil fabrication tethered to Chinese and Thai aluminum finstock supply. Single-source vulnerability concentrates in Los Angeles and Vancouver port gateways handling just-in-time component flows. Distribution runs through manufacturer-direct channels for large-tonnage chillers and authorized distributor networks for standardized packaged equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where magnetic-bearing centrifugal compressors are displacing conventional oil-lubricated designs across hospital and data center specifications.
For Market Incumbents: Cement control over inverter-driven component supply to defend margin position against refrigerant transition cost inflation. Prioritize backward integration into compressor design for chiller lines while accelerating R-454B qualification programs ahead of EPA deadlines. Lock in long-term service contracts for magnetic-bearing installations to capture recurring revenue from specialized maintenance requirements.
For New Entrants and Emerging Players: Independent building automation integrators represent the most accessible channel partner type for penetrating controls-convergence opportunities. Target warehouse fulfillment centers in Sun Belt markets where fast-install rooftop unit demand outstacks established OEM capacity. Lead with subscription-based energy management services to bypass capital-intensive equipment manufacturing barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with controls-integrated solution providers given building automation convergence accelerating recurring revenue multiples. Five-to-ten year viability favors firms with captive inverter electronics supply and pre-certified A2L equipment portfolios. Monitor EPA refrigerant phasedown enforcement intensity as the signal to watch for replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| A2L Refrigerant Qualification Program | EPA AIM Act compliance secures market access for rooftop and chiller product lines. |
| Magnetic-Bearing Centrifugal Platform Expansion | Hospital network specifications in Cleveland and Rochester anchor premium positioning. |
| Building Automation Integration Partnership | BACnet/IP and MQTT protocol adoption enables subscription-based energy services. |
| Inverter Electronics Supply Chain Control | Daikin Industries demonstrates margin defense through captive component production. |
| Cold-Climate Heat Pump Product Launch | Minnesota and Wisconsin K-12 retrofits displace gas-fired boiler infrastructure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with HVAC OEM procurement directors, contractor service managers, building automation integrators, and facility engineering leads. AHRI certification directories, EPA Section 608 technician databases, DOE Federal Register rulemakings, and ASHRAE Standard 90.1 adoption tracking provided validation benchmarks. Bottom-up equipment shipment analysis and top-down construction spending triangulation cross-checked market sizing across the projection horizon.
Granularity-level modeling distinguished magnetic-bearing from conventional chiller architectures, variable refrigerant flow from ductless configurations, and A2L-compatible from legacy refrigerant equipment categories. CAGRs were derived from replacement cycle acceleration curves and efficiency tier reset timing across hospital, data center, educational, and warehouse end-use segments. Input assumptions incorporated copper and aluminum price elasticity, port logistics disruption scenarios, and technician certification capacity constraints.
Caveats apply where EPA enforcement intensity, refrigerant supply chain readiness, or A2L technician training bottlenecks could materially shift the outlook. Deviation in AIM Act implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
US HVAC Services Market