
 India Chillers Market | 2026-2036
India Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
India Chillers Market Insights
BIS certification under IS 14511 for unitary air-conditioners and chillers is reorganizing competitive access for imported and domestic equipment. Carrier Corporation leverages its established testing infrastructure to fast-track compliance across its India portfolio. Blue Star Limited anchors its position through captive manufacturing of reciprocating compressors at its Wada facility. Voltas Limited competes aggressively on water-cooled system bids for IT park contracts in Hyderabad and Chennai.
Chillers are industrial refrigeration machines that remove heat from liquids via vapor-compression or absorption cycles, typically achieving chilled water temperatures between 4°C and 7°C for downstream air-handling or process cooling. These systems serve as thermal backbone infrastructure for large commercial complexes, pharmaceutical cleanrooms, and data center server halls. Water-cooled centrifugal technology dominates installed base value due to superior efficiency at capacities above 500 TR, while air-cooled scroll systems capture volume growth in mid-size commercial retrofits where cooling tower space is constrained. Absorption chillers using waste heat recovery command premium positioning in captive power and chemical process applications across Gujarat's industrial corridor.
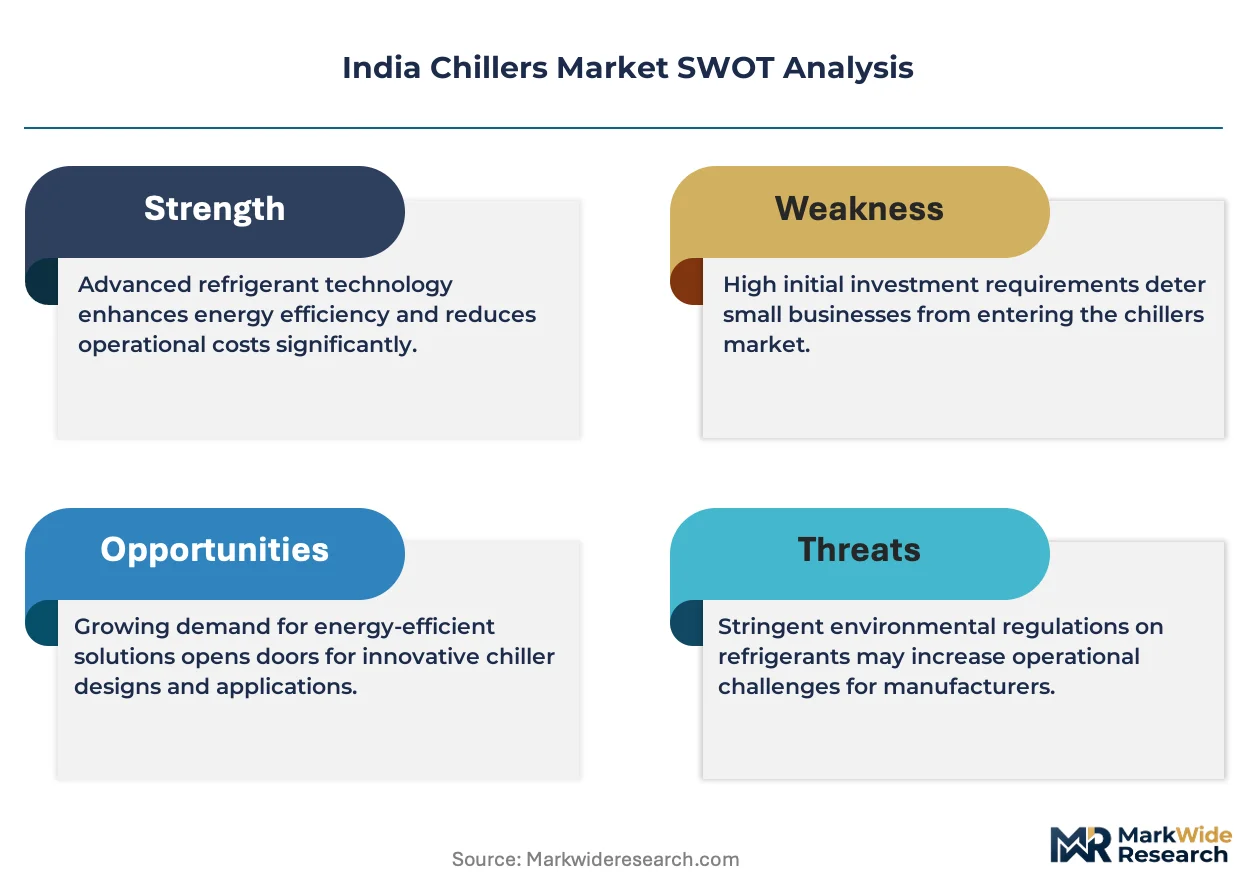
Bureau of Indian Standards efficiency mandates and Energy Conservation Building Code provisions enforced by the Bureau of Energy Efficiency are tightening minimum performance thresholds for new chiller installations. CDSCO temperature-compliance requirements for pharmaceutical manufacturing further segment demand toward precision-controlled systems with redundant compressor arrays. Stakeholders must monitor how upcoming amendments to the ECBC address district cooling integration and whether BIS expands testing protocols to cover variable-speed drive configurations in large-tonnage equipment.
Market Dynamics
BIS energy-efficiency mandates and CDSCO pharmaceutical cold-chain requirements are compressing equipment replacement cycles while concentrating procurement authority among large facility operators in Maharashtra and Gujarat.
Growth Catalysts
- ECBC enforcement in commercial construction:The Energy Conservation Building Code mandates high-efficiency chillers for new buildings above 100 kW connected load, accelerating demand in Delhi-NCR and Bengaluru IT corridors.
- Pharmaceutical cold-chain expansion:CDSCO temperature-compliance requirements for vaccine storage and active pharmaceutical ingredient manufacturing are driving precision chiller installations across Maharashtra's bulk drug clusters.
- Absorption technology adoption:Waste-heat recovery systems using lithium bromide cycles are gaining traction in Gujarat's chemical process industries with captive power generation.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials constitute 35-40% of chiller manufacturing cost, exposing domestic fabricators to London Metal Exchange commodity swings.
- Import dependence for variable-speed drives:High-capacity VFDs above 200 kW rely heavily on Chinese and German suppliers, creating supply concentration risk for centrifugal compressor manufacturers.
- Water scarcity in western states:Rajasthan and Gujarat face cooling tower make-up water restrictions that constrain water-cooled system deployment despite superior thermodynamic efficiency.
Strategic Opportunities
- Data center hyperscale builds:Noida and Hyderabad are attracting 100+ MW server hall investments requiring redundant chiller plants with N+1 compressor configurations.
- PLI scheme for white goods components:The Production Linked Incentive scheme subsidizes domestic compressor and heat exchanger manufacturing, reducing landed cost for indigenous equipment.
- Retrofit-ready scroll technology:Air-cooled scroll chillers with drop-in refrigerant compatibility are capturing replacement demand in space-constrained Mumbai commercial buildings.
Industry Challenges
- BIS testing infrastructure bottleneck:IS 14511 certification queues at NABL-accredited laboratories extend equipment launch timelines by 4-6 months for new market entrants.
- Refrigerant transition complexity:The phasedown of R-134a and R-410A under the Kigali Amendment requires simultaneous equipment redesign and technician reskilling for lower-GWP alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Chillers Market |
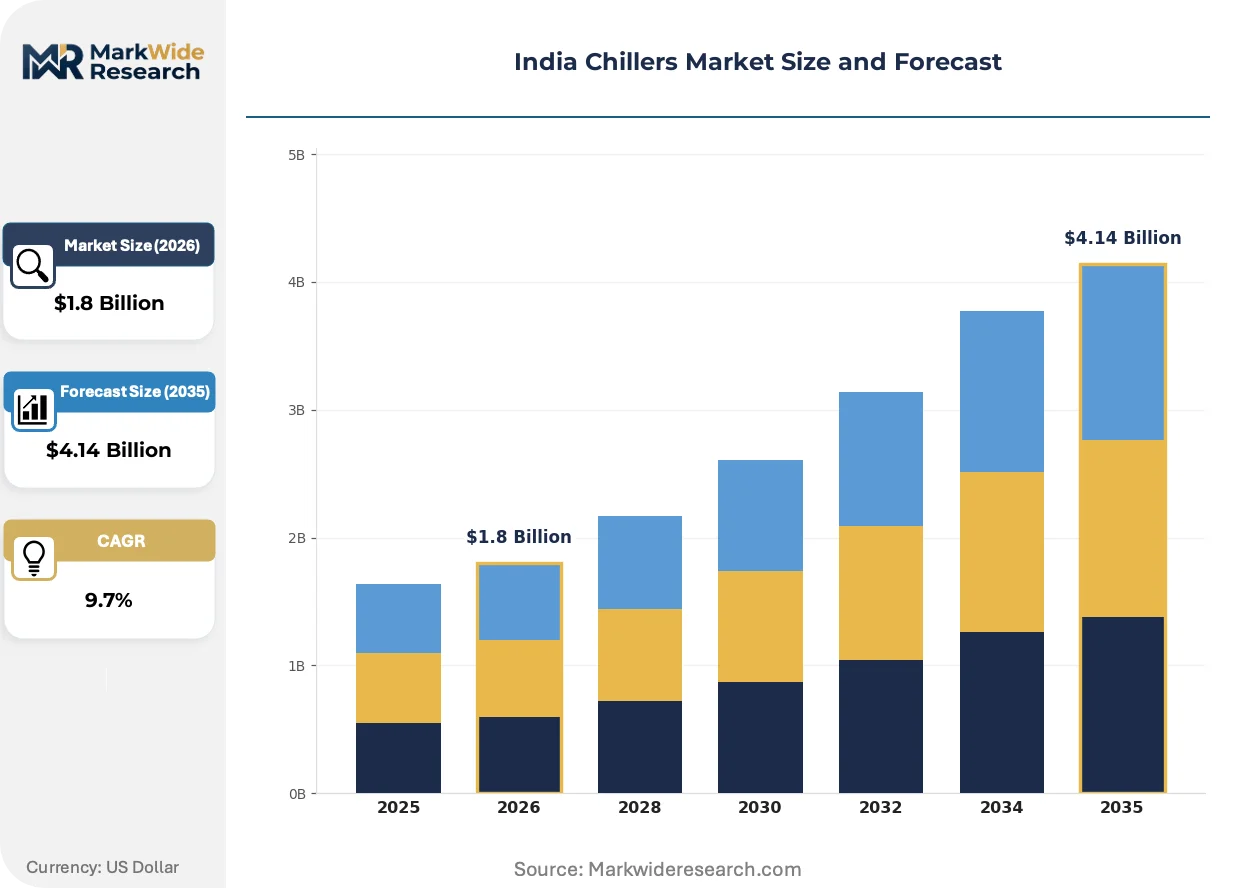
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Air-Cooled, Water-Cooled, Scroll, Reciprocating Application: Commercial Buildings, Food Processing, Pharmaceuticals, Data Centers End User: Manufacturing, Retail, Healthcare, Hospitality Technology: Centrifugal, Absorption, Vortex, Thermoelectric |
| Companies Covered | Daikin Industries Limited, Carrier Corporation, Johnson Controls International, Blue Star Limited, Voltas Limited, LG Electronics, Mitsubishi Electric India, Kirloskar Chillers, Thermax Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Chillers Market Trends and Innovations
Compressor technology architecture is fragmenting as magnetic bearing systems challenge conventional oil-lubricated designs across capacity bands, while regulatory pressure on synthetic refrigerants accelerates equipment refresh cycles.
Magnetic bearing centrifugal compressors are decomposing the traditional 500+ TR market structure previously dominated by oil-flooded designs. Data center operators in Hyderabad and Chennai specify oil-free systems for reduced maintenance intervals and elimination of lubricant contamination risks. This technology is decomposing the service revenue model for traditional chiller OEMs by extending maintenance intervals from 3,000 to 40,000 operating hours.
BIS amendments to IS 14511 are tightening integrated part load value requirements for unitary chillers above 300 kW. The revised standard mandates minimum IPLV thresholds that disqualify fixed-speed screw compressors from new commercial construction permits. Maharashtra and Gujarat facility managers are responding by specifying variable-speed centrifugal or scroll systems in tender documents.
Facility management contracts are unbundling chiller operations from bundled HVAC service agreements. Large commercial asset owners in Bengaluru and Delhi-NCR now separately procure equipment, installation, and 10-year performance contracts. This disaggregation is most visible in IT park developments where independent commissioning agents verify energy performance against design guarantees.
India Chillers Market Segmentation
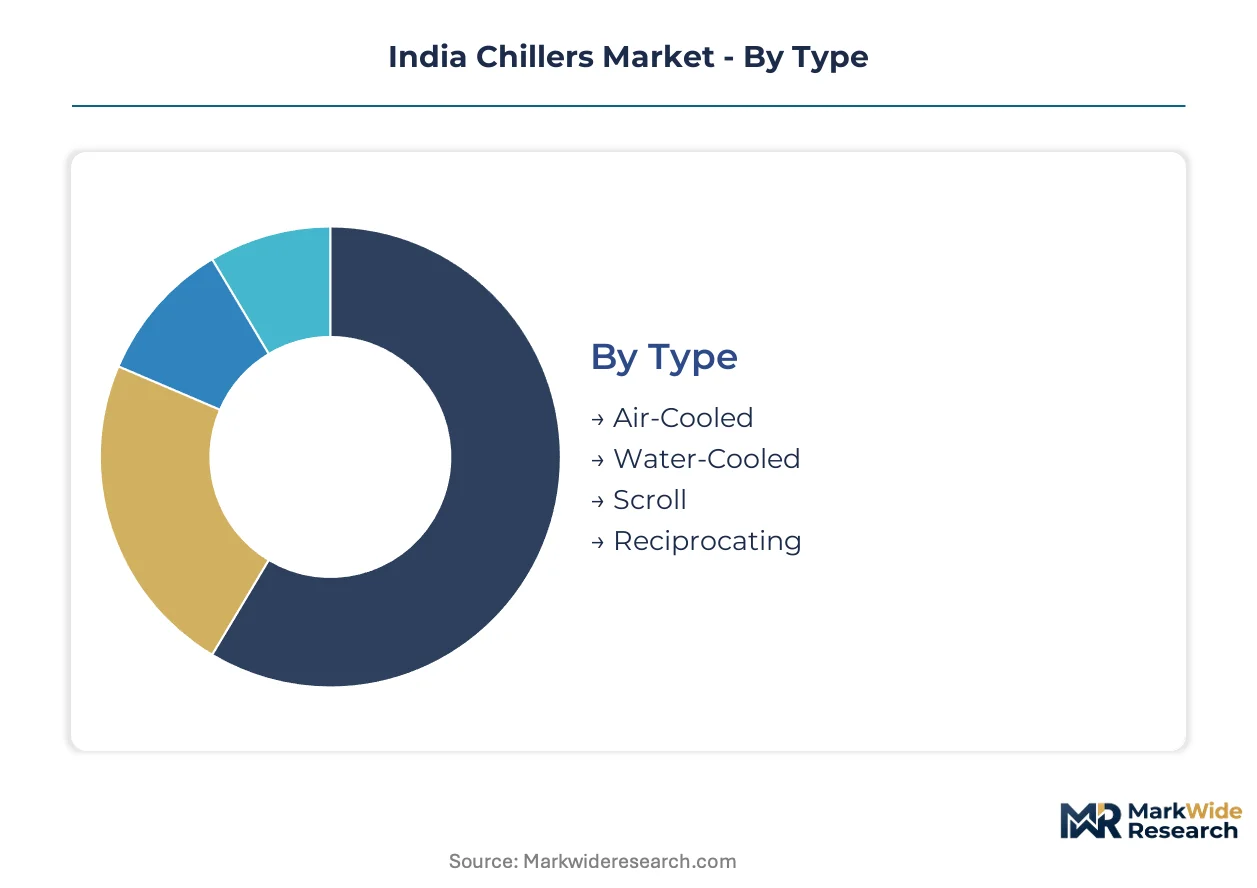
Chiller procurement patterns in India fragment sharply across cooling load requirements, regulatory exposure, and infrastructure maturity. Understanding these divides reveals where BIS mandates bite hardest and where export-oriented manufacturing creates technology arbitrage.
Type:
Domestic demand concentrates in air-cooled and water-cooled architectures, while scroll and reciprocating systems serve both indigenous replacement cycles and limited regional export into Bangladesh and Sri Lanka.
- Air-Cooled:These systems reject heat directly to ambient air through finned coils, eliminating cooling tower infrastructure. Demand clusters in Mumbai's high-rise commercial retrofits where terrace space commands premium valuations and water supply remains erratic.
- Water-Cooled:Shell-and-tube condensers paired with evaporative cooling towers deliver coefficient of performance advantages above 500 TR. Deployment concentrates in Hyderabad and Chennai data center campuses where N+1 redundancy requirements favor thermodynamic efficiency over capital minimization.
- Scroll:Hermetic orbiting scroll compressors dominate the 10-150 TR band with part-load efficiency. Gujarat pharmaceutical cleanrooms specify these for precise temperature holding within ±0.5°C bands.
- Reciprocating:Piston-driven compression survives in cost-sensitive industrial process cooling. Maharashtra small-batch chemical manufacturers maintain these for intermittent duty cycles where capital constraints override efficiency metrics.
Water-cooled systems command the established base. The steepest expansion runs through air-cooled scroll configurations.
Application:
Cost tier stratification separates precision-controlled pharmaceutical installations from price-sensitive food processing, with commercial buildings and data centers occupying intermediate positions on performance-per-rupee metrics.
- Commercial Buildings:Variable-primary flow chiller plants serve Delhi-NCR and Bengaluru IT parks. ECBC compliance mandates minimum IPLV thresholds that disqualify fixed-speed equipment from new construction permits.
- Food Processing:Ammonia-based industrial refrigeration dominates cold storage and blast freezing. Dairy cooperatives in Gujarat and Punjab favor absorption chillers where waste heat from captive power units reduces operating expenditure.
- Pharmaceuticals:CDSCO temperature-compliance requirements for vaccine storage and API manufacturing drive redundant compressor arrays. Maharashtra bulk drug clusters specify magnetic bearing centrifugal systems for elimination of oil contamination risks.
- Data Centers:Hyperscale builds in Noida and Mumbai require 2N chiller configurations with 40,000-hour maintenance intervals. Operators specify oil-free magnetic bearing technology to eliminate lubricant particulate threats to server hardware.
Commercial buildings anchor volume procurement. Pharmaceuticals generate the highest margin realization per installed ton.
End User:
Customer type determines specification authority concentration, with integrated manufacturing facilities centralizing procurement decisions while fragmented retail and hospitality operators defer to contractor recommendations.
- Manufacturing:Captive power availability shapes technology selection. Chemical process industries in Gujarat's industrial corridor specify waste-heat-fired absorption chillers where steam turbine exhaust delivers free thermal input.
- Retail:Shopping mall operators in Bengaluru and Mumbai prioritize rapid installation and compact footprints. Air-cooled scroll systems with drop-in refrigerant compatibility dominate replacement cycles.
- Healthcare:Hospital accreditation standards mandate redundant cooling for operating theaters and imaging suites. Delhi-NCR medical infrastructure specifies dual-compressor plants with automatic failover protocols.
- Hospitality:Star-rated hotels balance guest comfort against energy benchmarking requirements. Variable-speed centrifugal systems with building automation integration capture premium property new builds.
Manufacturing absorbs the largest single-facility capacities. Healthcare demonstrates the most inelastic demand for redundancy premiums.
Technology:
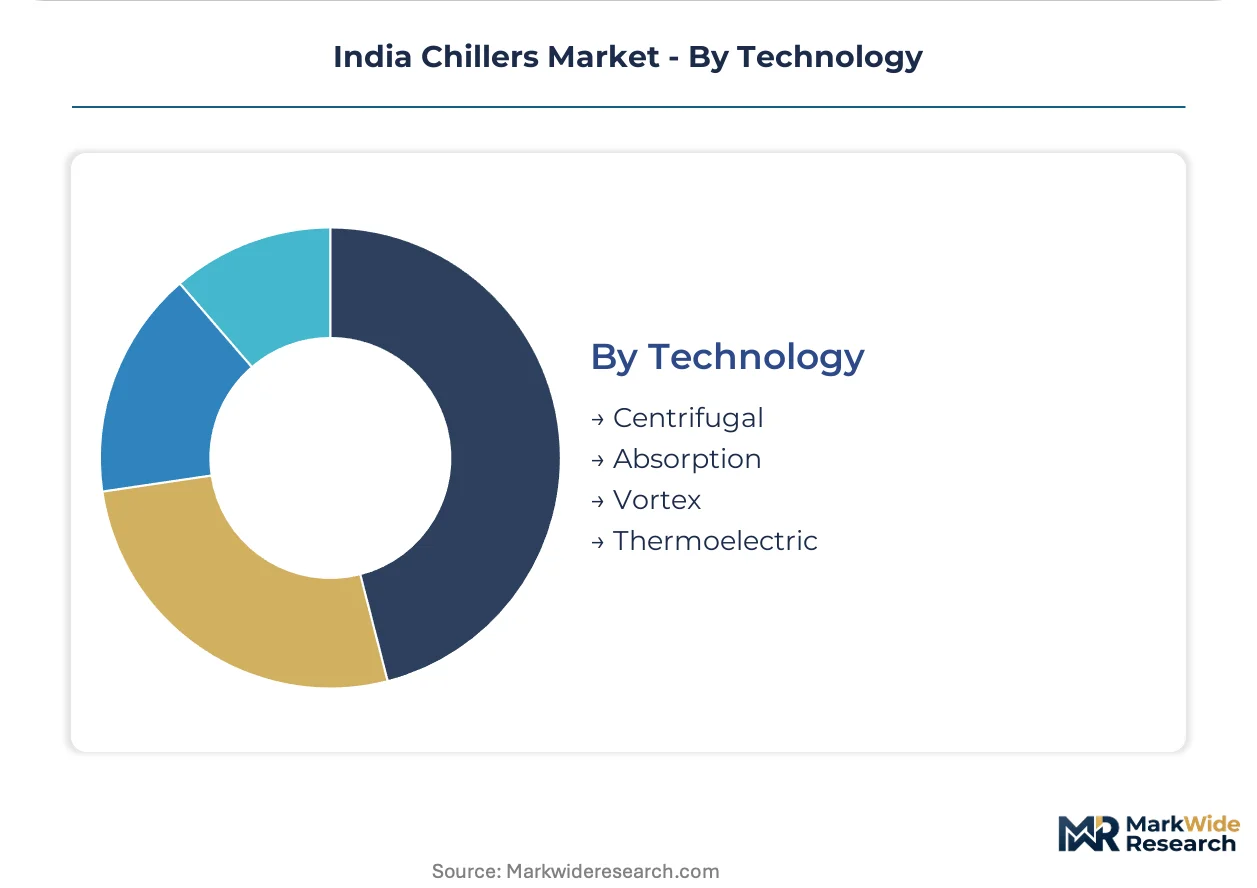
Supply concentration varies dramatically by thermodynamic cycle, with centrifugal and absorption technologies dominated by established domestic OEMs while vortex and thermoelectric remain import-dependent niche solutions.
- Centrifugal:Dynamic compression using impeller acceleration achieves highest efficiency above 300 TR. BIS amendments to IS 14511 are disqualifying fixed-speed designs from new commercial permits.
- Absorption:Lithium bromide-water cycles convert waste heat into cooling without electrical compression. Gujarat chemical manufacturers with captive cogen plants deploy these for operating cost arbitrage against grid-powered alternatives.
- Vortex:Compressed air expansion through tangential nozzles creates cooling without refrigerants. Limited deployment in hazardous environment applications where synthetic working fluids face prohibition.
- Thermoelectric:Peltier-effect solid-state cooling achieves precise temperature control in small capacities. Laboratory and semiconductor cleanroom applications in Bengaluru specify these for vibration-free operation.
Centrifugal technology anchors the revenue base. Absorption systems are climbing fastest on waste-heat recovery economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility operators in Maharashtra and Gujarat concentrate procurement authority for large-tonnage equipment, while Delhi-NCR and Bengaluru IT corridors drive mid-capacity commercial retrofits. BIS certification queues and CDSCO temperature mandates reshape competitive access across state boundaries.
Maharashtra
Pharmaceutical bulk drug clusters in Mumbai and Pune specify redundant compressor arrays for API manufacturing. CDSCO temperature-compliance requirements drive precision chiller installations with ±0.5°C control bands. Small-batch chemical manufacturers in Thane maintain reciprocating systems for intermittent duty cycles.
Gujarat
Chemical process industries with captive cogen plants deploy waste-heat-fired absorption chillers for operating cost arbitrage. Dairies in Anand and Vadodara favor lithium bromide cycles where steam turbine exhaust delivers free thermal input. Water scarcity constraints restrict cooling tower make-up for water-cooled centrifugal deployments.
Delhi-NCR
ECBC enforcement mandates high-efficiency chillers for new commercial construction above 100 kW connected load. Variable-primary flow chiller plants serve Gurgaon and Noida IT parks with minimum IPLV thresholds. Hospital accreditation standards in the capital drive dual-compressor plants with automatic failover for operating theaters.
Karnataka
Bengaluru IT corridors accelerate demand for air-cooled scroll systems in space-constrained high-rise retrofits. Independent commissioning agents verify energy performance against design guarantees in unbundled facility contracts. Magnetic bearing centrifugal systems penetrate data center specifications for 40,000-hour maintenance intervals.
Telangana
Hyperscale data center builds in Hyderabad require 2N chiller configurations with oil-free magnetic bearing technology. Water-cooled centrifugal systems dominate campus deployments where N+1 redundancy requirements favor thermodynamic efficiency. PLI scheme subsidies for compressor manufacturing reduce landed costs for indigenous equipment procurement.
India Chillers Market Competitive Landscape
Player mix skews toward diversified HVAC conglomerates with captive compressor manufacturing and specialized industrial refrigeration firms with absorption technology expertise. Market structure exhibits tiered consolidation with established domestic OEMs controlling centrifugal and absorption segments while multinational corporations compete on magnetic bearing and variable-speed drive platforms. Two strategic archetypes dominate: integrated manufacturers with backward integration into compressor fabrication, and technology licensors importing magnetic bearing systems for premium data center specifications. Competitive moves center on BIS certification fast-tracking and PLI-linked capacity expansion for heat exchanger and compressor components.
Among Japan-based diversified industrial groups, Daikin Industries Limited and Mitsubishi Electric India occupy positions emphasizing refrigerant transition readiness and variable-speed compressor platforms. Domestic conglomerates Blue Star Limited and Voltas Limited exemplify the captive-manufacturing archetype through in-house reciprocating compressor production and aggressive water-cooled system bidding for IT infrastructure contracts. Carrier Corporation anchors the multinational technology tier with established testing infrastructure for IS 14511 compliance acceleration.
| Leading Market Players |
|---|
| Daikin Industries Limited |
| Carrier Corporation |
| Johnson Controls International |
| Blue Star Limited |
| Voltas Limited |
| LG Electronics |
| Mitsubishi Electric India |
| Kirloskar Chillers |
| Thermax Limited |
| Others |
Pricing and Supply Chain Analysis
Ninety-day compressor lead times from German and Chinese VFD suppliers concentrate pricing power among domestic OEMs with captive manufacturing, while copper inventory cycles of 45-60 days expose fabricators to London Metal Exchange volatility that compresses margin buffers on fixed-price contracts.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper and aluminum prices dominate equipment procurement for pharmaceutical and data center projects. Price differentiation separates BIS-certified magnetic bearing centrifugal systems from standard screw compressor alternatives, with certification grade and after-sales service bundling as primary tiering mechanisms. Pricing pressure intensifies in the mid-capacity commercial retrofit segment as air-cooled scroll manufacturers compete on drop-in refrigerant compatibility. Manufacturing end-users demonstrate highest price sensitivity due to capital constraints on intermittent duty cycles, while data center operators show lowest sensitivity given total cost of ownership priorities.
Supply Chain Analysis
Inventory cycles of 45-60 days for copper tubing and aluminum fin stock reflect just-in-time sourcing patterns from domestic metal processors. Component supply concentrates in China for variable-speed drives above 200 kW, Germany for precision magnetic bearing assemblies, and India for reciprocating compressor castings. Raw material dependencies center on copper heat exchangers, aluminum coil stock, and rare-earth elements for high-efficiency motor magnets. Single-source vulnerability for high-capacity VFDs creates procurement risk for centrifugal chiller manufacturers. Distribution runs through authorized dealer networks serving regional contractor markets, with direct OEM engagement for large-tonnage pharmaceutical and data center specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as unbundled facility management contracts separate equipment procurement from performance guarantees, creating interoperability requirements between chiller controls and building automation systems.
For Market Incumbents: Shield market position through captive compressor manufacturing expansion under PLI scheme subsidies and accelerated BIS certification infrastructure investment. Magnetic bearing technology licensors threaten conventional oil-flooded centrifugal margins in data center specifications. Vertical integration into heat exchanger fabrication represents the critical defensive lever against commodity price volatility. For New Entrants and Emerging Players: Aftermarket service gaps in magnetic bearing maintenance present white-space opportunity where incumbent OEMs under-serve with 40,000-hour interval promises. Pharmaceutical cleanroom retrofits in Maharashtra offer most penetrable entry point given CDSCO compliance complexity and specification fragmentation. Target independent commissioning agent relationships as primary go-to-market angle for performance-guaranteed contracts. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because BIS efficiency mandates and refrigerant transition timelines force equipment replacement cycles regardless of macroeconomic conditions. Acquisition targets should demonstrate captive compressor manufacturing or established magnetic bearing technology licensing. Monitor PLI scheme amendment announcements for component subsidy expansion as inflection signal for domestic manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | PLI scheme subsidies reduce landed costs for indigenous reciprocating and scroll compressor production. |
| Magnetic Bearing Technology Licensing | Oil-free centrifugal systems capture data center specifications with 40,000-hour maintenance intervals. |
| BIS Certification Infrastructure Expansion | NABL-accredited laboratory capacity eliminates 4-6 month launch delays for new market entrants. |
| Refrigerant Transition R&D Investment | Lower-GWP alternative compatibility future-proofs equipment against Kigali Amendment phasedown schedules. |
| Performance Contracting Capability Buildout | Unbundled facility management contracts separate equipment procurement from 10-year energy guarantee verification. |
Research Methodology
A standing panel of plant engineers, HVAC contractor procurement heads, pharmaceutical facility managers, and data center operations directors provided ongoing calibration against secondary validation from BIS certification records, Bureau of Energy Efficiency ECBC compliance filings, CDSCO pharmaceutical manufacturing facility registrations, and customs import data for variable-speed drive components. Bottom-up equipment shipment analysis triangulated against top-down construction permit flows for commercial buildings above 100 kW connected load.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated chiller type, cooling capacity tier, application vertical, end-user category, and technology cycle dimensions. CAGRs derived from regression analysis of historical shipment patterns against regulatory enforcement timelines and construction pipeline data. Forecast inputs included PLI scheme subsidy disbursement trajectories and refrigerant phasedown schedule compliance assumptions.
Underlying assumptions cover BIS amendment implementation timelines and copper price band stability, with deviation risk concentrated in water scarcity restrictions affecting western state deployment and VFD supply concentration from Chinese suppliers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Europe Ventilation Equipment Market