
 Air-Cooled Heat Exchangers Market | 2026-2036
Air-Cooled Heat Exchangers Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Cooled Heat Exchangers Market Analysis
Data center operators is redrawing procurement priorities for air-cooled heat exchangers as hyperscale facilities prioritize dry-cooling to reduce water consumption. SPX Cooling Tech leverages its induced-draft technology portfolio to capture utility-scale power generation contracts across the southwestern United States. Kelvion Holding GmbH anchors its position through specialized aluminum fin manufacturing that serves European chemical processing complexes. Thermax competes aggressively in hybrid cooling configurations for Indian refineries seeking to reduce freshwater withdrawal rates.
An air-cooled heat exchanger transfers thermal energy between a process fluid and ambient air without evaporative water loss, typically employing extended aluminum or copper fin surfaces bonded to carbon steel or stainless steel tubes to achieve heat transfer coefficients of 50-150 W/m²K depending on fin geometry and air velocity. Its primary industrial purpose is to condense or cool process streams in locations where water scarcity, environmental discharge restrictions, or freezing conditions preclude wet cooling tower operation. Fin fan configurations dominate installed base volumes across power generation applications where large heat rejection duties and outdoor installation tolerances align with the technology's economic profile. Shell and tube variants command premium positioning in oil and gas processing where API 661 compliance and high-pressure containment requirements justify thicker wall constructions and specialized metallurgy. Plate-type air-cooled designs represent the fastest-growing product category in food and beverage applications, driven by hygienic design standards and clean-in-place compatibility that reduce microbial contamination risks.
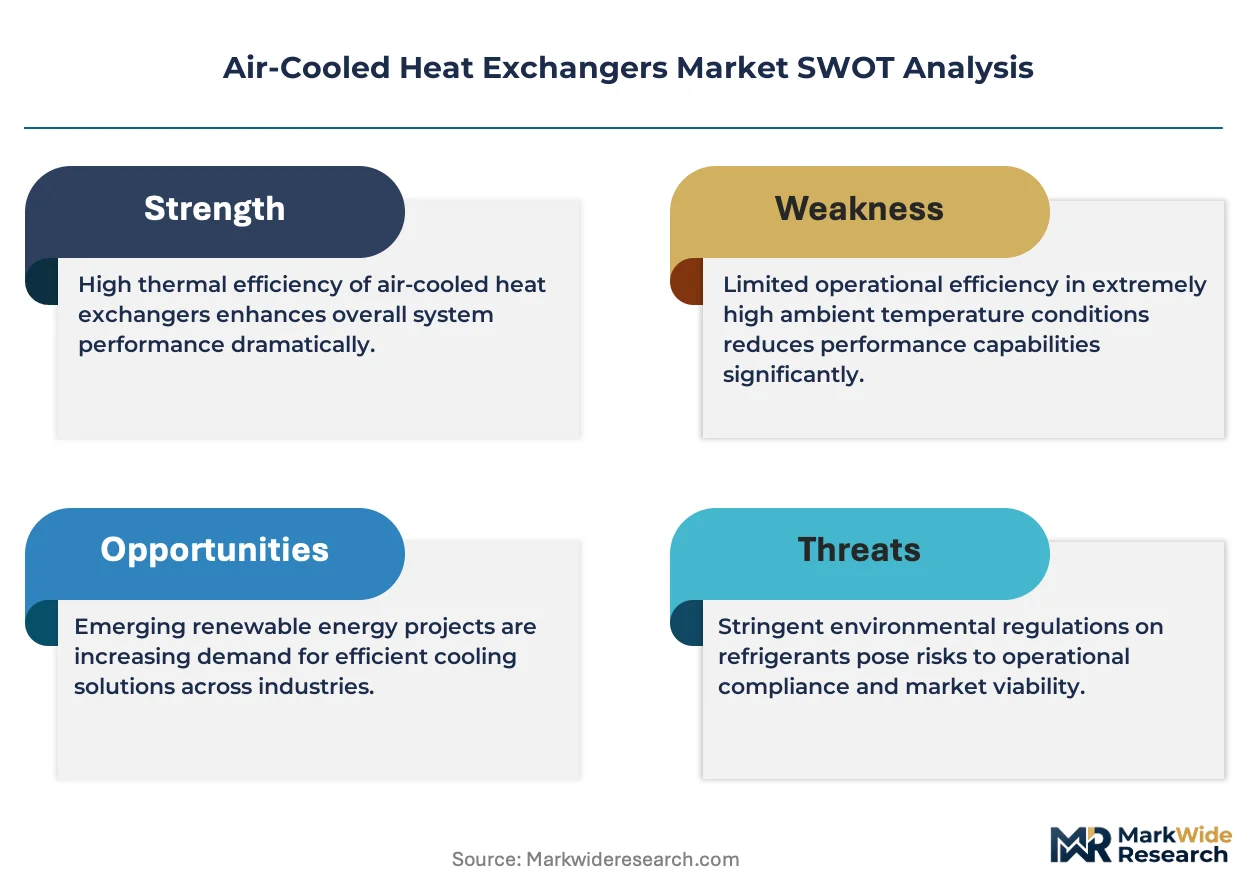
The EPA enforces refrigerant management rules under Section 608 of the Clean Air Act that constrain hydrofluorocarbon use in industrial cooling systems, while OSHA's Process Safety Management standard governs ammonia charge quantities in air-cooled installations serving chemical processing facilities. The Department of Energy's appliance efficiency regulations and FERC interconnection standards for generator cooling systems collectively shape equipment specification requirements and market access conditions for domestic manufacturers. Stakeholders must monitor evolving state-level water use restrictions and carbon border adjustment mechanisms to anticipate where dry-cooling retrofits will displace existing evaporative infrastructure.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is redirecting capital toward ammonia and CO2-based air-cooled architectures, compressing equipment replacement cycles across petrochemical and power generation installations.
Growth Catalysts
- AIM Act refrigerant mandates:The EPA's hydrofluorocarbon phasedown forces industrial operators to retrofit existing cooling infrastructure with ammonia or CO2-based air-cooled systems, accelerating replacement demand in Texas petrochemical corridors.
- Data center dry-cooling pivot:Hyperscale facility operators prioritize air-cooled heat exchangers to eliminate water consumption from thermal management, creating procurement pull for induced-draft and fin-fan configurations in arid southwestern states.
- Aluminum fin bonding advances:Improved mechanical and brazed fin-to-tube attachment techniques extend thermal performance envelopes, enabling wider deployment in high-temperature refinery applications previously reserved for shell-and-tube designs.
Market Restraints
- Copper and aluminum price volatility:Extended fin surfaces require significant non-ferrous metal volumes, exposing manufacturers to London Metal Exchange commodity swings that compress margin predictability on fixed-price contracts.
- API 661 compliance burden:Oil and gas processing specifications mandate thick-wall constructions and specialized metallurgy that extend engineering lead times and limit supplier pools to certified fabricators.
- Evaporative cooling cost advantage:Wet cooling towers maintain lower first-cost positions in water-available locations, constraining air-cooled penetration in budget-sensitive industrial brownfield retrofits.
Strategic Opportunities
- Hybrid cooling configurations:Indian refineries under freshwater withdrawal pressure adopt air-cooled/wet-cooled hybrid systems, opening design-engineering contracts for thermal optimization specialists.
- Plate-type hygienic designs:Food and beverage processors demand clean-in-place compatible air-cooled units with reduced microbial harborage points, creating premium positioning for welded-plate architectures.
- Carbon border adjustment preparation:European chemical complexes facing EU carbon border mechanisms accelerate dry-cooling retrofits to reduce Scope 2 emissions intensity ahead of compliance deadlines.
Industry Challenges
- Ammonia refrigeration specialist shortage:OSHA Process Safety Management requirements for ammonia-charged systems exceed available certified technician supply, extending commissioning timelines and inflating service rates.
- Legacy control system integration:Digital twin and predictive maintenance overlays must interface with decades-old SCADA architectures in existing petrochemical installations, multiplying engineering complexity.
- ISO 5149 certification timelines:Refrigeration safety standard compliance for CO2 transcritical systems requires extended testing protocols that delay product commercialization versus conventional HFC equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Cooled Heat Exchangers Market |
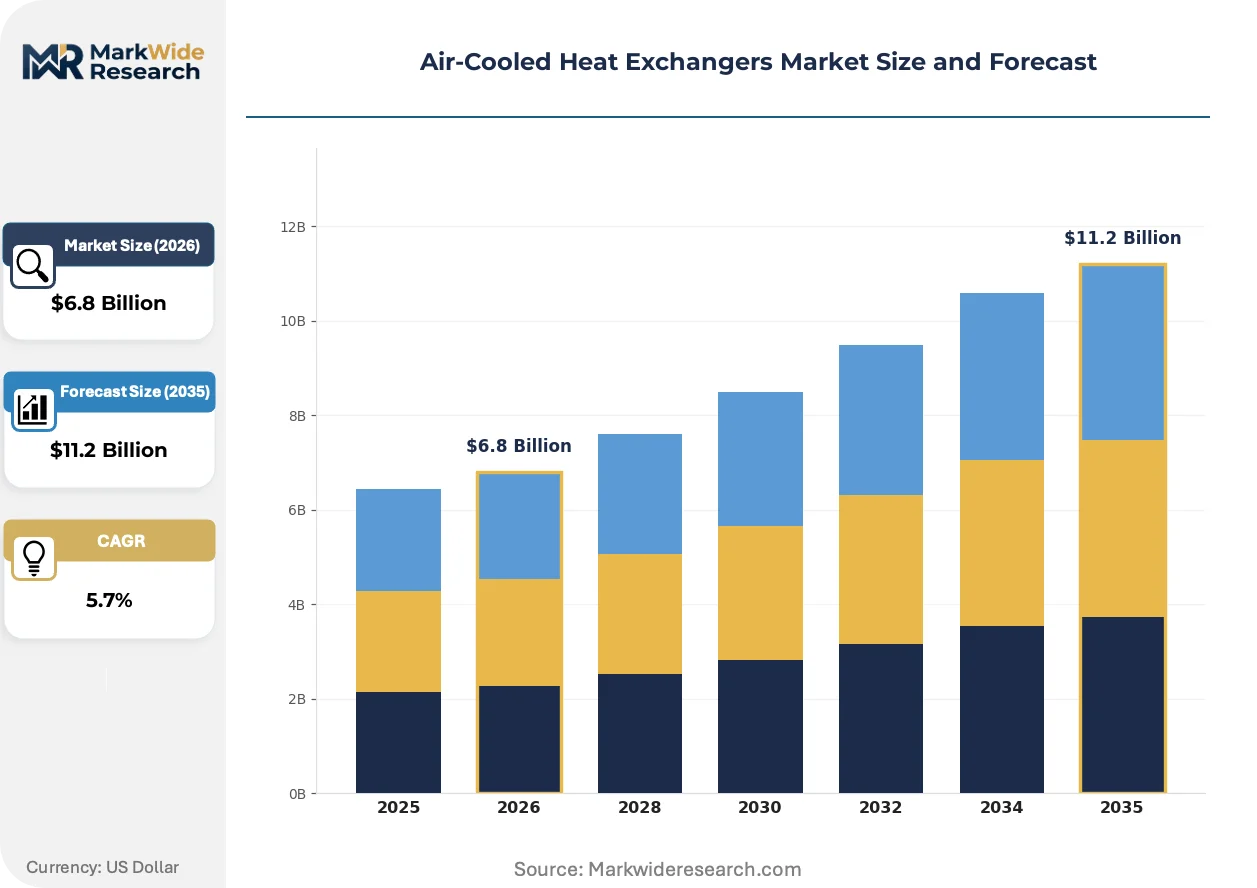
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fin Fan, Double Pipe, Shell and Tube, Plate Application: Power Generation, Chemical Processing, Food and Beverage, HVAC End User: Manufacturing, Oil and Gas, Pharmaceuticals, Mining Technology: Air-Cooled, Hybrid, Induced Draft, Forced Draft |
| Companies Covered | ALFA LAVAL, SPX Cooling Tech, Kelvion Holding GmbH, Exchanger Industries, Chart Industries, Kawasaki Heavy Industries, Thermax, SPG Dry Cooling, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Cooled Heat Exchangers Market Emerging Trajectories
Equipment architectures are bifurcating between standardized modular platforms for utility-scale deployment and application-engineered systems for process-critical installations, with digitalization penetrating both categories unevenly.
Microchannel aluminum coil technology is fragmenting the conventional round-tube plate-fin segment. Data center operators in Nevada and Arizona specify microchannel coils for their reduced refrigerant charge volumes and improved air-side heat transfer coefficients. The technology is fragmenting supplier hierarchies by enabling new entrants to bypass traditional tube mill relationships.
The EU F-Gas Regulation's quota reductions are compressing HFC availability for industrial cooling. European chemical processors face accelerated obsolescence of existing refrigeration-based heat rejection systems. Air-cooled ammonia and CO2 installations are capturing retrofit share in Germany's Ruhr industrial cluster and Rotterdam's port complexes.
Equipment-as-service contracting is displacing capital purchase models among independent power producers. Third-party thermal specialists assume operational risk for heat rejection performance, unbundling hardware supply from lifecycle optimization. Texas merchant power developers exhibit strongest appetite for outcome-based arrangements tied to guaranteed output availability.
Air-Cooled Heat Exchangers Market Segmentation
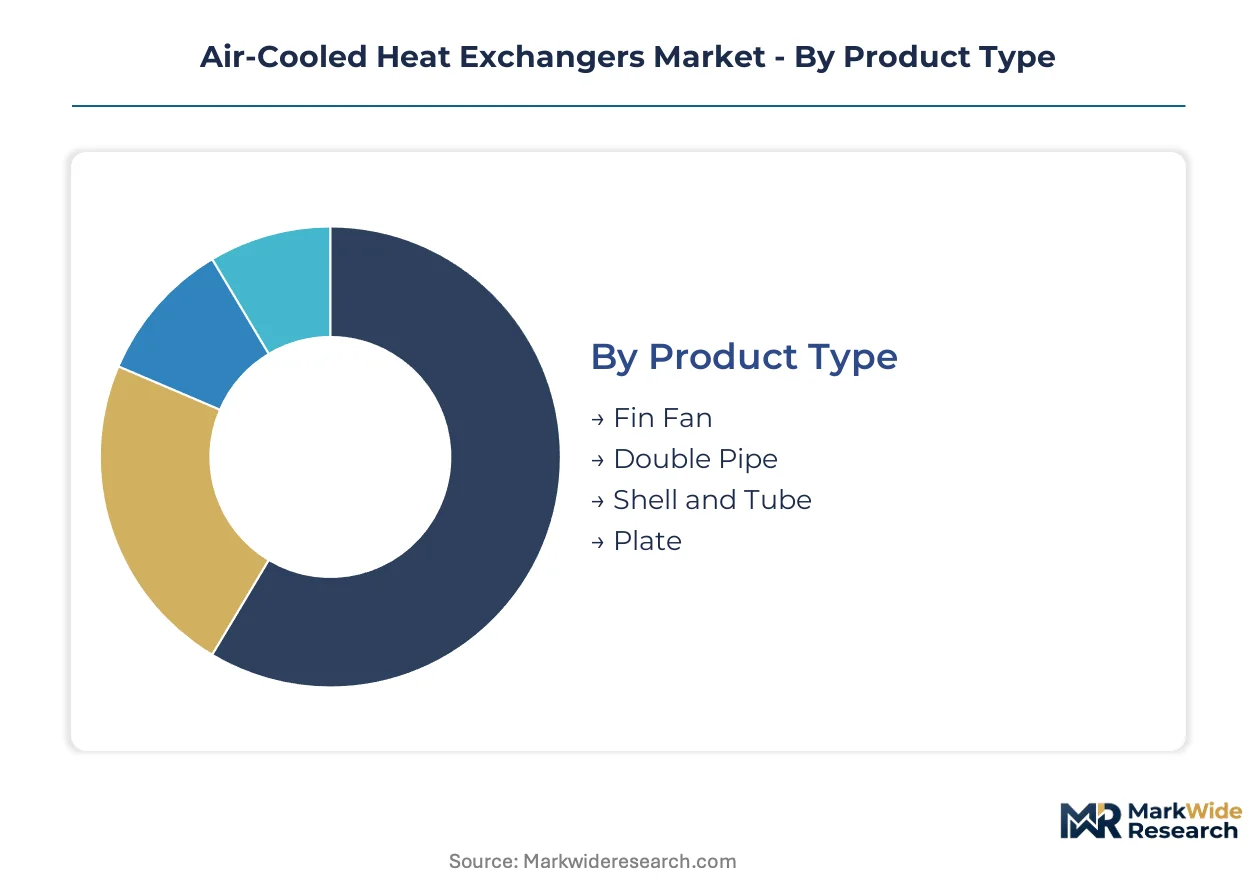
Air-cooled heat exchanger procurement patterns diverge sharply across product architectures and end-use requirements. Equipment specification priorities in Texas petrochemical corridors differ fundamentally from data center operator preferences in Nevada and Arizona. Understanding these segment boundaries clarifies where technology investments concentrate versus where cost minimization dominates purchasing decisions.
Product Type:
Fin fan configurations anchor domestic manufacturing volumes while plate-type systems drive export-led expansion into European food processing and Asian pharmaceutical installations.
- Fin Fan:Extended aluminum or copper fin surfaces bonded to carbon steel tubes achieve heat transfer coefficients of 50-150 W/m²K. Texas power generators and petrochemical operators absorb the majority of induced-draft and forced-draft fin fan production for large heat rejection duties in outdoor installations.
- Shell and Tube:Thick-wall constructions with specialized metallurgy satisfy API 661 compliance requirements for high-pressure containment. Oil and gas processing facilities in the Permian Basin and Gulf Coast corridors specify these units despite premium pricing and extended engineering lead times.
- Double Pipe:Compact annular configurations serve low-duty thermal management in remote mining operations and small-scale chemical processing where footprint constraints outweigh efficiency optimization.
- Plate:Welded-plate architectures with clean-in-place compatibility address hygienic design standards in food and beverage applications. European dairy processors and North American beverage manufacturers drive specification pull for reduced microbial harborage designs.
Fin fan configurations command the established base across power generation and petrochemical installations. The steepest expansion runs through plate-type systems gaining share in food processing and pharmaceutical cleanroom applications.
Application:
Power generation and chemical processing absorb high-margin engineered systems while HVAC and food and beverage procurement gravitates toward standardized modular platforms with shorter delivery cycles.
- Power Generation:Utility-scale merchant power developers in Texas and the southwestern United States specify air-cooled condensers and auxiliary cooling systems to eliminate water consumption from thermal cycles. FERC interconnection standards for generator cooling systems shape equipment specifications and supplier qualification requirements.
- Chemical Processing:Petrochemical complexes facing EPA hydrofluorocarbon phasedown mandates under the AIM Act accelerate ammonia and CO2-based air-cooled retrofits. OSHA Process Safety Management standards govern ammonia charge quantities and technician certification requirements.
- Food and Beverage:Dairy processors and beverage manufacturers prioritize hygienic plate-type designs with reduced cleaning cycle downtime. Clean-in-place compatibility reduces microbial contamination risks in FDA-regulated facilities.
- HVAC:Commercial building operators in water-scarce municipalities specify dry-cooling systems to comply with evolving municipal water use restrictions and avoid cooling tower maintenance burdens.
Power generation retains the largest installed capacity. Food and beverage applications are climbing the fastest as hygienic design standards penetrate mid-tier processing facilities.
End User:
Oil and gas and manufacturing end users dominate capital expenditure cycles while pharmaceutical and mining procurement exhibits more sporadic project-driven demand patterns.
- Oil and Gas:Upstream production facilities and midstream gas processing plants specify API 661 compliant shell and tube configurations for high-pressure hydrocarbon condensation. Permian Basin expansion and Gulf Coast LNG export projects concentrate demand for specialized metallurgy and thick-wall constructions.
- Manufacturing:Discrete manufacturing and process industries deploy fin fan and hybrid cooling systems for compressor intercooling and lubrication oil temperature control. Automotive and steel production facilities in the industrial Midwest represent steady replacement demand.
- Pharmaceuticals:FDA-regulated active pharmaceutical ingredient manufacturing requires validated thermal management systems with extensive documentation packages. Cleanroom-compatible plate-type units address stringent particulate and microbial control requirements.
- Mining:Remote extraction operations prioritize ruggedized double pipe and compact fin fan configurations for mobile crushing and processing equipment where water availability is limited and maintenance access is constrained.
Manufacturing commands the broadest installed footprint. The oil and gas segment shows the steepest near-term expansion tied to Permian Basin production growth and LNG export capacity additions.
Technology:
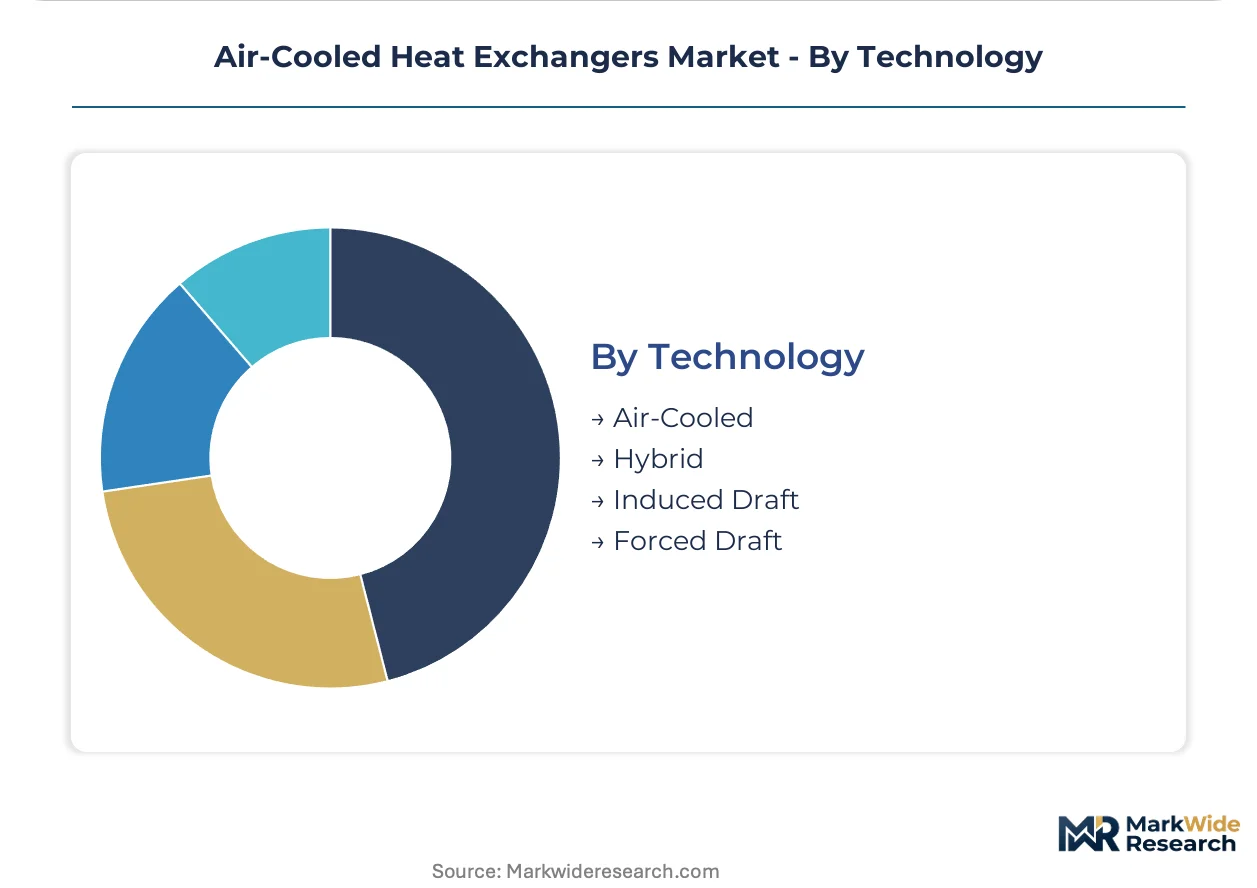
Air-cooled and induced draft systems anchor established procurement patterns while hybrid configurations gain traction in water-stressed jurisdictions and forced draft architectures penetrate cost-sensitive HVAC applications.
- Air-Cooled:Direct dry-cooling systems eliminate evaporative water loss entirely through extended surface heat transfer to ambient air. Data center operators in Nevada, Arizona, and New Mexico specify these architectures to achieve zero water consumption from thermal management.
- Induced Draft:Axial fans mounted above tube bundles draw air upward through finned surfaces, enabling uniform air distribution and reduced recirculation risk. SPX Cooling Tech and established suppliers capture utility-scale power generation contracts across the southwestern United States with this configuration.
- Hybrid:Combined air-cooled and wet-cooled systems optimize water consumption against thermal performance in variable ambient conditions. Indian refineries under freshwater withdrawal pressure adopt these configurations to reduce intake volumes while maintaining output reliability during peak summer conditions.
- Forced Draft:Blower-mounted configurations positioned below tube bundles offer lower first-cost positions and simplified maintenance access. Budget-sensitive commercial HVAC installations and industrial brownfield retrofits specify forced draft where water scarcity does not justify induced draft premiums.
Induced draft technology commands the established base across power generation and chemical processing. Hybrid configurations are gaining share fastest as water stress intensifies across multiple industrial geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial equipment exports flow into Dutch chemical processing complexes and French food manufacturing facilities, establishing a north-south trade corridor for air-cooled heat exchanger procurement across Western Europe.
United States
Texas petrochemical corridor expansions and independent power project buildouts absorb record volumes of fin-fan and induced-draft units. EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act redirects investment toward ammonia and CO2-based architectures. Data center operators in Nevada and Arizona specify dry-cooling systems to eliminate water consumption from thermal management.
Germany
Ruhr industrial cluster chemical processors face accelerated obsolescence of existing refrigeration-based heat rejection systems. EU F-Gas Regulation quota reductions compress HFC availability for industrial cooling. Air-cooled ammonia and CO2 installations capture retrofit share in Rotterdam's port complexes and Germany's chemical processing heartland.
India
Refineries under freshwater withdrawal pressure adopt hybrid cooling configurations to reduce intake volumes while maintaining output reliability. Central Electricity Authority guidelines shape thermal optimization requirements for power sector installations. Maharashtra and Gujarat industrial corridors drive specification pull for air-cooled condensers in merchant power developments.
China
Dual carbon goals and water scarcity policies in northern provinces accelerate dry-cooling retrofits in coal-fired power stations and steel production facilities. Ministry of Ecology and Environment discharge restrictions constrain wet cooling tower operation in Yellow River basin industrial zones. Shandong Peninsula chemical complexes specify extended surface heat transfer equipment for process stream condensation.
United Arab Emirates
Desalination-integrated power projects and aluminum smelting facilities prioritize air-cooled architectures to minimize freshwater consumption in arid conditions. Dubai and Abu Dhabi municipal water use restrictions shape equipment specifications for commercial and industrial cooling applications. NEOM Northwest development incorporates dry-cooling infrastructure for renewable energy integration.
Air-Cooled Heat Exchangers Market Vendor Landscape
Player mix skews toward diversified thermal engineering conglomerates with cross-sector cooling portfolios, creating a tiered structure where specialized fabricators compete on API certification against integrated process technology providers. Three archetypes dominate: European precision-engineering specialists with aluminum fin manufacturing depth, North American utility-scale power generation contractors, and Asian integrated industrial equipment conglomerates. Competitive moves concentrate on hybrid cooling configuration engineering partnerships and ammonia refrigeration system safety certification acquisition.
Among European precision-engineering specialists, Kelvion Holding GmbH and SPG Dry Cooling exemplify the certified-fabricator archetype serving chemical processing compliance requirements. SPX Cooling Tech anchors North American positioning through utility-scale contracting relationships. Thermax occupies a position within Asian integrated industrial equipment supply, representing the diversified conglomerate model with refinery and power sector reach across water-stressed jurisdictions.
| Leading Market Players |
|---|
| ALFA LAVAL |
| SPX Cooling Tech |
| Kelvion Holding GmbH |
| Exchanger Industries |
| Chart Industries |
| Kawasaki Heavy Industries |
| Thermax |
| SPG Dry Cooling |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Aluminum fin-to-tube bonding techniques replacing conventional mechanical expansion methods are redrawing procurement geography toward specialized metallurgy centers while compressing margin structures for legacy fabricators dependent on commodity tube mills. This substitution dynamic concentrates pricing power with brazing technology licensees in Germany and Japan while forcing second-tier suppliers toward forced-draft configurations with thinner material specifications.
Pricing Analysis
Microchannel coil architectures command 15-25% premiums over conventional round-tube plate-fin designs due to reduced refrigerant charge requirements and improved air-side coefficients. Three-tier pricing structure across API 661 certified, ISO 5149 compliant, and uncertified economy tiers reflects engineering documentation depth and metallurgy traceability. Cost compression in standard fin-fan configurations is intensifying because Chinese aluminum extrusion capacity is flooding export markets. Merchant power developers in Texas exhibit lowest price sensitivity due to FERC-mandated reliability requirements, while commercial HVAC operators in water-scarce municipalities drive procurement toward lowest first-cost forced-draft units.
Supply Chain Analysis
China and Germany anchor aluminum fin stock and precision tube production for air-cooled heat exchanger fabrication, with India emerging as a secondary brazing alloy processing hub. Extended surface manufacturing draws from London Metal Exchange copper and aluminum contracts, specialized brazing paste formulations, and carbon steel tube from integrated mills. Single-source vulnerability concentrates in high-purity ammonia refrigeration components sourced from a limited German and Austrian supplier base. Distribution runs through EPC contractors and OEM aftermarket channels, with direct procurement growing among data center operators seeking design-engineering integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified ammonia refrigeration technician scarcity constrains commissioning velocity and inflates service margins, creating acquisition value for training-capable specialists and technology licensors with safety protocol intellectual property.
For Market Incumbents: Consolidate API 661 certification depth and ammonia PSM compliance capabilities to defend against emerging microchannel entrants bypassing traditional tube mill relationships. Acquire brazing technology licensees in Germany or Japan to secure aluminum fin bonding supply chain control. Prioritize backward integration into aluminum fin stock production to offset London Metal Exchange volatility exposure on fixed-price power generation contracts. For New Entrants and Emerging Players: Differentiate on CO2 transcritical system engineering for European chemical processors facing EU F-Gas Regulation quota compression. Target plate-type hygienic configurations in North American beverage manufacturing where clean-in-place compatibility commands premium positioning. Pursue equipment-as-service contracting models among Texas merchant power developers seeking outcome-based thermal performance guarantees. For Investors and Strategic Acquirers: EPA AIM Act hydrofluorocarbon phasedown deadlines reshape the acquisition landscape toward ammonia and CO2 refrigeration specialists with OSHA PSM certification infrastructure. Long-term viability centers on regulatory compliance capability rather than manufacturing scale alone. Monitor EPA Section 608 enforcement intensity and state-level water use restriction expansion as demand inflection signals for dry-cooling retrofit cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Fin Stock | Captive supply of extended surface material insulates margin from London Metal Exchange volatility. |
| API 661 Certification Investment | Thick-wall construction qualification opens Permian Basin and Gulf Coast oil and gas procurement channels. |
| Ammonia PSM Training Infrastructure | Certified technician pipelines address OSHA compliance bottlenecks extending commissioning timelines. |
| CO2 Transcritical System Commercialization | ISO 5149 compliance enables European retrofit capture under EU F-Gas Regulation quota reductions. |
| Equipment-as-Service Contracting | Outcome-based arrangements align revenue with merchant power availability guarantees in Texas markets. |
Methodological Framework
The analysis maps fin-fan, shell-and-tube, plate-type, and hybrid cooling configurations, each validated through plant engineers at petrochemical facilities, procurement leads at data center operators, EPC contractors, and aftermarket service heads. Primary interviews with maintenance directors and OEM procurement teams cross-reference customs data, ACC industry reports, SEC 10-K equipment disclosures, and FERC interconnection filings. Bottom-up installation tracking triangulates against top-down thermal engineering demand modeling.
Consistency checks validate volume and value outputs against EIA power sector cooling disclosures, IEA industrial efficiency benchmarks, and EPA refrigerant transition timelines across the projection horizon. Segmentation models incorporate product architecture, application intensity, end-user capital cycle timing, and regional water stress policy frameworks. CAGRs derive from equipment replacement cycle compression under AIM Act mandates and data center dry-cooling adoption curves.
Material uncertainties — aluminum and copper price volatility, EPA enforcement intensity variation, and ammonia technician certification pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory phase-in schedules and industrial water restriction diffusion patterns. Recalibration cycles align with material shifts in EPA rulemaking and state-level discharge permit restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
India Chillers Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Industrial Heating Equipment Market