
 Industrial Chiller Market | 2026-2036
Industrial Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Chiller Market Outlook
Chinese compressor manufacturing is shifting toward magnetic bearing and oil-free centrifugal platforms. Carrier Corporation leverages vertical integration across refrigerant circuits and controls to sustain pricing power in water-cooled systems. Trane Technologies anchors North American project engineering through its chiller-plant optimization software and service density.
An industrial chiller is a vapor-compression or absorption-based refrigeration system that removes process heat from liquids—typically water or glycol brine—at temperatures ranging from -40°C to +20°C, then circulates the cooled fluid through heat exchangers to stabilize manufacturing equipment, reaction vessels, or building HVAC loops. Water-cooled chillers dominate capacity installations above 500 tons where cooling tower infrastructure exists, while air-cooled units capture retrofit demand in water-scarce geographies and distributed pharmaceutical facilities. Absorption chillers, fired by waste heat or natural gas, compete where electricity tariffs spike or where industrial cogeneration plants supply thermal energy.
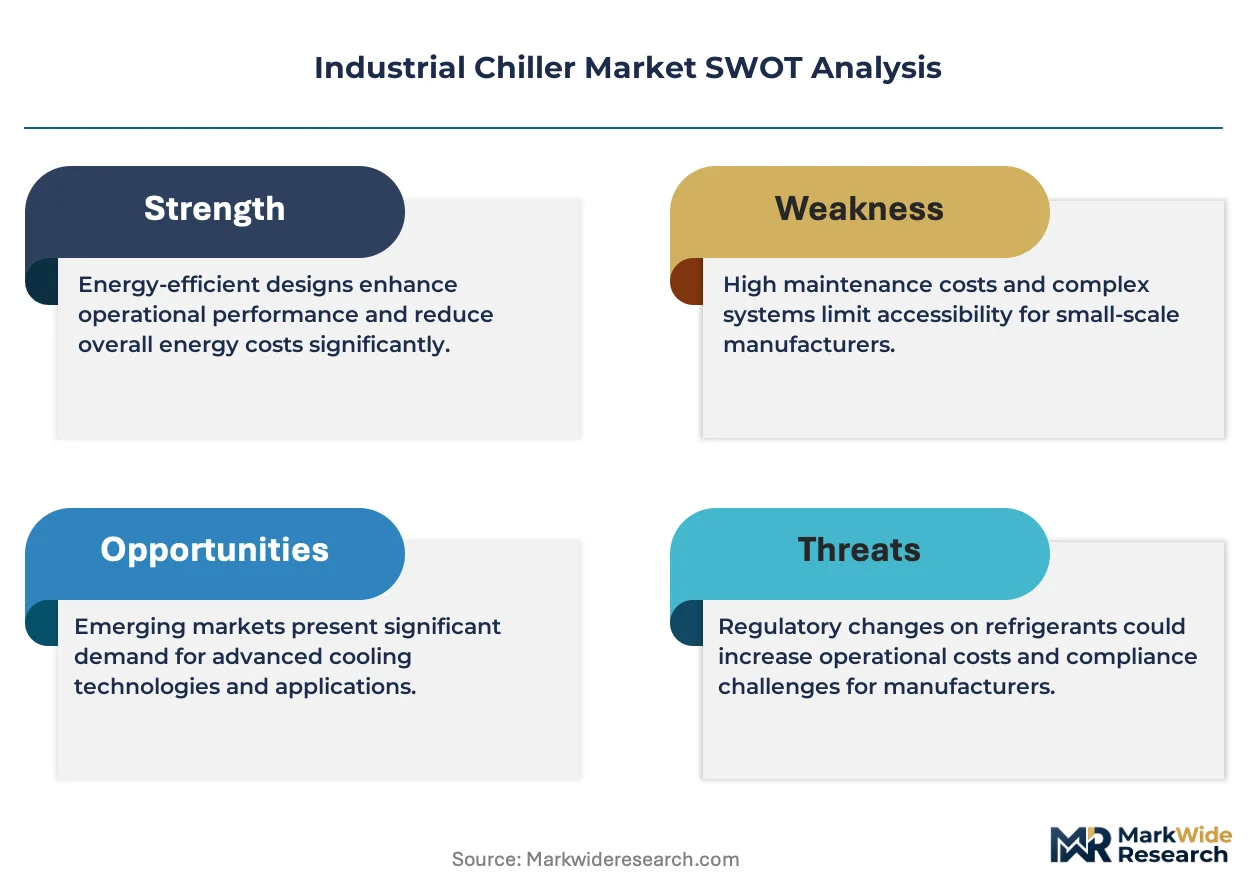
The US EPA refrigerant phasedown, the EU F-Gas Regulation, and Japan's METI energy-efficiency standards for cooling equipment are tightening allowable global warming potential thresholds and minimum performance coefficients, forcing OEMs to redesign compressor architectures and qualify alternative refrigerants before legacy products lose market access. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps that block project approvals.
Market Dynamics
The US EPA's AIM Act refrigerant phasedown is compressing product development cycles and forcing simultaneous redesign of compressor architectures, heat exchanger materials, and control electronics across the installed base.
Growth Catalysts
- Pharmaceutical precision cooling mandates:FDA temperature-validation requirements for biologics manufacturing are expanding demand for glycol-based process chillers with ±0.1°C stability across US and EU facilities.
- China's chemical processing expansion:Petrochemical clusters in Zhejiang and Shandong provinces are procuring absorption chillers to utilize waste heat from steam crackers and reduce grid electricity draw.
- F-Gas Regulation retrofit cycles:The EU's tightening GWP thresholds are accelerating replacement of R-134a and R-410A systems with R-513A and R-1234ze platforms in food processing and cold chain infrastructure.
Market Restraints
- Copper and rare-earth input volatility:Magnetic bearing motors and brazed-plate heat exchangers depend on copper and neodymium supplies concentrated in Chinese processing facilities, exposing OEMs to tariff and export-control disruptions.
- Absorption chiller technical ceiling:Coefficient of performance limitations below 1.2 thermal COP restrict absorption units to waste-heat-abundant sites, excluding them from electrified greenfield projects.
- Refrigerant certification fragmentation:Divergent EPA Significant New Alternatives Policy and EU F-Gas approval timelines create stranded inventory risk for multi-territory chiller OEMs.
Strategic Opportunities
- Data center liquid cooling convergence:Hyperscale facilities in Northern Virginia and Frankfurt are integrating industrial chillers with direct-to-chip cooling loops, opening chiller-plant-as-a-service revenue models.
- India PLI scheme for cooling equipment:Production-linked incentives for component manufacturing are attracting magnetic bearing compressor assembly to Gujarat and Tamil Nadu industrial corridors.
- Natural refrigerant technology pairing:Ammonia-based chillers with integrated leak-detection IoT are capturing cold storage retrofit demand in California and Netherlands logistics hubs ahead of carbon-border adjustments.
Industry Challenges
- Refrigerant-handling technician shortage:EPA Section 608 certification requirements for low-GWP blends lag training program deployment, extending commissioning timelines for A2L and A3 refrigerant systems.
- Legacy control system integration:BACnet and Modbus protocol mismatches between 1990s-era building management systems and modern chiller PLCs force costly middleware development for facility retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Chiller Market |
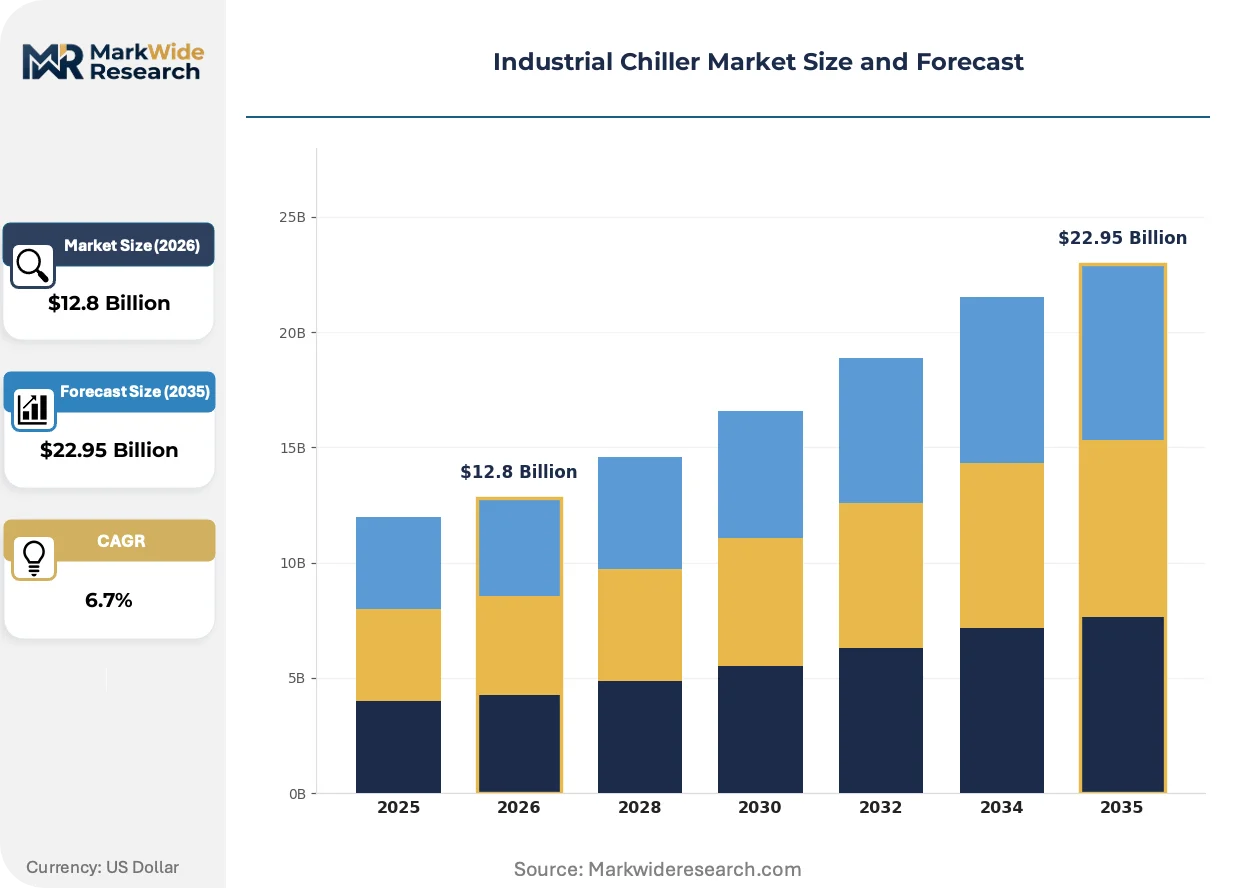
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled Chillers, Water-Cooled Chillers, Screw Chillers, Absorption Chillers End User: Manufacturing, Food & Beverage, Pharmaceuticals, Plastics Application: Cooling Processes, HVAC Systems, R&D, Industrial Refrigeration Technology: Vapor Compression, Thermoelectric, Magnetic Refrigeration, Centrifugal |
| Companies Covered | Carrier Corporation, Emerson Electric Co., Trane Technologies, Chillerone, Baltimore Aircoil Company, Johnson Controls, Mitsubishi Electric Corporation, Frigel Group, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Chiller Market Strategic Shifts
Magnetic bearing compressors, predictive maintenance algorithms, and natural refrigerant architectures are simultaneously advancing, compressing the performance gap between oil-free centrifugal platforms and traditional flooded-screw systems.
Magnetic bearing technology is converging with oil-free centrifugal compressor designs to eliminate mechanical friction losses and enable variable-speed operation down to 10% load without surge. Pharmaceutical and semiconductor fabs in Singapore and Germany are specifying these platforms for 24/7 process cooling. The technology is converging with digital twin software to compress commissioning cycles and reduce field service dependency for remote diagnostics.
The EU F-Gas Regulation's 2024 ban on refrigerants with GWP above 750 in new stationary equipment is forcing OEMs to qualify R-1234ze(E) and R-515B blends in screw and scroll compressor lines ahead of US EPA alignment. Industrial consequence includes shortened product lifecycles and accelerated obsolescence of R-134a-based inventory. Food processing and beverage chilling applications in France and Italy are responding fastest, with retrofit demand concentrating in facilities under 200 tons capacity.
Service contract unbundling is fragmenting the traditional chiller procurement bundle into separate hardware, installation, and performance-guarantee agreements. Independent service providers and energy-as-a-service platforms are displacing OEM captive service arms in North American commercial real estate and institutional healthcare. This pattern is most visible in Texas and Florida hospital systems, where facility managers prioritize uptime penalties over brand loyalty in vendor selection.
Industrial Chiller Market Segmentation
Industrial chiller procurement patterns diverge sharply between process-critical applications demanding ±0.1°C stability and comfort-cooling installations prioritizing capital efficiency. Segmentation reveals how refrigerant transition timelines, waste-heat availability, and facility infrastructure shape technology selection across end-use verticals.
Product Type:
Volume deployment concentrates in air-cooled platforms, while premium engineering gravitates toward water-cooled and oil-free centrifugal systems for large-tonnage process loads.
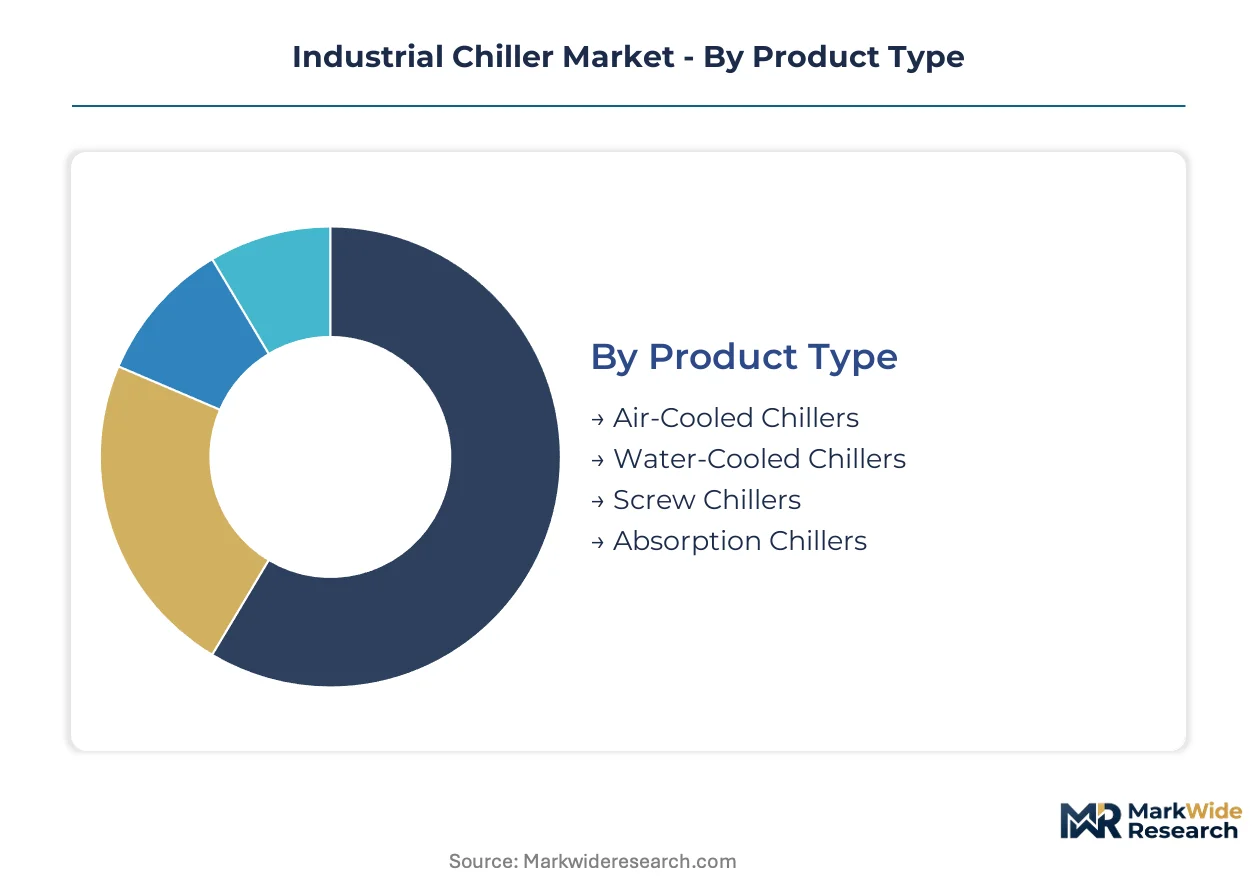
- Air-Cooled Chillers:Self-contained units reject heat directly to ambient air through finned condenser coils, eliminating cooling tower infrastructure. Demand clusters in water-scarce geographies and distributed pharmaceutical facilities where piping complexity must stay minimal. California and Arizona manufacturing plants specify these for retrofit installations where municipal water restrictions apply.
- Water-Cooled Chillers:Shell-and-tube condensers paired with evaporative cooling towers deliver superior thermodynamic efficiency above 500 tons. Petrochemical complexes in Zhejiang and Shandong provinces deploy these for continuous process cooling where waste-heat recovery integration matters. The segment commands premium pricing through copper-nickel alloy heat exchanger specifications and variable-primary-flow controls.
- Screw Chillers:Positive-displacement compression using twin helical rotors handles medium-pressure refrigerants across 100-500 ton ranges. Food processing facilities in Italy and France favor these for R-513A retrofit compatibility under tightening F-Gas thresholds.
- Absorption Chillers:Lithium bromide or ammonia-water cycles driven by waste heat or natural gas combustion achieve cooling without electric compression. Cogeneration plants at Singapore pharmaceutical campuses integrate these to utilize exhaust steam from gas turbines.
Mature deployment sits with water-cooled chillers in heavy industrial corridors. Newer deployment is concentrated in air-cooled platforms for distributed facilities and water-stressed regions.
End User:
Customer concentration varies from price-sensitive manufacturing procurement to specification-driven pharmaceutical engineering with validation documentation requirements.
- Manufacturing:Automotive stamping plants and metal fabrication facilities demand robust cooling for hydraulic systems and welding equipment. German automotive suppliers in Bavaria specify redundant chiller arrays to prevent production line stoppages costing millions per hour.
- Food & Beverage:Dairy pasteurization, brewery fermentation, and cold chain logistics require hygienic design with stainless steel fluid paths. Netherlands logistics hubs are retrofitting ammonia-based systems with integrated IoT leak detection ahead of carbon-border adjustments.
- Pharmaceuticals:Biologics manufacturing mandates glycol-based process chillers with continuous temperature validation for FDA compliance. Singapore and Germany semiconductor fabs specify magnetic bearing platforms for 24/7 cleanroom cooling with zero oil contamination risk.
- Plastics:Injection molding and extrusion processes require rapid heat removal to maintain dimensional tolerance. Texas and Florida hospital systems prioritize uptime penalties over brand loyalty when selecting service providers for these critical loads.
Pharmaceutical procurement maintains the steepest expansion trajectory through biologics capacity buildouts. Manufacturing demand is plateauing as automotive electrification reshapes metalworking intensity.
Application:
Process cooling applications command engineering premiums against commodity HVAC replacement cycles, with R&D and industrial refrigeration occupying specialized niches.
- Cooling Processes:Direct heat removal from chemical reactors, extrusion lines, and semiconductor etching equipment. Chemical processing clusters in China's coastal provinces are driving absorption chiller procurement to utilize waste heat from steam crackers.
- HVAC Systems:Building comfort cooling for commercial real estate and institutional healthcare. Texas hospital systems are unbundling service contracts into separate hardware, installation, and performance-guarantee agreements.
- R&D:Laboratory environmental chambers and test bench cooling with extreme temperature stability requirements. Germany's Fraunhofer institutes specify magnetic bearing compressors for vibration-sensitive measurement equipment.
- Industrial Refrigeration:Cold storage warehouses and blast freezing operations using ammonia or CO2 transcritical cycles. California logistics hubs are capturing natural refrigerant retrofit demand ahead of EPA phasedown deadlines.
Process cooling generates margin concentration through custom engineering. HVAC applications are commoditizing toward equipment-as-a-service models.
Technology:
Architecture selection hinges on efficiency targets, refrigerant regulatory status, and maintenance accessibility across facility lifecycles.
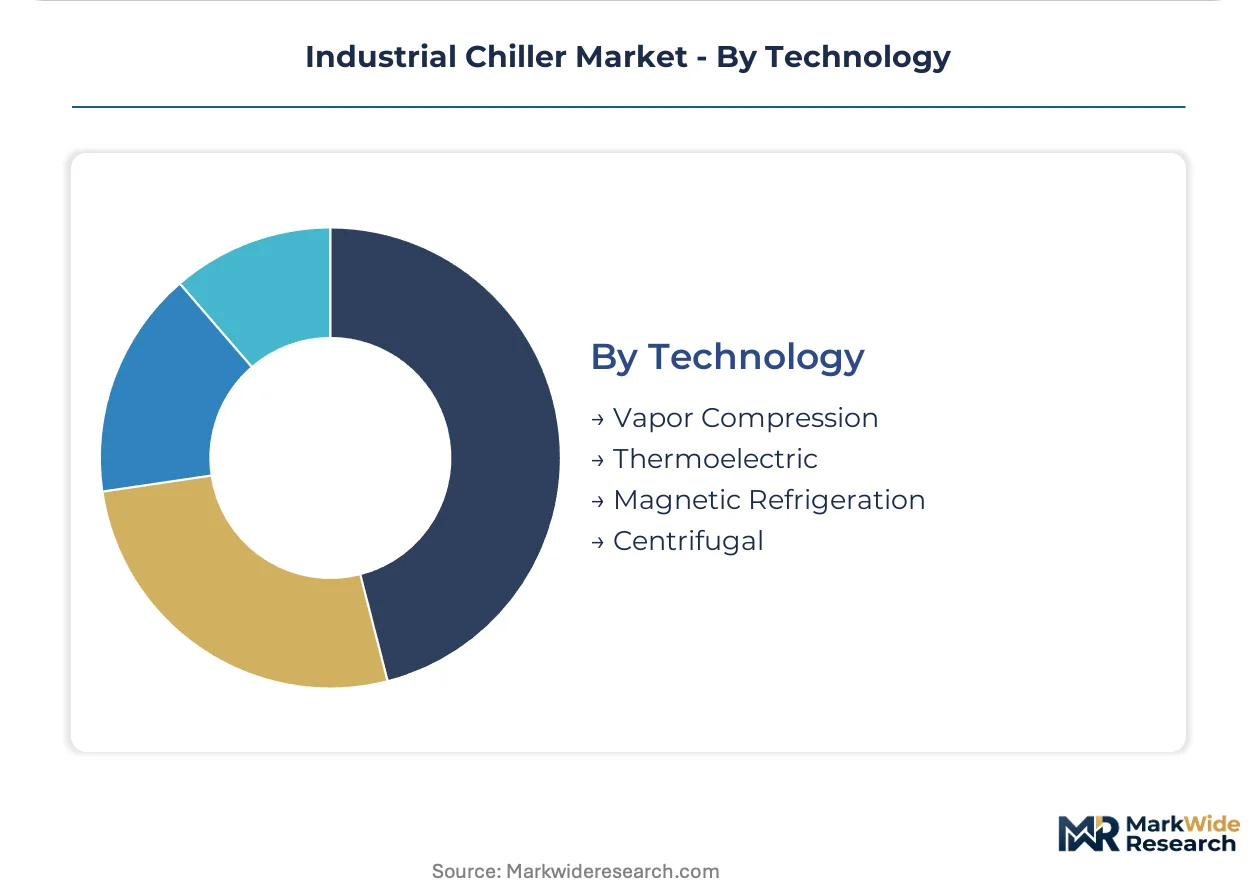
- Vapor Compression:Dominant mechanical refrigeration cycle using reciprocating, scroll, screw, or centrifugal compressors. The EU F-Gas Regulation's 2024 GWP thresholds are forcing OEMs to qualify R-1234ze(E) and R-515B blends across these compressor lines.
- Thermoelectric:Solid-state Peltier cooling for precision temperature control in small-capacity applications. Laboratory equipment manufacturers in Japan integrate these for vibration-free cooling below 5 kW.
- Magnetic Refrigeration:Emerging magnetocaloric effect technology eliminating refrigerant fluids entirely. METI-funded consortia in Japan are piloting these for commercial deployment in food retail applications.
- Centrifugal:Dynamic compression using impellers for large-tonnage applications above 300 tons. Magnetic bearing convergence is eliminating oil systems and enabling variable-speed operation down to 10% load without surge.
Centrifugal platforms are gaining share fastest through magnetic bearing adoption. Thermoelectric deployment remains confined to sub-tonnage precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate processing in Jiangxi and Chilean mining districts anchors chiller demand for smelter cooling circuits. Magnetic bearing compressor assembly concentrates in Chinese coastal manufacturing zones. Absorption chiller procurement clusters near cogeneration plants in Singapore and German chemical corridors.
United States
Data center liquid cooling deployments in Northern Virginia and pharmaceutical precision cooling mandates in Massachusetts drive centrifugal chiller demand. EPA AIM Act refrigerant phasedown compresses OEM product development cycles toward low-GWP alternatives. Texas hospital systems are unbundling service contracts into performance-guarantee agreements separate from hardware procurement.
China
Petrochemical expansion in Zhejiang and Shandong provinces accelerates absorption chiller procurement for waste-heat recovery from steam crackers. MIIT energy-efficiency standards tighten minimum performance coefficients for cooling equipment. Yangtze River Delta manufacturing clusters are shifting magnetic bearing compressor assembly toward oil-free centrifugal platforms.
Germany
Automotive stamping plants in Bavaria specify redundant chiller arrays to prevent production line stoppages costing millions per hour. EU F-Gas Regulation 2024 GWP thresholds accelerate R-513A and R-1234ze qualification across screw compressor lines. Fraunhofer institutes in Baden-Württemberg deploy magnetic bearing compressors for vibration-sensitive measurement equipment cooling.
India
Production-linked incentive schemes for cooling equipment components attract magnetic bearing compressor assembly to Gujarat and Tamil Nadu industrial corridors. BIS certification requirements for imported refrigeration equipment create compliance barriers for non-domestic OEMs. Maharashtra pharmaceutical facilities are scaling glycol-based process chillers for biologics manufacturing temperature validation.
Japan
METI-funded consortia pilot magnetocaloric refrigeration technology for commercial food retail deployment. Semiconductor fabs in Kanto and Kansai regions specify magnetic bearing platforms for 24/7 cleanroom cooling with zero oil contamination risk. Chubu industrial corridors integrate absorption chillers with gas turbine cogeneration plants to reduce grid electricity draw.
Industrial Chiller Market Competitive Environment
Global majors compete with regional champions across refrigerant transition timelines and service density networks. The vendor base stratifies between full-system integrators with captive controls technology and component specialists supplying heat exchangers and compressors to third-party assemblers. Three archetypes dominate: vertically integrated HVAC conglomerates, independent process-cooling specialists, and emerging Asian fabricators with cost-optimized platforms. Competitive moves concentrate on M&A for refrigerant handling capabilities and strategic partnerships for IoT-enabled predictive maintenance services.
Within the vertically integrated tier, Carrier Corporation and Trane Technologies occupy positions defined by chiller-plant optimization software and North American project engineering density. Daikin Industries exemplifies the Asian-scale archetype with manufacturing concentration across multiple compressor technologies. Among European specialists, Frigel Group represents the process-cooling segment focused on distributed manufacturing facilities and precision temperature stability requirements.
| Leading Market Players |
|---|
| Carrier Corporation |
| Emerson Electric Co. |
| Trane Technologies |
| Chillerone |
| Baltimore Aircoil Company |
| Johnson Controls |
| Mitsubishi Electric Corporation |
| Frigel Group |
| Daikin Industries |
| Others |
Value Chain & Pricing Dynamics
FDA temperature-validation mandates for biologics manufacturing are compressing procurement timelines and forcing OEMs to pre-qualify glycol-based process chillers with extended warranty coverage, which inflates upfront capital outlays while creating aftermarket service revenue anchors. This specification-driven demand concentrates pricing power with vendors possessing captive controls technology and certified service networks across pharmaceutical corridors in Massachusetts and Singapore.
Pricing Analysis
Warranty and performance-guarantee bundling now separates premium water-cooled centrifugal platforms from unbundled air-cooled alternatives where independent service providers compete on uptime penalties. Three-tier pricing structure across premium magnetic bearing systems, standard screw compressor lines, and economy scroll units reflects certification grade and after-sales density rather than raw manufacturing cost. Cost compression in mid-range screw chillers is intensifying because R-513A retrofit compatibility under EU F-Gas thresholds has commoditized this segment. Pharmaceutical facilities exhibit lowest price sensitivity due to FDA validation documentation requirements, while distributed food processing plants in water-scarce geographies drive aggressive procurement of air-cooled alternatives.
Supply Chain Analysis
EPA Section 608 certification requirements and EU F-Gas handling licenses gate component sourcing for low-GWP refrigerant systems, limiting qualified heat exchanger and compressor suppliers to facilities with documented environmental compliance. Manufacturing concentrates in China for magnetic bearing motors and brazed-plate heat exchangers, in Germany for precision screw compressor machining, and in Japan for advanced control electronics. Copper and neodymium draws from Chinese processing facilities exposes OEMs to export-control disruptions. Distribution runs through authorized dealer networks with captive installation crews rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around refrigerant-transition capabilities, with EPA AIM Act phasedown timelines and EU F-Gas alignment pressures forcing sub-scale assemblers without certification infrastructure toward exit or acquisition.
For Market Incumbents: Extend service contract penetration in pharmaceutical and data center verticals to lock in recurring revenue ahead of hardware commoditization. Carrier Corporation and Trane Technologies should deepen backward integration into refrigerant handling and controls software to defend margin position against emerging Asian fabricators with cost-optimized platforms. Captive certification programs for A2L and A3 refrigerant technicians represent the critical lever for commissioning speed differentiation. For New Entrants and Emerging Players: The price-point gap between premium magnetic bearing centrifugal systems and economy scroll compressors in the 100-300 ton range creates white-space opportunity for mid-market oil-free screw platforms with predictive maintenance subscriptions. Target pharmaceutical facilities in India and Southeast Asia where BIS and local certification requirements have slowed incumbent penetration. A chiller-plant-as-a-service revenue model with guaranteed efficiency performance bypasses capital-budget constraints at hospital systems in Texas and Florida. For Investors and Strategic Acquirers: Re-rating potential sits with process-cooling specialists possessing FDA-validated installation track records and captive IoT predictive maintenance platforms, given data center liquid cooling convergence and pharmaceutical biologics expansion. Long-term viability over the next decade hinges on refrigerant-transition execution speed rather than manufacturing scale alone. The signal to watch is EPA Significant New Alternatives Policy approval velocity for R-1234ze and R-515B blends, which determines stranded inventory risk and product lifecycle compression rates.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | EPA AIM Act and EU F-Gas alignment forces simultaneous compressor, heat exchanger, and control redesign across product lines. |
| Magnetic Bearing Assembly Expansion | MIIT energy-efficiency standards in China and PLI schemes in India attract oil-free centrifugal manufacturing to Asian industrial corridors. |
| Service Contract Unbundling | Texas hospital systems and Northern Virginia data centers now separate hardware procurement from performance-guarantee agreements. |
| Natural Refrigerant Certification | Ammonia-based chillers with integrated IoT leak detection capture California and Netherlands cold storage retrofit demand. |
| Predictive Maintenance Platform Integration | Digital twin software convergence with magnetic bearing compressors reduces field service dependency for Singapore pharmaceutical fabs. |
Study Parameters
Multi-period observation of EPA refrigerant phasedown implementation, EU F-Gas retrofit cycle velocity, and pharmaceutical facility commissioning timelines anchored the trend analysis, supplemented by interviews with plant engineers at chemical processing clusters, aftermarket service heads at OEM captive networks, and procurement leads at hyperscale data center operators. Secondary validation drew from EPA Significant New Alternatives Policy filings, ECHA refrigerant registration databases, SEC 10-K disclosures from listed HVAC conglomerates, and MIIT energy-efficiency standard publications. Bottom-up and top-down triangulation cross-checked regional absorption chiller procurement data against petrochemical capacity expansion announcements.
Input-output matrix modeling connected compressor technology adoption rates, refrigerant qualification timelines, and end-use vertical expansion patterns across the projection horizon. Segmentation dimensions included product architecture, cooling capacity tier, refrigerant regulatory status, end-use industry, and regional energy infrastructure type. CAGRs were derived from installed base replacement cycles and greenfield project pipelines rather than extrapolated trend fitting. Industry-specific forecast inputs incorporated pharmaceutical temperature-validation mandate enforcement intensity and data center liquid cooling adoption curves.
Inputs from plant engineer interviews and customs trade data were available through the study window; gaps in real-time A2L refrigerant technician certification deployment rates introduce uncertainty bands around commissioning timeline assumptions. Forecasts reflect documented regulatory phasedown schedules and announced manufacturing capacity investments. A model refresh is warranted upon material change in EPA Significant New Alternatives Policy approval velocity or EU F-Gas threshold acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Dedicated Outdoor Air System Market
HVAC Equipment
Blowers Market
HVAC Equipment
Radiant Heating and Cooling Systems Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
Warm Air Heater Market