
 Industrial Ventilation Equipment Market | 2026-2036
Industrial Ventilation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Ventilation Equipment Market Analysis
The gap between premium engineered ventilation and commodity air-moving equipment is expanding as energy-efficiency mandates and smart-building integration split procurement criteria. Greenheck Fan Corporation leverages backward integration into fan blade manufacturing to control lead times for custom industrial orders. Systemair AB competes through standardized modular platforms that reduce installation complexity across European manufacturing sites.
Industrial ventilation equipment encompasses mechanical systems designed to control airborne contaminants, temperature, and humidity within enclosed workspaces, typically operating at airflow rates from hundreds to millions of cubic feet per minute depending on facility scale and hazard classification. These systems serve primarily to protect worker health, maintain process integrity, and comply with occupational exposure limits in heavy industrial environments. Blowers and fans represent the mature volume core where margin compression is acute, while hybrid technology configurations that combine mechanical and natural ventilation elements capture expanding margin pools as facilities pursue net-zero operational targets. Dust control applications within mining and chemicals end-use segments are outgrowing general air quality control installations due to stricter respirable particulate enforcement.
OSHA ventilation standards in the US, EU F-Gas Regulation restrictions on fluorinated greenhouse gases in cooling circuits, and CE marking requirements for mechanical equipment collectively elevate product certification costs while disqualifying non-compliant suppliers from project bids. EPA and MEE enforcement of particulate matter thresholds in manufacturing zones directly shapes replacement cycles for legacy dust collection infrastructure. Stakeholders must evaluate whether to absorb compliance-driven R&D costs internally or cede position to vertically integrated competitors with captive testing laboratories.
Market Dynamics
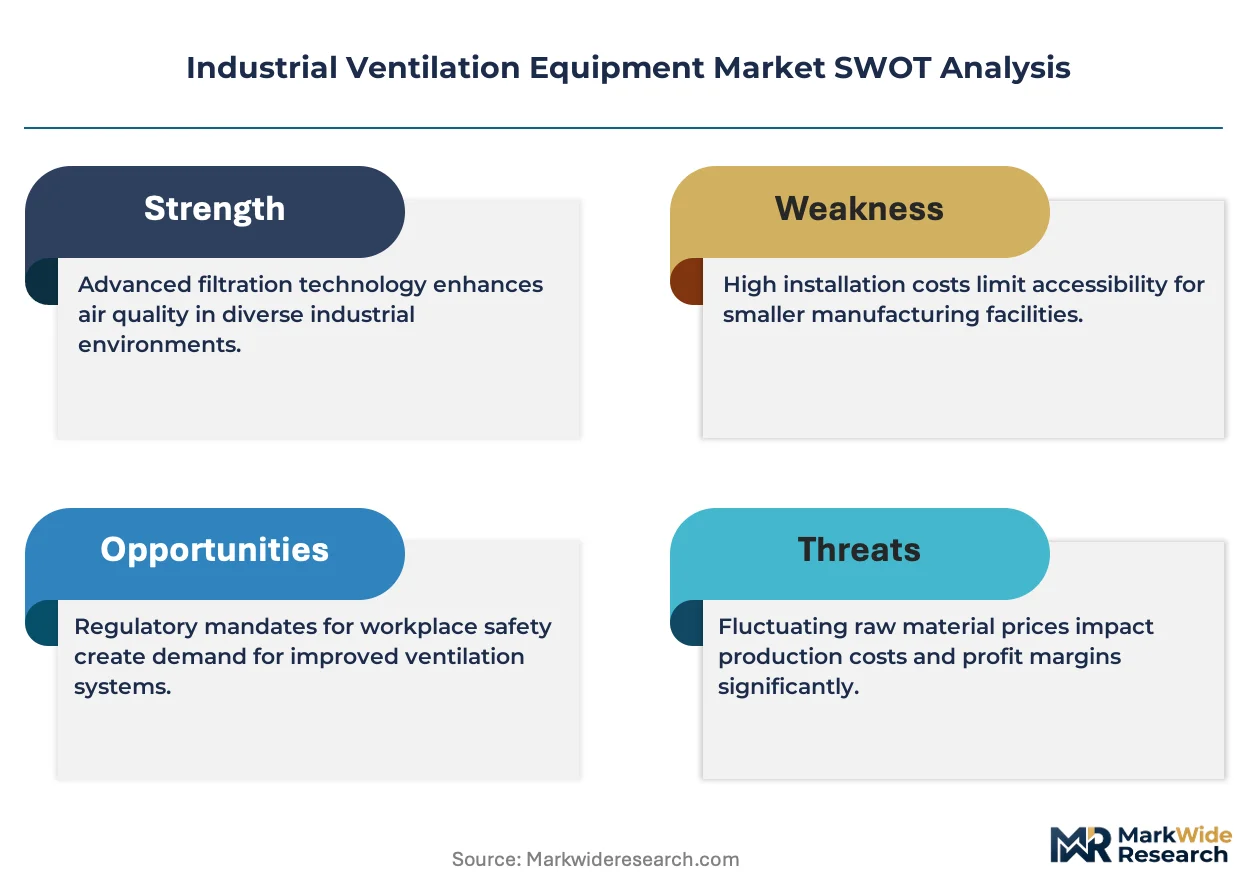
Energy-efficiency mandates and smart-building integration are splitting procurement criteria between premium engineered ventilation and commodity air-moving equipment, widening the competitive gap between specialized and standardized suppliers.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in cooling circuits accelerate replacement of legacy refrigeration-linked ventilation systems in chemical processing facilities across Germany and France.
- Respirable particulate enforcement:EPA and MEE tightening of particulate matter thresholds in manufacturing zones drives replacement cycles for dust collection infrastructure in mining and heavy chemicals.
- Net-zero operational targets:Hybrid technology configurations combining mechanical and natural ventilation elements capture expanding margin pools as industrial facilities pursue decarbonization pathways.
Market Restraints
- Aluminum and steel input volatility:Fan blade and housing manufacturers face margin compression from commodity metal price swings, with limited pass-through power in competitive bid environments.
- Certification cost elevation:OSHA ventilation standards, EU F-Gas Regulation, and CE marking requirements collectively disqualify non-compliant suppliers from project bids while elevating product development costs.
- Technical limitation in retrofit compatibility:Legacy ductwork infrastructure in aging industrial facilities constrains adoption of high-efficiency variable-speed drives without comprehensive system redesign.
Strategic Opportunities
- India's pharmaceutical clusters:Underpenetrated demand for contamination-controlled ventilation in bulk drug manufacturing creates white space for specialized cleanroom air handling systems.
- Technology convergence:Integration of IoT sensors with predictive maintenance algorithms enables service contract expansion and remote monitoring revenue streams.
- Channel innovation through direct specification:Engineering-procurement-construction firms increasingly source ventilation skids directly from manufacturers, bypassing traditional distribution layers.
Industry Challenges
- Commissioning and balancing expertise shortage:Qualified technicians for airflow testing and system optimization remain scarce relative to installation volume in expanding manufacturing corridors.
- Integration complexity with building management systems:BACnet and Modbus protocol harmonization demands specialized software engineering capacity that mid-tier suppliers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Ventilation Equipment Market |
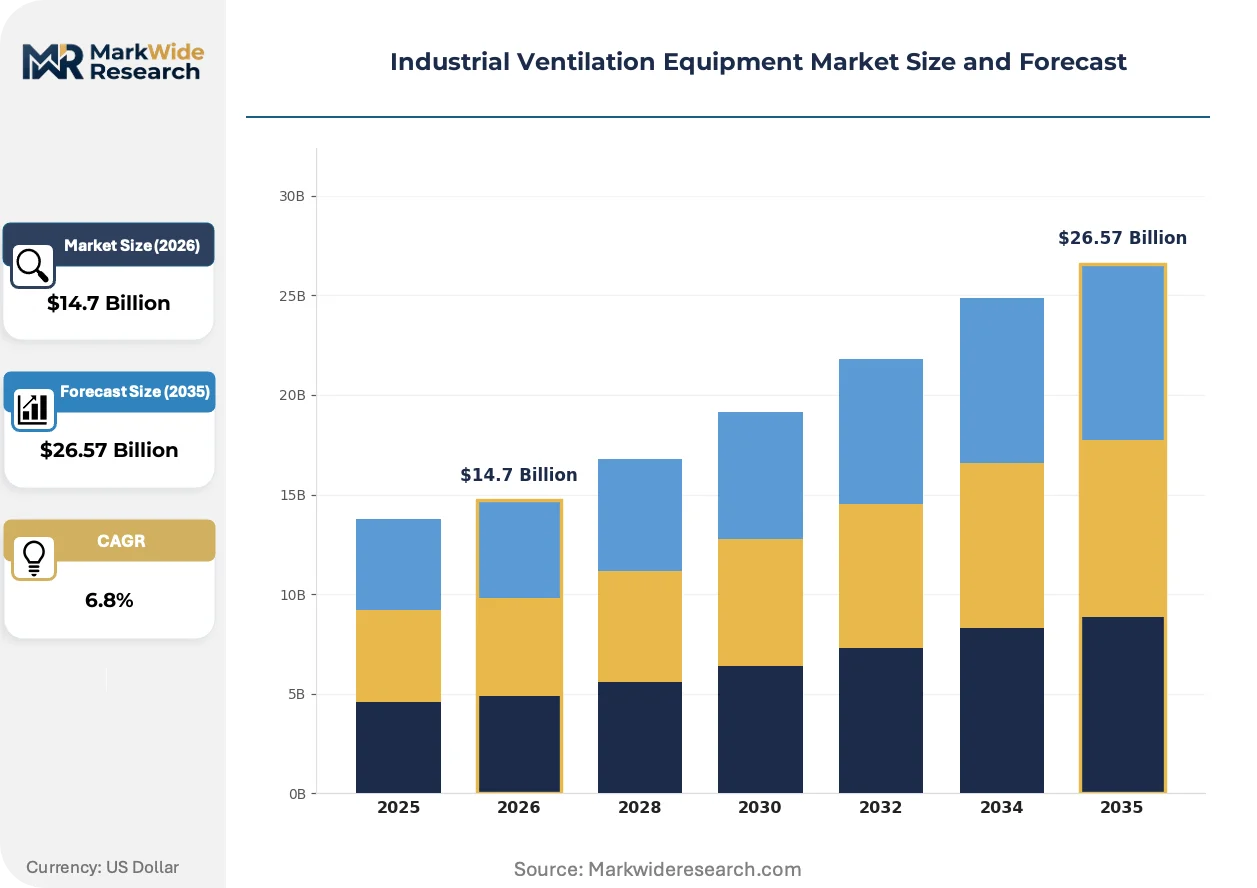
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blowers, Fans, Filters, Ducts Technology: Mechanical, Natural, Hybrid, CE Marked End User: Manufacturing, Construction, Mining, Chemicals Application: Air Quality Control, Dust Control, Cooling, Heating |
| Companies Covered | Loren Cook Company, Air Systems Components, Greenheck Fan Corporation, Fantech, Vent-Axia, Systemair AB, Titus, Big Ass Fans, Soler & Palau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Ventilation Equipment Market Emerging Trajectories
Digitalization of airflow control and predictive service models are restructuring how ventilation systems are specified, installed, and maintained across industrial end-uses.
Variable refrigerant flow integration with dedicated outdoor air systems is modularizing how pharmaceutical and electronics manufacturing facilities manage both temperature and contamination control through unified platforms. Cleanroom operators in Singapore and South Korea adopt these configurations to reduce mechanical room footprint while maintaining ISO 14644 compliance. The approach compresses traditional separate-system procurement into single-source responsibility contracts.
OSHA's updated ventilation standards for combustible dust handling force grain processing and metalworking facilities to upgrade collection hood designs and duct velocities. The rule mandates documented airflow verification that legacy systems cannot satisfy without control upgrades. Chemical processors in Texas and Louisiana respond by front-loading capital plans to avoid production interruptions during enforcement windows.
Specification authority is migrating from facilities maintenance departments to corporate sustainability offices, with energy performance guarantees replacing first-cost evaluation in capital requests. Industrial buyers in China's manufacturing corridors now require ISO 50001-aligned measurement and verification protocols for ventilation energy consumption. This shift compresses vendor selection timelines while elevating technical documentation burdens on suppliers.
Industrial Ventilation Equipment Market Segmentation
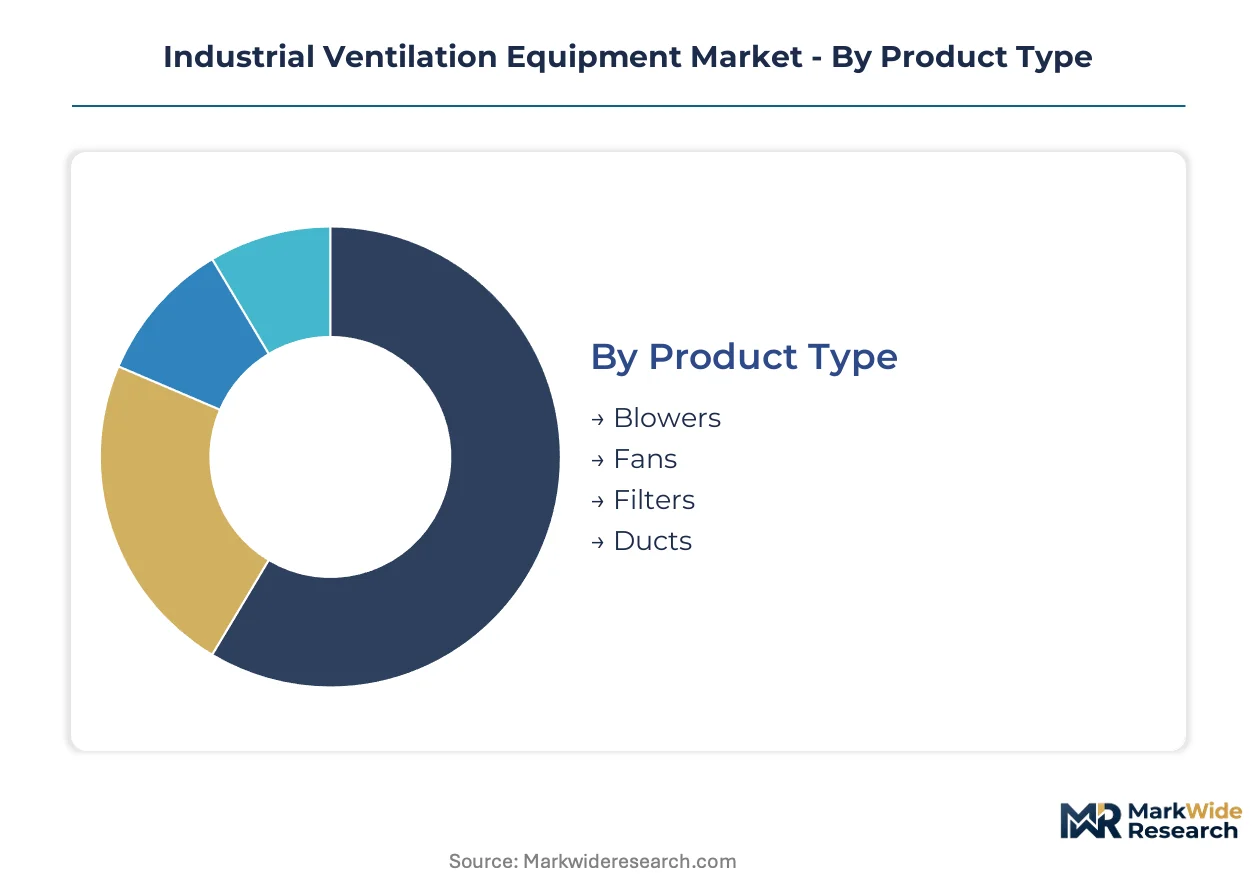
Industrial ventilation equipment procurement splits along four distinct axes that determine replacement urgency and margin capture. Product type and technology choices drive capital allocation priorities, while end-user concentration and application specificity shape regional demand patterns.
Product Type:
Replacement cycles vary sharply across equipment categories, with energy-efficiency mandates accelerating obsolescence of legacy mechanical components.
- Blowers:Centrifugal and axial designs dominate heavy industrial airflow generation, typically specified for continuous-duty operations in chemical processing corridors. Germany's expanding chemical facilities and US Gulf Coast petrochemical clusters are driving demand for corrosion-resistant alloy housings as OSHA tightens emission verification requirements.
- Fans:Propeller and vane-axial configurations serve lower-pressure applications where modularity matters more than precision control. India's pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are retrofitting legacy facilities with variable-speed fan arrays to meet contamination control standards.
- Filters:HEPA and activated carbon media capture respirable particulates and volatile organic compounds in cleanroom environments.
- Ducts:Galvanized steel and aluminum fabrication systems transport conditioned air throughout facility networks.
Fans sit at the top of the volume ranking, with blowers climbing the fastest.
Technology:
Cost tier separation between basic mechanical systems and premium smart-enabled configurations is widening as decarbonization targets reshape procurement criteria.
- Mechanical:Motor-driven forced-air systems remain the installed base majority, though rising electricity costs and carbon accounting pressures erode their economic advantage in long-horizon facilities.
- Natural:Buoyancy-driven ventilation through roof vents and louvers eliminates energy consumption entirely. Mining operations in Western Australia and Chile's Atacama Desert deploy these configurations for underground air exchange where electrical infrastructure is unreliable or hazardous.
- Hybrid:Combined mechanical-natural systems optimize energy use by engaging powered components only when natural forces prove insufficient. Chemical processing facilities in Germany and France are expanding adoption as EU F-Gas Regulation compliance deadlines approach, with hybrid configurations reducing refrigerant-linked ventilation loads.
- CE Marked:Certified equipment meeting EU machinery directive safety and electromagnetic compatibility standards commands price premiums in European project bids while disqualifying uncertified competitors.
Mechanical systems retain volume leadership, with hybrid technology gaining share fastest.
End User:
Customer type determines specification authority, with corporate sustainability offices displacing facilities maintenance departments in capital request evaluation.
- Manufacturing:Automotive assembly, electronics fabrication, and food processing facilities require continuous air quality maintenance for both worker protection and product integrity. China's manufacturing corridors in the Pearl River Delta and Yangtze River Delta concentrate replacement demand as MEE enforcement of particulate thresholds accelerates legacy system retirement.
- Chemicals:Petrochemical, specialty chemical, and pharmaceutical production demands explosion-proof ventilation and corrosion-resistant materials. Texas and Louisiana processors are front-loading capital plans to avoid production interruptions during OSHA enforcement windows for combustible dust handling.
- Mining:Underground and surface extraction operations prioritize dust suppression and diesel exhaust evacuation.
- Construction:Temporary ventilation for tunneling, demolition, and confined-space work emphasizes portability and rapid deployment.
Manufacturing commands the largest installed base, with chemicals expanding most quickly.
Application:
Application-specific margin pools diverge based on regulatory enforcement intensity and technical complexity of performance verification.
- Dust Control:Collection hoods, cyclone separators, and baghouse systems capture respirable particulates in mining, grain processing, and metalworking. EPA tightening of PM2.5 and PM10 thresholds in manufacturing zones drives replacement cycles for legacy infrastructure that cannot satisfy documented airflow verification mandates.
- Air Quality Control:General ventilation for temperature, humidity, and contaminant dilution serves baseline industrial comfort and safety requirements.
- Cooling:Process cooling and comfort air conditioning integration with ventilation systems faces transformation under EU F-Gas Regulation restrictions on fluorinated greenhouse gases.
- Heating:Makeup air heating and combustion exhaust management supports cold-climate operations and thermal process integration.
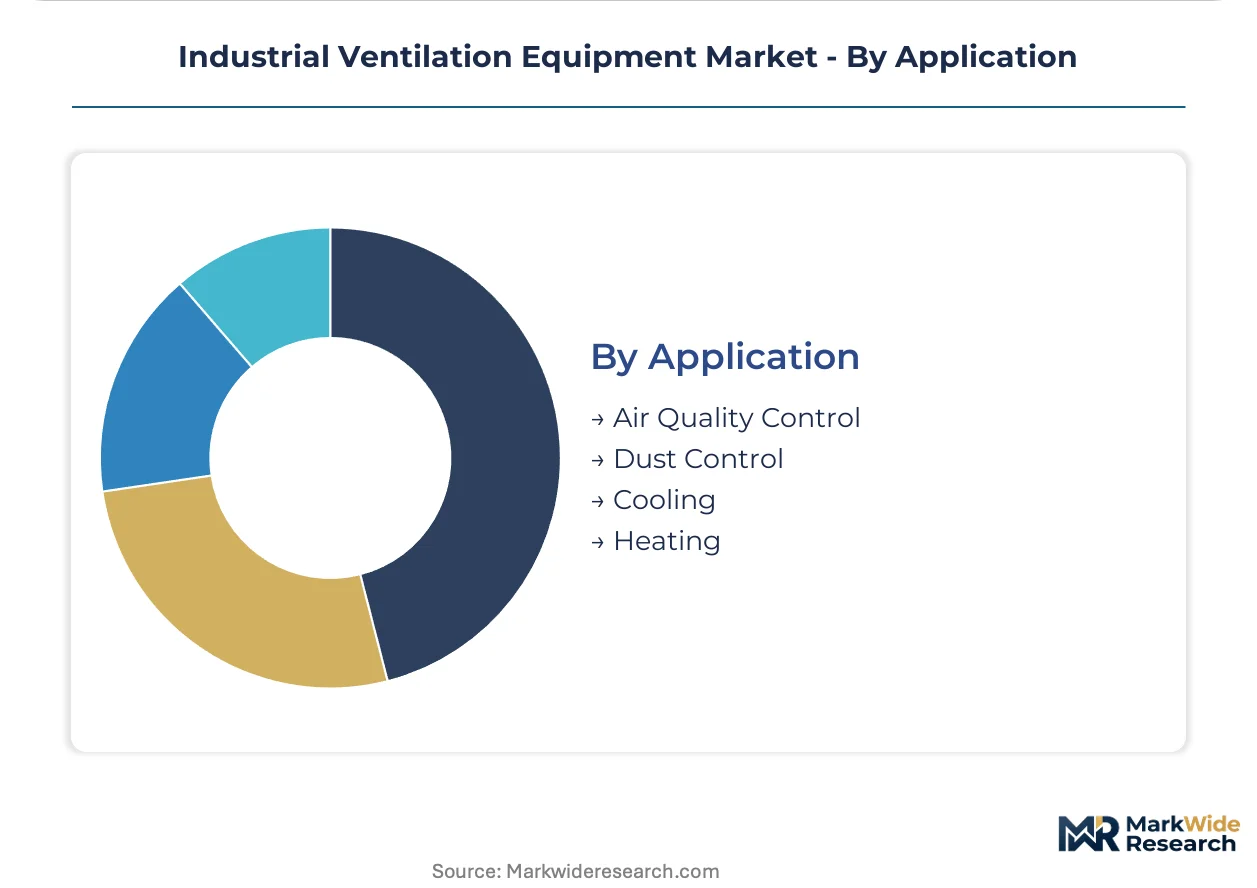
Air quality control holds volume dominance, with dust control climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent anchors European ventilation innovation, while Chinese manufacturing scale and US chemical processing expertise concentrate replacement demand across three distinct regulatory environments.
United States
OSHA ventilation standards and EPA particulate enforcement drive replacement cycles in Gulf Coast petrochemical corridors. Chemical processors in Texas and Louisiana front-load capital plans to avoid production interruptions during combustible dust handling enforcement windows. Houston and Beaumont clusters prioritize corrosion-resistant alloy housings for emission verification compliance.
Germany
EU F-Gas Regulation deadlines accelerate hybrid ventilation adoption in chemical processing facilities. CE marking requirements and machinery directive compliance elevate certification barriers for non-European suppliers. The Rhine-Ruhr industrial belt and Bavarian chemical parks expand procurement of combined mechanical-natural systems to reduce refrigerant-linked loads.
China
MEE enforcement of particulate thresholds in manufacturing zones accelerates legacy system retirement in Yangtze River Delta and Pearl River Delta corridors. Dual carbon goals and ISO 50001-aligned verification protocols reshape procurement criteria toward energy performance guarantees. Shenzhen and Shanghai facilities now require documented airflow measurement for dust collection infrastructure.
India
Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad retrofit legacy facilities with variable-speed fan arrays for contamination control. CDSCO quality mandates and bulk drug production expansion create underpenetrated demand for cleanroom air handling systems. Gujarat's Special Economic Zones concentrate specialized ventilation procurement authority.
South Korea
Cleanroom operators in Seoul Capital Area and Busan-Ulsan corridor adopt variable refrigerant flow integration with dedicated outdoor air systems. MFDS pharmaceutical manufacturing standards and electronics fabrication growth compress traditional separate-system procurement into single-source contracts. Gyeonggi-do semiconductor facilities drive ISO 14644-compliant modular platform demand.
Industrial Ventilation Equipment Market Vendor Landscape
Top-tier vendors anchor premium engineered ventilation, while mid-tier fabricators compete on installation speed and regional service density. The market structures around three strategic archetypes: backward-integrated specialists controlling component manufacturing, modular platform providers standardizing European installations, and specification-driven engineering houses capturing direct EPC relationships. Consolidation pressure favors M&A activity among regional distributors, while technology licensing agreements proliferate for IoT-enabled predictive maintenance capabilities.
Among US-based fabricators, Loren Cook Company and Greenheck Fan Corporation occupy positions in the premium-tier engineered segment, exemplifying backward integration strategies into fan blade manufacturing. Systemair AB represents the modular platform archetype with standardized configurations reducing installation complexity. Fantech anchors the mid-tier specification channel, sitting within the direct EPC sourcing trend bypassing traditional distribution layers.
| Leading Market Players |
|---|
| Loren Cook Company |
| Air Systems Components |
| Greenheck Fan Corporation |
| Fantech |
| Vent-Axia |
| Systemair AB |
| Titus |
| Big Ass Fans |
| Soler & Palau |
| Others |
Supply Flow & Price Mechanics
Hybrid ventilation technology adoption simultaneously reshapes cost economics and supply concentration as EU F-Gas Regulation deadlines force chemical processors toward combined mechanical-natural systems. This transition compresses margins for commodity fan manufacturers while elevating premium-tier pricing power for certified hybrid system integrators.
Pricing Analysis
Bundled service contracts now separate premium ventilation suppliers from commodity equipment vendors. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking certification, corrosion-resistant alloy specifications, and predictive maintenance software integration. Cost compression in standard-tier axial fans intensifies because aluminum and steel input volatility limits pass-through power in competitive bid environments. Pharmaceutical manufacturers in India exhibit highest price sensitivity, while German chemical processors prioritize energy performance guarantees over first-cost evaluation.
Supply Chain Analysis
Single-source vulnerability sits with Chinese galvanized steel duct fabrication and German precision motor manufacturing. Component sourcing draws from China, Germany, and the United States for fan blades, variable-frequency drives, and HEPA media respectively. Tariff exposure on aluminum sheet imports from primary producing regions elevates landed cost unpredictability for housing fabricators. Distribution runs through engineering-procurement-construction firms increasingly sourcing ventilation skids directly from manufacturers, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial ventilation equipment represents a late-cycle quality story as specification authority migrates toward corporate sustainability offices demanding ISO 50001-aligned energy performance guarantees. This demand shift elevates premium engineered systems over commodity replacements.
For Market Incumbents: Anticipate margin compression in standard fan arrays from Chinese import competition by deepening backward integration into fan blade manufacturing and captive alloy casting capacity. Prioritize CE marking investment and EU F-Gas Regulation compliance certification to disqualify non-compliant bidders from German and French chemical processing contracts. For New Entrants and Emerging Players: IoT-enabled predictive maintenance algorithms offer a technology-first wedge into service contract expansion and remote monitoring revenue streams. Target India's pharmaceutical clusters in Hyderabad and Ahmedabad for cleanroom air handling systems where CDSCO quality mandates create underpenetrated demand for contamination-controlled ventilation. Pursue direct EPC specification relationships bypassing traditional distribution markups. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional distributors lacking IoT integration capabilities or hybrid system engineering expertise. Five-to-ten year viability favors acquisition targets with established testing laboratory infrastructure and captive certification capacity. Watch OSHA enforcement window timing for combustible dust handling as inflection indicator for replacement cycle acceleration in US Gulf Coast chemical corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fan Blade Manufacturing | Greenheck Fan Corporation controls lead times for custom industrial orders through in-house production of corrosion-resistant alloy components. |
| Modular Platform Standardization | Systemair AB reduces installation complexity across European manufacturing sites through pre-engineered configuration libraries. |
| Predictive Maintenance Service Contracts | Integration of IoT sensors with airflow monitoring algorithms enables recurring revenue streams from pharmaceutical cleanroom operators. |
| Direct EPC Specification Relationships | Fantech captures procurement authority migration from facilities maintenance to corporate sustainability offices through engineering house partnerships. |
| CE Marking and EU F-Gas Compliance Investment | Certified equipment commands price premiums in German chemical park bids while disqualifying uncertified competitors from project participation. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads were validated against secondary sources including SEC 10-K filings, customs and trade data, and industry association reports from ACC and Cefic. This triangulation approach ensures demand-side replacement cycle assumptions align with supplier-reported order backlogs and capacity utilization.
Historical trendline analysis of equipment replacement cycles, energy-efficiency mandate adoption curves, and regulatory enforcement patterns informed the projection framework. Segmentation dimensions modeled include product type, technology configuration, end-user industry, and application specificity across the analysis window. CAGRs were derived from regression analysis of installed base aging, particulate threshold tightening timelines, and net-zero operational target adoption in manufacturing and chemical processing.
The model holds under steady regulatory enforcement intensity and commodity metal price stability; deviation in OSHA or MEE inspection frequency, or acute aluminum and steel volatility, would shift replacement timing and margin capture assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Global Radiant Floor Heating Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Modular Refrigeration Unit Market