
 Welded Spiral Heat Exchangers Market | 2026-2036
Welded Spiral Heat Exchangers Market Size, Share, and Industry Trends Forecast 2026-2036
Welded Spiral Heat Exchangers Market Outlook
Preventive maintenance contracts and remote thermal monitoring subscriptions are decoupling equipment revenue from long-term customer relationships in the welded spiral heat exchanger sector. Alfa Laval AB leverages its installed base to anchor recurring service income across Nordic process industries. Danfoss A/S competes through channel control in district heating retrofit markets. Gooch Thermal Systems, Inc. specializes in custom-engineered welded spiral configurations for North American chemical processors.
Welded spiral heat exchangers consist of two metal strips wound concentrically and welded alternately to form dual spiral channels, typically fabricated from stainless steel or corrosion-resistant alloys with channel gaps ranging from 5 mm to 30 mm depending on fouling tolerance requirements; this geometry enables counter-current flow with high thermal efficiency and self-cleaning shear stress for viscous or particulate-laden fluids in chemical, petrochemical, and food processing duties. Stainless steel material grades dominate current procurement volumes due to their balance of chloride resistance and weldability, while high-pressure product variants command premium positioning in hydrogen and supercritical CO2 applications. Customized configurations represent the fastest-growing product type as engineering procurement shifts toward site-specific thermal-hydraulic optimization rather than catalog selections.
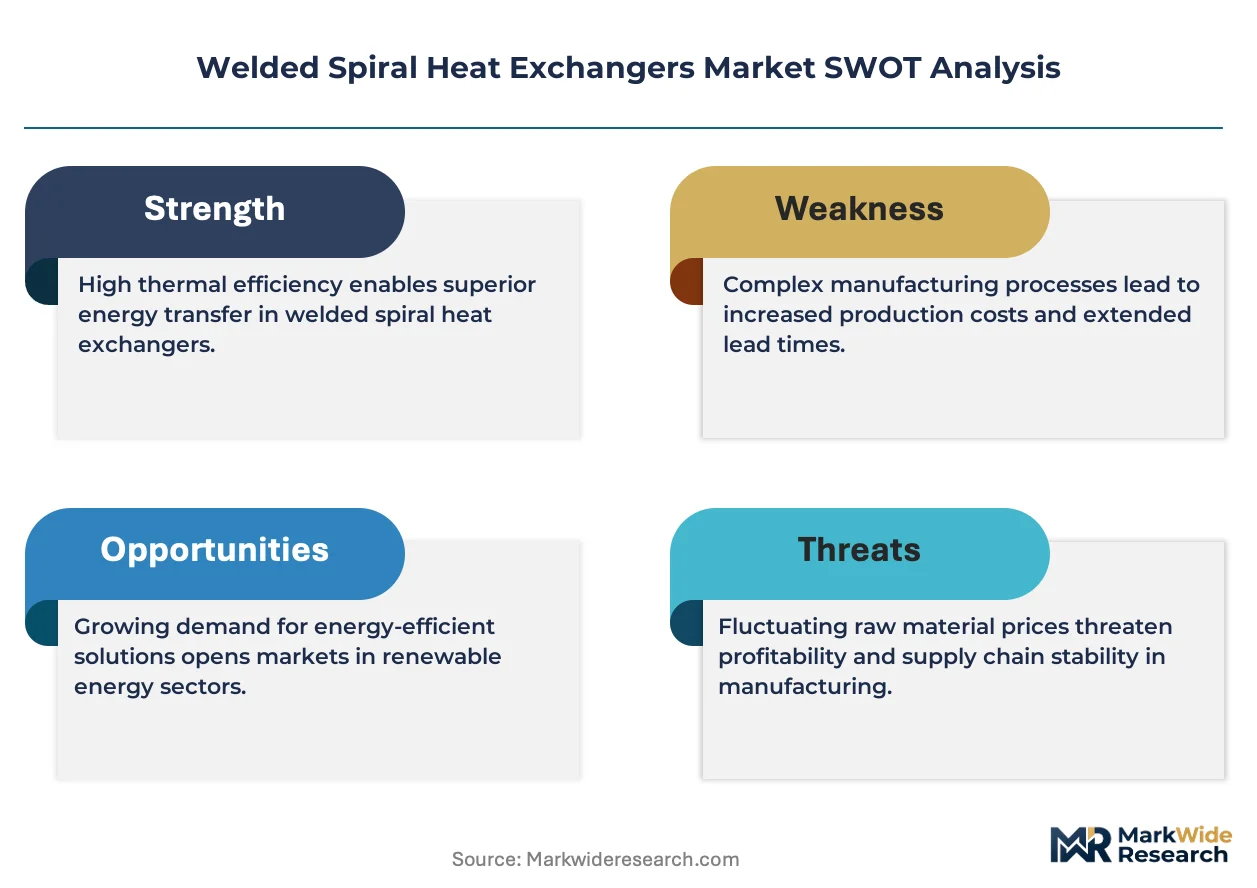
ASME Boiler and Pressure Vessel Code Section VIII governs welded construction and hydrostatic testing protocols for units deployed in US process facilities, while the EU Pressure Equipment Directive 2014/68/EU harmonizes conformity assessment across member states. Both frameworks elevate compliance costs for non-certified fabricators and create procurement preference for established suppliers with notified body relationships. Stakeholders must monitor evolving carbon border adjustment mechanisms and embodied carbon disclosure rules that will soon differentiate suppliers based on mill-source traceability and weld energy intensity.
Market Dynamics
The EU F-Gas Regulation is compressing replacement cycles across European process industries, forcing facility operators to retire conventional shell-and-tube units ahead of schedule and adopt welded spiral configurations with higher thermal efficiency and lower refrigerant charge requirements.
Growth Catalysts
- EU F-Gas Regulation:Tightening phasedown schedules for hydrofluorocarbons are accelerating equipment turnover in chemical processing plants, where welded spiral designs reduce refrigerant inventory by 40-60% compared to conventional alternatives.
- Petrochemical cluster density:Rhine corridor facilities in Germany are executing coordinated replacement programs, creating concentrated demand bursts for corrosion-resistant alloy units rated for aggressive acid service.
- Supercritical CO2 cycle adoption:Welded spiral geometries with high-pressure ratings are capturing share in carbon capture and hydrogen liquefaction pilot projects, where channel geometry tolerates extreme pressure differentials.
Market Restraints
- Nickel alloy cost volatility:Hastelloy and Inconel price swings compress fabrication margins and deter speculative inventory building by mid-sized fabricators serving North American chemical processors.
- Notified body concentration:EU Pressure Equipment Directive certification depends on a limited pool of accredited inspection bodies, creating bottlenecks for new market entrants without established conformity assessment relationships.
- Shell-and-tube residual preference:Conservative engineering specifications in legacy food and dairy applications resist specification changes despite demonstrated fouling advantages of spiral geometry.
Strategic Opportunities
- India PLI scheme alignment:Process equipment localization incentives under the Production Linked Incentive framework create openings for joint ventures with domestic stainless steel fabricators serving specialty chemical zones.
- Remote thermal monitoring integration:IoT sensor deployment enables predictive maintenance subscriptions that extend customer lifetime value beyond equipment sale margins.
- Hydrogen refueling station standardization:Pre-cooling heat exchanger specifications for 700-bar dispensing infrastructure remain unsettled, allowing first-movers to establish design conventions.
Industry Challenges
- ASME Section VIII welder certification scarcity:Qualified pressure vessel welders command premium wages and extended lead times, constraining output expansion for US-focused fabricators.
- Legacy DCS integration complexity:Welded spiral units with embedded temperature sensors require protocol translation layers to communicate with decades-old distributed control systems prevalent in mature European petrochemical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welded Spiral Heat Exchangers Market |
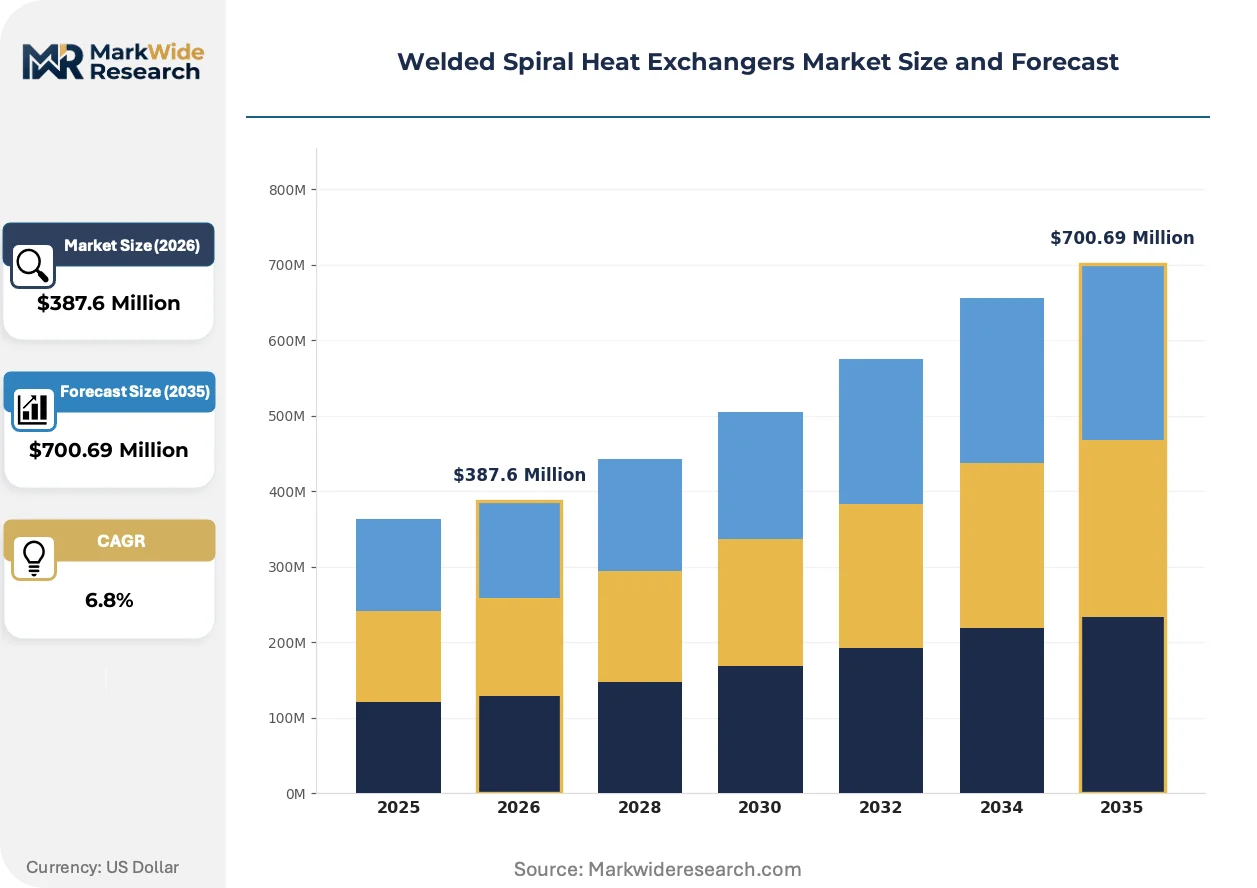
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High-Pressure, Compact, Customized Material: Stainless Steel, Carbon Steel, Alloy, Copper End User: Oil & Gas, Chemical Processing, Power Generation, Food & Beverage Application: Cooling, Heating, Heat Recovery, Condensation |
| Companies Covered | Alfa Laval AB, Danfoss A/S, Gooch Thermal Systems, Inc., Nexson Group, Kelvion Holding GmbH, Kurose Chemical Equipment Co., Ltd., Shanghai Shenglin M&E Technology Co., Ltd., Tranter International Inc., API Heat Transfer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welded Spiral Heat Exchangers Market Strategic Shifts
Additive manufacturing of flow distributors is compressing lead times for customized channel geometries. Digital twin deployment enables real-time performance optimization. Carbon border adjustment preparation is forcing mill-source documentation upgrades.
Laser powder bed fusion of stainless steel flow distributors is electrifying prototyping cycles for site-specific thermal-hydraulic configurations. Chemical processors in the Netherlands are adopting these additively manufactured components for pilot-scale trials within 6-8 weeks versus 16-20 weeks for conventional machining. This velocity is electrifying competitive differentiation for engineering-intensive bids where first-mover demonstration advantages secure multi-year framework agreements.
The EU Carbon Border Adjustment Mechanism is tightening embodied carbon disclosure requirements for imported steel and alloy components. Fabricators must now document mill-specific emission factors and weld energy intensity to avoid tariff penalties on units shipped into EU member states. German process equipment buyers are already screening supplier submissions for ISO 14064-aligned carbon accounting, creating procurement preference for domestic and near-shore fabricators with verified low-carbon supply chains.
Engineering procurement organizations are consolidating vendor panels and demanding outcome-based thermal performance guarantees rather than equipment-only transactions. Chemical sector buyers in Belgium and the Netherlands now specify guaranteed heat transfer coefficients and fouling resistance over 5-year operating windows, transferring operational risk to equipment suppliers. This reconfiguration is most visible in contract structures along the Antwerp-Rotterdam chemical corridor, where integrated service agreements now outnumber traditional purchase orders for heat exchanger replacements.
Welded Spiral Heat Exchangers Market Segmentation
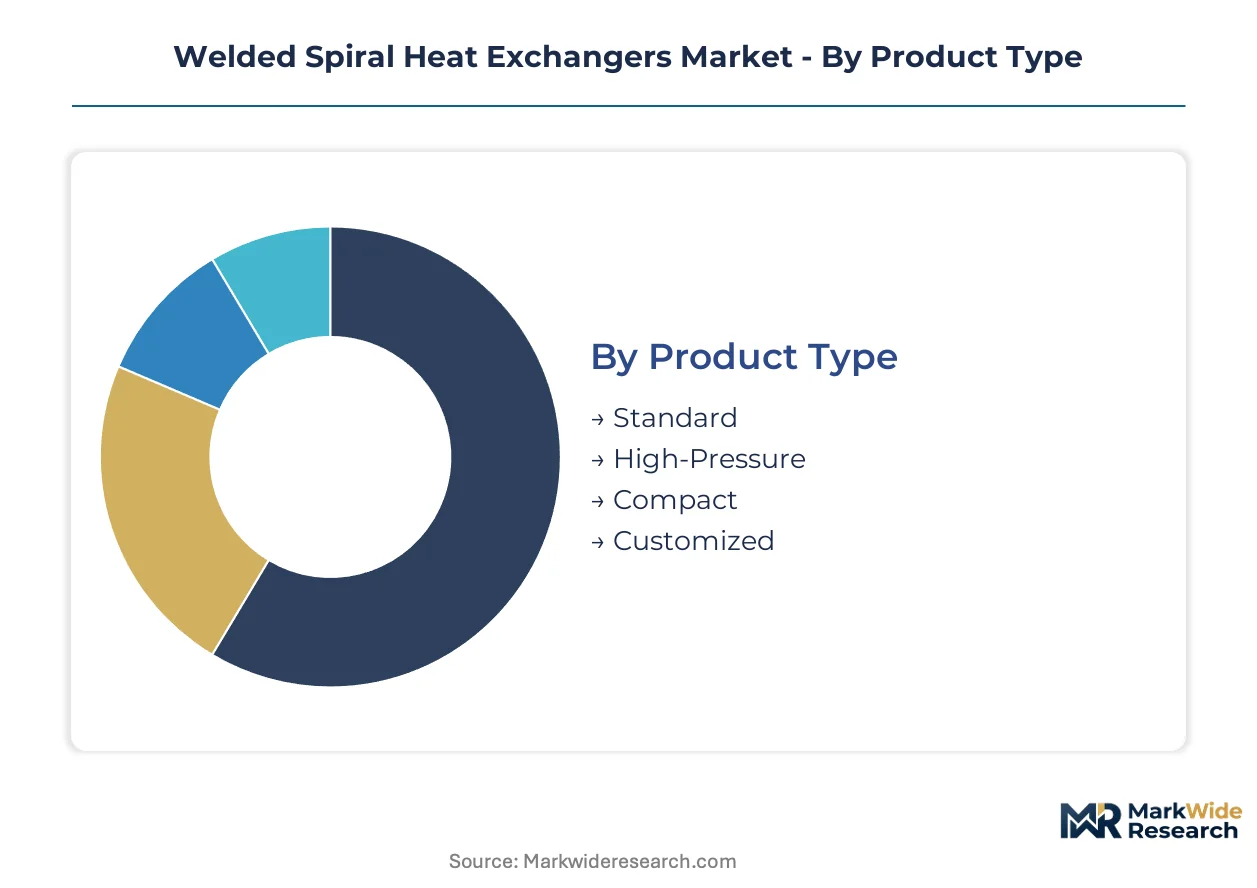
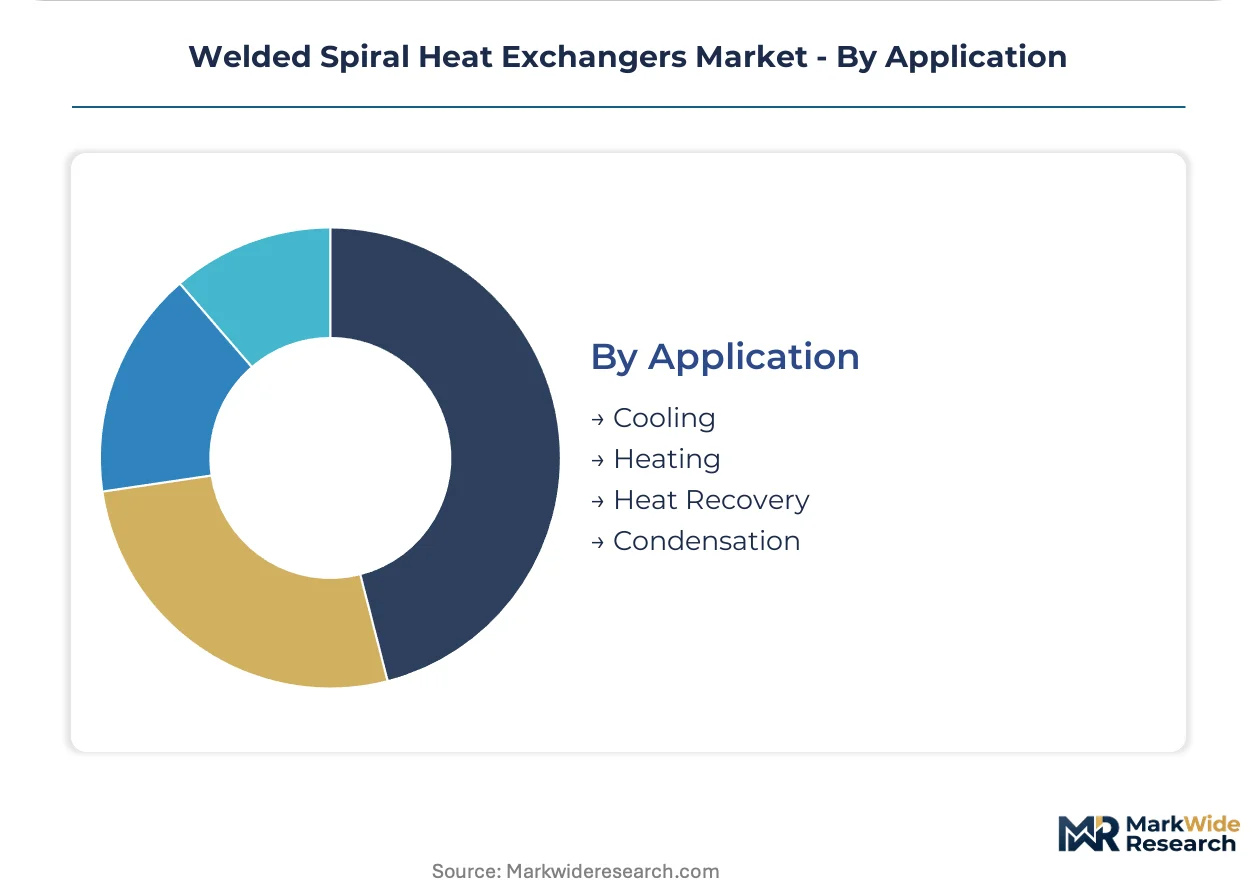
Welded spiral heat exchanger procurement splits across four dimensions that each reshape supplier engagement models. Product type determines engineering intensity and margin structure. Material selection governs corrosion resistance specifications and alloy cost exposure. End user concentration drives geographic demand clustering. Application scope defines thermal duty requirements and fouling tolerance thresholds.
Product Type:
Buyers differentiate primarily by pressure rating requirements and customization depth rather than catalog availability.
- Standard:Off-the-shelf configurations with fixed channel gaps and pressure ratings serve maintenance replacement cycles in mature process facilities. Rhine corridor chemical processors in Germany favor these units for scheduled turnarounds where thermal duty profiles remain unchanged.
- High-Pressure:Units rated for extreme pressure differentials employ thicker spiral plate stock and full-penetration weld seams. Hydrogen liquefaction pilot projects and supercritical CO2 carbon capture installations specify these variants where channel geometry tolerates mechanical stress concentrations.
- Compact:Reduced footprint designs target space-constrained retrofit installations in urban district heating substations. Dutch municipal heating operators specify these for building basement replacements where shell-and-tube removal access is restricted.
- Customized:Site-specific thermal-hydraulic optimization with variable channel gaps and asymmetric flow configurations. Belgium and Netherlands engineering procurement organizations now demand guaranteed heat transfer coefficients over 5-year operating windows for these engineered units.
Standard configurations lead volumes today; customized designs are gaining share fastest.
Material:
Alloy procurement decisions hinge on chloride exposure severity and weldability trade-offs that fabrication shops must resolve.
- Stainless Steel:Austenitic grades dominate current procurement due to balanced chloride resistance and weldability. ASME Section VIII fabrication shops in Texas and Louisiana rely on 316L stock for sour gas processing duties where hydrogen sulfide exposure is moderate.
- Carbon Steel:Lower-cost option for non-corrosive thermal duties in clean utility applications. Indian specialty chemical zones under PLI scheme incentives specify carbon steel for cooling water loops where metallurgical upgrade budgets are constrained.
- Alloy:Hastelloy and Inconel variants command premium positioning for aggressive acid service. Nickel price volatility compresses fabrication margins and deters speculative inventory building by mid-sized North American fabricators.
- Copper:High thermal conductivity suits clean fluid applications in food processing and potable water systems. EU F-Gas Regulation compliance timelines are compressing replacement cycles for copper-channel units in refrigeration duty.
Stainless steel leads volumes today; alloy grades are climbing the fastest.
End User:
Industry verticals impose distinct certification, documentation, and lifecycle service requirements on suppliers.
- Oil & Gas:Upstream separation and downstream refining duties demand ASME Section VIII certification with full material traceability. Gulf Coast petrochemical complexes specify welded spiral units for crude preheating trains where fouling resistance reduces cleaning frequency.
- Chemical Processing:Aggressive acid and solvent service drives corrosion-resistant alloy specifications. Antwerp-Rotterdam chemical corridor buyers now contract for outcome-based thermal performance guarantees rather than equipment-only transactions.
- Power Generation:Flue gas heat recovery and cooling water applications favor standard configurations with predictable pressure drop characteristics. German lignite plant retrofits under emissions compliance deadlines are accelerating replacement demand.
- Food & Beverage:Conservative engineering specifications in legacy dairy applications resist specification changes despite demonstrated fouling advantages. USDA and FDA sanitary standards constrain channel geometry options for pasteurization duties.
Chemical processing leads volumes today; power generation is expanding most quickly.
Application:
Thermal duty type determines fouling tolerance, temperature approach requirements, and control system integration complexity.
- Cooling:Rejection of process heat to cooling water or ambient air represents the largest installed base. Self-cleaning shear stress from spiral geometry reduces maintenance intervals in cooling tower loop applications.
- Heating:Process fluid preheating duties require precise temperature control and low approach temperatures. District heating network operators in Denmark specify welded spiral units for return line temperature boosting.
- Heat Recovery:Waste heat capture from exhaust streams or hot process effluents. EU Carbon Border Adjustment Mechanism preparation is forcing mill-source documentation upgrades for recovered heat duty units.
- Condensation:Vapor-to-liquid phase change duties with high latent heat transfer coefficients. Netherlands chemical processors deploy these for solvent recovery where counter-current flow maximizes thermal efficiency.
Cooling leads volumes today; heat recovery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates replacement demand along petrochemical corridors while India attracts fabrication investment through localization incentives. The United States maintains stringent certification requirements that favor established suppliers. China scales domestic production for chemical processing self-sufficiency.
Germany
Petrochemical clusters along the Rhine corridor execute coordinated replacement programs for corrosion-resistant welded spiral units. The EU F-Gas Regulation compresses equipment turnover schedules, forcing early retirement of shell-and-tube systems. BASF and Bayer facilities in Ludwigshafen and Leverkusen anchor concentrated demand bursts for high-pressure alloy configurations.
United States
Gulf Coast refineries specify ASME Section VIII certified units for crude preheating trains with fouling resistance requirements. EPA emissions standards and OSHA process safety management protocols elevate compliance documentation burdens. Texas and Louisiana process facilities drive procurement volumes for sour gas processing duties using 316L stainless steel fabrications.
China
Dual carbon goals under MIIT industrial policy accelerate heat recovery installations in steel and cement sectors. GB standards for pressure equipment harmonize with international codes while favoring domestic certification bodies. Yangtze River Delta chemical processors expand welded spiral adoption for solvent recovery and condensation duties.
India
PLI scheme incentives for process equipment localization attract joint ventures with stainless steel fabricators. BIS pressure vessel standards create conformity assessment pathways for domestic suppliers. Gujarat and Maharashtra specialty chemical zones drive demand for cost-optimized carbon steel cooling configurations.
Netherlands
Antwerp-Rotterdam chemical corridor buyers contract for outcome-based thermal performance guarantees over five-year operating windows. ECHA REACH compliance requirements govern material traceability for alloy components. Port of Rotterdam hydrogen liquefaction pilot projects specify high-pressure welded spiral geometries for extreme differential tolerance.
Welded Spiral Heat Exchangers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with engineering-intensive customized configurations concentrating around established European fabricators while standardized replacements fragment across regional metalworking shops. The vendor base organizes into three archetypes: integrated thermal solution providers with installed base service arms, alloy-specialist fabricators with notified body relationships, and regional job shops serving maintenance turnarounds. Consolidation pressure operates through vertical integration of heat transfer design capability and geographic expansion via distribution partnerships.
Among Nordic-based integrated specialists, Alfa Laval AB anchors recurring service income models across process industries. Danfoss A/S occupies a position within district heating retrofit channels. Gooch Thermal Systems, Inc. exemplifies the North American custom-engineering archetype for chemical processor specifications. These three represent distinct competitive vectors: service-anchored retention, channel-controlled retrofit access, and application-specific engineering intensity.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Danfoss A/S |
| Gooch Thermal Systems, Inc. |
| Nexson Group |
| Kelvion Holding GmbH |
| Kurose Chemical Equipment Co., Ltd. |
| Shanghai Shenglin M&E Technology Co., Ltd. |
| Tranter International Inc. |
| API Heat Transfer |
| Others |
Value Chain & Pricing Dynamics
ASME-certified welder concentrations in Texas and Louisiana create labor-cost differentials that widen pricing-tier spreads between premium certified fabrications and standard-grade alternatives. Regional wage premiums for qualified pressure vessel welders under ASME Section VIII protocols compress margins for US-focused suppliers while enabling European and Asian competitors to capture mid-market share through lower labor-input costs.
Pricing Analysis
Capacity additions in India under PLI scheme incentives are reshaping price floors for carbon steel cooling configurations. Three-tier pricing structure across premium certified, standard ASME-grade, and economy non-certified levels separates project-based engineered units from catalog replacements. Price differentiation centers on ASME Section VIII certification tier and alloy grade specification. Pricing pressure stems from nickel alloy cost volatility in Hastelloy and Inconel grades. Chemical processors in mature European markets exhibit lowest price sensitivity due to outcome-based contracting requirements, while Indian specialty chemical zones under PLI incentives drive highest price sensitivity.
Supply Chain Analysis
Ocean freight cost volatility from Asian alloy mills to European fabrication centers amplifies total landed cost uncertainty for corrosion-resistant units. Supply concentrates in Germany, China, and India for spiral plate fabrication, with stainless steel strip mills in South Korea and Japan feeding raw material inputs. The supply chain draws from nickel alloy producers in Australia and Indonesia, stainless steel mills in China and South Korea, and specialized welding consumable suppliers in Germany and the United States. Single-source vulnerability around EU notified body certification creates procurement bottlenecks for new market entrants. Distribution runs through direct engineering sales for customized configurations and regional distributors for standard replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The welded spiral heat exchanger market functions as a stable compounder anchored by regulatory-forced replacement cycles under EU F-Gas Regulation phasedown schedules. Equipment turnover mandates create predictable demand visibility across European process industries regardless of macroeconomic cyclicality.
For Market Incumbents: Cement installed base retention through preventive maintenance contract bundling and remote thermal monitoring subscription anchoring. Deepen backward integration into alloy mill relationships to buffer nickel price volatility exposure. Fortify notified body certification relationships against EU Pressure Equipment Directive bottlenecks that threaten new entrant expansion. For New Entrants and Emerging Players: Enter via hydrogen refueling station pre-cooling specifications where 700-bar design standards remain unsettled and first-mover demonstration advantages secure multi-year framework agreements. Target Indian specialty chemical zones under PLI scheme localization incentives through joint ventures with domestic stainless steel fabricators. Pursue additive manufacturing prototyping velocity as a competitive wedge for pilot-scale trial conversion. For Investors and Strategic Acquirers: Integrated thermal solution providers with installed base service arms are the most active acquirer in this space, seeking alloy-specialist fabricators with established notified body relationships. The market supports long-term compounder viability through regulatory-forced replacement cycles and outcome-based contracting reconfiguration. Acquisition target archetype: regional custom-engineering shops with chemical processor relationships and ASME Section VIII certification infrastructure. Monitor EU Carbon Border Adjustment Mechanism implementation timing as inflection indicator for near-shore fabrication preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive sourcing from nickel producers in Australia buffers margin compression from Hastelloy price volatility. |
| Additive Manufacturing Capability Buildout | Laser powder bed fusion of stainless steel flow distributors compresses prototyping cycles from 20 weeks to 8 weeks. |
| Remote Thermal Monitoring Platform Launch | IoT sensor deployment enables predictive maintenance subscriptions that extend customer lifetime value beyond equipment margins. |
| Notified Body Relationship Expansion | EU Pressure Equipment Directive certification partnerships unlock access to Rhine corridor replacement demand bursts. |
| Hydrogen Refueling Pre-Cooling Standardization | First-mover establishment of 700-bar heat exchanger design conventions secures multi-year framework agreements. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and maintenance directors, procurement lead surveys at chemical processors, and aftermarket service head consultations — were reconciled against secondary validation from ASME Boiler and Pressure Vessel Code documentation, EU Pressure Equipment Directive regulatory filings, customs trade data on alloy component imports, and SEC filings from listed thermal equipment suppliers. Bottom-up unit shipment estimates by product type and material grade were triangulated against top-down market value reconstruction across end-user verticals.
Data-stream reconciliation across primary field intelligence and secondary source validation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, material grade specification, end-user industry vertical, thermal duty application, and regional regulatory cluster. CAGRs were derived from regression analysis of replacement cycle timing, regulatory compliance deadlines, and capacity expansion announcements. Industry-specific forecast inputs incorporated EU F-Gas Regulation phasedown schedules and ASME Section VIII welder certification pipeline constraints.
The model holds under stable regulatory enforcement timelines and alloy price mean-reversion assumptions; deviation in EU Carbon Border Adjustment Mechanism implementation pace or sustained nickel supply disruption would shift replacement demand geography and margin structure. Forecasts reflect documented assumptions regarding notified body certification capacity and hydrogen infrastructure deployment velocity. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
US HVAC Services Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Thermocompressors Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
US HVAC Systems Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
Industrial Air Blower Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Combustion Controls, Equipments and Systems Market