
 Heating Equipment Market | 2026-2036
Heating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Heating Equipment Market Intelligence
Modular system architecture is decoupling heating generation from distribution hardware, letting buyers mix heat pumps with third-party hydronic controls. Bosch Thermotechnology leverages captive compressor production to anchor premium positioning in European markets. Carrier Global competes through extensive service-channel control across North American commercial accounts. Midea Group dominates cost-optimized manufacturing of electric furnaces for Asian residential exports.
Heating equipment comprises engineered thermal energy systems designed to raise indoor or process temperatures through combustion, electric resistance, or vapor-compression cycles, typically rated by output capacity in BTU/hr or kilowatts and minimum efficiency thresholds. These systems serve residential comfort, commercial space conditioning, and industrial process heat requirements. Heat pumps now represent the fastest-expanding product category as electrification mandates tighten across multiple jurisdictions. Natural gas retains the largest installed base but faces margin compression where carbon pricing expands. High-efficiency condensing boilers command premium pricing in retrofit markets with strict building codes.
The EU F-Gas Regulation and EPA refrigerant phase-down rules are reshaping product design requirements for heat pump manufacturers seeking cross-border market access. China's GB energy-efficiency standards and NMPA-equivalent equipment certification processes govern import eligibility for foreign boiler and furnace suppliers. Stakeholders must track how refrigerant chemistry transitions and efficiency tier upgrades interact with local installation workforce capacity.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant options while China's district heating expansion concentrates procurement volumes, forcing manufacturers to reconcile divergent chemistry standards with scale economies.
Growth Catalysts
- Electrification Mandates:Germany's Building Energy Act requires renewable heating in new residential construction, accelerating heat pump specification rates among municipal housing developers.
- Refrigerant Chemistry Transition:The EPA's phasedown of HFCs under AIM Act rules is redirecting R&D spending toward propane and CO₂ vapor-compression architectures.
- Urban District Heating:China's northern provinces are expanding centralized heat networks, concentrating boiler and heat pump demand within state-owned utility procurement frameworks.
Market Restraints
- Copper and Rare Earth Volatility:Compressor manufacturing depends on copper winding and neodymium magnet supply chains concentrated in Chinese processing facilities.
- Installation Workforce Bottlenecks:Certified heat pump technicians remain scarce in rural German regions and Midwestern US states, extending project timelines.
- Natural Gas Infrastructure Lock-In:Existing pipeline networks and furnace installed bases in Poland and the Netherlands create substitution friction for electrification retrofits.
Strategic Opportunities
- Hybrid System Configurations:Pairing air-source heat pumps with thermal storage buffers addresses cold-climate performance gaps in Scandinavian residential markets.
- Service Channel Disintermediation:Direct-to-installer digital platforms are bypassing traditional wholesale distributors for spare parts and control modules.
- Industrial Process Heat:High-temperature heat pumps using steam compression cycles are penetrating food processing and chemical manufacturing applications.
Industry Challenges
- Refrigerant Handling Certification:F-Gas qualified technician shortages in France and Italy delay deployment timelines for R32 and R290 systems.
- Legacy Control Integration:Proprietary communication protocols between heat pumps and third-party building management systems require middleware development.
- Testing Laboratory Capacity:GB standard certification queues for Chinese market entry extend product launch schedules by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heating Equipment Market |
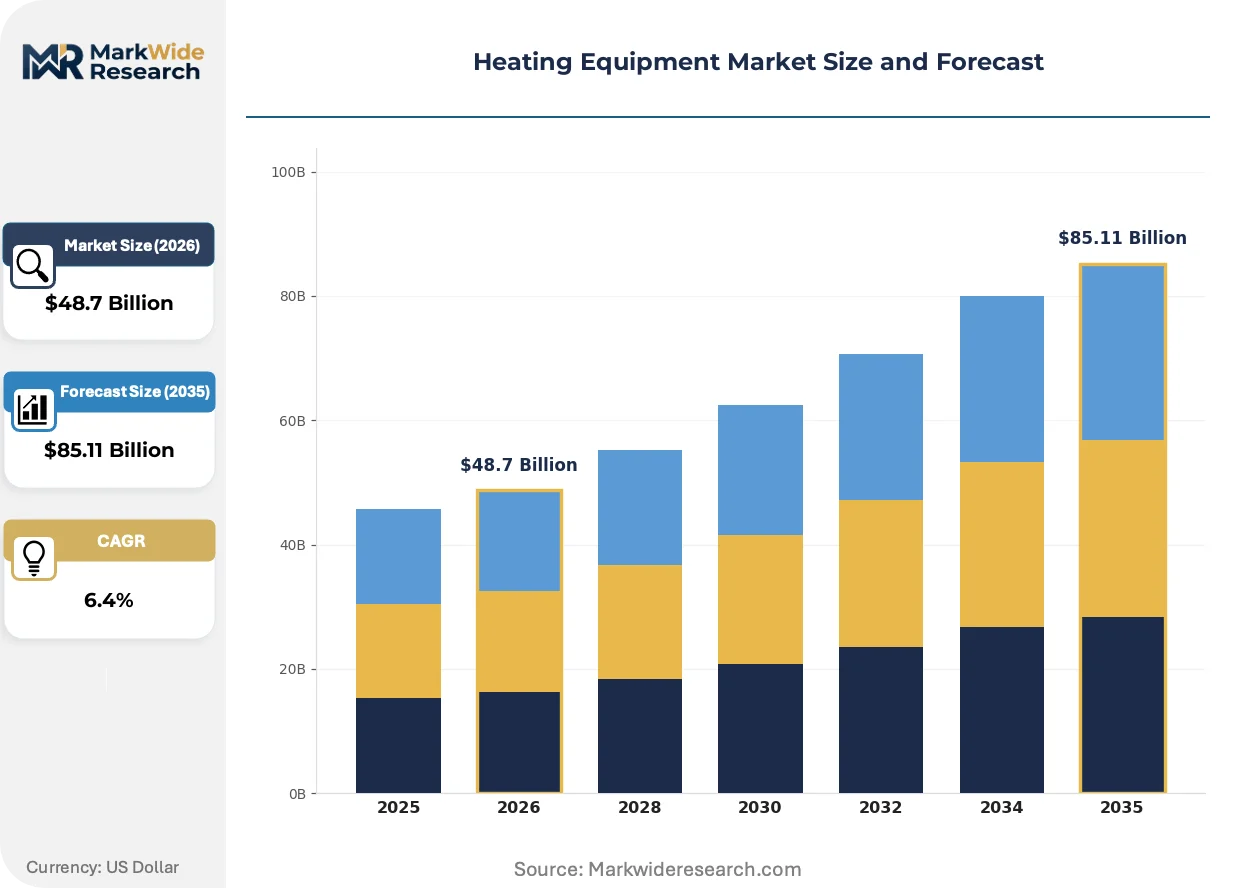
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boilers, Furnaces, Heat Pumps, Radiant Heaters Fuel Type: Natural Gas, Electric, Oil, Biomass Thermal Efficiency: High Efficiency, Mid Efficiency, Low Efficiency, Condensing End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Mitsubishi Electric, Johnson Controls, Daikin Industries, Bosch Thermotechnology, Rheem Manufacturing, Carrier Global, Lennox International, Midea Group, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heating Equipment Market Strategic Shifts & Innovations
Refrigerant chemistry transitions and modular system architectures are converging to decouple hardware manufacturing from installation-site configuration decisions.
CO₂ transcritical heat pump cycles are absorbing market attention for commercial hot water and space conditioning applications in temperate climates. Japanese and Korean equipment buyers are specifying these systems for supermarket and hotel retrofits. The technology is absorbing engineering talent from conventional HFC platform development, compressing legacy product roadmaps.
The EU F-Gas Regulation's quota allocation mechanism is forcing refrigerant portfolio consolidation among multinational manufacturers. Production lines in Poland and the Czech Republic are retooling for lower-GWP alternatives. Residential air-to-water heat pumps face the steepest compliance cost escalation, prompting price tier compression between premium and mid-range offerings.
Building developers are unbundling equipment procurement from installation contracts, treating heat pumps as commodity hardware while retaining specialized firms for hydronic design. German and Austrian residential project developers pioneered this split-contract model. The practice is now penetrating Dutch commercial new-build specifications, compressing margins for full-service HVAC contractors.
Heating Equipment Market Segmentation
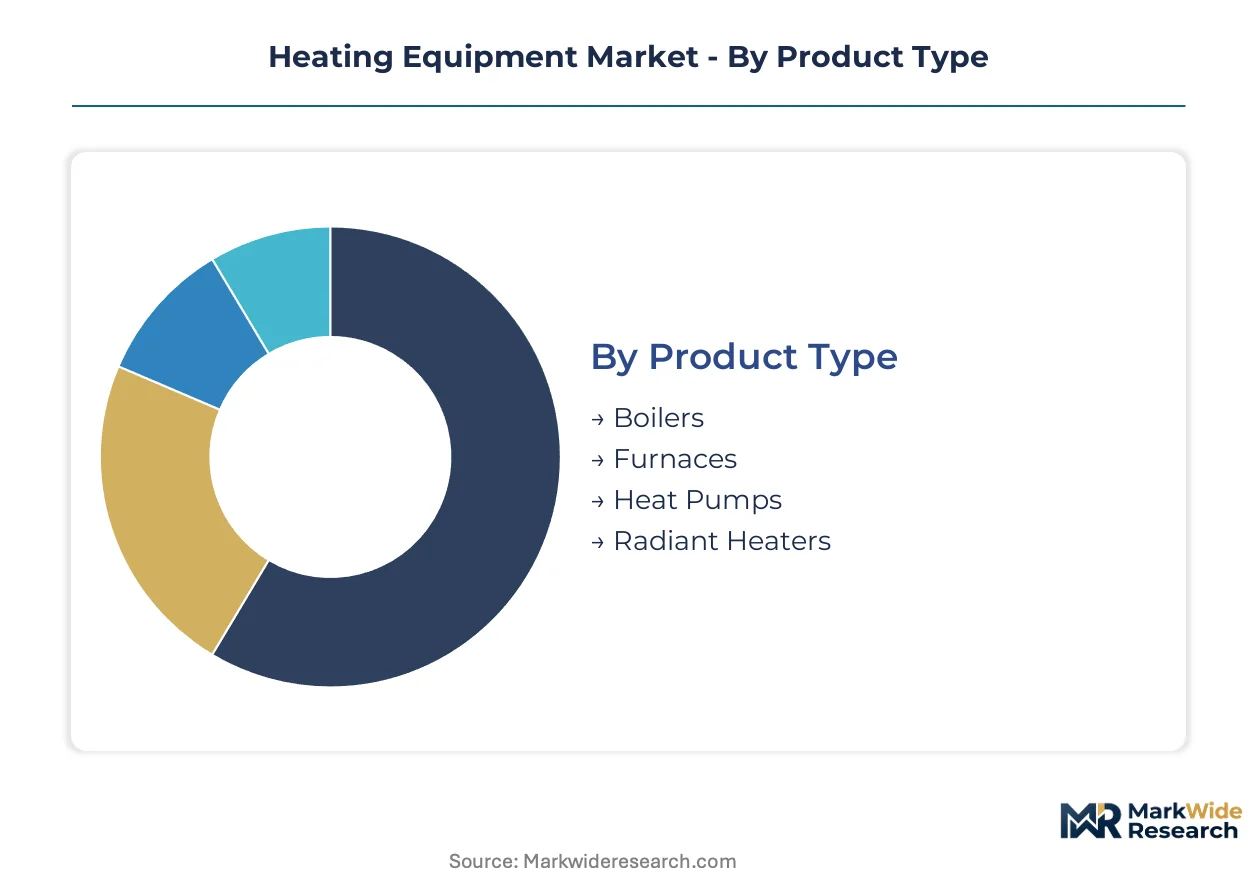
Segmentation in heating equipment reveals divergent capital requirements and margin structures across product architectures. Fuel transitions and efficiency regulations are fragmenting traditional procurement patterns while creating new competitive battlegrounds.
Product Type:
Capital intensity varies sharply across product architectures, with compressor-based systems demanding the highest upfront manufacturing investment.
- Heat Pumps:Vapor-compression systems using refrigerant cycles transfer ambient thermal energy indoors, requiring precision-machined compressors and electronic expansion valves. German municipal housing developers specify these systems under renewable heating mandates, though certified installation capacity bottlenecks constrain deployment velocity.
- Boilers:Pressurized vessels generate hot water or steam through combustion or electric resistance, rated by thermal output and seasonal efficiency metrics. China's northern provinces concentrate procurement through state-owned district heating utilities, absorbing high volumes of gas-fired and electric boiler capacity.
- Furnaces:Forced-air combustion systems distribute heated air through ductwork, dominant in North American residential construction. Mid-efficiency units face margin compression as regional efficiency codes tighten.
- Radiant Heaters:Infrared and hydronic panel systems deliver localized thermal comfort without forced air circulation. Industrial warehouses and agricultural facilities specify these for spot heating applications.
Most installed capacity flows through Boilers. Expansion is steepest in Heat Pumps.
Fuel Type:
Customer procurement patterns cluster around three cost tiers: subsidized electrification, legacy hydrocarbon infrastructure, and emerging bioenergy alternatives.
- Electric:Resistance elements and vapor-compression cycles deliver thermal energy without on-site combustion. Scandinavian residential markets pair air-source heat pumps with thermal storage buffers to address cold-climate performance gaps.
- Natural Gas:Methane combustion retains the largest installed base globally, though carbon pricing in the Netherlands and Poland creates substitution friction for electrification retrofits.
- Oil:Liquid petroleum derivatives serve rural and off-grid installations where pipeline infrastructure remains absent. Northeastern US states and Atlantic Canada retain significant deployed base.
- Biomass:Pellet and chip combustion systems utilize renewable solid fuels for residential and light commercial applications. Austrian and Czech districts specify these where local forestry supply chains support fuel logistics.
Natural Gas retains dominant installed capacity. Electric systems are gaining share fastest where grid capacity and policy incentives align.
Thermal Efficiency:
Margin structures compress toward premium tiers as building codes mandate minimum performance thresholds across major markets.
- Condensing:Systems recover latent heat from exhaust gases through secondary heat exchangers, achieving thermal efficiencies above ninety percent. German and Austrian retrofit markets command premium pricing for these units under strict building energy codes.
- High Efficiency:Equipment meets or exceeds regional performance standards without full condensing architecture. EU F-Gas Regulation compliance costs concentrate in this tier, prompting portfolio consolidation.
- Mid Efficiency:Conventional combustion systems occupy price-sensitive replacement markets where code grandfathering permits continued installation. Volume manufacturing concentrates in cost-optimized Asian export hubs.
- Low Efficiency:Legacy atmospheric combustion units face phase-out schedules across multiple jurisdictions, surviving only in regulatory exemption zones.
Condensing technology commands premium pricing in retrofit markets. High Efficiency systems represent the fastest-growing trajectory as code minimums ratchet upward.
End User:
Application-specific thermal load profiles dictate equipment specification, with industrial process heat demanding the most customized engineering.
- Industrial:Process heat systems serve manufacturing operations requiring precise temperature control and high thermal output. Food processing and chemical manufacturing applications are absorbing high-temperature heat pump development.
- Commercial:Space conditioning and hot water systems serve retail, hospitality, and office facilities. Japanese and Korean supermarket and hotel retrofits specify CO₂ transcritical heat pump cycles.
- Residential:Single-family and multi-family dwellings specify comfort heating and domestic hot water systems. German residential builders are unbundling equipment procurement from installation contracts, treating heat pumps as commodity hardware.
- Institutional:Schools, hospitals, and government facilities procure through extended tender processes with life-cycle cost evaluation criteria.
Residential applications absorb highest unit volumes. Industrial process heat is climbing the fastest as electrification penetrates manufacturing thermal loads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central European engineering traditions established modern heating equipment manufacturing during the 19th century industrial expansion, with subsequent scaling in Northeast Asian production corridors during the late 20th century. Contemporary demand clusters around electrification policy zones and district heating infrastructure investments.
United States
Forced-air furnace replacement cycles and commercial building retrofits drive equipment procurement across Midwestern and Southern states. EPA refrigerant phase-down rules under AIM Act provisions redirect manufacturer R&D spending toward lower-GWP alternatives. Atlanta and Dallas-Fort Worth metropolitan areas concentrate HVAC contractor networks and distribution warehousing for residential heat pump deployment.
Germany
Municipal housing developers specify heat pump systems under Building Energy Act renewable heating mandates, accelerating specification rates in new construction. EU F-Gas Regulation quota allocations compress refrigerant options for domestic manufacturers. The Ruhr industrial corridor and Bavarian manufacturing clusters host retooling production lines for propane and CO₂ vapor-compression architectures.
China
Northern province urbanization expands centralized district heating networks, concentrating boiler and heat pump procurement through state-owned utility frameworks. GB energy-efficiency standards and NMPA-equivalent certification govern import eligibility for foreign suppliers. Beijing-Tianjin-Hebei and Yangtze River Delta urban agglomerations absorb highest volumes of gas-fired and electric boiler capacity.
Japan
Commercial facility retrofits specify CO₂ transcritical heat pump cycles for supermarket and hotel applications in temperate climate zones. METI efficiency standards and JIS certification requirements shape product development priorities. Osaka-Kansai and Nagoya-Chubu industrial corridors concentrate engineering talent migration from conventional HFC platform development.
Netherlands
Carbon pricing mechanisms and natural gas infrastructure phase-out timelines create substitution friction for residential electrification retrofits. EU Green Deal implementation accelerates building code efficiency tier upgrades. Randstad urban clusters concentrate certified heat pump technician training programs and hydronic system design specialist firms.
Heating Equipment Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive component manufacturing capabilities. Market concentration remains moderate with distinct tiering between premium European engineering houses and scale-driven Asian exporters. Three strategic archetypes dominate: integrated manufacturers controlling compressor production, service-channel operators leveraging installation network density, and cost-optimized volume producers serving price-sensitive replacement markets. Capacity expansion and refrigerant chemistry transitions constitute the dominant competitive moves across all tiers.
Among diversified industrial groups, Bosch Thermotechnology and Carrier Global exemplify contrasting strategic positions, while Midea Group occupies the scale-driven export tier. Bosch Thermotechnology leverages captive compressor manufacturing to anchor premium positioning. Carrier Global competes through extensive service-channel control. Midea Group dominates cost-optimized manufacturing for Asian residential exports.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| Johnson Controls |
| Daikin Industries |
| Bosch Thermotechnology |
| Rheem Manufacturing |
| Carrier Global |
| Lennox International |
| Midea Group |
| Trane Technologies |
| Others |
Cost & Logistics Intelligence
German municipal housing developers unbundling equipment procurement from installation contracts are treating heat pumps as commodity hardware, forcing manufacturers to absorb margin compression or differentiate through captive component production. This buyer-driven commoditization concentrates pricing power with scale producers while fragmenting margins for full-service contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment sales, with differentiation anchored in compressor manufacturing origin and F-Gas certification tier. Premium European engineering houses command spreads through captive production in Ruhr and Bavarian clusters, while mid-tier offerings face cost compression from EU refrigerant quota allocations. Price erosion runs through standard-tier residential air-to-water systems as Polish and Czech retooling investments mature. Municipal procurement frameworks in China exhibit lowest price sensitivity; rural German replacement markets show highest.
Supply Chain Analysis
Dual-sourcing mandates from state-owned Chinese district heating utilities and German municipal developers require manufacturers to qualify secondary compressor suppliers, extending certification timelines. Production gravity centers on China, Germany, and Poland, with precision-machined compressors and electronic expansion valves drawing from Taiwanese semiconductor foundries and Chinese rare earth processing. Single-source vulnerability concentrates in neodymium magnet supply chains. Distribution runs through wholesale HVAC distributors in North America, direct-to-installer platforms in Germany, and state utility procurement frameworks in northern China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant chemistry transitions and modular system architectures are compressing legacy product roadmaps while expanding premium-tier addressable market for integrated manufacturers with captive compressor production.
For Market Incumbents: Deepen backward integration into compressor manufacturing to defend margin position against commodity hardware pricing pressure from Asian exporters. Retool Polish and Czech production lines for propane and CO₂ architectures ahead of EU F-Gas quota tightening. Anchor premium positioning through F-Gas qualified technician training partnerships in France and Italy. For New Entrants and Emerging Players: Specialized hydronic controls firms bypassing traditional wholesale distributors offer partnership entry points into German and Dutch residential new-build specifications. White-space concentration sits with thermal storage buffer integration for Scandinavian cold-climate retrofits and high-temperature heat pump development for food processing applications. Direct-to-installer digital platforms provide lowest-friction go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists controlling captive compressor production and F-Gas certification infrastructure. Long-term viability favors integrated manufacturers over pure-play distributors as equipment commoditization accelerates. Monitor GB standard certification queue lengths as inflection signal for Chinese market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production in Ruhr and Bavarian clusters anchors premium pricing power against Asian volume exporters. |
| Refrigerant Portfolio Retooling | Polish and Czech production lines shifting to propane and CO₂ cycles secure EU F-Gas Regulation compliance. |
| Direct-to-Installer Platform Launch | Digital spare parts distribution bypasses wholesale intermediaries in German and Dutch specification markets. |
| Thermal Storage Buffer Integration | Pairing air-source heat pumps with storage addresses Scandinavian cold-climate performance gaps. |
| F-Gas Technician Certification Investment | Training partnerships in France and Italy accelerate deployment timelines for R32 and R290 systems. |
Research Approach
Coverage spans Germany, China, the United States, Japan, and the Netherlands, with primary inputs from each market cluster combining interviews with HVAC contractor network managers, municipal procurement officers, compressor manufacturing engineers, and hydronic system design specialists. Secondary validation draws from EPA AIM Act filings, EU F-Gas Regulation quota allocation records, Chinese GB standard certification databases, and METI efficiency standard disclosures. Bottom-up equipment shipment data triangulates against top-down district heating investment flows.
Rate-of-change decomposition separates volume growth from mix-shift and pricing trajectory across the analysis window. Segmentation dimensions model product architecture, fuel type, thermal efficiency tier, and end-use application. CAGRs derive from installed base replacement cycles, electrification mandate penetration curves, and refrigerant transition cost pass-through assumptions. Compressor manufacturing capacity utilization and F-Gas qualified technician density serve as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and rare earth price volatility, installation workforce expansion rates, and natural gas infrastructure phase-out policy revisions. Deviation in Chinese district heating procurement volumes or EU F-Gas quota enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Air Volume Controllers Market