
 GCC Green Buildings Market | 2026-2036
GCC Green Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Green Buildings Market Insights
Project procurement channels across the GCC are tilting toward design-build and integrated project delivery models that bundle green certification with construction contracts. BASF SE leverages its regional chemical manufacturing footprint to supply low-VOC coatings and insulation systems tailored to desert climates. Kingspan Group plc anchors its position through controlled distribution of insulated panel systems that meet Estidama and LEED thermal performance thresholds. AECOM competes by embedding energy modeling and sustainability consulting into early-stage master planning for giga-projects across Saudi Arabia.
Green buildings in the GCC are structures designed, constructed, and operated to minimize environmental impact through reduced energy consumption, water efficiency, and sustainable material selection, typically achieving thermal transmittance values below 0.3 W/m²K for envelope assemblies in cooling-dominated climates. Their primary purpose is to lower operational carbon intensity while maintaining occupant comfort in extreme heat conditions exceeding 45°C ambient temperatures. The certification standard dimension shows LEED and Estidama dominating developer preferences, with Estidama gaining ground in Abu Dhabi-mandated projects where Pearl Rating compliance is compulsory for new construction permits. Material type segmentation reveals energy-efficient glass and recycled steel capturing expanding share as facade specifications tighten under revised green building codes in Dubai and Riyadh.
Saudi Arabia's Saudi Building Code and the UAE's Estidama framework, alongside LEED accreditation requirements, collectively shape product specifications and contractor eligibility for public-sector developments. The country's national construction regulator and municipal planning authorities in Dubai and Abu Dhabi enforce progressive energy-performance thresholds that filter market access for foreign material suppliers. Stakeholders must monitor how evolving carbon disclosure rules and cooling-load reduction mandates redefine competitive advantage across specification chains.
Market Dynamics
Estidama Pearl Rating System mandates are compressing project timelines and forcing early-stage energy modeling into master planning contracts across Abu Dhabi and Dubai developments.
Growth Catalysts
- Estidama compliance mandates:Abu Dhabi's municipal planning authorities require Pearl Rating certification for all new construction permits, creating non-negotiable demand for certified materials and design consultants.
- Cooling-load reduction targets:Saudi Arabia's national building codes are tightening thermal transmittance thresholds for envelope assemblies in Riyadh and Jeddah commercial towers.
- Giga-project pipelines:Saudi Vision 2030 developments in NEOM and the Red Sea Project are embedding LEED and Saudi Green Building Forum standards into procurement specifications.
Market Restraints
- High-performance glass import dependency:Energy-efficient glazing with low solar heat gain coefficients relies on European and East Asian manufacturing, exposing projects to currency and shipping volatility.
- Specialized contractor scarcity:The GCC lacks sufficient quantity of commissioning agents and energy modelers certified for complex desert-climate simulations.
- Recycled steel specification gaps:Regional steel producers maintain limited EPD-verified production lines, forcing developers to absorb premium costs for imported structural materials.
Strategic Opportunities
- Kuwait and Oman penetration:These markets currently operate below 15% green-certified stock and lack mandatory rating systems, offering first-mover positioning as regulations mature.
- Integrated project delivery expansion:Design-build contracts bundling certification consulting with construction are displacing traditional design-bid-award sequences in Dubai commercial developments.
- Passive cooling convergence:Mashrabiya-inspired facade systems combined with phase-change materials are opening new specification categories for heritage-responsive high-performance envelopes.
Industry Challenges
- Commissioning agent shortages:Projects face 6-12 month delays securing professionals qualified for Estidama and LEED thermal performance verification in cooling-dominated climates.
- Multi-certification complexity:Developers pursuing simultaneous LEED, Estidama, and Saudi Green Building Forum ratings encounter conflicting documentation requirements and overlapping audit timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Green Buildings Market |
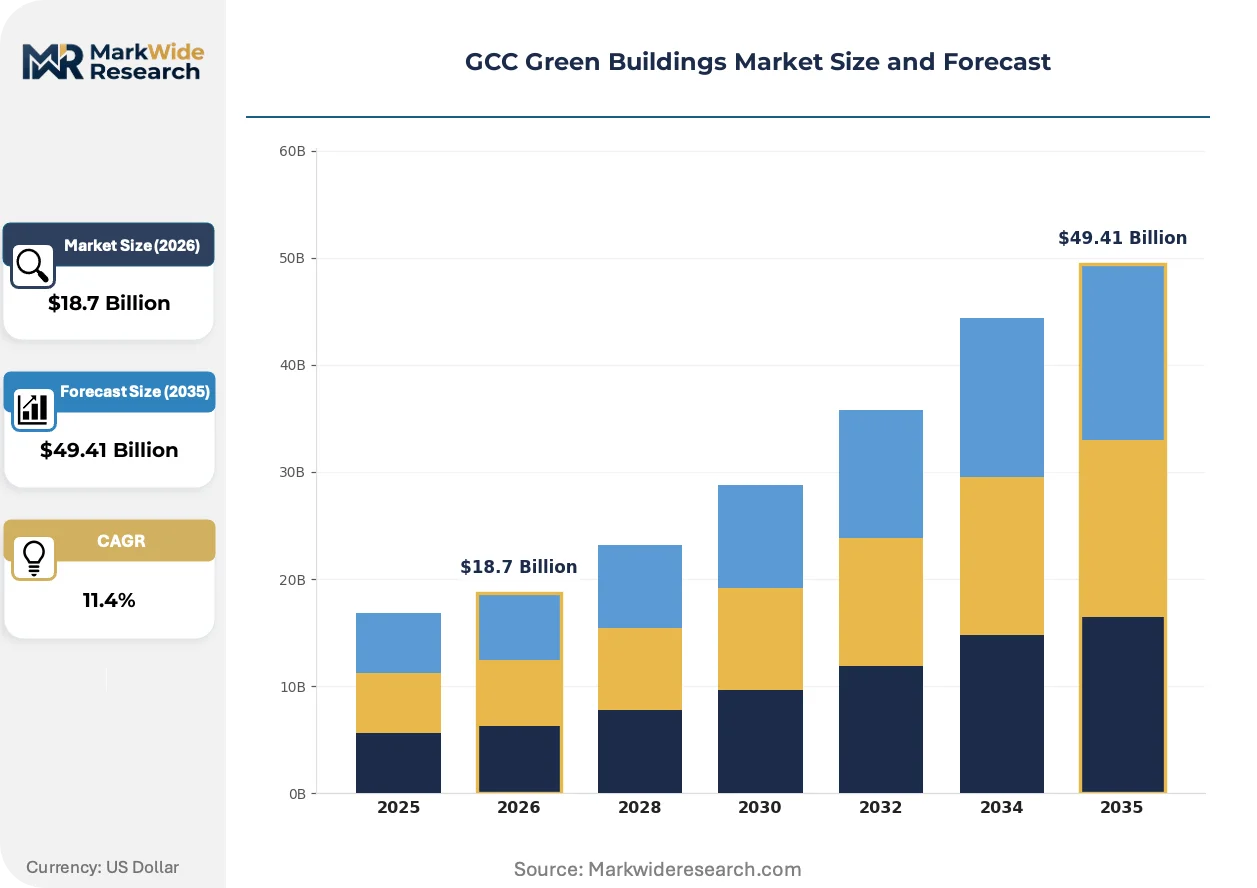
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Industrial, Institutional Material Type: Recycled Steel, Bamboo, Low-VOC Paints, Energy-Efficient Glass Certification Standard: LEED, BREEAM, Green Star, Estidama Technology Adoption: Solar Panels, Smart HVAC, Rainwater Harvesting, Energy Management Systems |
| Companies Covered | Forbo International SA, BASF SE, Alumasc Group plc, Owens Corning, DuPont de Nemours Inc, Kingspan Group plc, Interface Inc, AECOM, Bauder Limited, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Green Buildings Market Trends and Innovations
Building envelope technologies and procurement contracting models are undergoing rapid recalibration as thermal performance mandates tighten and project delivery timelines compress across the Gulf.
Electrochromic glazing systems dynamically modulate solar heat gain based on real-time irradiance data, eliminating the need for external shading devices in high-rise towers. Dubai-based commercial developers are specifying these systems for premium office assets at accelerating rates. Conventional static low-E glass with fixed performance specifications is rendering obsolete for Class A developments seeking Pearl 3+ ratings.
Saudi Arabia's Saudi Building Code is introducing mandatory energy disclosure requirements for commercial properties above 5,000 square meters, mirroring EU CSRD carbon reporting frameworks. This regulatory shift forces asset owners to install sub-metering infrastructure and disclose operational carbon intensity to prospective tenants. Riyadh's central business district office stock faces the steepest compliance burden as retrofit deadlines approach.
Master developers in the GCC are consolidating material procurement through approved vendor lists that pre-qualify suppliers based on EPD documentation and regional manufacturing presence. This buyer concentration is squeezing independent distributors and favoring chemical and insulation producers with captive GCC production assets. The pattern is most pronounced in Dubai's sustainable city megaprojects where developer-led consortiums negotiate volume contracts directly with envelope system manufacturers.
GCC Green Buildings Market Segmentation
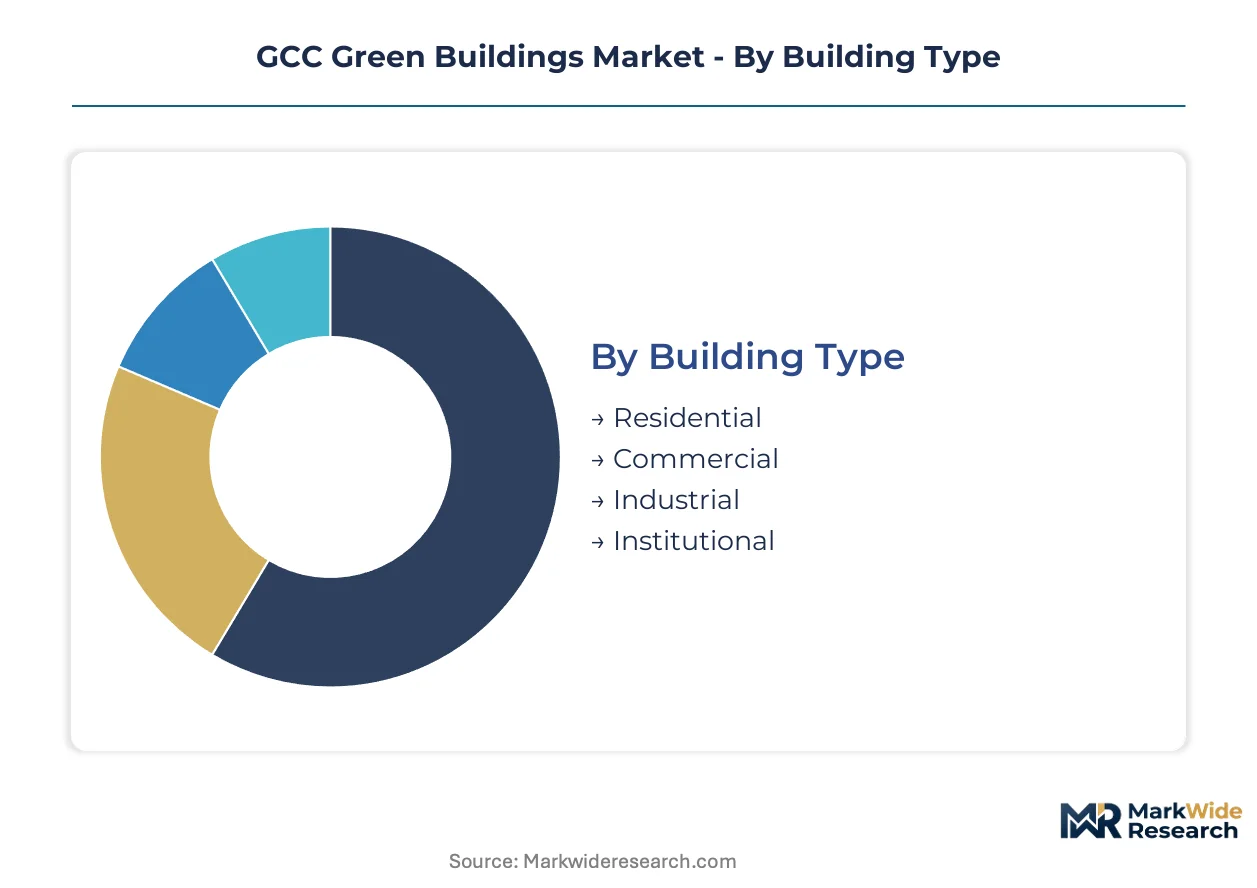
Segmentation in the GCC green buildings market reveals how procurement priorities diverge across project scales and certification pathways. Developers align material specifications and technology investments with the compliance intensity of their target building category.
Building Type:
Commercial towers turn over specifications fastest as developers chase Estidama Pearl ratings for leasing premiums, while institutional projects cycle slowest due to extended public procurement timelines.
- Residential:Villa compounds and mid-rise apartment blocks in Dubai's sustainable city corridors specify low-VOC coatings and enhanced envelope insulation to meet municipality thermal codes. Demand clusters in master-planned communities where developers bundle green certification with sales positioning.
- Commercial:High-rise office and retail assets in Riyadh and Abu Dhabi drive the steepest specification upgrades as landlords seek Pearl 3+ ratings for tenant attraction. Cooling-load reduction mandates from Saudi Arabia's national building codes are compressing facade procurement cycles.
- Industrial:Warehouse and logistics facilities in Jeddah's port zones adopt solar PV and recycled steel framing to satisfy corporate sustainability commitments from multinational tenants.
- Institutional:Government complexes and healthcare facilities in Kuwait and Oman face extended design phases but embed the most stringent multi-certification requirements.
Commercial dominates installed base. Residential is where expansion concentrates.
Material Type:
Cost tiers separate specification accessibility: premium imports command facade positions while regional production anchors structural applications.
- Recycled Steel:Structural framing with EPD-verified recycled content faces supply bottlenecks as regional mills lack certified production lines. Projects in NEOM and the Red Sea development absorb import premiums for compliance with Saudi Green Building Forum standards.
- Energy-Efficient Glass:Low solar heat gain coefficient glazing with dynamic electrochromic capability is displacing static low-E specifications in Abu Dhabi's Class A commercial towers. European and East Asian manufacturing dependence exposes projects to currency volatility.
- Bamboo:Engineered bamboo flooring and interior finishes serve boutique hospitality and residential projects seeking biophilic design differentiation with lower embodied carbon than conventional timber.
- Low-VOC Paints:Desert-formulated coatings from regional chemical producers meet Estidama indoor air quality thresholds for schools and healthcare facilities across Dubai and Sharjah.
Energy-efficient glass captures the highest specification value. Recycled steel faces the steepest supply constraints.
Certification Standard:
Volume flows toward mandatory systems while voluntary standards attract premium project positioning.
- Estidama:Abu Dhabi's compulsory Pearl Rating for all new construction permits creates non-negotiable demand across building categories. Dubai developers voluntarily pursue Pearl certification to signal quality in competitive leasing markets.
- LEED:The most widely recognized international standard anchors Saudi Vision 2030 giga-project specifications and multinational corporate mandates. Riyadh commercial towers increasingly require LEED Gold minimum for anchor tenant commitments.
- BREEAM:UK-origin certification maintains niche presence among British-educated developer teams and specific institutional investor requirements in Qatar and Bahrain.
- Green Star:Australian-derived standard sees limited GCC adoption, primarily in education and healthcare projects with Australian contractor involvement.
Estidama dominates permit-driven volume. LEED is climbing the fastest among voluntary certifications.
Technology Adoption:
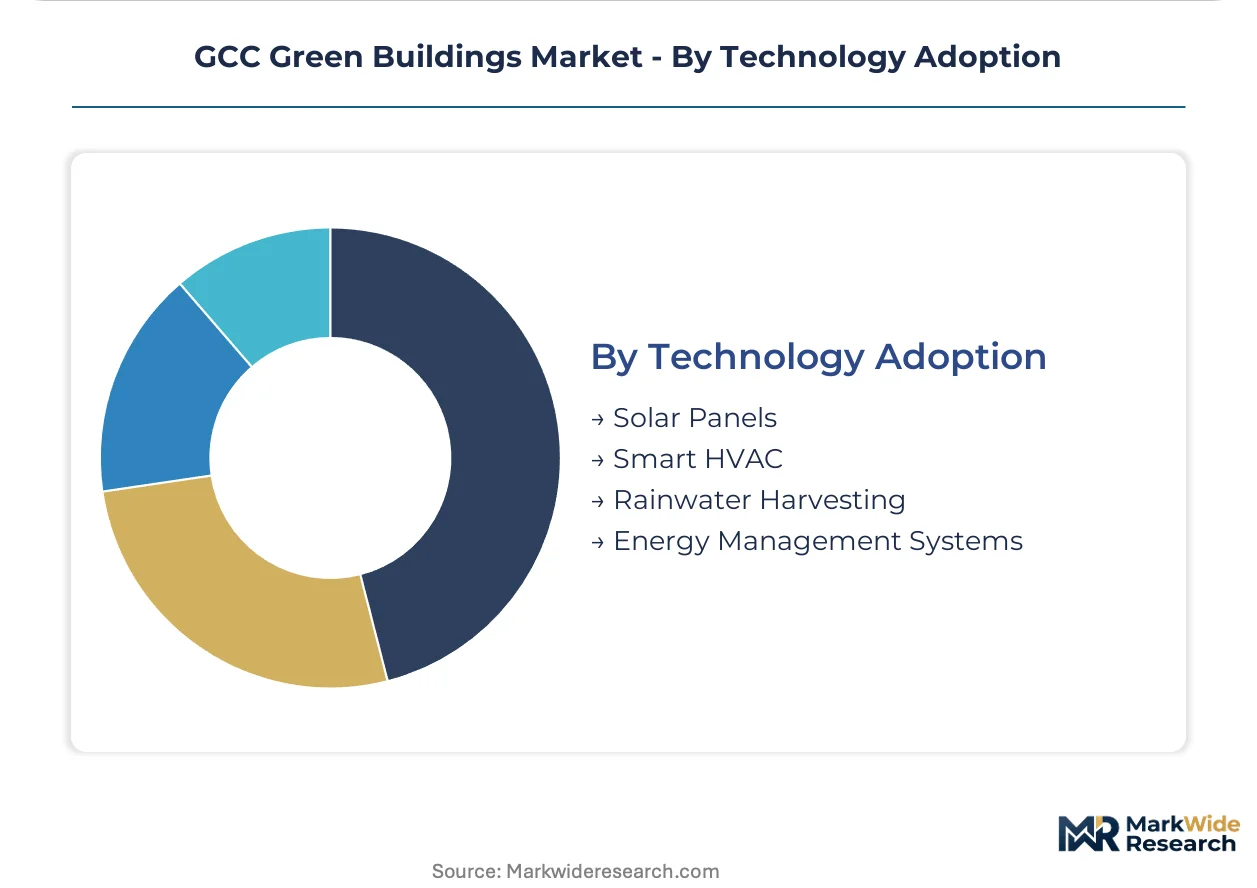
Application context determines deployment speed: envelope-integrated systems move slower than plug-in operational technologies.
- Smart HVAC:Variable refrigerant flow systems with demand-controlled ventilation and IoT-enabled fault detection are becoming baseline for commercial towers in Dubai's central business district. Saudi building codes mandate sub-metering infrastructure that enables optimization.
- Solar Panels:Rooftop and facade-integrated photovoltaic arrays serve net-zero aspirations in NEOM and Masdar City developments. Procurement concentrates through developer-approved vendor lists that favor regional manufacturing presence.
- Energy Management Systems:Building automation platforms with real-time carbon disclosure capabilities are mandatory for Saudi commercial properties above 5,000 square meters under new energy disclosure rules.
- Rainwater Harvesting:Greywater recycling and storage infrastructure addresses water scarcity in Qatar and Bahrain residential compounds, though deployment lags behind energy-focused technologies.
Smart HVAC dominates operational technology spend. Solar panels are gaining share fastest as giga-project pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC electricity grid interconnector network underwrites regional green building deployment by enabling shared renewable energy certificates across member states. Saudi Arabia's 2,400 km East-West power corridor and the UAE's Al Sweihan solar array feed clean electrons into construction supply chains. National building codes now mandate thermal performance thresholds that vary by cooling-degree-day exposure.
Saudi Arabia
Riyadh's commercial tower pipeline and NEOM giga-projects absorb the bulk of high-performance envelope imports. The Saudi Building Code enforcement by the national construction regulator tightens thermal transmittance thresholds for envelope assemblies above 20 stories. Jeddah's King Abdullah Economic City clusters specification demand for LEED Gold minimums among multinational anchor tenants.
United Arab Emirates
Abu Dhabi's Estidama Pearl Rating mandates create non-negotiable demand for certified materials across all new construction permits. Dubai's Sustainable City and Masdar developments concentrate procurement through developer-approved vendor lists that pre-qualify suppliers on EPD documentation. Sharjah's municipal authority is adopting adapted Pearl Rating thresholds for mid-rise residential stock.
Qatar
Doha's Lusail City development embeds QSAS certification requirements into infrastructure contracts for the 2022 World Cup legacy districts. The Qatar General Organization for Standardization enforces green building standards for government complexes above 10,000 square meters. Ras Laffan's industrial zone pilots solar-integrated warehouse specifications for petrochemical logistics tenants.
Kuwait
Kuwait City's Sabah Al-Ahmad Sea City represents the flagship sustainable development in a market below 15% green-certified stock. The Public Authority for Housing Welfare issues guidelines rather than mandates, leaving certification voluntary for private developers. Al-Zour's refinery expansion district is testing BREEAM In-Use protocols for operational industrial assets.
Oman
Muscat's Sultan Qaboos University medical city anchors institutional green building adoption in the absence of mandatory national rating systems. The Ministry of Housing and Urban Planning encourages Pearl-equivalent performance through subsidized financing for certified residential projects. Duqm's special economic zone offers tariff exemptions for developers achieving third-party environmental verification.
GCC Green Buildings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply. The GCC green buildings market structures around three tiers: global chemical conglomerates with regional manufacturing footprints, specialized envelope system producers with controlled distribution networks, and engineering consultancies embedding sustainability verification into master planning contracts. Consolidation pressure runs highest among insulation and coating suppliers as developer consortiums negotiate volume contracts directly. Strategic moves center on backward integration into regional feedstock sourcing and captive production of EPD-documented structural materials.
Within the chemical supply archetype, BASF SE anchors its position through desert-formulated low-VOC coating production at GCC manufacturing assets. Kingspan Group plc exemplifies the controlled distribution model for insulated panel systems meeting Estidama thermal thresholds. AECOM occupies the consultancy tier by embedding energy modeling and Pearl Rating compliance into early-stage giga-project planning across Saudi Vision 2030 developments.
| Leading Market Players |
|---|
| Forbo International SA |
| BASF SE |
| Alumasc Group plc |
| Owens Corning |
| DuPont de Nemours Inc |
| Kingspan Group plc |
| Interface Inc |
| AECOM |
| Bauder Limited |
| Others |
Pricing and Supply Chain Analysis
The Jebel Ali-Dammam maritime corridor's freight cost volatility shapes GCC green building material procurement, compressing margins for imported high-performance glazing while amplifying price premiums for regional producers with captive manufacturing assets. Supply concentration in Saudi Arabia's eastern industrial zone and the UAE's Jafza free trade area creates tiered pricing power that downstream developers navigate through volume consolidation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Estidama Pearl 3+ certified envelope systems from Pearl 2 baseline specifications and uncertified conventional materials. Certification grade and volume scale drive price differentiation, with bulk procurement by NEOM and Red Sea Project master developers commanding 15-20% discounts off list. Pricing pressure stems from European electrochromic glass import dependency exposing projects to euro-dirham volatility. Public-sector institutional buyers exhibit highest price sensitivity due to fixed-budget procurement protocols, while private commercial developers in Dubai's Class A office segment absorb premiums for leasing differentiation.
Supply Chain Analysis
Export control regimes on advanced coating technologies and low-emissivity glass manufacturing equipment limit technology transfer to GCC production facilities, constraining regional supply expansion. Manufacturing concentrates in Germany, South Korea, and China for energy-efficient glazing systems, while Saudi Arabia and the UAE anchor regional insulation and coating production. Supply chains draw from silica sand feedstock, petrochemical-derived polymers, and aluminum extrusions. Single-source vulnerability runs through European electrochromic glass suppliers with no qualified regional alternatives. Distribution runs through developer-approved vendor lists that pre-qualify suppliers on EPD documentation, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC green buildings sit in early-cycle expansion as mandatory Estidama and Saudi Building Code adoption accelerates specification upgrades across construction permits. Penetration remains below 20% in Kuwait and Oman, leaving substantial runway for certified material demand.
For Market Incumbents: Build switching-cost moats through captive EPD documentation and Estidama pre-certification of entire product lines. BASF SE and Kingspan Group plc should deepen backward integration into regional feedstock sourcing to defend against import volatility. Threat from Chinese electrochromic glass producers entering through Dubai free zones demands accelerated Pearl Rating pre-approval investments. Capacity addition in Saudi Arabia's Jubail industrial city anchors supply security for Vision 2030 giga-project pipelines.
For New Entrants and Emerging Players: Mid-market commercial buildings in Kuwait City and Muscat represent the most penetrable entry point given sub-15% green-certified stock and absence of mandatory rating systems. Oman's Duqm special economic zone tariff exemptions offer regulatory arbitrage for third-party environmental verification. Boutique hospitality projects seeking biophilic bamboo finishes provide niche positioning. Go-to-market through engineering consultant partnerships embedding material specifications into early-stage master planning contracts bypasses procurement gatekeeper concentration.
For Investors and Strategic Acquirers: Carve-out targets emerge from European building envelope specialists with stranded GCC distribution assets seeking regional manufacturing partnerships. Long-term viability hinges on regulatory ratchet effects tightening thermal performance thresholds across cooling-dominated climates. Acquisition archetype: mid-cap insulation producers with EPD-verified production lines and existing Pearl Rating compliance. Signal to watch is Saudi Arabia's national construction regulator mandating embodied carbon disclosure for structural steel, which would force regional mill upgrades and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Feedstock | BASF SE's captive GCC chemical production secures supply continuity for desert-formulated low-VOC coatings against import volatility. |
| Estidama Pre-Certification Investment | Early Pearl Rating compliance locks in specification preference for Abu Dhabi's mandatory permit-driven construction pipeline. |
| Developer-Approved Vendor List Positioning | Direct volume contracts with Dubai Sustainable City consortiums displace independent distributor margins. |
| EPD Documentation Infrastructure | Environmental product declaration verification opens access to Saudi Green Building Forum procurement specifications. |
| Commissioning Agent Capability Buildout | Certified energy modeler scarcity creates 6-12 month project bottlenecks that trained workforce expansion resolves. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Saudi Building Code regulatory filings, and Estidama Pearl Rating certification databases. Primary interviews engaged sustainability consultants at AECOM, procurement directors at NEOM development consortiums, and envelope system specification engineers at Dubai-based master developers. Secondary validation drew from UAE Ministry of Energy and Infrastructure disclosures, Saudi General Authority for Statistics construction indices, and GCC electricity grid interconnector utilization reports. Bottom-up project pipeline enumeration triangulates against top-down construction spending forecasts.
Forecast inputs span building type segmentation across residential, commercial, industrial, and institutional categories; certification standard adoption curves for Estidama, LEED, and Saudi Green Building Forum; material type specification shares for energy-efficient glass, recycled steel, and low-VOC coatings; and technology adoption rates for smart HVAC and solar PV integration. CAGRs derive from regression analysis of permit issuance trends, thermal performance mandate phase-in schedules, and giga-project procurement timelines. Cooling-load reduction targets and carbon disclosure rule evolution anchor scenario boundaries.
Stress conditions across euro-dirham exchange rate volatility, electrochromic glass shipping disruption, and Saudi Building Code enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory ratchet speed and master developer consolidation trajectories. Material shifts in GCC electricity grid decarbonization pace or Pearl Rating mandate expansion to Kuwait and Oman would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Malaysia Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
3D Printing Building Construction Market
Building Construction
UAE Facade Market
Building Construction
China Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Energy-Efficient Building Market
Building Construction
France Prefab Wood Building Market
Building Construction
El Salvador Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Prefabricated Construction Market
Building Construction
Poland Construction Market
Building Construction
Indonesia Prefabricated Buildings Market