
 Air Volume Controllers Market | 2026-2036
Air Volume Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Air Volume Controllers Market Analysis
High-efficiency smart control tiers is collapsing the price premium that once separated electromechanical from electronic actuation in commercial specifications. Johnson Controls leverages its building automation platform to bundle controller sales with software services. Siemens anchors European project pipelines through its certification depth under EN 1751 and ISO 9001 quality protocols. Daikin Industries dominates Asian supply with manufacturing scale across Japan and China.
Air volume controllers regulate airflow distribution in ducted HVAC and cleanroom environments through damper modulation, typically achieving pressure-independent operation within 5-10% of setpoint across 0.5-3.0 inches water column differential. Variable Air Volume configurations lead commercial retrofit demand where zone-level thermal control cuts fan energy consumption against constant volume alternatives. Smart Controls technology is capturing margin pools as electromechanical units commoditize in residential and light commercial tiers. Multi-Duct controllers sustain premium positioning in hospital and pharmaceutical cleanroom applications where redundancy requirements exclude simpler architectures.
ASHRAE Standard 90.1 in the United States and the EU Energy Performance of Buildings Directive together mandate minimum airflow efficiency thresholds that disqualify legacy pneumatic installations from new construction and major renovation. The EPA Energy Star program and equivalent EU Ecodesign regulations extend these requirements to equipment certification, creating compliance costs that favor established suppliers with testing infrastructure. Stakeholders must weigh the pace of smart control penetration against the residual installed base of pneumatic systems still operating within grandfathered facilities.
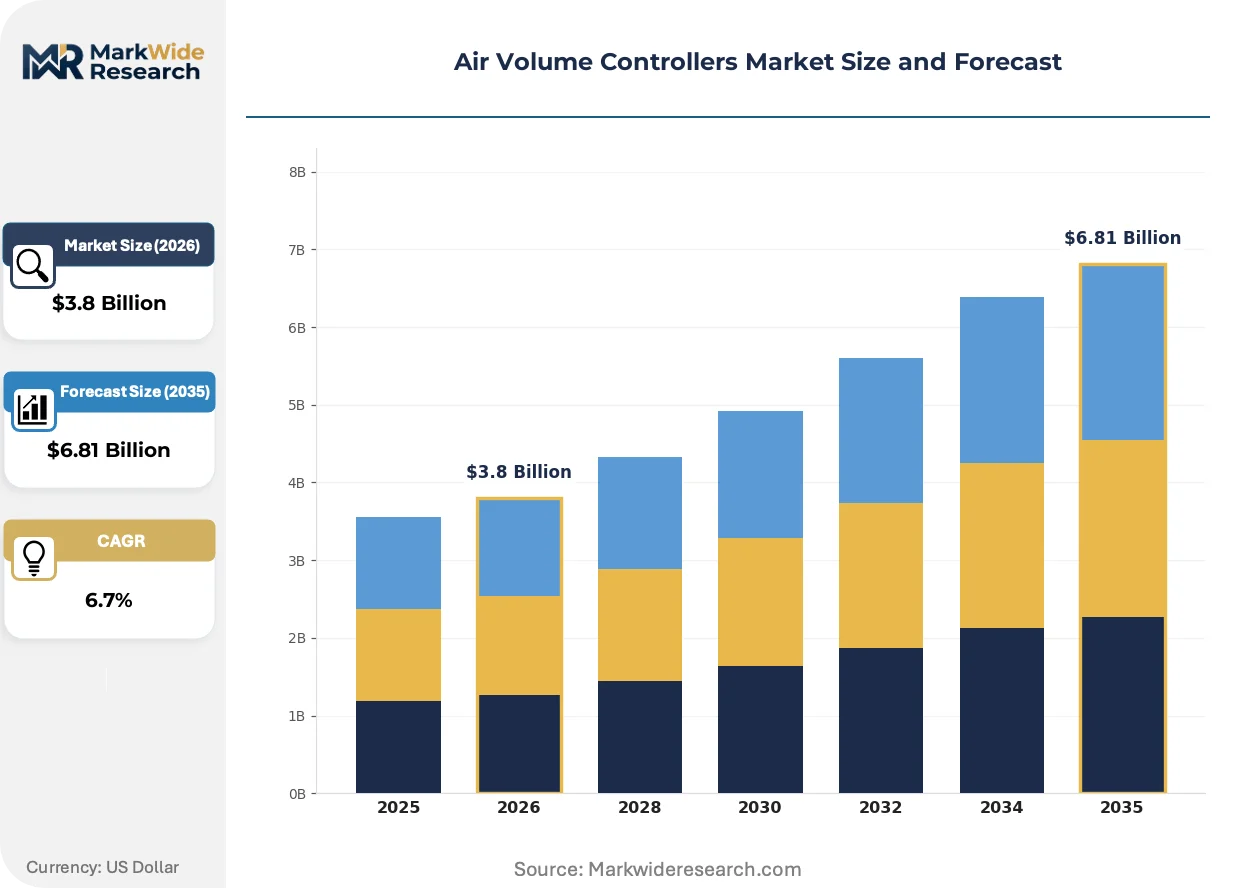
Market Dynamics
The transition from pneumatic to electronic actuation is compressing specification tiers as smart controls absorb functionality once delivered through separate building automation layers, collapsing the traditional electromechanical-electronic price gap.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Retrofit mandates across Germany, France, and Italy are accelerating replacement of legacy pneumatic installations in commercial buildings.
- Cleanroom redundancy requirements:Pharmaceutical manufacturing expansion in Singapore and Switzerland is driving specification of multi-duct controller architectures.
- Zone-level thermal optimization:Variable Air Volume configurations are cutting fan energy consumption in U.S. commercial retrofits against constant volume alternatives.
Market Restraints
- Copper and rare earth input volatility:Electronic actuator manufacturing faces cost pressure from magnet material supply concentration.
- Testing infrastructure barriers:EPA Energy Star and EU Ecodesign certification costs disadvantage smaller suppliers without captive laboratories.
- Pneumatic system residual base:Grandfathered facilities in Japan and the United States delay full electronic conversion cycles.
Strategic Opportunities
- Software service bundling:Building automation platforms are opening controller sales through predictive maintenance subscriptions.
- Hospital HVAC renovation:Infection control upgrades in Canadian and Australian healthcare facilities are specifying pressure-independent operation.
- Dual carbon compliance:China's MEE efficiency mandates are creating specification windows for smart-controlled units in new construction.
Industry Challenges
- Controls integration complexity:BACnet and Modbus protocol interoperability demands specialized commissioning expertise.
- ASHRAE 90.1 compliance timelines:Documentation burden for airflow efficiency thresholds extends project approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Volume Controllers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Duct, Multi-Duct, Variable Air Volume, Constant Air Volume Application: HVAC Systems, Industrial Ventilation, Building Automation, Clean Rooms End User: Commercial Buildings, Residential Properties, Manufacturing Plants, Educational Institutions Technology: Electromechanical, Pneumatic, Electronic, Smart Controls |
| Companies Covered | Johnson Controls, Schneider Electric, Siemens, Trane Technologies, Systemair, Lennox International, Honeywell International, Daikin Industries, TROX GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Volume Controllers Market Emerging Trajectories
Digital twin integration is reshaping how air volume controllers are specified, commissioned, and serviced across commercial building portfolios.
Mesh networking for damper-level communication is fragmenting the traditional star-topology dependency on centralized building automation panels. Facility managers in Nordic commercial portfolios are piloting wireless actuator coordination. This topology is fragmenting hardware procurement patterns as zone-level intelligence reduces panel density requirements.
The EU F-Gas Regulation is tightening refrigerant containment requirements that indirectly elevate airtightness standards for ducted HVAC components. Controller specifications now integrate leakage monitoring as a bundled function. Pharmaceutical cleanroom projects in the Netherlands and Belgium are leading this specification shift.
Performance contracting is altering how controllers are procured in U.S. federal building retrofits. Energy Service Companies now specify and own equipment through guaranteed savings arrangements. This model is compressing upfront capital requirements for municipal infrastructure agencies.
Air Volume Controllers Market Segmentation
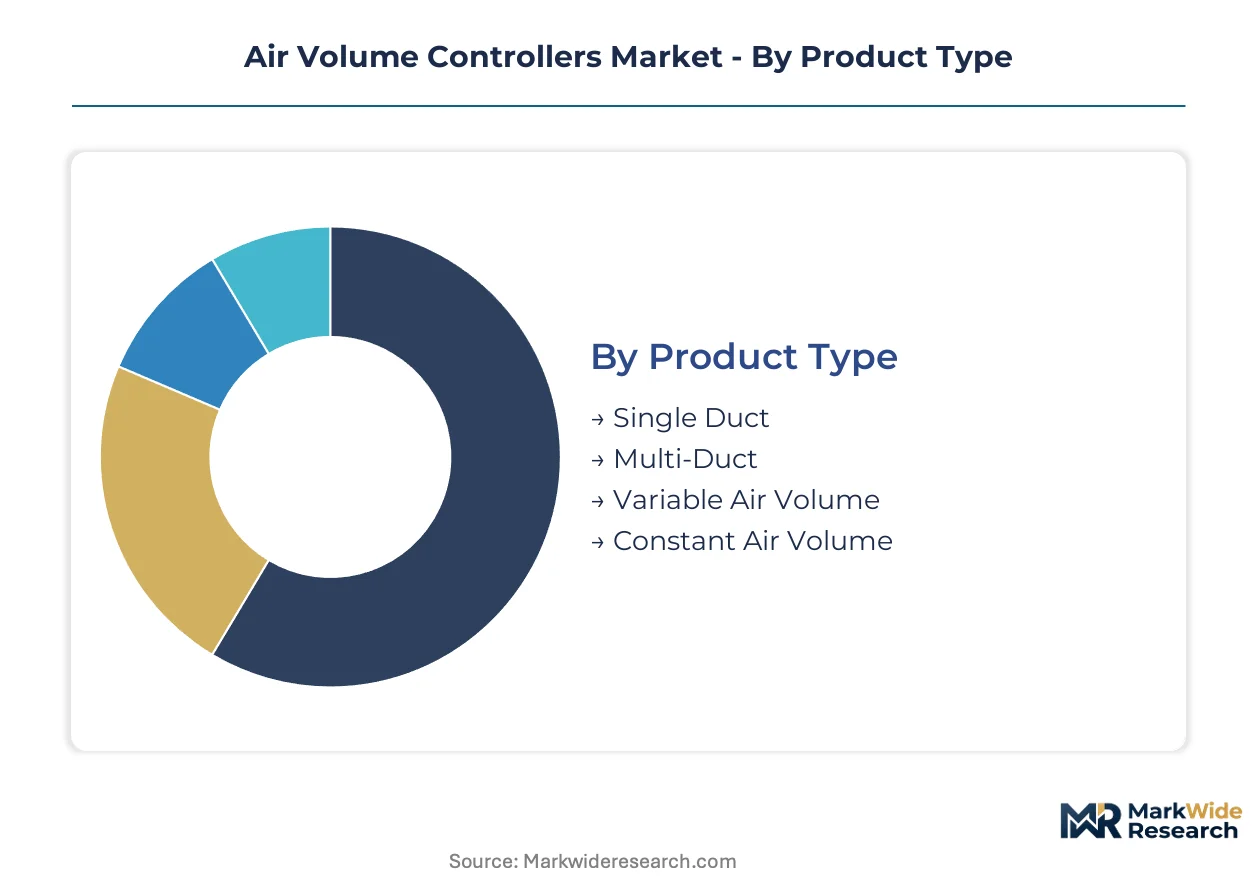
Segmentation in air volume controllers reveals how specification tiers align with building energy codes and retrofit cycles. Product architecture, application environment, and control technology each create distinct procurement patterns across commercial and industrial verticals.
Product Type:
Variable Air Volume and Multi-Duct units dominate export-led demand from German and Swiss manufacturing bases, while Single Duct and Constant Air Volume configurations serve price-sensitive domestic retrofit markets in North America and Asia-Pacific.
- Variable Air Volume:Zone-level damper modulation enables pressure-independent airflow regulation across 0.5-3.0 inches water column differential. Demand concentrates in U.S. commercial retrofits where ASHRAE 90.1 mandates displace legacy constant volume systems in federal and municipal buildings.
- Multi-Duct:Redundant airflow pathways serve pharmaceutical cleanrooms and hospital operating suites requiring uninterrupted pressurization. Swiss and Singaporean manufacturing expansion is driving specification of these architectures where single-point failure risks are unacceptable.
- Single Duct:Simplified damper assemblies serve light commercial and residential tiers where cost compression favors electromechanical actuation over electronic alternatives.
- Constant Air Volume:Fixed airflow delivery persists in grandfathered industrial ventilation and legacy educational infrastructure where full system replacement is capital-constrained.
Variable Air Volume holds the largest share; momentum sits with Multi-Duct as cleanroom redundancy requirements expand.
Application:
Cost tier stratification separates premium cleanroom specifications from commoditized HVAC retrofits, with building automation integration commanding mid-tier pricing.
- HVAC Systems:Ducted climate control in commercial buildings represents the volume base, with smart-controlled units capturing margin as electromechanical alternatives commoditize in residential tiers.
- Clean Rooms:Pharmaceutical and semiconductor manufacturing demand airtight damper coordination with leakage monitoring bundled under EU F-Gas Regulation compliance. Netherlands and Belgian projects lead this specification shift.
- Building Automation:BACnet and Modbus protocol integration enables zone-level intelligence that reduces centralized panel density in Nordic commercial portfolios piloting wireless actuator mesh networks.
- Industrial Ventilation:Fume extraction and process cooling in manufacturing plants favors robust pneumatic systems where electronic actuator supply chains face copper and rare earth volatility.
HVAC Systems anchors volume; Clean Rooms deliver the steepest expansion trajectory as pharmaceutical capacity expands.
End User:
Customer type determines specification stringency, with healthcare and education procurement governed by infection control standards that residential and light commercial tiers escape.
- Commercial Buildings:Office and retail retrofits across Germany, France, and Italy are accelerating under EU Energy Performance of Buildings Directive mandates that disqualify legacy pneumatic installations from renovation subsidies.
- Educational Institutions:University and K-12 infrastructure in Canada and Australia is specifying pressure-independent operation for infection control upgrades in aging HVAC systems.
- Manufacturing Plants:Process ventilation and climate control in industrial facilities favors constant volume architectures where production continuity outweighs energy optimization.
- Residential Properties:Single-family and multifamily construction deploys electromechanical Single Duct units where smart control premiums face consumer price resistance.
Commercial Buildings command the dominant share; Educational Institutions are climbing the fastest as post-pandemic ventilation standards tighten.
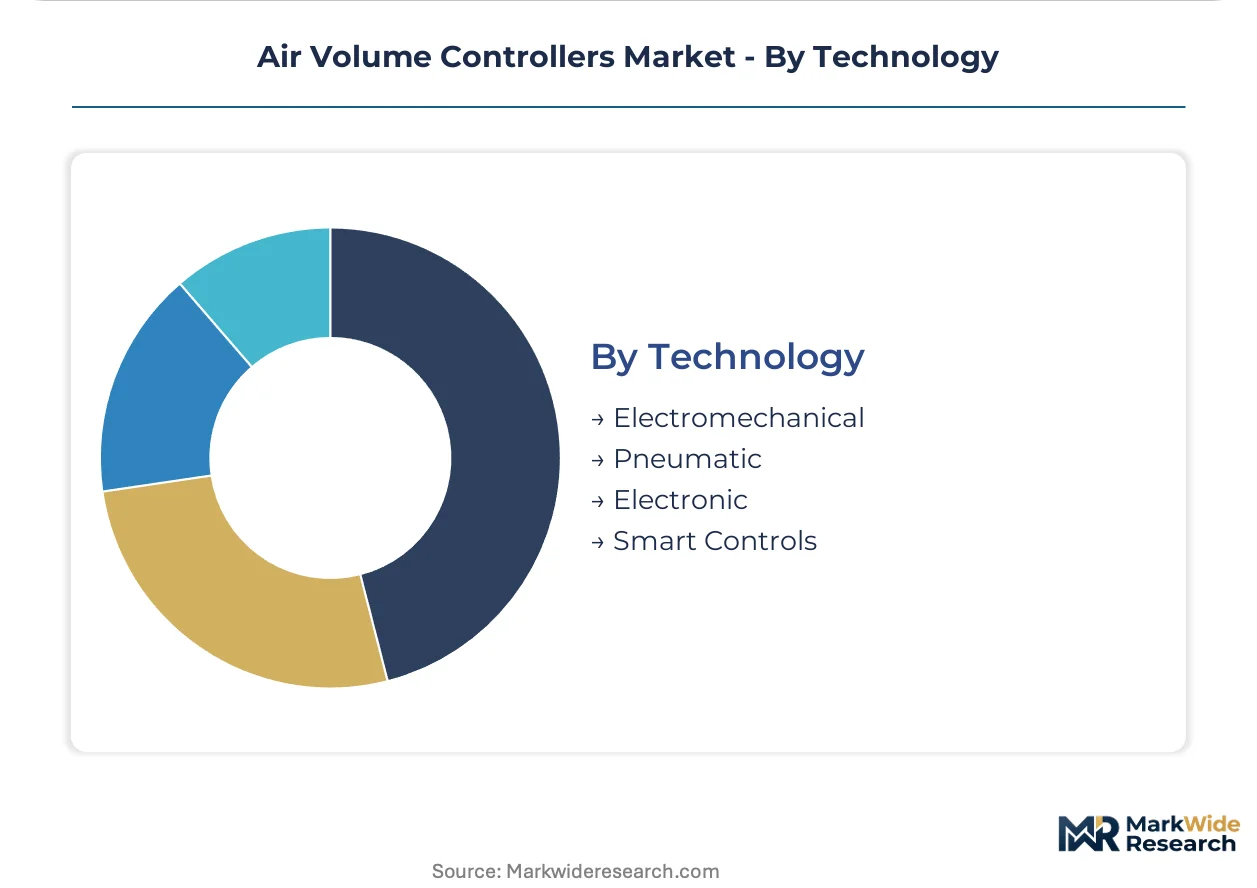
Technology:
Maturity gradients separate declining pneumatic installations from expanding smart control penetration, with electronic actuation absorbing functionality from separate building automation layers.
- Smart Controls:Predictive maintenance subscriptions and digital twin integration enable software service bundling that collapses the traditional electromechanical-electronic price gap. Johnson Controls leverages its building automation platform to capture this margin pool.
- Electronic:Precision actuation with BACnet/Modbus interoperability serves mid-tier commercial specifications where EPA Energy Star certification creates testing infrastructure barriers for smaller suppliers.
- Pneumatic:Compressed air-powered modulation persists in grandfathered Japanese and U.S. facilities where full conversion cycles are delayed by capital constraints.
- Electromechanical:Basic motor-driven dampers commoditize in residential and light commercial tiers where regulatory compliance requirements are minimal.
Electronic technology retains the largest installed base; Smart Controls are gaining share fastest as building automation platforms integrate controller functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in German manufacturing clusters for precision actuation hardware, while specification demand fragments across North American retrofit cycles and Asian cleanroom expansion. Controller procurement patterns diverge sharply between EU regulatory compliance markets and cost-optimized Asian deployment tiers.
United States
Federal building retrofits and municipal HVAC upgrades drive specification of pressure-independent Variable Air Volume units. ASHRAE Standard 90.1 mandates disqualify legacy pneumatic installations from new construction and major renovation projects. Chicago and New York commercial portfolios accelerate smart control procurement under Energy Service Company performance contracting arrangements.
Germany
Renovation rates for commercial HVAC infrastructure exceed peer European economies, accelerating electronic actuator displacement of pneumatic systems. The EU Energy Performance of Buildings Directive channels subsidy eligibility toward certified efficient installations. Stuttgart and Munich industrial zones anchor manufacturing of precision damper assemblies for export-led Multi-Duct demand.
China
New construction in pharmaceutical and semiconductor manufacturing clusters specifies smart-controlled units under Ministry of Ecology and Environment efficiency mandates. Dual carbon compliance timelines compress procurement windows for electronic actuation over legacy alternatives. Yangtze River Delta cleanroom projects in Suzhou and Wuxi drive premium Multi-Duct architecture uptake.
Japan
Grandfathered pneumatic installations in industrial facilities delay full electronic conversion cycles despite METI efficiency guidelines. Capital constraints in aging infrastructure sustain compressed air-powered modulation in manufacturing plants. Osaka and Nagoya industrial corridors retain substantial legacy base while Tokyo commercial retrofits pilot wireless actuator mesh networks.
Switzerland
Pharmaceutical manufacturing expansion drives specification of redundant Multi-Duct controllers where single-point failure risks are unacceptable. Swissmedic cleanroom standards and EU F-Gas Regulation leakage monitoring requirements elevate airtightness specifications. Basel and Zurich pharmaceutical clusters lead integration of bundled leakage detection functions.
Air Volume Controllers Market Vendor Landscape
Concentration sits with diversified building automation conglomerates that leverage captive distribution through specification bundling. Tiered competitive structure separates premium-tier platform integrators from mid-tier component specialists and regional electromechanical fabricators. Dominant strategic moves include software service bundling through predictive maintenance subscriptions and backward integration into electronic actuator manufacturing to secure magnet material supply chains.
Within the building automation platform tier, Johnson Controls and Siemens exemplify archetype positioning through captive specification channels. Honeywell International occupies a position bridging component supply and system integration. Among diversified HVAC manufacturers, Daikin Industries and Trane Technologies represent scale-driven end consolidation. TROX GmbH anchors German precision manufacturing specialization for cleanroom-grade applications.
| Leading Market Players |
|---|
| Johnson Controls |
| Schneider Electric |
| Siemens |
| Trane Technologies |
| Systemair |
| Lennox International |
| Honeywell International |
| Daikin Industries |
| TROX GmbH |
| Others |
Supply Flow & Price Mechanics
Electronic actuator displacement of pneumatic modulation is redrawing procurement economics as magnet material sourcing migrates toward Asian refining corridors and legacy copper-wound alternatives face cost compression. German precision manufacturers capture premium positioning through EN 1751 certification depth while Chinese scale producers undercut on standardized electronic tiers.
Pricing Analysis
ASHRAE Standard 90.1 and the EU Energy Performance of Buildings Directive dictate the pricing tier structure across commercial retrofit specifications. Three-tier pricing structure across premium smart-controlled, standard electronic, and economy electromechanical levels separates certified efficient installations from grandfathered pneumatic alternatives. Pricing pressure stems from copper and rare earth magnet volatility in electronic actuator manufacturing. Residential and light commercial tiers exhibit highest price sensitivity, while pharmaceutical cleanroom buyers absorb premium multi-duct positioning.
Supply Chain Analysis
Rare earth magnet processing concentration in China underwrites electronic actuator cost structures and creates single-source vulnerability for precision damper manufacturers. Component sourcing draws from German precision machining clusters, Chinese magnet refining, and Japanese motor assemblies. Tariff exposure runs through trans-Pacific electronic component flows. Distribution runs through building automation platform bundling and HVAC contractor specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning expertise for BACnet and Modbus protocol integration represents the critical capability gap separating platform-integrated suppliers from component vendors, with smart control penetration outpacing qualified installer availability.
For Market Incumbents: Fortify backward integration into electronic actuator manufacturing to secure magnet material supply chains against rare earth concentration risk. Deepen EN 1751 and ISO 9001 certification moats to exclude smaller competitors lacking captive testing infrastructure. Channel control through building automation platform bundling defends margin pools as electromechanical tiers commoditize.
For New Entrants and Emerging Players: Predictive maintenance subscription gaps in mid-tier commercial portfolios offer white-space entry where Johnson Controls and Siemens under-serve regional contractor networks. Target U.S. municipal HVAC retrofits where Energy Service Company performance contracting compresses upfront capital barriers. Position through wireless actuator mesh network commissioning expertise in Nordic pilot markets.
For Investors and Strategic Acquirers: The market sits at a smart control penetration phase that favors building automation platform consolidators over standalone component specialists. Five-to-ten year viability hinges on software service bundling capability and regulatory certification depth. Acquisition focus should center on mid-tier electronic actuator manufacturers with captive laboratory infrastructure. Watch ASHRAE 90.1 compliance timeline acceleration as the inflection signal warranting position adjustment.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Service Bundling | Predictive maintenance subscriptions through Johnson Controls' platform collapse electromechanical-electronic price gaps. |
| Backward Integration | In-house magnet material sourcing secures supply chains against Chinese rare earth processing concentration. |
| Certification Investment | EN 1751 and EPA Energy Star laboratory infrastructure excludes smaller competitors from premium specification tiers. |
| Wireless Mesh Deployment | Zone-level intelligence pilots in Nordic commercial portfolios reduce centralized panel density requirements. |
| Cleanroom Specification Capture | Multi-duct redundancy architectures serve Swissmedic standards in Basel pharmaceutical manufacturing expansion. |
Methodological Framework
Operator-level perspectives from HVAC contractors, building automation integrators, pharmaceutical facility engineers, and energy service company procurement managers anchored the qualitative base. Secondary validation drew from ASHRAE technical standards documentation, EPA Energy Star certification databases, EU Ecodesign regulatory filings, and customs trade data for damper assembly imports. Bottom-up segment sizing triangulated against top-down construction spending and HVAC equipment replacement cycles.
Sensitivity analysis across smart control penetration scenarios, rare earth price volatility bands, and regulatory compliance timeline variations shaped the analytical framework. Segmentation dimensions spanned product architecture, application environment, control technology, and end-user vertical. CAGRs were derived from installation base turnover rates and new construction permitting data. Forecast inputs incorporated EU Green Deal retrofit subsidy allocation and China's MEE dual carbon enforcement intensity.
Underlying assumptions cover pneumatic-to-electronic conversion pace, magnet material supply stability, and certification cost trajectory, with deviation risk concentrated in grandfathered facility capital constraint persistence and wireless protocol standardization timing. Revision becomes warranted when ASHRAE 90.1 enforcement intensity or EU F-Gas Regulation leakage monitoring mandates cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Mexico Compressed Air Treatment Equipment Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Blowers Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Global Industrial Air Chiller Market