
 Hydro Chillers Market | 2026-2036
Hydro Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydro Chillers Market Analytics
Preventive maintenance contracts and remote monitoring subscriptions is hardening into the core revenue stream rather than an after-sale add-on. Daikin Industries leverages its captive service network across Asia-Pacific to lock in multi-year thermal management agreements. Trane Technologies anchors its North American position through predictive analytics platforms that reduce unplanned downtime for industrial clients. Carrier Global differentiates by integrating software-defined capacity modulation that lets customers pay for cooling output rather than installed equipment.
Hydro chillers are closed-loop refrigeration systems that circulate water or water-glycol mixtures to remove process heat, typically operating between -30°C and 25°C setpoints depending on compressor staging and refrigerant selection. These units serve pharmaceutical crystallization, plastic injection molding, and semiconductor fabrication where precise temperature stability prevents material deformation or yield loss. Water-cooled configurations dominate heavy industrial sites with available cooling tower infrastructure, while portable units capture growing share in medical equipment and small-batch chemical processing where footprint flexibility matters. Vapor compression technology leads installed base but faces margin pressure as absorption systems gain traction in facilities with waste heat recovery potential.
US DOE minimum efficiency standards and EPA SNAP refrigerant phase-down rules are forcing OEMs to redesign compressor architectures and qualify lower-GWP working fluids. China's GB standards for industrial cooling energy intensity and the EU F-Gas Regulation create divergent compliance pathways that fragment product platforms across regions. Stakeholders must decide whether to develop modular refrigerant-agnostic chassis or region-locked dedicated product families as regulatory timelines tighten.
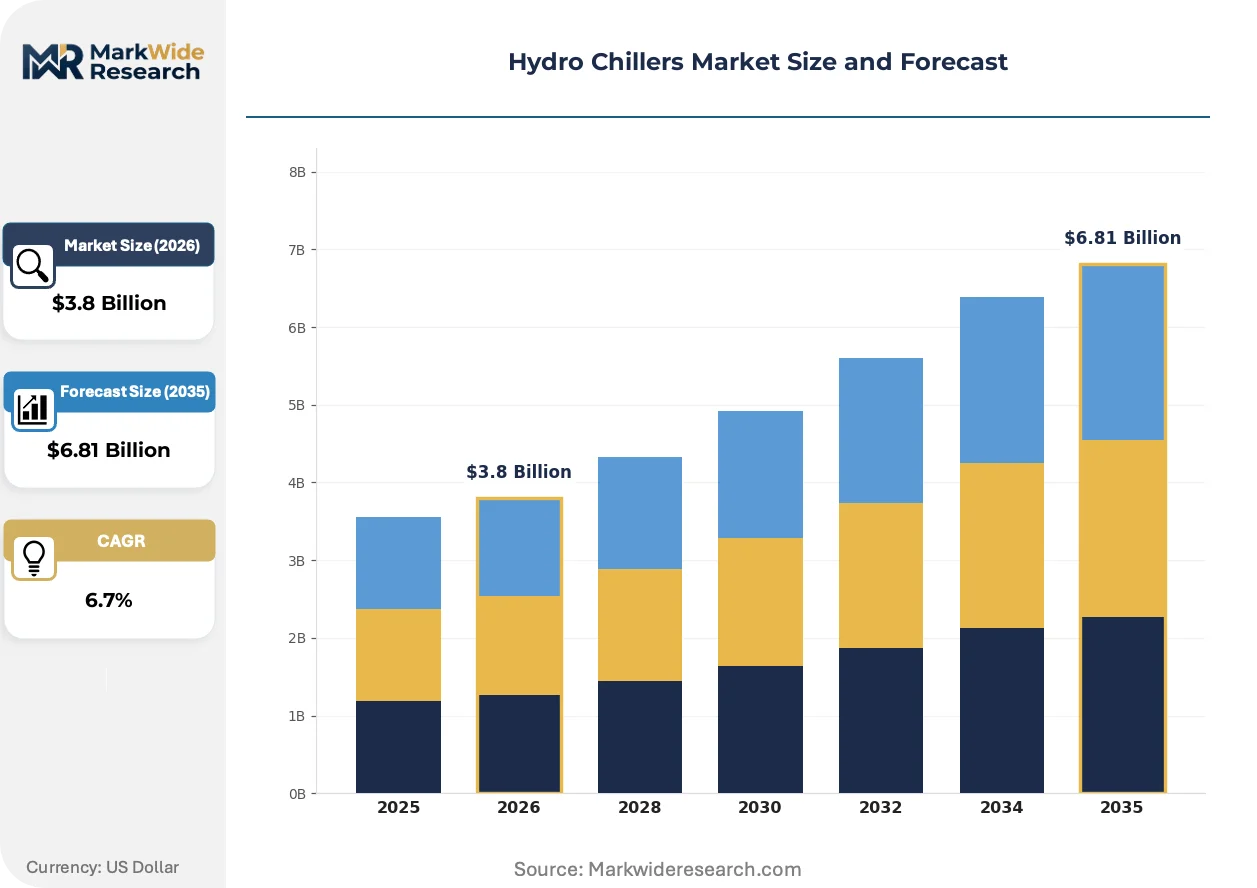
Market Dynamics
AI-driven data center thermal loads are compressing chiller procurement cycles from five-year replacement schedules to continuous capacity scaling, forcing OEMs to abandon fixed-capacity architectures for software-defined modulation platforms.
Growth Catalysts
- EPA SNAP refrigerant phase-down:The mandate accelerates R-134a replacement programs, creating retrofit demand across existing pharmaceutical and semiconductor installations that cannot absorb downtime during peak production windows.
- Data center liquid cooling:Hyperscale facilities in Northern Virginia and Frankfurt are specifying -10°C supply temperatures for direct-to-chip cooling loops, pulling capacity from industrial chiller manufacturers into IT infrastructure contracts.
- China's dual carbon goals:Provincial industrial parks in Jiangsu and Guangdong face binding energy intensity targets that favor absorption chillers recovering waste heat from chemical processing clusters.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials account for 35-40% of bill-of-materials costs, compressing margins when London Metal Exchange prices spike during energy transition infrastructure buildouts.
- Compressor supply concentration:Scroll and screw compressor production clusters in Germany and Japan create 16-20 week lead time exposure for North American chiller assemblers without captive manufacturing.
- Water scarcity constraints:Cooling tower-dependent water-cooled configurations face permitting restrictions in Arizona, Nevada, and South African mining regions where aquifer depletion triggers regulatory moratoriums.
Strategic Opportunities
- India pharmaceutical cold chain:CDSCO temperature validation requirements for biologics storage are creating demand for portable glycol chillers in Mumbai and Hyderabad manufacturing zones where utility reliability remains intermittent.
- EU F-Gas Regulation service revenue:Mandatory leak detection and refrigerant recovery protocols position OEMs with captive technician networks to capture decade-long maintenance contracts independent of original equipment sales.
- AI-enabled predictive maintenance:Vibration analysis and oil condition monitoring converge with chiller control systems, allowing manufacturers to sell thermal output guarantees rather than capital equipment.
Industry Challenges
- Refrigerant technician certification gaps:EPA Section 608 and EU F-Gas certification timelines create 6-12 month workforce deployment delays during regional demand surges.
- Legacy BAS integration friction:BACnet and Modbus protocol mismatches between 1990s-era building automation systems and modern IoT-enabled chillers extend commissioning cycles and erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydro Chillers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Liquid-Cooled, Portable Application: Industrial Processes, HVAC Systems, Medical Equipment, Chemical Processing Technology: Vapor Compression, Absorption, Thermoelectric, Phase Change End User: Manufacturing, Healthcare, Food & Beverage, Data Centers |
| Companies Covered | Daikin Industries, Ltd., Trane Technologies plc, Carrier Global Corporation, Johnson Controls International plc, Mitsubishi Electric Corporation, Smardt Chiller Group, Inc., Thermax Limited, Drake Refrigeration Inc., Polyscience Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydro Chillers Market Evolving Landscape
Refrigerant chemistry, control software, and thermal storage are compressing the traditional chiller value chain into integrated energy-service platforms where hardware margins subsidize long-term output contracts.
Magnetic bearing centrifugal compressors eliminate oil management systems and reduce part-load energy consumption by 15-25% compared to conventional lubricated designs. Pharmaceutical manufacturers in Switzerland and Singapore are specifying oil-free configurations for cleanroom applications where refrigerant contamination risks invalidate batch production. This technology is converging with thermal energy storage tanks, allowing facilities to arbitrage electricity rates by pre-cooling during off-peak periods.
The EU F-Gas Regulation's 2030 phase-down schedule for hydrofluorocarbons is compressing R-410A and R-134a availability, forcing OEMs to qualify propane, ammonia, and hydrofluoroolefin blends across product lines. Industrial sites in the Netherlands and Denmark face accelerated retrofit deadlines that favor complete system replacement over refrigerant conversion. Chiller manufacturers with modular, refrigerant-agnostic chassis architectures capture specification preference from engineering firms managing pan-European facility portfolios.
Service unbundling is separating preventive maintenance from equipment procurement, with data center operators in Singapore and Ireland negotiating thermal availability contracts that transfer compressor failure risk to OEM balance sheets. Channel intermediaries in traditional HVAC distribution face disintermediation as manufacturers deploy direct technician networks for critical facility accounts. This pattern concentrates most visibly in pharmaceutical and semiconductor verticals where unplanned downtime costs exceed equipment replacement value within 48 hours.
Hydro Chillers Market Segmentation
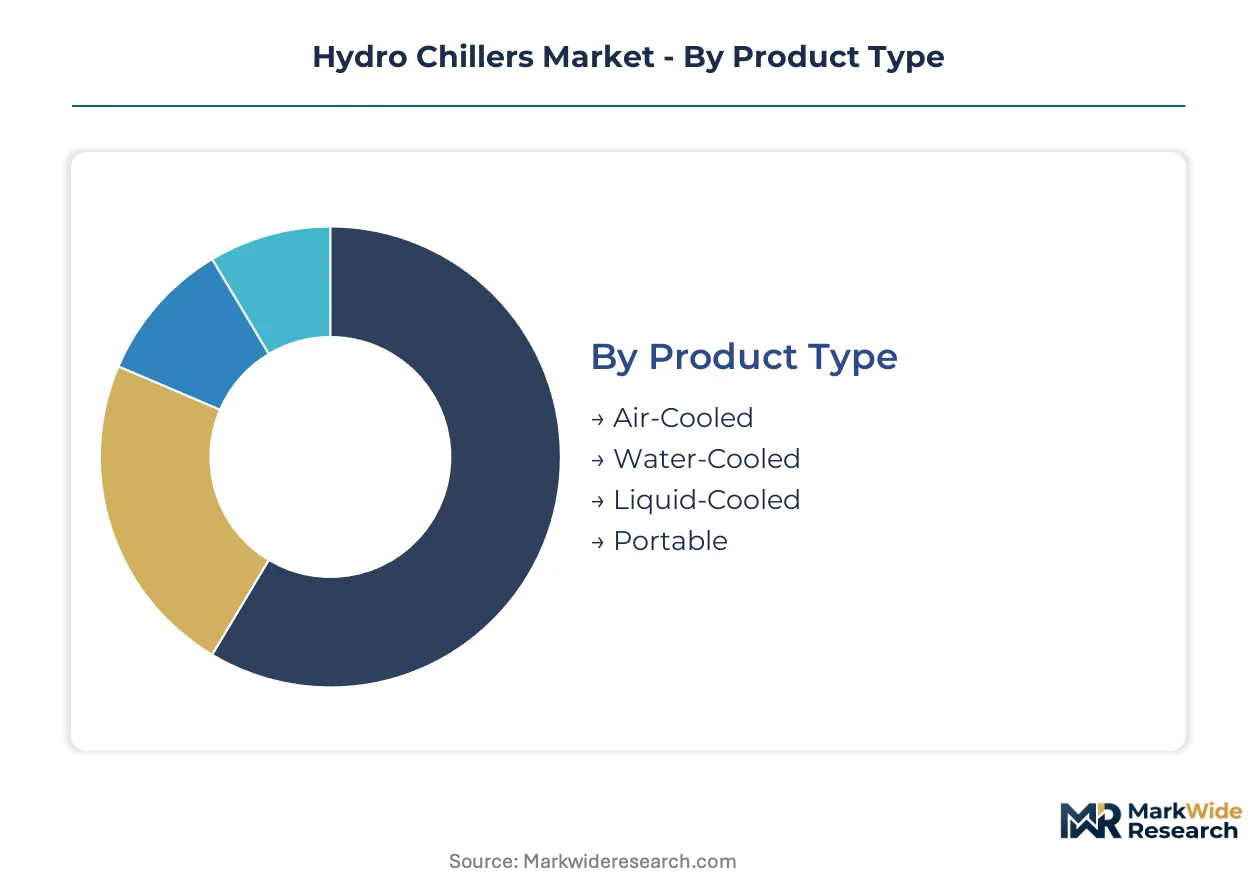
Segmentation in hydro chillers reveals divergent upgrade cycles across cooling architectures and end-use verticals. Equipment replacement timelines compress from fifteen-year industrial standards to three-year refresh rates in hyperscale data centers, fragmenting procurement patterns and service contract structures.
Product Type:
Replacement cycles vary dramatically by cooling medium, with infrastructure-bound systems facing longer depreciation schedules than modular alternatives.
- Air-Cooled:Self-contained units reject heat directly to ambient air through finned condenser coils, eliminating cooling tower dependencies. Demand clusters in Arizona and Nevada mining operations where water scarcity triggers regulatory moratoriums on tower-dependent systems.
- Water-Cooled:Shell-and-tube or plate heat exchangers couple to centralized cooling towers, achieving higher thermodynamic efficiency at the cost of water treatment infrastructure. Pharmaceutical crystallization lines in Switzerland and Singapore specify these configurations for precise setpoint stability where batch contamination risks dwarf capital costs.
- Liquid-Cooled:Direct-to-chip architectures circulate dielectric fluids or water-glycol mixtures at sub-zero temperatures for AI server thermal management.
- Portable:Skid-mounted or caster-based units serve temporary process cooling and emergency redundancy in intermittent-utility environments.
Volume placements concentrate in Water-Cooled configurations; the faster expansion belongs to Portable systems serving distributed pharmaceutical manufacturing.
Application:
Cost tier differentiation separates mission-critical installations with uptime guarantees from commodity comfort cooling contracts.
- Industrial Processes:Continuous-duty systems maintain ±0.5°C stability for plastic injection molding and semiconductor wafer fabrication. Jiangsu and Guangdong industrial parks drive specification volume under binding provincial energy intensity targets.
- HVAC Systems:Comfort cooling and dehumidification for commercial buildings, typically operating at higher setpoints with wider dead bands than process applications. Carrier Global's software-defined capacity modulation targets this tier with output-based pricing rather than equipment ownership models.
- Medical Equipment:MRI magnet cooling and linear accelerator temperature management where failure triggers immediate patient care disruption.
- Chemical Processing:Exothermic reaction control and solvent recovery applications favoring absorption technology where waste heat streams offset energy costs.
Margin concentration sits with Medical Equipment specifications; steepest expansion trajectory runs through Chemical Processing absorption retrofits.
Technology:
Technology maturity curves determine whether segments compete on installed cost or operational efficiency metrics.
- Vapor Compression:Dominant installed base using mechanical refrigeration cycles with scroll, screw, or centrifugal compressors. EPA SNAP refrigerant phase-down rules force OEMs to redesign compressor architectures and qualify lower-GWP working fluids across existing pharmaceutical and semiconductor installations.
- Absorption:Heat-activated systems using lithium bromide or ammonia-water working pairs, eliminating compressor electricity draw where waste heat is available. China's dual carbon goals accelerate deployment across chemical processing clusters recovering exhaust heat from manufacturing lines.
- Thermoelectric:Solid-state Peltier devices for sub-500W cooling loads in portable medical and laboratory equipment.
- Phase Change:Thermal energy storage systems exploiting latent heat of fusion for load shifting and peak demand reduction.
Revenue share concentrates in Vapor Compression; technology transition momentum favors Absorption systems under tightening energy intensity regulations.
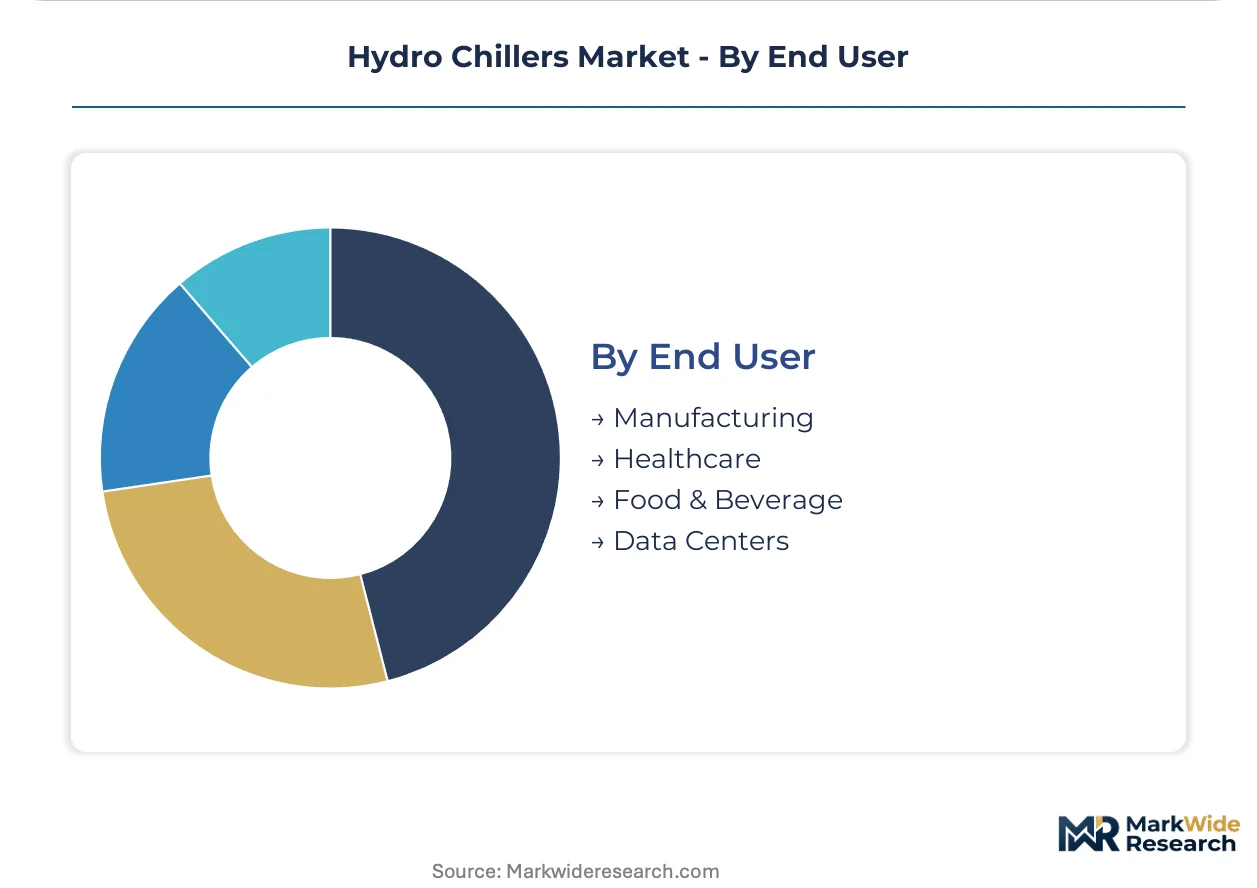
End User:
Customer type dictates contract structure, with some verticals accepting thermal-output agreements while others demand equipment ownership.
- Manufacturing:Process cooling for automotive stamping, textile finishing, and metal forming operations with seasonal load curves. Trane Technologies anchors North American position through predictive analytics platforms that reduce unplanned downtime for industrial clients facing 48-hour failure cost exposures exceeding replacement value.
- Healthcare:Hospital central plants and diagnostic imaging suites requiring redundant capacity and continuous monitoring. Daikin Industries leverages captive service networks across Asia-Pacific to lock multi-year thermal management agreements with tier-one medical centers.
- Food & Beverage:Brewery fermentation control, dairy pasteurization cooling, and cold chain logistics supporting temperature-sensitive distribution.
- Data Centers:Hyperscale facilities in Northern Virginia and Frankfurt specifying -10°C supply temperatures for direct-to-chip cooling loops, compressing procurement cycles from five-year replacement schedules to continuous capacity scaling.
Contract value concentrates in Data Center verticals; service revenue expansion runs deepest in Healthcare through mandatory leak detection and refrigerant recovery protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration tilts toward East Asian industrial corridors while consumption spreads across data center clusters in Northern Virginia and Frankfurt. European regulatory pressure on fluorinated gases is reshaping supplier footprints faster than demand migration.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth is pulling industrial chiller capacity into IT infrastructure contracts. EPA SNAP refrigerant phase-down rules are forcing pharmaceutical installations in New Jersey and North Carolina to accelerate R-134a replacement programs. Arizona and Nevada mining operations face water scarcity moratoriums that favor air-cooled configurations over traditional tower-dependent systems.
China
Provincial industrial parks in Jiangsu and Guangdong operate under binding energy intensity targets that favor absorption chillers recovering waste heat. GB standards for industrial cooling energy intensity are tightening performance thresholds for equipment procurement. Yangtze River Delta manufacturing zones are deploying closed-loop refrigeration systems for semiconductor wafer fabrication where temperature stability prevents yield loss.
Germany
Chemical processing clusters in North Rhine-Westphalia are retrofitting absorption systems to exploit waste heat recovery potential under EU F-Gas Regulation timelines. The 2030 phase-down schedule for hydrofluorocarbons is compressing R-410A availability and favoring complete system replacement over conversion. Frankfurt data center operators are specifying -10°C supply temperatures for direct-to-chip cooling loops.
India
CDSCO temperature validation requirements for biologics storage are creating demand for portable glycol chillers in Mumbai and Hyderabad manufacturing zones. Pharmaceutical cold chain expansion is accelerating where utility reliability remains intermittent. Gujarat and Maharashtra industrial corridors are absorbing capacity from Chinese suppliers facing margin pressure from copper and aluminum price volatility.
Switzerland
Pharmaceutical manufacturers in Basel and Geneva are specifying oil-free magnetic bearing configurations for cleanroom applications where refrigerant contamination risks invalidate batch production. Swissmedic validation protocols for temperature-sensitive production are hardening procurement criteria. The country's precision manufacturing base is converging with thermal energy storage tanks to arbitrage electricity rates through pre-cooling during off-peak periods.
Hydro Chillers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology maturity curves. Vapor compression incumbents with captive compressor manufacturing face margin pressure from modular refrigerant-agnostic challengers. Three archetypes dominate: integrated HVAC conglomerates with service networks, specialized chiller OEMs with magnetic bearing expertise, and thermal-as-a-service platforms selling output guarantees. Consolidation is concentrating around predictive analytics capabilities and multi-year maintenance contract portfolios.
Among Asia-Pacific-based conglomerates, Daikin Industries, Ltd. and Mitsubishi Electric Corporation exemplify the integrated archetype leveraging captive technician networks for multi-year thermal management agreements. Trane Technologies plc and Carrier Global Corporation anchor the North American premium tier through software-defined modulation platforms. Johnson Controls International plc occupies a position spanning both equipment ownership and service unbundling models. Smardt Chiller Group, Inc. represents the magnetic bearing specialist tier gaining specification preference in pharmaceutical cleanroom applications.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Trane Technologies plc |
| Carrier Global Corporation |
| Johnson Controls International plc |
| Mitsubishi Electric Corporation |
| Smardt Chiller Group, Inc. |
| Thermax Limited |
| Drake Refrigeration Inc. |
| Polyscience Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up compressor specialists anchor supply concentration in Germany and Japan, translating captive manufacturing positions into pricing discipline that resists commoditization even as copper and aluminum volatility squeezes heat exchanger margins. This ownership pattern feeds back into procurement behavior, with North American assemblers accepting longer lead times to lock in cost predictability rather than diversifying into unproven supplier bases.
Pricing Analysis
Cost-down pressure on mid-range vapor compression units accelerates because EPA SNAP refrigerant phase-down rules force simultaneous compressor redesign and lower-GWP fluid qualification. Three-tier pricing structure across premium magnetic bearing, standard scroll-screw hybrid, and economy portable configurations separates buyers by certification grade and after-sales bundling intensity. Pharmaceutical crystallization lines in Switzerland exhibit lowest price sensitivity, prioritizing oil-free contamination guarantees over capital expenditure optimization. Standard HVAC comfort cooling contracts face greatest pricing softness, with Carrier Global's output-based software modulation capturing share from traditional equipment ownership models.
Supply Chain Analysis
Heat exchanger materials draw from Chinese aluminum smelting clusters, Chilean copper concentrate, and German precision tube forming, creating multi-node geographic exposure. Scroll and screw compressor production rests on Japanese mechatronics specialists and Bavarian machining houses, feeding 16-20 week lead time vulnerability into North American chiller assembly. Single-source vulnerability concentrates in magnetic bearing controllers sourced from Swiss precision electronics suppliers. Distribution runs through captive OEM technician networks for critical facility accounts, bypassing traditional HVAC intermediaries in pharmaceutical and semiconductor verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressor supply concentration in Germany and Japan props pricing discipline, with scroll-screw manufacturing bottlenecks limiting rapid capacity response to hyperscale data center demand surges.
For Market Incumbents: Hedge refrigerant transition risk by qualifying propane and hydrofluoroolefin blends across modular chassis architectures before EU F-Gas Regulation deadlines harden. Deepen backward integration into magnetic bearing controller production to reduce Swiss precision electronics dependency. Capture multi-year thermal availability contracts in Northern Virginia and Frankfurt data center clusters, transferring compressor failure risk onto balance sheets while locking recurring service revenue. For New Entrants and Emerging Players: Enter via portable glycol chiller specialization for Mumbai and Hyderabad pharmaceutical zones where CDSCO temperature validation requirements meet intermittent utility reliability. Target absorption system retrofits in Jiangsu and Guangdong chemical processing clusters under binding provincial energy intensity targets. Lead with waste heat recovery engineering partnerships rather than equipment-only positioning. For Investors and Strategic Acquirers: Mandatory leak detection and refrigerant recovery protocol expansion under EU F-Gas Regulation is the leading indicator that captive technician network value will decouple from original equipment sales over the mid-term horizon. Acquire asset-light thermal-as-a-service platforms with predictive analytics capabilities and existing pharmaceutical cleanroom validation credentials. Watch for EPA Section 608 certification backlog duration as signal of regional demand surge timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Agnostic Chassis Development | Modular platforms capture pan-European specification preference as F-Gas deadlines fragment compliance pathways. |
| Magnetic Bearing Controller Backward Integration | In-house production of Swiss-sourced precision electronics reduces lead time exposure and margin compression. |
| Thermal Availability Contract Expansion | Output-based pricing transfers compressor failure risk to OEMs while locking decade-long maintenance revenue. |
| Absorption System Waste Heat Partnerships | Chemical processing cluster alliances exploit China's dual carbon goals and binding energy intensity targets. |
| Predictive Analytics Platform Acquisition | Vibration analysis and oil condition monitoring capabilities enable thermal output guarantees rather than capital sales. |
Research Methodology
Trade association filings, customs and import-export databases, and SEC 10-K equipment manufacturer disclosures formed the secondary backbone, cross-referenced against primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at pharmaceutical and semiconductor facilities. Bottom-up unit shipment tallies by cooling architecture and end-use vertical were reconciled with top-down capital expenditure tracking across data center development pipelines.
Historical trendline analysis of replacement cycle compression and technology transition velocity informed projection modeling across vapor compression, absorption, thermoelectric, and phase change technology segments, further disaggregated by air-cooled, water-cooled, liquid-cooled, and portable product configurations. CAGR derivation incorporated regulatory timeline phasing for EPA SNAP and EU F-Gas mandates, copper-aluminum price volatility scenarios, and hyperscale data center thermal load density assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated refrigerant phase-down schedules or prolonged compressor supply disruptions. A small set of named triggers warrants ongoing watch: EPA Section 608 technician certification backlog duration, Yangtze River Delta industrial policy shifts, and Northern Virginia data center permitting velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Louvers Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Compressor Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
North America Residential Heat Pump Market