
 Centrifugal Chillers Market | 2026-2036
Centrifugal Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Chillers Market Analysis
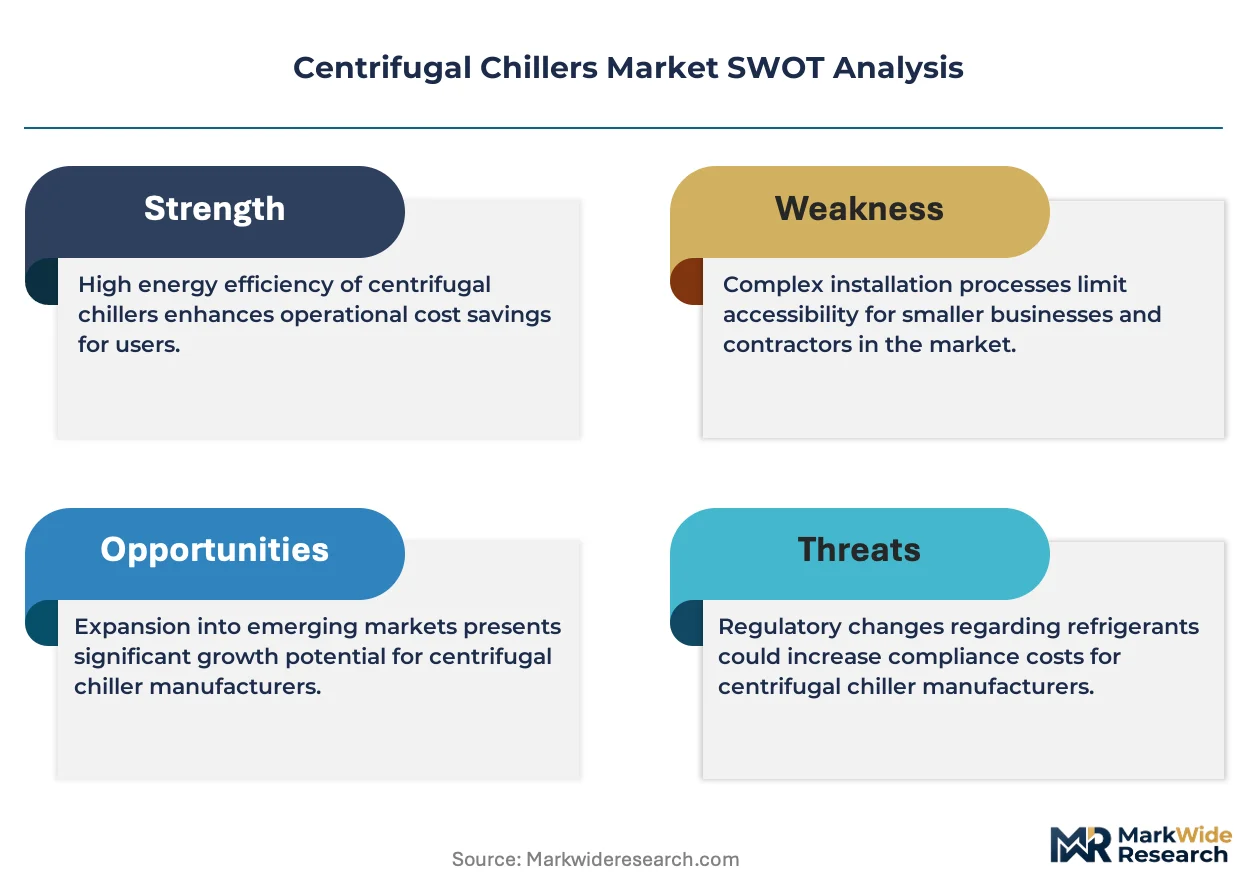
The performance gap between premium magnetic-bearing systems and conventional oil-lubricated units is recalibrating procurement criteria across commercial and institutional buyers. Trane Technologies leverages its portfolio of oil-free compressor technology to command positioning in high-efficiency installations. Johnson Controls anchors large-scale project pipelines through extensive service networks and building automation integration. Carrier Corporation differentiates via deep manufacturing scale across water-cooled and modular product configurations.
Centrifugal chillers are large-capacity vapor-compression refrigeration systems that use centrifugal force to compress refrigerant vapor, typically achieving cooling outputs from 200 to 2,000+ tons with coefficients of performance exceeding 6.0 at standard conditions. These systems serve as central cooling plants for commercial complexes, industrial processes, and district energy networks where continuous high-load operation demands maximum thermodynamic efficiency. Water-cooled centrifugal chillers occupy the dominant share of installed base value due to superior efficiency in large-scale applications, while variable speed drive technology is capturing disproportionate growth as part-load optimization becomes a primary design priority. Modular configurations are expanding addressable market reach by enabling phased capacity additions in constrained mechanical spaces.
The EPA's AIM Act refrigerant phasedown and corresponding SNAP program revisions are reshaping equipment specifications and retrofit timelines across the United States. ASHRAE Standard 90.1 and IECC building energy codes are tightening minimum efficiency thresholds, compressing the viable competitive set for new construction bids. Stakeholders must monitor refrigerant transition roadmaps and regional code adoption cycles to align product development and inventory positioning with compliance deadlines.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing equipment replacement cycles and forcing specification overhauls across commercial and institutional cooling portfolios. This regulatory compression is recalibrating procurement priorities toward lower-GWP alternatives ahead of compliance deadlines.
Growth Catalysts
- Data center cooling expansion:Hyperscale facilities in the United States, India, and China are deploying high-capacity centrifugal systems to manage thermal loads from AI infrastructure and cloud computing density.
- F-Gas Regulation in Europe:The EU's tightening quotas on fluorinated gases are accelerating retrofit demand and creating pull-through for next-generation refrigerant platforms in commercial buildings.
- Magnetic-bearing compressor diffusion:Oil-free technology is penetrating mid-scale installations previously served by conventional lubricated units, expanding addressable market boundaries.
Market Restraints
- Copper and rare earth input volatility:Magnetic-bearing rotors and heat exchanger materials face price instability that compresses margin visibility for equipment manufacturers.
- Specialized service technician scarcity:Oil-free systems require distinct maintenance protocols, and qualified field personnel concentrate in metropolitan clusters across Germany, Japan, and the United States.
- Refrigerant transition friction:ASHRAE Standard 15 safety code revisions and local fire authority interpretations are creating permitting delays for A2L-class lower-GWP alternatives.
Strategic Opportunities
- District energy network modernization:European and North American cities are retrofitting centralized cooling plants with high-efficiency centrifugal units to meet decarbonization targets.
- Modular configuration adoption:Phased capacity expansion in constrained mechanical spaces is opening mid-scale commercial segments previously inaccessible to large-tonnage systems.
- India's cooling action plan:The India Cooling Action Plan and associated energy efficiency mandates are creating regulatory tailwinds for high-COP equipment in commercial real estate and industrial process cooling.
Industry Challenges
- Refrigerant handling certification bottlenecks:EPA Section 608 technician certification requirements and evolving safety standards for mildly flammable alternatives are compressing qualified installer availability.
- Building automation integration complexity:Legacy BAS protocols and proprietary control architectures are creating commissioning friction and extended project timelines for smart-connected chiller deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Chillers Market |
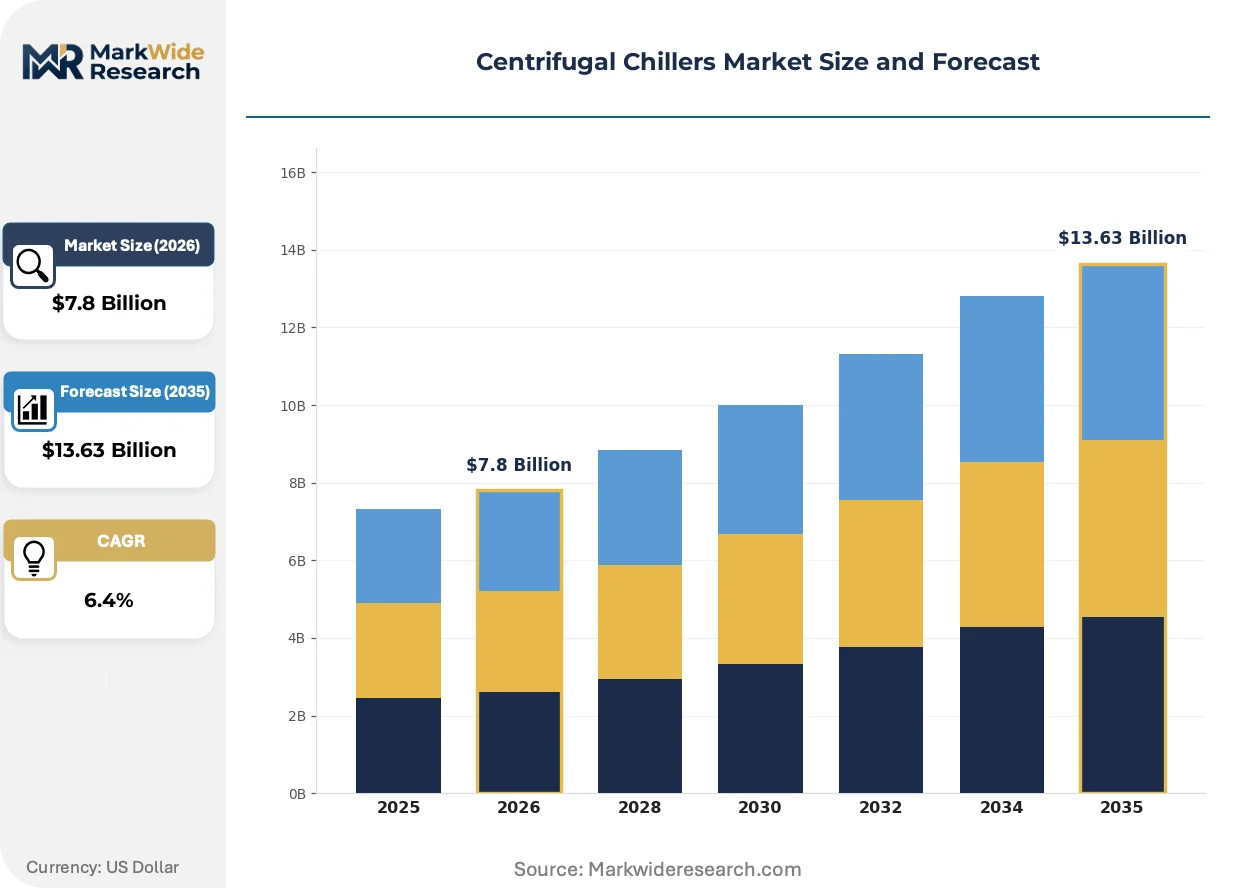
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Absorption, Modular End User: Commercial, Industrial, Residential, Institutional Installation: Outdoor, Indoor, Rooftop, Centralized Technology: Variable Speed Drive, Scroll Compression, Screw Compression, Centrifugal |
| Companies Covered | Trane Technologies, Johnson Controls, Daikin Industries, Carrier Corporation, Mitsubishi Electric Corporation, York, Smardt Chiller Group, Mitsubishi Heavy Industries, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Chillers Market Emerging Trajectories
Refrigerant chemistry transitions and compressor bearing technologies are actively restructuring equipment specifications and service economics across the centrifugal chiller installed base. These shifts are compressing traditional product lifecycles and redefining competitive differentiation.
Magnetic-bearing oil-free compressor technology is consolidating its position in premium efficiency tiers. Data center operators and pharmaceutical manufacturers are specifying these systems for continuous-load applications where part-load optimization delivers measurable energy savings. This technology is consolidating procurement criteria around total cost of ownership rather than first-cost metrics, compressing the viable competitive set for conventional oil-lubricated units.
REACH and the EU F-Gas Regulation are mandating refrigerant transitions with accelerating phase-down schedules. Equipment manufacturers must recertify product lines for lower-GWP alternatives including R-1234ze and R-513A, compressing development timelines. European commercial building retrofits are most affected, with contractors stockpiling legacy refrigerant to bridge availability gaps during specification transitions.
Performance contracting and energy-as-a-service models are displacing traditional capital purchase arrangements for large-scale cooling infrastructure. Facility managers in healthcare and higher education verticals are transferring operational risk to equipment vendors and energy service companies. This pattern is most visible in the United States, where municipal budget constraints and IRA-aligned financing mechanisms are accelerating adoption of outsourced thermal plant operation.
Centrifugal Chillers Market Segmentation
Centrifugal chiller procurement patterns diverge sharply across cooling load profiles, building constraints, and regulatory exposure. Specification decisions cascade from thermal tonnage requirements through refrigerant compliance timelines to maintenance infrastructure availability.
Product Type:
Cost tier separates buyers seeking maximum efficiency against those prioritizing deployment flexibility and first-cost containment.
- Water-Cooled:These systems achieve coefficients of performance exceeding 6.0 through heat rejection to cooling towers, making them the default specification for data centers and district cooling plants in the United States and China where continuous high-load operation dominates.
- Modular:Phased capacity expansion enables facility managers to match cooling supply to actual occupancy ramps, penetrating mid-scale commercial retrofits in constrained mechanical spaces across Germany and Japan where full-plant replacement proves infeasible.
- Air-Cooled:Eliminates cooling tower infrastructure, suiting remote industrial sites and water-scarce geographies.
- Absorption:Waste heat recovery integration serves combined heat and power installations and district energy networks.
Volume sits with Water-Cooled; growth tilts toward Modular.
End User:
Application criticality determines specification stringency and service contract depth.
- Commercial:Office complexes, retail centers, and hospitality properties prioritize part-load optimization through variable speed drive integration as ASHRAE Standard 90.1 tightens efficiency thresholds across new construction bids.
- Industrial:Process cooling for pharmaceuticals, petrochemicals, and food processing demands continuous reliability, driving magnetic-bearing adoption in Germany and Singapore where unplanned downtime carries severe production penalties.
- Institutional:Healthcare and higher education campuses leverage performance contracting models to transfer operational risk.
- Residential:Large multifamily and luxury high-rise applications remain niche due to first-cost barriers.
Commercial commands installed base value; Industrial shows steepest specification upgrade trajectory.
Installation:
Site constraints and climate exposure reshape equipment packaging and control architecture.
- Centralized:Dedicated mechanical plants serving entire campuses or districts enable optimized maintenance staffing and refrigerant management, dominating university and hospital deployments across the United States.
- Rooftop:Weatherized enclosures with integrated pumping overcome limited ground-level space in urban commercial density corridors of Mumbai and São Paulo.
- Indoor:Basement and penthouse placements require acoustic attenuation and ventilation engineering.
- Outdoor:Ambient temperature swings demand expanded condensing capacity and freeze protection protocols.
Centralized anchors replacement demand; Rooftop gains share in vertical urban construction.
Technology:
Compression mechanism and speed control strategy separate efficiency tiers and maintenance regimes.
- Variable Speed Drive:Part-load optimization through inverter-controlled motor speed matches cooling output to thermal demand curves, capturing disproportionate specification share in data center and pharmaceutical applications where load profiles fluctuate diurnally.
- Centrifugal:Dynamic compression via high-speed impellers achieves unmatched efficiency at 500+ ton capacities, retaining dominance in district cooling and large industrial process applications across the United Arab Emirates and South Korea.
- Scroll Compression:Positive displacement reliability serves smaller tonnage segments and distributed systems.
- Screw Compression:Balanced efficiency and compression ratio flexibility occupies mid-capacity commercial applications.
Centrifugal holds capacity leadership; Variable Speed Drive expands most quickly across retrofit specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Pudong district anchors centrifugal chiller procurement intensity, hosting hyperscale data center clusters and district cooling plants that consume high-capacity vapor-compression systems. Procurement patterns concentrate in economies where urbanization, industrial cooling density, and regulatory compression intersect.
United States
Data center construction in Northern Virginia's Loudoun County and Phoenix's Desert Ridge corridor drives specification volume for water-cooled centrifugal systems. EPA's AIM Act refrigerant phasedown compresses retrofit timelines across commercial building portfolios. Johnson Controls and Trane Technologies anchor project pipelines through service network density in Chicago's commercial corridor and Houston's petrochemical cluster.
China
Beijing-Tianjin-Hebei's district energy networks and Shenzhen's semiconductor fabrication parks generate concentrated demand for magnetic-bearing compressor technology. MEE enforcement of dual carbon goals tightens efficiency thresholds for new construction permits. Carrier Corporation and Daikin Industries compete for positioning in Shanghai's Lingang New Area and Chengdu's Tianfu New District cooling infrastructure.
Germany
Frankfurt's data center belt and BASF's Ludwigshafen chemical complex sustain premium-tier equipment demand. EU F-Gas Regulation quotas accelerate refrigerant transition roadmaps for commercial building retrofits. Smardt Chiller Group and Mitsubishi Electric penetrate Munich's healthcare and pharmaceutical verticals where oil-free reliability commands specification priority.
India
Mumbai's BKC financial district and Hyderabad's HITEC City technology parks expand addressable market for modular centrifugal configurations. India Cooling Action Plan mandates energy efficiency labeling for commercial refrigeration equipment. LG Electronics and York capture share in Bangalore's Whitefield tech corridor where phased capacity expansion suits constrained mechanical spaces.
Japan
Tokyo's Otemachi-Marunouchi-Yaesu district cooling network and Osaka's pharmaceutical manufacturing belt sustain replacement demand for high-COP systems. METI efficiency standards and refrigerant transition schedules compress product lifecycles. Mitsubishi Heavy Industries anchors domestic project pipelines while exporting magnetic-bearing technology to Singapore's Biopolis and Taiwan's Hsinchu Science Park.
Centrifugal Chillers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across efficiency tier and service integration depth, compressing the viable competitive set for conventional oil-lubricated configurations. The vendor base stratifies into three archetypes: integrated building automation providers, specialized oil-free compressor technology developers, and diversified industrial conglomerates with captive HVAC divisions. Dominant competitive moves include strategic partnerships for district energy modernization and technology licensing agreements for magnetic-bearing compressor diffusion into mid-scale applications.
Within the integrated building automation tier, Trane Technologies and Johnson Controls exemplify positioning through extensive service network density and control system integration. Among diversified industrial conglomerates, Daikin Industries and Mitsubishi Electric occupy positions spanning residential through commercial cooling portfolios. Carrier Corporation sits within the manufacturing scale archetype, leveraging water-cooled and modular product breadth. These three company groupings represent distinct competitive vectors: automation-anchored lifecycle revenue, conglomerate-backed R&D scale, and manufacturing-driven cost position.
| Leading Market Players |
|---|
| Trane Technologies |
| Johnson Controls |
| Daikin Industries |
| Carrier Corporation |
| Mitsubishi Electric Corporation |
| York |
| Smardt Chiller Group |
| Mitsubishi Heavy Industries |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Magnetic-bearing oil-free compressor technology versus conventional oil-lubricated systems bifurcates procurement economics across the centrifugal chillers landscape, concentrating pricing power with premium-tier vendors in data center and pharmaceutical verticals while compressing margins for commodity manufacturers dependent on copper and rare earth input stability.
Pricing Analysis
Value-based pricing tied to energy savings guarantees and uptime performance dominates specification decisions for magnetic-bearing systems in hyperscale data center deployments. Three-tier pricing structure across premium, standard, and economy levels separates oil-free magnetic-bearing units from variable-speed conventional systems and fixed-speed legacy configurations. Pricing pressure stems from copper price volatility and rare earth magnet supply constraints compressing margin visibility for equipment manufacturers. Commercial real estate developers exhibit highest price sensitivity, while pharmaceutical and semiconductor process cooling buyers prioritize total cost of ownership over first-cost metrics.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon enforcement are reshaping sourcing patterns for compressor castings and heat exchanger assemblies. Manufacturing concentration centers on China, the United States, and Germany for centrifugal compressor impellers, precision bearings, and control system electronics. Critical input dependencies include copper tube bundles, neodymium rare earth magnets, and refrigerant-grade steel vessels. Single-source vulnerability concentrates in Japanese and German magnetic-bearing controller suppliers. Distribution runs through OEM-direct project sales for large-tonnage systems and authorized distributor networks for modular configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifugal chillers market sits in a technology-transition phase as magnetic-bearing oil-free compressor systems displace conventional oil-lubricated units across premium efficiency tiers, recalibrating competitive positioning around part-load optimization and refrigerant compliance roadmaps.
For Market Incumbents: Deploy service network density as the primary defensive lever against emerging oil-free specialists. Expand certified technician training pipelines in secondary metropolitan clusters to address specialized maintenance scarcity for magnetic-bearing systems. Deepen backward integration into magnetic-bearing rotor manufacturing to secure supply continuity against rare earth price volatility. Anchor large-scale project pipelines through performance contracting arrangements that transfer operational risk and lock in long-term service revenue streams. For New Entrants and Emerging Players: Digital-channel direct specification tools targeting consulting engineers and energy service companies bypass incumbent distributor control. Mid-scale modular centrifugal configurations in India's constrained commercial retrofits and Southeast Asian data center expansions represent the most penetrable white-space opportunity. Pursue technology licensing agreements with established magnetic-bearing compressor developers to accelerate market entry without captive R&D investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated building automation providers seeking to consolidate lifecycle revenue capture. Long-term viability favors vendors with demonstrated refrigerant transition roadmaps and ASHRAE 90.1 compliance certification pipelines. Monitor EPA SNAP program revision timelines and EU F-Gas quota enforcement as inflection indicators for equipment replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Recertification | EPA AIM Act compliance deadlines and EU F-Gas quotas compress product development timelines for lower-GWP alternatives. |
| Magnetic-Bearing Technology Licensing | Mid-scale market penetration accelerates as oil-free compressor developers license bearing technology to regional manufacturers. |
| Performance Contracting Model Expansion | Healthcare and higher education verticals transfer operational risk to vendors through energy-as-a-service arrangements. |
| Service Network Geographic Extension | Qualified technician scarcity in secondary markets creates competitive moat for incumbents with training infrastructure. |
| District Energy Joint Ventures | European and North American cities retrofit centralized cooling plants through public-private partnerships meeting decarbonization targets. |
Methodological Framework
Independent corroboration across plant engineering directors, OEM procurement teams, aftermarket service heads, and energy service company executives underwrites the qualitative findings. Primary interviews with facility managers at hyperscale data center operators and pharmaceutical process cooling specialists were validated against secondary sources including EPA SNAP program filings, ASHRAE Standard 90.1 revision documentation, and EU F-Gas Regulation quota enforcement records. Bottom-up equipment shipment analysis triangulates against top-down construction spending data for commercial, industrial, and institutional verticals.
Rate-of-change decomposition across the projection horizon separates volume growth from value expansion and mix-shift effects. Segmentation dimensions modeled include product type tier, end-use vertical, installation configuration, and technology architecture. CAGRs derive from regression analysis of historical equipment replacement cycles, regulatory compliance deadline clustering, and energy efficiency standard adoption curves. Refrigerant transition roadmaps and magnetic-bearing technology diffusion rates serve as industry-specific forecast inputs.
Inputs from regulatory filing databases and equipment manufacturer certification records were available through the study window; gaps in real-time project pipeline visibility and proprietary service contract terms introduce uncertainty bands. Forecasts reflect documented assumptions regarding refrigerant phasedown enforcement consistency and copper price trajectory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Global Home Ventilation System Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
Europe Air Conditioning Equipment Market