
 Kitchen Hood System Market | 2026-2036
Kitchen Hood System Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Hood System Market Foresight
A capital-intensity divergence between in-house motor manufacturing and outsourced assembly is reorganizing competitive tiers across the kitchen hood system industry. Broan-NuTone leverages its captive supply of blower motors to sustain margin resilience against commodity stainless steel volatility. ZLINE Kitchen & Bath anchors its position through vertical control over Italian design sourcing and direct-to-consumer channel dominance.
A kitchen hood system is an engineered ventilation appliance comprising a canopy, grease filters, blower assembly, and ducting interface, designed to capture airborne contaminants, heat, and moisture generated during cooking operations at extraction rates typically measured in cubic feet per minute. Wall-mounted configurations occupy the largest installed base across North American residential kitchens due to compatibility with standard cabinetry layouts, while island installations command premium positioning in open-plan luxury developments where ducting infrastructure must route through ceiling cavities. Stainless steel dominates material selection for commercial hospitality deployments where NSF International sanitation standards mandate non-porous, corrosion-resistant surfaces.
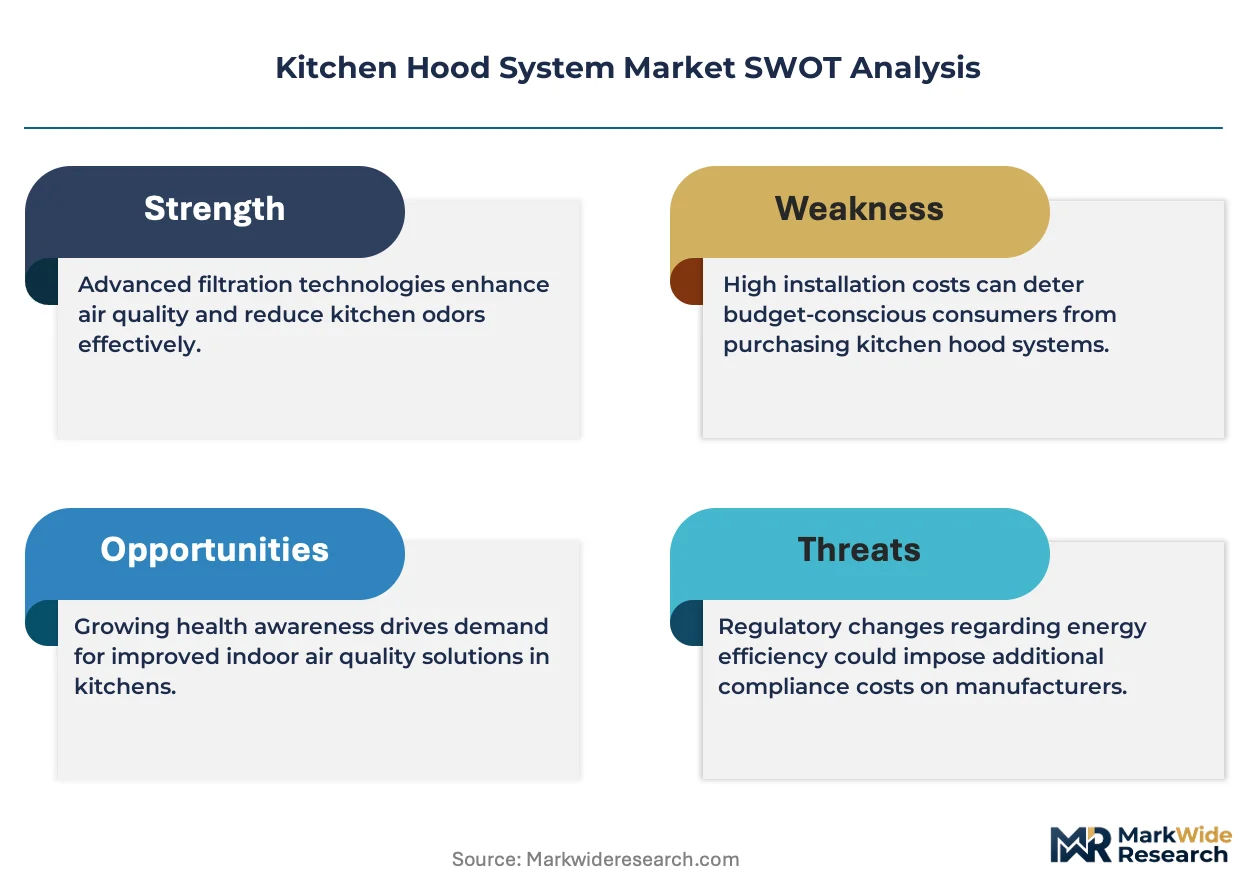
The U.S. Department of Energy and the EPA's ENERGY STAR program jointly shape product efficiency benchmarks and testing protocols that determine market access for hood systems sold in American jurisdictions. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based downdraft cooling integrations and mandate minimum airflow efficiency thresholds for CE-marked products distributed across European member states. Stakeholders must monitor evolving building electrification codes and induction cooktop pairing requirements that will redefine extraction capacity specifications and filter maintenance protocols.
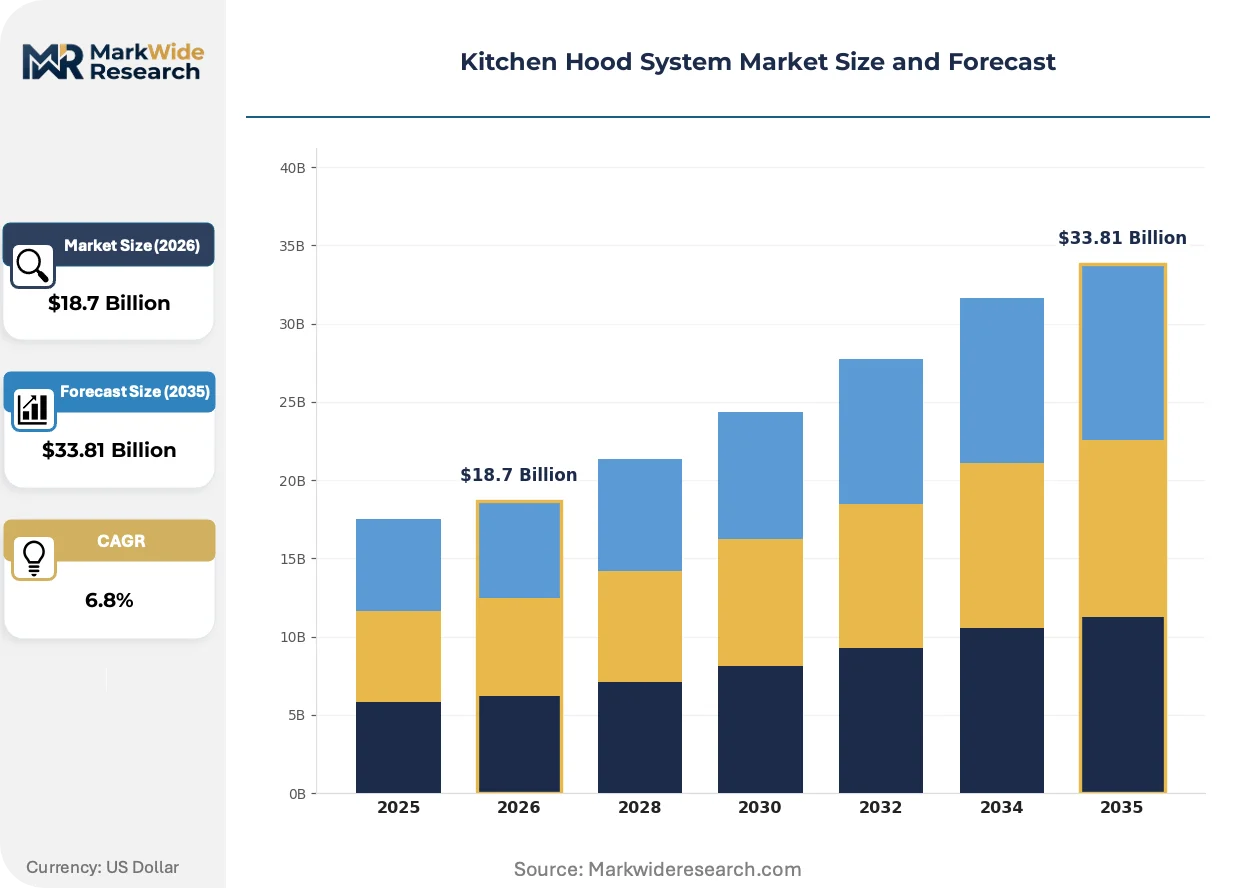
Market Dynamics
The kitchen hood system market is restructuring around motor manufacturing economics, where captive blower production separates margin-resilient suppliers from stainless steel price takers. This capital-intensity divergence is compressing competitive tiers and forcing strategic choices between in-house assembly and outsourced manufacturing partnerships.
Growth Catalysts
- DOE Efficiency Standards:The U.S. Department of Energy's tightening minimum airflow requirements are accelerating replacement cycles for non-compliant legacy installations in residential renovations.
- Urban Condominium Density:Compact apartment layouts in China's tier-one cities mandate high-performance extraction systems that exceed legacy ducted ventilation capacity.
- Induction Cooktop Pairing:Building electrification codes are redefining extraction specifications and filter maintenance protocols for induction-compatible hood systems.
Market Restraints
- Stainless Steel Volatility:Commodity price swings for 304-grade stainless steel compress margins for non-vertically integrated assemblers lacking captive metal sourcing.
- Supply Concentration Risk:Motor and blower assembly clusters in specific manufacturing geographies create vulnerability to logistics disruptions and tariff exposure.
- Downdraft Cooling Constraints:The EU F-Gas Regulation restricts refrigerant-based downdraft integrations, eliminating a premium product category from CE-marked portfolios.
Strategic Opportunities
- Direct-to-Consumer Channels:E-commerce platforms and manufacturer-direct sales are bypassing traditional kitchen retail intermediaries, capturing margin and customer data simultaneously.
- Italian Design Sourcing:Vertical control over European aesthetic development enables premium positioning in North American luxury kitchen renovations.
- ENERGY STAR Certification:EPA efficiency benchmarks create a regulatory tailwind for certified products accessing federal procurement and utility rebate programs.
Industry Challenges
- NSF Sanitation Compliance:Commercial hospitality deployments require corrosion-resistant surface certification that extends testing timelines and engineering cycles.
- Legacy Ducting Retrofit Complexity:Ceiling cavity routing in open-plan luxury developments demands specialized installation coordination with HVAC contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Hood System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Island, Under-Cabinet, Downdraft Installation Type: Fixed, Portable, Integrated, Modular Material: Stainless Steel, Aluminum, Glass, Composite End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | COSMO, Frigidaire, ZLINE Kitchen & Bath, Brano, Vissani, Hauslane, Broan-NuTone, Rustic Kitchen & Bath, Ciarra Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Hood System Market Shifts & Advancements
Active reshaping in kitchen hood systems centers on three vectors: motor and filtration technology compression, regulatory efficiency mandates tightening across jurisdictions, and procurement channel fragmentation disrupting traditional distribution.
DC brushless motor technology is miniaturizing blower assemblies while maintaining extraction rates measured in cubic feet per minute. High-rise residential developers in urban condominium markets are specifying these compact units to accommodate constrained mechanical chases. The technology is miniaturizing equipment footprints and enabling installation in previously inaccessible ceiling cavities.
The EU Ecodesign Directive is mandating minimum airflow efficiency thresholds for CE-marked products distributed across European member states. Manufacturers must redesign blower curves and filter geometries to meet these specifications or face market exclusion. Commercial hospitality suppliers with NSF International certification pipelines are most affected, as dual compliance extends development cycles.
Builder and contractor procurement is consolidating toward specification-grade suppliers capable of delivering certified products at volume scale. Traditional kitchen retail showrooms are losing share to direct manufacturer relationships and project-based distributor partnerships. This channel rotation is most visible in North American multi-family residential developments where general contractors control appliance specifications.
Kitchen Hood System Market Segmentation
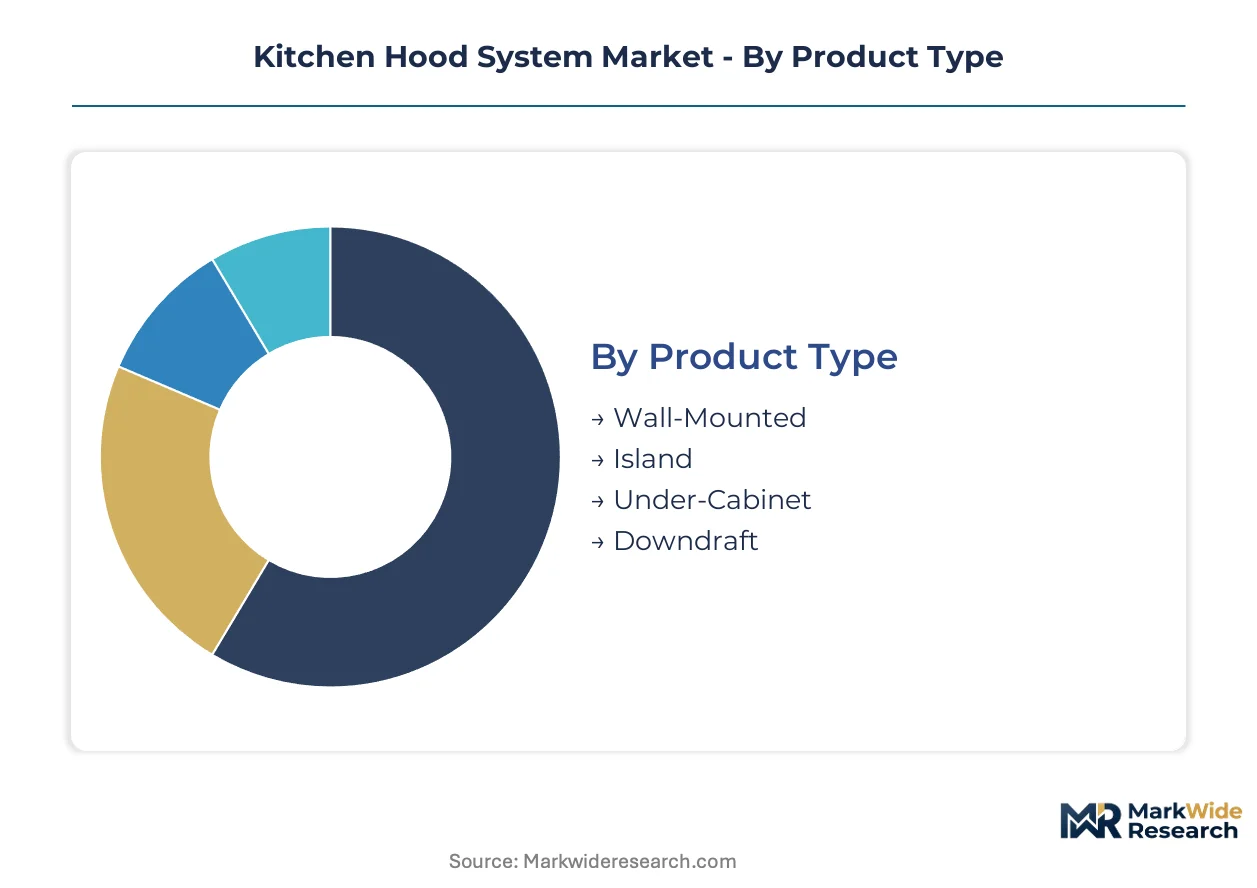
Kitchen hood system segmentation reveals where capital allocation and engineering cycles concentrate across architectural form factors, installation logistics, material specifications, and end-use compliance requirements. Margin pools diverge sharply between commodity replacement demand and specification-grade new construction.
Product Type:
Margin concentration follows installation complexity and ducting infrastructure requirements rather than unit volume alone.
- Wall-Mounted:These configurations integrate with standard 30-inch and 36-inch cabinetry modules through rear-wall ducting interfaces. North American residential renovation contractors specify these units most heavily where existing ductwork minimizes retrofit labor. The EPA ENERGY STAR certification pathway is most mature for this form factor.
- Island:Ceiling-suspended canopies require remote blower placement and concealed ducting through overhead cavities, commanding premium positioning in open-plan luxury developments. China's tier-one city developers specify these for compact high-rise layouts where kitchen islands anchor social space planning.
- Under-Cabinet:Space-constrained installations integrate filtration and blower assemblies within cabinetry envelopes, common in older urban housing stock with limited headroom.
- Downdraft:Retractable ventilation systems eliminate overhead canopy requirements but face regulatory constraints from EU F-Gas Regulation on refrigerant-based cooling integrations.
The dominant share belongs to Wall-Mounted configurations, while Island installations are gaining share fastest in luxury residential segments.
Installation Type:
Procurement patterns split between new construction specification and replacement retrofit, with very different margin structures.
- Fixed:Permanent ducted installations dominate commercial hospitality deployments where NSF International sanitation standards mandate hard-piped grease extraction systems. These installations generate recurring filter maintenance revenue streams.
- Modular:Field-configurable blower and canopy combinations allow general contractors to adapt specifications across multi-family residential projects without engineering change orders. North American builder procurement is consolidating toward these specification-grade suppliers.
- Portable:Ductless recirculating units with charcoal filtration serve rental housing and temporary kitchen installations where permanent ducting is prohibited.
- Integrated:Cooktop-embedded ventilation systems pair directly with induction and gas ranges, requiring coordinated appliance procurement through single-source suppliers.
Fixed installations command the largest installed base, though Modular systems are expanding most quickly in multi-family development channels.
Material:
Surface specification directly determines compliance pathway access and replacement cycle duration.
- Stainless Steel:304-grade and 430-grade alloys dominate commercial hospitality where NSF International mandates non-porous, corrosion-resistant surfaces for grease-laden environments. Commodity price volatility for nickel and chromium inputs compresses assembler margins without captive metal sourcing.
- Aluminum:Lightweight extrusions enable under-cabinet and portable configurations where structural load limits constrain canopy mass, prevalent in older European housing stock with timber ceiling joists.
- Glass:Tempered and coated glass surfaces enable aesthetic differentiation in premium residential renovations, though thermal shock resistance limits proximity to high-BTU gas ranges.
- Composite:Engineered polymer and mineral composites reduce unit weight for ceiling-suspended island installations while enabling non-standard color matching.
Stainless Steel retains the dominant specification share, while Composite materials are climbing the fastest in design-forward residential segments.
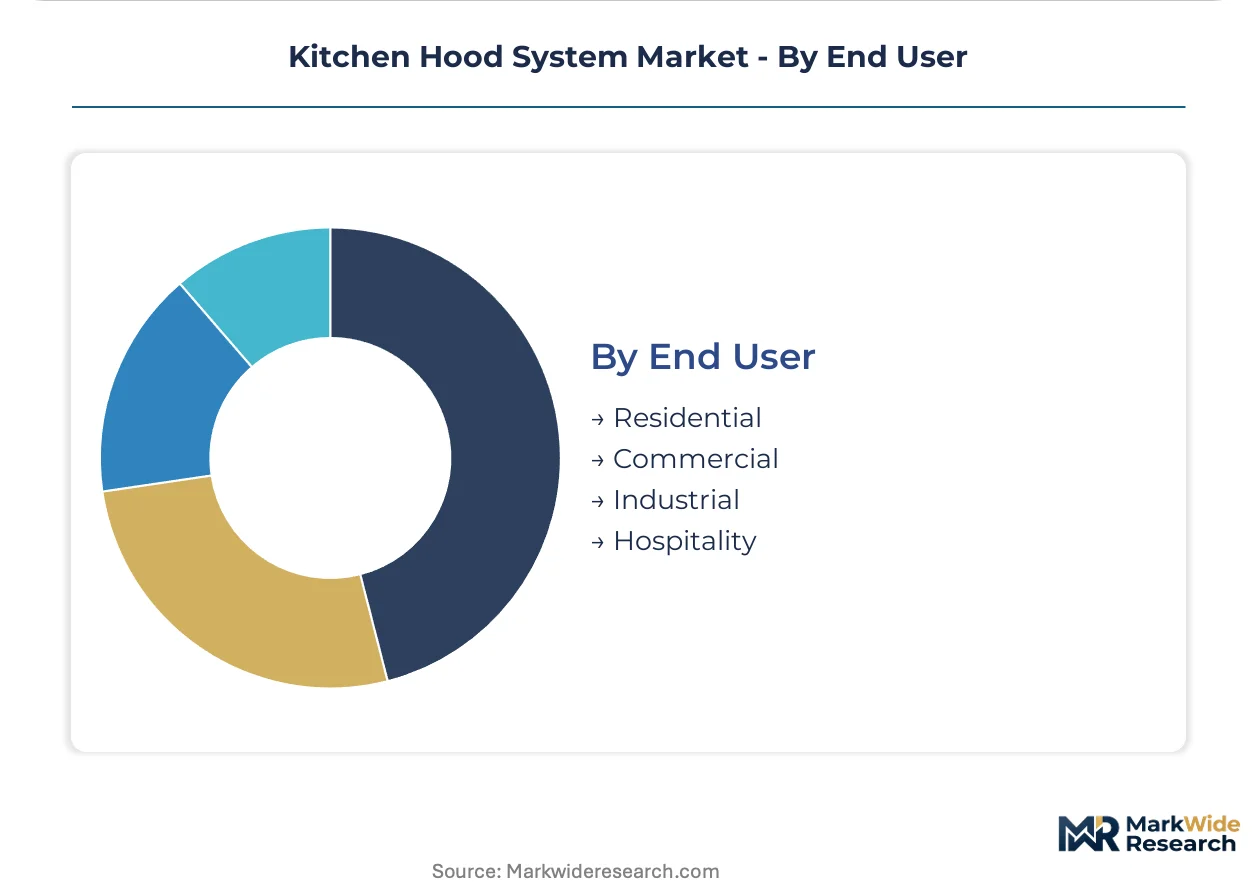
End User:
Compliance intensity and procurement authority concentration vary dramatically across installation settings.
- Residential:Single-family and multi-family homeowners drive replacement cycles through kitchen renovation activity, with purchasing decisions increasingly shifting to direct-to-consumer channels bypassing traditional retail showrooms.
- Commercial:Restaurant and foodservice operators face the most stringent grease extraction requirements under local fire codes and EPA emissions guidelines, mandating scheduled hood cleaning protocols.
- Hospitality:Hotel and institutional kitchen operators balance NSF sanitation compliance with aesthetic coordination across property portfolios, extending engineering validation timelines.
- Industrial:Central commissary and food manufacturing facilities specify heavy-duty extraction capacity measured in thousands of cubic feet per minute, with procurement controlled by facility engineering departments rather than chefs or contractors.
Residential demand holds the dominant volume position, while Hospitality specifications are closing the gap fastest in urban luxury development clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's tier-one cities show the lowest price elasticity as compact apartment layouts mandate high-performance extraction systems, while North American residential renovators exhibit higher sensitivity to stainless steel commodity swings.
United States
The U.S. Department of Energy's tightening minimum airflow requirements are accelerating replacement cycles for non-compliant legacy installations in residential renovations. The EPA's ENERGY STAR program shapes product efficiency benchmarks and testing protocols that determine market access. Chicago and New York metro developers specify wall-mounted configurations compatible with standard cabinetry layouts.
China
Urban condominium density in Shanghai, Beijing, and Shenzhen mandates extraction systems that exceed legacy ducted ventilation capacity in compact high-rise layouts. The Ministry of Ecology and Environment enforces dual carbon goals that constrain refrigerant-based cooling integrations. Guangdong province manufacturing clusters supply blower motor assemblies to domestic and export markets.
Germany
The EU Ecodesign Directive and F-Gas Regulation constrain downdraft cooling integrations and mandate minimum airflow efficiency thresholds for CE-marked products. Bavaria and North Rhine-Westphalia house engineering centers redesigning blower curves and filter geometries for compliance. Berlin's building electrification codes are redefining extraction specifications for induction-compatible hood systems.
Italy
European aesthetic development enables premium positioning in North American luxury kitchen renovations through vertical control over design sourcing. The EU Ecodesign Directive extends development cycles for dual-compliant commercial hospitality suppliers. Lombardy and Veneto industrial districts concentrate stainless steel fabrication and canopy finishing operations.
India
Residential kitchen renovations in urban condominiums are accelerating replacement cycles as middle-class households upgrade from basic recirculating units. The Bureau of Indian Standards sets appliance safety and performance benchmarks for domestic market access. Maharashtra and Gujarat manufacturing hubs assemble ducted ventilation systems for tier-one city distribution.
Kitchen Hood System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the kitchen hood system industry. The vendor base organizes around three strategic tiers: captive motor manufacturers defending margin resilience against commodity volatility, Italian design-sourced premium positioners, and direct-to-consumer channel specialists capturing customer data. Consolidation pressures favor specification-grade suppliers capable of delivering certified products at volume scale. Dominant competitive moves include backward integration into blower production and e-commerce platform development bypassing traditional retail intermediaries.
Among North American appliance manufacturers, Broan-NuTone exemplifies the captive supply archetype through in-house motor production, while Frigidaire represents established brand leverage in builder and contractor procurement channels. ZLINE Kitchen & Bath occupies a position within the direct-to-consumer tier, anchoring premium residential renovation demand through vertical control over European aesthetic sourcing.
| Leading Market Players |
|---|
| COSMO |
| Frigidaire |
| ZLINE Kitchen & Bath |
| Brano |
| Vissani |
| Hauslane |
| Broan-NuTone |
| Rustic Kitchen & Bath |
| Ciarra Appliances |
| Others |
Supply & Pricing Matrix
Capacity utilization at Guangdong province blower motor clusters shapes both supply concentration and price floors for kitchen hood system assemblers. Scale economies in captive motor manufacturing allow integrated producers to absorb stainless steel volatility while outsourced competitors face margin compression from commodity input swings.
Pricing Analysis
Filter replacement service contracts and extended maintenance agreements drive lifetime value beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial installations from residential renovation products and basic recirculating units. Cost compression in economy-tier ductless systems is intensifying because of charcoal filter commoditization and Asian import competition. Multi-family residential developers exhibit highest price sensitivity, while hospitality procurement teams prioritize certification compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for 304-grade stainless steel sheet and nickel-chromium alloys feeding Chinese and Italian fabrication centers. Motor winding copper draws from Chilean and Peruvian mining operations, while electronic control modules source from South Korean and Taiwanese semiconductor packaging facilities. Single-source vulnerability concentrates in Guangdong blower assembly clusters exposed to tariff escalation and logistics disruption. Distribution runs through project-based distributor partnerships serving North American general contractors and direct-to-consumer platforms bypassing traditional kitchen retail showrooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building electrification codes and induction cooktop proliferation threaten legacy gas-range hood specifications, forcing incumbents to defend substitution risk through extraction capacity redesign and filter protocol innovation.
For Market Incumbents: Shield specification-grade positioning by deepening backward integration into DC brushless motor production and securing ENERGY STAR certification pipelines ahead of DOE efficiency tightening. Counter downdraft ventilation substitution by emphasizing island canopy performance in open-plan luxury developments where ceiling cavity routing remains technically superior. For New Entrants and Emerging Players: Anchor in India's tier-one city residential renovation channel where middle-class households upgrade from basic recirculating units and procurement authority fragments across contractors and direct-to-consumer platforms. Exploit aesthetic differentiation through composite material canopy finishes targeting design-forward segments underserved by stainless steel incumbents. For Investors and Strategic Acquirers: Captive motor manufacturers with Guangdong production footprints and Italian design-sourced premium positioners represent the most defensible acquisition archetypes as channel consolidation favors specification-grade suppliers. Monitor EPA ENERGY STAR program expansion and utility rebate program adoption as inflection indicators for certified product demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blower Motor Production | In-house DC brushless manufacturing absorbs stainless steel volatility and defends margin resilience against commodity price swings. |
| Direct-to-Consumer Channel Development | E-commerce platform investment captures customer data and bypasses traditional kitchen retail intermediaries in North American renovation markets. |
| ENERGY STAR Certification Investment | EPA efficiency benchmark compliance unlocks federal procurement access and utility rebate program eligibility for specification-grade products. |
| Italian Design Sourcing Partnership | Vertical control over European aesthetic development enables premium positioning in luxury kitchen renovation segments. |
| Modular Product Architecture Launch | Field-configurable blower and canopy combinations reduce engineering change orders for multi-family residential general contractors. |
Research Methodology
Operator-level perspectives from HVAC contractors, kitchen renovation specialists, commercial foodservice operators, and multi-family residential developers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with aftermarket service technicians and procurement managers at hospitality portfolio operators. Secondary validation drew from DOE appliance efficiency filings, EPA ENERGY STAR certification databases, EU Ecodesign Directive compliance registries, and customs trade data for stainless steel sheet imports. Bottom-up unit shipment estimates triangulated against top-down construction spending allocation models.
Sensitivity analysis around induction cooktop penetration rates and building electrification code adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, installation type, material specification, and end-use compliance intensity. CAGRs derived from polynomial trend fitting against historical replacement cycle data and new construction permit flows. Industry-specific forecast inputs incorporated blower motor technology substitution curves and filter maintenance protocol evolution.
Material uncertainties — regulatory efficiency standard acceleration, stainless steel commodity price spikes, and logistics disruption at Guangdong manufacturing clusters — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EPA ENERGY STAR program expansion and EU F-Gas Regulation enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Steam Boiler Systems Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
United Kingdom Heating Equipment Market