
 North America, Europe, and Asia Pacific Air Compressor Market | 2026-2036
North America, Europe, and Asia Pacific Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
North America, Europe, and Asia Pacific Air Compressor Market Analytics
Multi-source procurement for precision-machined airend components is repositioning how OEMs manage compressor assembly costs. Atlas Copco AB leverages its captive foundry network to control rotor casting quality across European facilities. Ingersoll Rand sustains aftermarket revenue through proprietary controller ecosystems that lock in service contracts. Siemens AG anchors its position with integrated variable-speed drive packages that reduce energy draw in German automotive plants.
Air compressors in North America, Europe, and Asia Pacific are mechanical devices that convert power into potential energy stored in pressurized air, typically delivering discharge pressures from 100 to 175 psi for industrial duty cycles. Rotary screw compressors dominate installed base value across manufacturing applications where continuous duty requirements exceed 4,000 annual operating hours. Reciprocating units retain share in intermittent-duty automotive service bays and smaller construction sites where capital constraints favor lower first cost. Oil and gas pipeline service applications increasingly specify centrifugal designs for multi-megawatt base load compression, concentrating margin pools in aftermarket parts and condition monitoring services.
The US Department of Energy enforces mandatory efficiency standards under 10 CFR 431 that disqualify fixed-speed models from federal procurement channels, reshaping product mix toward variable frequency drive configurations. EU F-Gas Regulation and REACH compliance requirements from ECHA pressure manufacturers to eliminate synthetic lubricants with high global warming potential from sealed compressor systems. Stakeholders must monitor how California's Title 24 building codes and China's GB energy efficiency grades converge on test protocols, as harmonized standards would collapse regional product differentiation strategies.
Market Dynamics
The US Department of Energy's 10 CFR 431 efficiency mandates are compressing product lifecycles and forcing OEMs to abandon fixed-speed architectures before natural replacement cycles conclude. This regulatory pressure is redrawing competitive boundaries across all three regions.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants in sealed systems is accelerating demand for oil-free compressor technologies in food and beverage processing lines across Germany and France.
- China's industrial corridor expansion:Automotive and electronics assembly plants in Jiangsu and Guangdong provinces require high-volume compressed air infrastructure for robotic welding and precision coating operations.
- Permanent magnet motor integration:Variable-speed drive packages with synchronous motor technology are capturing share in German automotive stamping plants seeking to cut energy draw during partial-load operation.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing facilities creates input cost volatility for high-efficiency motor production.
- REACH compliance complexity:ECHA substance restrictions on synthetic lubricants with high global warming potential force reformulation cycles that extend R&D timelines by 18-24 months.
- Centrifugal compressor capex thresholds:Multi-megawatt base load systems require project financing structures that exclude mid-sized manufacturing facilities from accessing most efficient compression technology.
Strategic Opportunities
- Southeast Asia manufacturing migration:Vietnam and Indonesia electronics assembly growth is outpacing installed compressed air capacity, creating greenfield specification opportunities.
- Condition monitoring convergence:Integration of vibration analysis with IoT edge computing enables predictive maintenance contracts that capture lifetime value from aftermarket parts and service.
- California Title 24 building codes:Mandatory energy efficiency grades for compressed air systems in commercial buildings are creating regulatory tailwind for premium variable-speed configurations in Western US states.
Industry Challenges
- Rotor machining skill scarcity:Precision grinding of screw compressor airends requires specialized tooling expertise concentrated in aging workforce pools across Midwest US manufacturing regions.
- Legacy controller integration friction:Proprietary communication protocols from incumbent OEMs block third-party monitoring solutions, complicating multi-vendor facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America, Europe, and Asia Pacific Air Compressor Market |
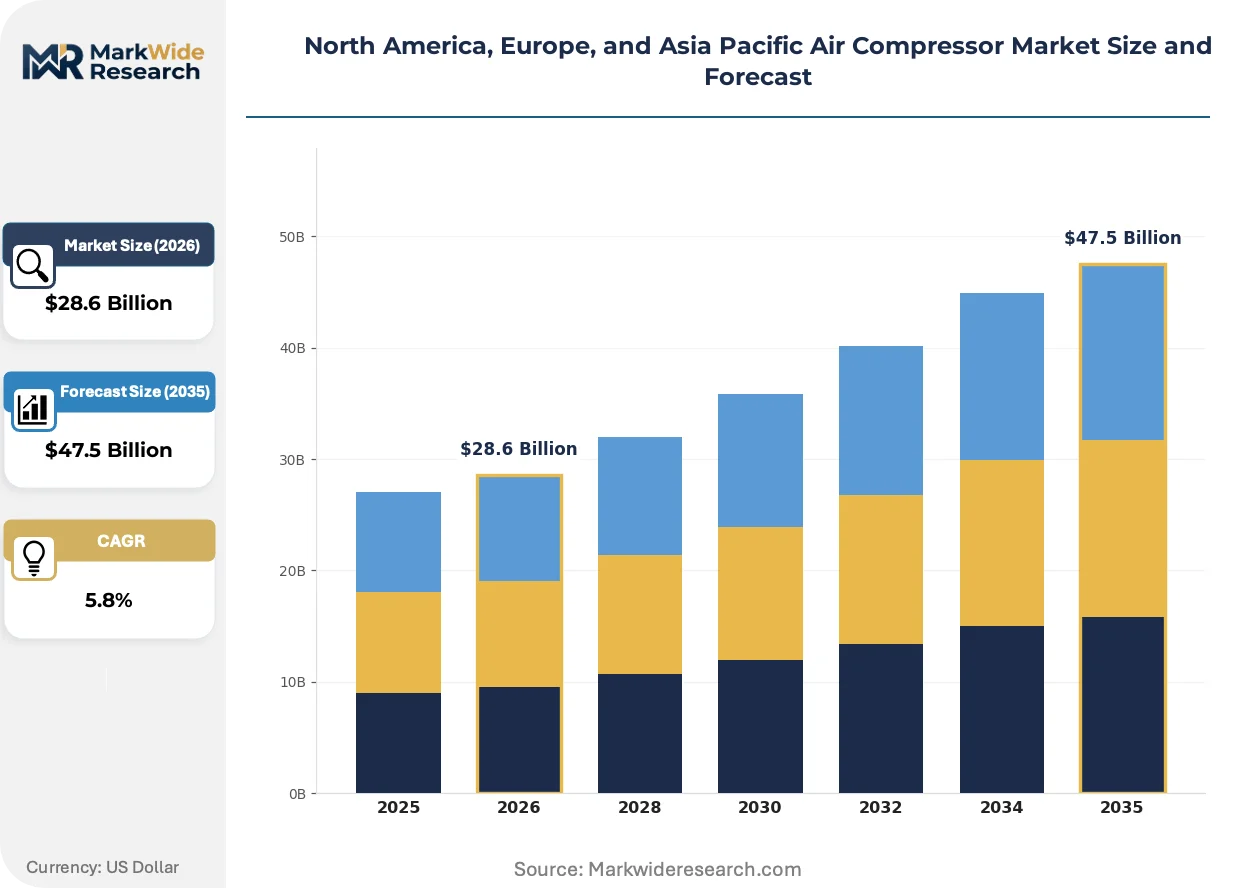
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Screw, Reciprocating, Centrifugal, Scroll Application: Manufacturing, Construction, Oil & Gas, Automotive End User: Aerospace, Food & Beverage, Healthcare, Chemical Power Source: Electric, Diesel, Gas, Solar |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Mitsubishi Heavy Industries Ltd., Hitachi Industrial Equipment Systems Co. Ltd., Siemens AG, KAESER KOMPRESSOREN, Doosan Portable Power, ELGi Equipments Limited, BAUER COMP Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America, Europe, and Asia Pacific Air Compressor Market Evolving Landscape
Digital twin deployment and edge-based analytics are compressing maintenance intervals and rewriting how compressed air service contracts are priced and delivered across industrial facilities.
Permanent magnet synchronous motor technology paired with advanced power electronics is overtaking induction motor drives in continuous-duty applications above 75 kW. German automotive stamping plants are specifying these configurations for new press lines. The technology is overtaking conventional variable frequency drives by eliminating rotor losses and enabling 95%-plus motor efficiency across partial load curves.
REACH authorization requirements from ECHA are forcing lubricant suppliers to reformulate synthetic compressor oils with lower global warming potential. Manufacturers must submit substitution plans for perfluoropolyether-based fluids used in oil-free systems. Food and beverage processors in France and Italy are accelerating audits of sealed compressor lubricant inventories to preempt compliance deadlines.
Compressed air-as-a-utility contracting is displacing capital purchase models in multi-site manufacturing portfolios. Third-party operators assume ownership of on-site generation assets and charge per cubic meter delivered. This model is most visible in Japanese electronics assembly where METI energy efficiency guidelines favor outsourced utility management over in-house compressor fleets.
North America, Europe, and Asia Pacific Air Compressor Market Segmentation
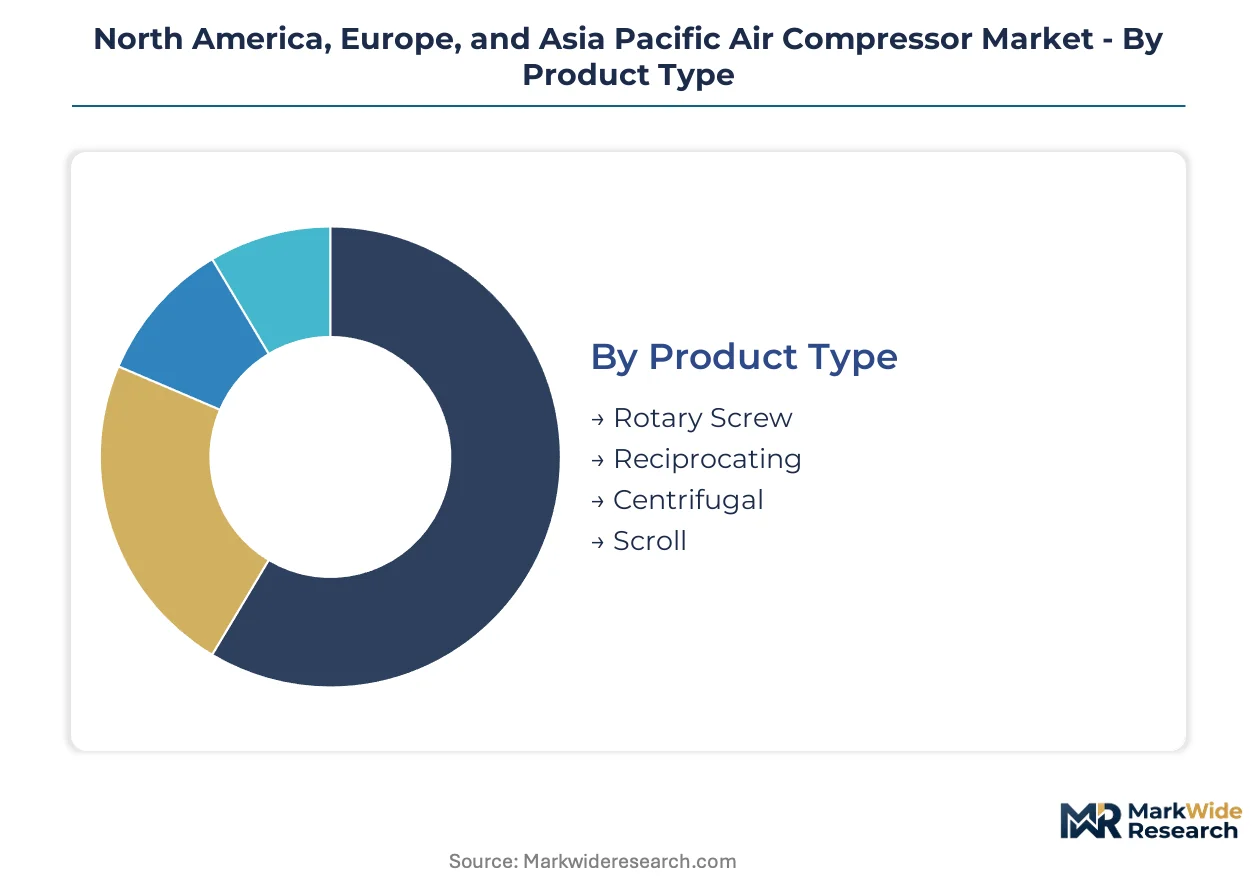
Segmentation reveals how compressor specifications diverge across duty cycles, energy sources, and regulatory environments. Understanding these splits exposes where margin pools concentrate and which technology transitions are structurally inevitable.
Product Type:
Supply concentration for precision-machined airend components shapes competitive positioning across compressor architectures.
- Rotary Screw:Positive displacement machines with intermeshing helical rotors deliver continuous airflow for industrial duty cycles exceeding 4,000 annual hours. German automotive stamping plants and China's Jiangsu electronics corridors specify these for robotic welding and coating lines under tightening EU F-Gas and China GB efficiency mandates.
- Reciprocating:Piston-driven compression generates intermittent high-pressure output suited for automotive service bays and smaller construction sites where capital constraints dominate procurement decisions. These units retain installed base share where duty cycles remain below 2,000 hours annually.
- Centrifugal:Dynamic compression through rotating impellers handles multi-megawatt base loads in pipeline service and large-scale manufacturing.
- Scroll:Orbiting spiral design produces oil-free compressed air for medical and laboratory environments requiring stringent air purity standards.
Rotary screw compressors absorb the bulk of installed capacity; scroll designs are expanding most quickly in healthcare and food processing applications.
Application:
Cost tier differentiation separates premium continuous-duty systems from intermittent-use configurations across industrial verticals.
- Manufacturing:Automated assembly lines, metal fabrication, and packaging operations require reliable compressed air infrastructure with integrated variable-speed drives. France and Italy food processors are accelerating audits of sealed system lubricants to preempt REACH authorization deadlines from ECHA.
- Oil & Gas:Pipeline transmission and upstream processing specify multi-stage centrifugal systems with aftermarket service contracts capturing lifetime value. US Gulf Coast petrochemical clusters and North Sea platforms drive specification for explosion-proof configurations.
- Construction:Mobile diesel-driven units serve remote sites with intermittent demand profiles and limited grid access.
- Automotive:Stamping, painting, and final assembly lines in Germany, Michigan, and Guangdong provinces anchor demand for high-volume, precision-pressure compressed air systems.
Manufacturing absorbs the bulk of installed capacity; oil and gas applications command the steepest expansion trajectory for aftermarket service revenue.
End User:
Customer type determines certification requirements and lubricant specifications that fragment supplier relationships.
- Food & Beverage:Oil-free compression with FDA and EFSA-compliant materials handling is mandatory for product contact zones. German processors face EU F-Gas phasedown pressures accelerating technology refresh cycles.
- Healthcare:Medical-grade air for respiratory therapy and surgical tools requires ISO 8573-1 Class 0 certification with redundant backup systems. US hospital systems and Japanese medical device manufacturers specify scroll and oil-free rotary technologies.
- Aerospace:Precision manufacturing of turbine components and airframe assemblies demands ultra-dry compressed air with dew point monitoring.
- Chemical:Process gas compression and instrument air systems in Texas and Rotterdam chemical corridors specify corrosion-resistant materials and hazardous area certifications.
Food and beverage absorbs the bulk of installed capacity; healthcare is climbing the fastest on aging infrastructure replacement and pandemic-driven capacity expansion.
Power Source:
Geography determines grid reliability and renewable penetration that shapes power source selection across facility types.
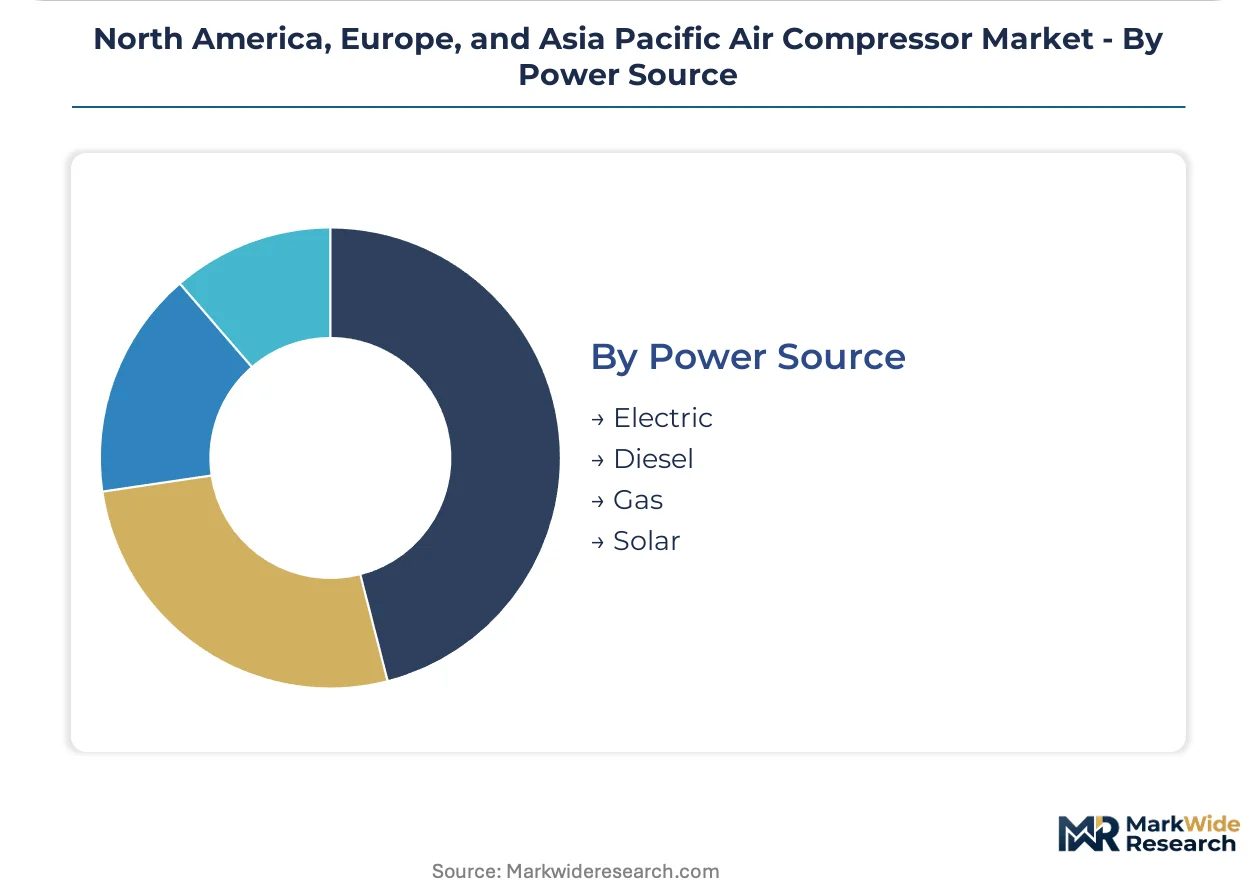
- Electric:Grid-connected permanent magnet motor drives dominate continuous-duty applications above 75 kW. California Title 24 building codes and China's GB energy efficiency grades are converging test protocols that favor variable-speed electric configurations.
- Diesel:Off-grid and backup power for construction, mining, and emergency services maintains share where electrification remains uneconomical.
- Gas:Natural gas engine drives serve large industrial facilities with on-site fuel access and combined heat and power integration.
- Solar:Photovoltaic-powered compression with battery storage is penetrating remote agricultural and water pumping applications in Australia's interior and India's Rajasthan state.
Electric drives absorb the bulk of installed capacity; solar configurations are gaining share fastest in off-grid and sustainability-focused procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial compressed air demand clusters in three distinct manufacturing corridors. Germany's automotive stamping plants, China's Jiangsu electronics assembly hubs, and the US Gulf Coast petrochemical belt each drive specification intensity for high-volume, precision-pressure systems.
United States
Automotive stamping plants in Michigan and petrochemical clusters along the Texas Gulf Coast anchor demand for multi-megawatt centrifugal systems. The US Department of Energy enforces 10 CFR 431 efficiency mandates that disqualify fixed-speed models from federal procurement channels. California's Title 24 building codes are creating regulatory tailwind for premium variable-speed configurations in Western states.
Germany
Food and beverage processing lines across Bavaria and Baden-Württemberg drive adoption of oil-free compressor technologies amid tightening EU F-Gas Regulation phasedown schedules. ECHA REACH compliance requirements pressure manufacturers to eliminate synthetic lubricants with high global warming potential from sealed systems. Stuttgart's automotive stamping plants specify permanent magnet synchronous motor drives for new press lines.
China
Automotive and electronics assembly plants in Jiangsu and Guangdong provinces require high-volume compressed air infrastructure for robotic welding and precision coating operations. MIIT GB energy efficiency grades are converging test protocols with Western standards. The Yangtze River Delta manufacturing corridor is outpacing installed capacity expansion, forcing technology refresh cycles.
Japan
Electronics assembly operations in the Kanto and Kansai regions favor compressed air-as-a-utility contracting over capital purchase models. METI energy efficiency guidelines favor outsourced utility management over in-house compressor fleets. Nagoya's automotive component suppliers are specifying condition monitoring integration with IoT edge computing.
India
Automotive manufacturing in Tamil Nadu and pharmaceutical processing in Maharashtra drive specification for oil-free scroll and rotary technologies. BIS energy efficiency standards are tightening alignment with ISO 8573-1 air purity certifications. The Delhi-Mumbai Industrial Corridor is attracting greenfield electronics assembly investment requiring compressed air infrastructure.
North America, Europe, and Asia Pacific Air Compressor Market Competitive Landscape
Permanent magnet motor integration dominates the current landscape as OEMs race to meet efficiency mandates ahead of regulatory deadlines. The vendor base concentrates around three tiers: European precision engineering houses with captive foundry networks, North American full-line suppliers with proprietary controller ecosystems, and Asian conglomerates leveraging vertical manufacturing integration. Strategic archetypes include efficiency-focused technology licensors, aftermarket service aggregators, and regional fabrication specialists. M&A activity and strategic technology licensing are the dominant competitive vectors reshaping market boundaries.
Among European precision engineering specialists, Atlas Copco AB and KAESER KOMPRESSOREN exemplify the foundry-integrated archetype controlling rotor casting quality. Siemens AG anchors the industrial automation tier with integrated drive packages. Ingersoll Rand occupies a position in the North American aftermarket service tier through proprietary controller ecosystems. Mitsubishi Heavy Industries Ltd. and Hitachi Industrial Equipment Systems Co. Ltd. represent the Asian conglomerate model with captive manufacturing integration.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Mitsubishi Heavy Industries Ltd. |
| Hitachi Industrial Equipment Systems Co. Ltd. |
| Siemens AG |
| KAESER KOMPRESSOREN |
| Doosan Portable Power |
| ELGi Equipments Limited |
| BAUER COMP Holding GmbH |
| Others |
Value Network & Pricing Analysis
Rare earth magnet costs flow from Chinese processing facilities through permanent magnet motor production lines, concentrating pricing power among OEMs with captive neodymium supply agreements before reaching tiered equipment configurations downstream.
Pricing Analysis
High-volume rotary screw configurations sacrifice margin for installed base capture while oil-free centrifugal systems command premium positioning. Pricing stratifies across premium variable-speed permanent magnet drives, standard induction motor packages, and economy fixed-speed units based on energy efficiency certification tier and bundled aftermarket service scope. Cost compression in mid-tier electric drives is intensifying because REACH lubricant reformulation is extending R&D cycles. Small automotive service bays exhibit acute price sensitivity; German automotive stamping plants prioritize lifecycle energy cost over first cost.
Supply Chain Analysis
ISO 8573-1 Class 0 certification requirements gate supplier access to food and beverage and healthcare end-use segments, fragmenting component sourcing across qualified vendors. Precision-machined airend production draws from German and Japanese tooling expertise, with rotor casting concentrated in European captive foundries. Neodymium and dysprosium sourcing rests on Chinese processing concentration, creating single-source vulnerability for high-efficiency motor production. Distribution runs through OEM-direct specification for large manufacturing accounts and industrial distribution channels for smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is executing a forced transition from fixed-speed induction architectures to permanent magnet synchronous motor drives, with regulatory deadlines compressing replacement cycles ahead of natural equipment retirement.
For Market Incumbents: Deploy captive foundry capacity to lock in rotor machining quality as precision grinding skill scarcity intensifies across Midwest US manufacturing regions. Accelerate proprietary controller ecosystem development to block third-party monitoring integration and protect aftermarket service contract capture. Atlas Copco AB and KAESER KOMPRESSOREN illustrate this defensive posture through integrated airend production. For New Entrants and Emerging Players: California Title 24 building codes in the United States open a window for premium variable-speed configurations in Western states where regulatory tailwind exceeds incumbent coverage. Target Vietnam and Indonesia electronics assembly corridors where greenfield compressed air capacity lags manufacturing migration. Pursue compressed air-as-a-utility contracting models to bypass capital purchase barriers in Japanese electronics assembly operations. For Investors and Strategic Acquirers: Permanent magnet motor integration announcements from German automotive stamping plants are the leading indicator that efficiency-focused technology licensors will command valuation premiums. Position acquisition screening around aftermarket service aggregators with condition monitoring capabilities and IoT edge computing integration. A model refresh is warranted upon material change in rare earth magnet supply policy or REACH authorization timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Eliminates rotor losses and enables 95%-plus efficiency across partial load curves in German automotive plants. |
| Condition Monitoring Convergence | Integrates vibration analysis with IoT edge computing to capture lifetime aftermarket value from predictive maintenance contracts. |
| REACH Lubricant Reformulation | Forces 18-24 month R&D cycles to substitute perfluoropolyether fluids and maintain oil-free system certification. |
| Compressed Air-as-a-Utility Contracting | Displaces capital purchase models in Japanese electronics assembly where METI guidelines favor outsourced management. |
| Southeast Asia Manufacturing Migration | Creates greenfield specification opportunities in Vietnam and Indonesia where installed capacity trails electronics assembly growth. |
Research Methodology
Independent corroboration across compressor OEM technical directors, plant engineers at German automotive stamping facilities, and aftermarket service heads underwrites the qualitative findings in this study. Primary interviews with maintenance directors, food and beverage processing line managers, and industrial distribution channel partners combined with secondary validation from customs trade data, SEC 10-K filings, and EU ECHA REACH authorization databases. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates were triangulated to anchor market sizing.
Comparable historical periods spanning efficiency mandate implementation phases anchored the forecast window to observed technology transition velocities across the projection horizon. Segmentation modeling incorporated product type, application vertical, end-use certification requirements, and power source configuration dimensions. CAGRs were derived from installed base turnover rates and regulatory deadline impacts on replacement demand, with permanent magnet motor adoption curves and rare earth magnet price volatility as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for fixed-speed compressor retention would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and rare earth supply continuity that material shifts in Chinese export policy or REACH timeline acceleration would invalidate. A model refresh is warranted upon material change in EU F-Gas Regulation phasedown schedules or California Title 24 code expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
France HVAC Market
HVAC Equipment
Middle-East and Africa Compressor Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
HVAC Pumps Market