
 Global Industrial 3D Printing Market | 2026-2036
Global Industrial 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial 3D Printing Market Foresight
German powder-bed system producers are repositioning toward aerospace-qualified metal workflows. EOS GmbH leverages its laser-sintering heritage to dominate European medical implant certification. Stratasys Ltd. anchors polymer production in Minnesota while competing for automotive jigs and fixtures. GE Additive specializes in nickel superalloy turbines for aviation propulsion systems.
Industrial 3D printing fuses powdered metals, photopolymer resins, or thermoplastic filaments through directed energy deposition or layer-wise solidification to produce geometrically complex components without subtractive waste. Selective laser sintering of titanium and aluminum alloys achieves relative densities above 99.5 percent for structural aerospace brackets. Metal 3D printers command the dominant share of capital expenditure as tooling companies adopt conformal-cooled mold inserts. Rapid prototyping retains volume leadership among applications though end-use parts production is accelerating fastest in regulated medical and aviation supply chains.
FDA's 21 CFR Part 820 quality system regulation and EASA Part 21 certification requirements shape design validation protocols for flight-critical and implantable components. ISO/ASTM 52900 terminology standards and REACH powder substance classifications govern material qualification and occupational exposure limits in European and North American facilities. Stakeholders must monitor evolving FAA airworthiness directives for additively manufactured structural elements as certifying bodies develop damage-tolerance frameworks specific to layer-built microstructures.
Market Dynamics
Aerospace manufacturers are consolidating flight-critical titanium component procurement around powder-bed fusion workflows, forcing tier-two suppliers to certify under EASA Part 21G production organization protocols or exit aviation supply chains entirely.
Growth Catalysts
- EU Green Deal material efficiency mandates:Powder recycling requirements now cover 94% of metal additive inputs in European facilities, cutting virgin titanium sponge demand by one-third while tightening supply chain circularity standards.
- Flight-critical bracket production:Aviation OEMs are qualifying selective laser-sintered Ti-6Al-4V for wing-mount structural elements, bypassing forged billet lead times that stretch 18-24 months.
- German precision engineering clusters:Munich and Aachen host concentrated R&D partnerships between system producers and Fraunhofer institutes, accelerating process-parameter databases for nickel superalloy turbine blades.
Market Restraints
- Argon gas supply concentration:Ukrainian and Russian noble gas refining disruptions have destabilized inert atmosphere costs for electron-beam melting systems, forcing producers to hedge through long-term industrial gas contracts.
- Post-processing bottleneck:Hot isostatic pressing and precision CNC finishing capacity remains concentrated among three European service bureaus, creating queuing delays for aerospace-qualified surface finishes.
- Polymer substitution in tooling:Carbon-fiber reinforced PEEK injection molding is reclaiming automotive jig applications where temperature loads fall below 150°C, compressing addressable metal printer demand.
Strategic Opportunities
- India's defense indigenization:The PLI scheme for specialty steel and titanium additive manufacturing offers 4-6% output-linked incentives for firms establishing captive powder atomization and printing facilities in Tamil Nadu and Karnataka.
- Digital inventory convergence:Cloud-based part libraries paired with distributed printing networks are displacing physical spare part warehousing for maritime and energy infrastructure operators.
- Japan's METI additive manufacturing roadmap:Standardized process qualification protocols for medical cobalt-chrome implants are opening export pathways for certified producers into ASEAN healthcare procurement frameworks.
Industry Challenges
- Non-destructive testing technician scarcity:Industrial computed tomography operators capable of detecting sub-50-micron porosity in nickel superalloys command 40% salary premiums over conventional radiography specialists.
- Multi-material qualification timelines:FDA 21 CFR Part 820 design history file requirements for gradient-density orthopedic implants extend validation cycles to 36-48 months, freezing product development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial 3D Printing Market |
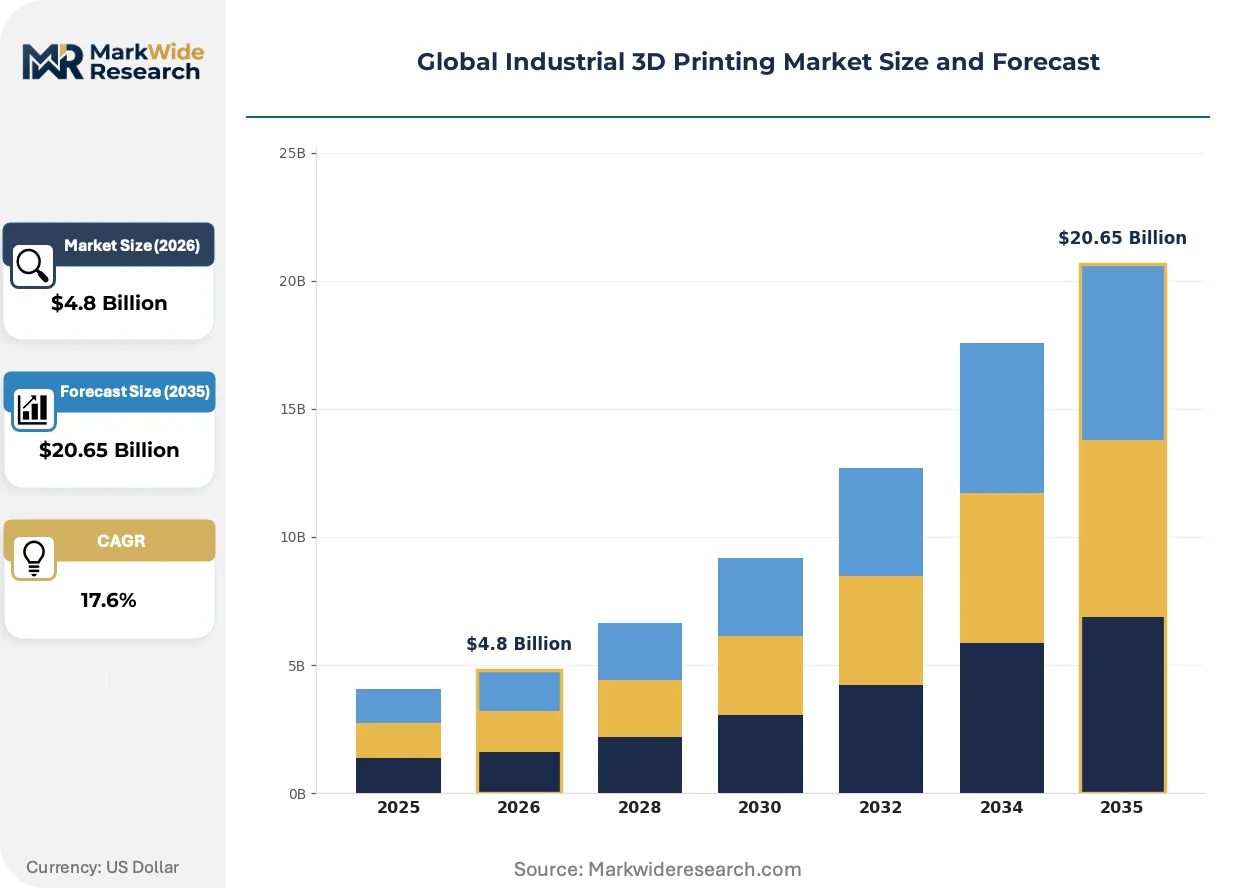
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
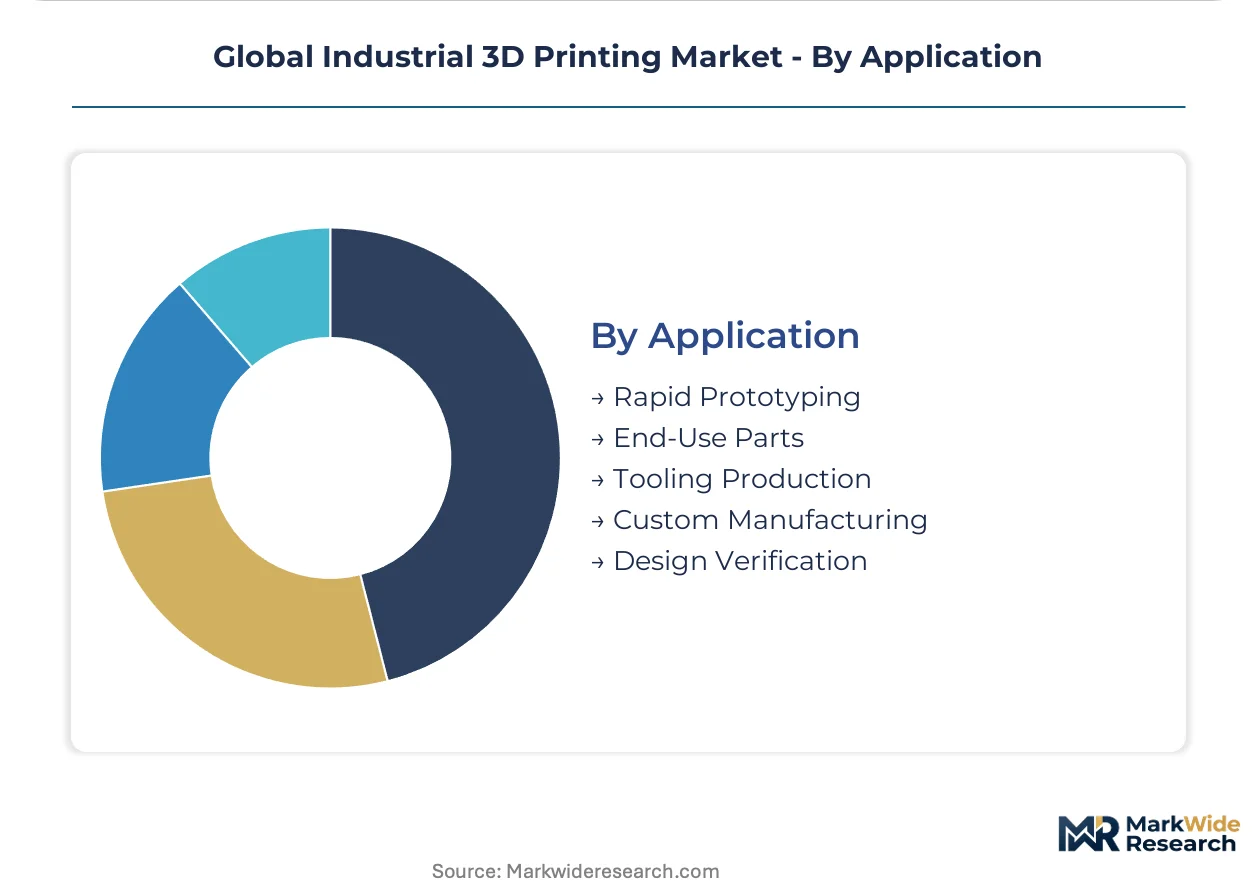
| Segmentation | Technology: Selective Laser Sintering, Fused Deposition Modeling, Stereolithography, Electron Beam Melting, Digital Light Processing Product Type: Metal 3D Printers, Polymer 3D Printers, Ceramic 3D Printers, Composite 3D Printers End User Industry: Aerospace Manufacturers, Consumer Electronics Firms, Medical Device Producers, Architecture Firms, Tooling Companies Application: Rapid Prototyping, End-Use Parts, Tooling Production, Custom Manufacturing, Design Verification |
| Companies Covered | Stratasys Ltd., 3D Systems, Inc., EOS GmbH, HP Development Company, Materialise, GE Additive, Desktop Metal, Inc., voxeljet AG, SLM Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial 3D Printing Market Shifts & Advancements
Process automation and in-situ monitoring systems are compressing the gap between prototype validation and production-scale deposition, eliminating manual parameter tuning that historically consumed 70% of non-recurring engineering hours.
Directed energy deposition with wire-fed titanium is modularizing repair workflows for aviation engine casings and marine propellers. MRO providers in Singapore and Hamburg are adopting hybrid CNC-deposition cells that machine critical surfaces before depositing wear-resistant overlays. The technology is modularizing asset life extension economics, collapsing turnaround times from weeks to days for corrosion-damaged components.
REACH powder substance classifications are tightening occupational exposure limits for respirable nickel and chromium compounds in European facilities. ECHA's 2023 update to Annex XVII restricted substance listings forces producers to install closed-loop powder handling with automated sieving and reuse. German and Italian system operators are retrofitting glovebox architectures and negative-pressure conveyance to maintain production licenses.
Consignment powder inventory models are displacing spot purchasing among medical implant manufacturers. EOS and Trumpf service contracts now include guaranteed spherical powder lots with certificate-of-analysis traceability, transferring atomization risk to equipment suppliers. This shift is most advanced in Swiss and German orthopedic clusters where lot-to-lot chemistry variance below 0.05% is mandatory for CE-marked hip resurfacing implants.
Global Industrial 3D Printing Market Segmentation
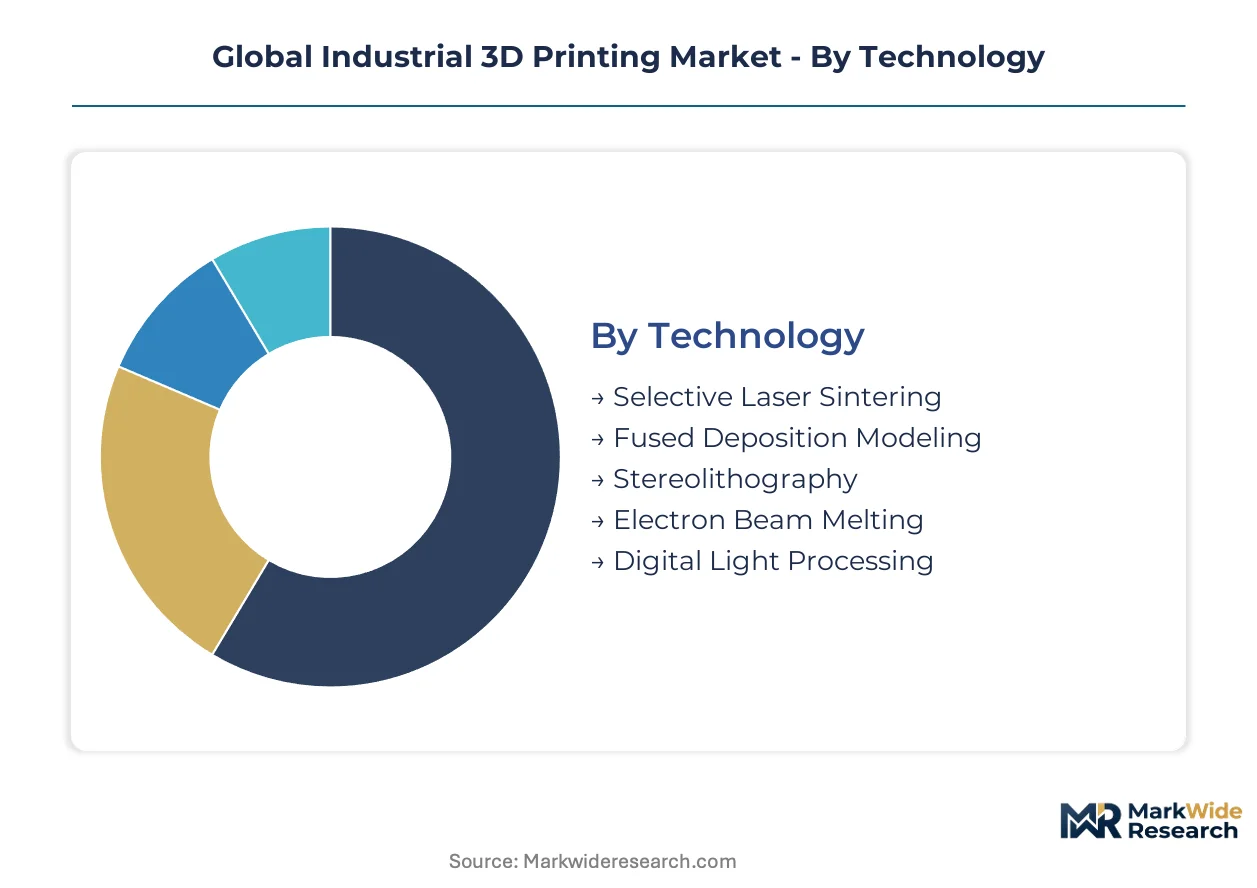
Industrial 3D printing segmentation reveals stark capital-intensity gradients across technologies and product categories. Powder-bed metal systems demand tenfold higher upfront investment than filament-based polymer units, concentrating procurement decisions among aerospace and medical device producers with multi-year amortization horizons.
Technology:
Capital requirements vary by an order of magnitude across deposition modalities, with laser-based metal systems commanding the steepest facility investments.
- Selective Laser Sintering:Powder-bed fusion of polymers and metals achieves layer resolutions below 50 microns through precise laser scanning patterns. German aerospace suppliers in Munich and Aachen are consolidating procurement around EOS and Trumpf systems for Ti-6Al-4V flight brackets, driven by EASA Part 21G production organization mandates that disqualify lower-precision alternatives.
- Electron Beam Melting:Vacuum-chamber processing of reactive alloys eliminates oxidation in titanium and nickel superalloy components. Ukrainian and Russian argon supply disruptions have destabilized operating economics for European electron-beam operators, forcing long-term hedging contracts with industrial gas suppliers.
- Fused Deposition Modeling:Thermoplastic extrusion dominates low-cost prototyping with minimal facility requirements.
- Stereolithography:Photopolymer vat polymerization delivers surface finishes unmatched by filament methods.
- Digital Light Processing:Projector-based curing accelerates dental and jewelry workflows with reduced pixel distortion.
Metal-directed energy modalities absorb the bulk of installed capacity; polymer extrusion systems are expanding most quickly among consumer electronics design studios.
Product Type:
Hardware margins stratify sharply by material compatibility, with multi-laser metal platforms generating service revenue multiples beyond polymer-only units.
- Metal 3D Printers:Multi-laser powder-bed systems processing titanium, aluminum, and nickel superalloys command seven-figure price tags and mandatory cleanroom infrastructure. GE Additive and EOS dominate aviation-qualified installations, with hot isostatic pressing integration now standard for fatigue-critical turbine components.
- Polymer 3D Printers:Fused deposition and vat photopolymerization units serve prototyping and short-run production at accessible capital thresholds. Stratasys anchors North American automotive jig production in Minnesota, though carbon-fiber PEEK injection molding is reclaiming applications below 150°C thermal loads.
- Ceramic 3D Printers:Oxide and non-oxide slurry systems address dental and aerospace thermal protection applications.
- Composite 3D Printers:Continuous fiber reinforcement enables structural automotive and drone components.
Metal hardware captures the dominant share of capital expenditure; polymer systems are gaining share fastest among tooling companies adopting distributed manufacturing networks.
End User Industry:
Regulatory burden intensity separates addressable customer tiers, with FDA and EASA certification requirements filtering procurement to qualified producers.
- Aerospace Manufacturers:Flight-critical component qualification demands exhaustive process-parameter databases and damage-tolerance frameworks specific to layer-built microstructures. Boeing and Airbus supply chains are consolidating titanium bracket procurement around powder-bed fusion, bypassing forged billet lead times stretching 18-24 months.
- Medical Device Producers:Implantable component manufacturing requires ISO 13485 quality systems and FDA 21 CFR Part 820 design history files. Swiss and German orthopedic clusters mandate lot-to-lot chemistry variance below 0.05% for CE-marked hip resurfacing implants, driving consignment powder inventory models with guaranteed certificate-of-analysis traceability.
- Consumer Electronics Firms:Rapid design iteration cycles favor low-cost polymer prototyping without regulatory overhead.
- Architecture Firms:Large-format concrete and polymer systems enable complex facade element production.
- Tooling Companies:Conformal-cooled mold inserts represent the bridge application between prototyping and production-scale metal printing.
Aerospace procurement concentrates the highest-value installed base; medical device production is climbing the fastest as implant qualification protocols mature.
Application:
Revenue recurrence patterns distinguish one-time design validation from recurring production workflows with powder and service contracts.
- End-Use Parts:Production-scale deposition of flight-critical brackets, orthopedic implants, and energy components generates recurring powder consumption and maintenance revenue. FAA airworthiness directives for additively manufactured structural elements are formalizing damage-tolerance frameworks that validate production economics.
- Rapid Prototyping:Design iteration support retains volume leadership across all technologies despite lower per-part value capture. Consumer electronics firms in Asia-Pacific and North America drive filament and resin consumption for pre-production validation cycles.
- Tooling Production:Conformal-cooled injection mold inserts reduce cycle times 20-40% versus conventional drilling.
- Custom Manufacturing:Low-volume, high-mix production serves maritime and energy spare part digital inventory models.
- Design Verification:Form and fit testing precedes commitment to hard tooling in traditional manufacturing workflows.
Prototyping retains the largest transaction volume; end-use part production is gaining share fastest as certification frameworks stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge refining capacity in Ukraine and Russia has destabilized noble gas supply chains for European electron-beam melting operators. Powder atomization infrastructure concentrates in Germany, China, and the United States, shaping regional competitive access to aerospace-qualified feedstock.
United States
Aviation OEMs in Wichita and Seattle are qualifying Ti-6Al-4V flight brackets through FAA airworthiness directives for additively manufactured structural elements. The FAA's evolving damage-tolerance frameworks for layer-built microstructures are formalizing production economics for domestic suppliers. Minnesota hosts concentrated polymer production for automotive jig applications, though carbon-fiber PEEK injection molding is reclaiming thermal loads below 150°C.
Germany
Precision engineering clusters around Munich and Aachen are accelerating process-parameter databases for nickel superalloy turbine blades through Fraunhofer institute partnerships. EASA Part 21G production organization protocols are forcing tier-two suppliers to certify or exit aviation supply chains entirely. REACH powder substance classifications and ECHA's 2023 Annex XVII updates mandate closed-loop powder handling with automated sieving for production license retention.
China
MIIT's additive manufacturing roadmap is standardizing process qualification protocols for domestic aviation and medical implant production. Dual carbon goals are accelerating powder recycling requirements in state-owned aerospace facilities. Yangtze River Delta industrial zones are consolidating captive powder atomization capacity to reduce import dependence for spherical titanium alloys.
India
The PLI scheme for specialty steel and titanium additive manufacturing offers output-linked incentives for firms establishing captive facilities in Tamil Nadu and Karnataka. CDSCO's evolving medical device regulations are creating pathways for orthopedic implant producers to access ASEAN healthcare procurement frameworks. Defense indigenization mandates are driving sovereign capacity for flight-critical component production.
Japan
METI's additive manufacturing roadmap is standardizing qualification protocols for medical cobalt-chrome implants. PMDA's alignment with international quality system regulations is opening export pathways for certified producers. Kanto and Kansai industrial corridors host concentrated R&D partnerships between system producers and university medical centers for gradient-density orthopedic applications.
Global Industrial 3D Printing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aerospace-qualified metal workflows and distributed service bureau networks. The vendor base stratifies across three tiers: multi-laser powder-bed system producers with seven-figure price tags, mid-scale polymer specialists serving automotive tooling, and regional service bureaus handling post-processing bottlenecks. Dominant competitive moves include backward integration into captive powder atomization and strategic partnerships with Fraunhofer-type research institutes for process-parameter database development.
Among German laser-sintering heritage producers, EOS GmbH exemplifies the medical implant certification archetype through European regulatory alignment. GE Additive occupies a position within aviation-qualified installations for nickel superalloy turbine components. Stratasys Ltd. anchors North American polymer production capacity while competing for tooling applications against injection molding substitution.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| 3D Systems, Inc. |
| EOS GmbH |
| HP Development Company |
| Materialise |
| GE Additive |
| Desktop Metal, Inc. |
| voxeljet AG |
| SLM Solutions |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Yangtze River Delta and family-owned German mid-caps around Munich anchor powder atomization capacity, creating divergent pricing discipline across aerospace-qualified and prototyping-grade tiers. This ownership fragmentation concentrates supply-side leverage among captive titanium sponge refiners while forcing independent printer OEMs into long-term offtake contracts to secure spherical alloy feedstock.
Pricing Analysis
Warranty and service bundling separates seven-figure multi-laser metal platforms from unbundled polymer extrusion units, with EOS and Trumpf contracts incorporating guaranteed powder lots and hot isostatic pressing integration. Three-tier pricing structure across aerospace-certified, industrial-grade, and prototyping tiers reflects EASA Part 21G certification investment and cleanroom infrastructure requirements. Cost compression in polymer tooling segments is intensifying because carbon-fiber PEEK injection molding reclaims applications below 150°C thermal loads. Automotive jig buyers exhibit highest price sensitivity; aviation OEMs prioritize qualification speed over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale aerospace demand, while distributor networks serve fragmented tooling and medical implant producers. Powder atomization concentrates in Germany, China, and the United States; argon gas refining rests on Ukrainian and Russian supply disrupted by regional conflict. Spherical titanium alloys, nickel superalloy feedstock, and photopolymer resins constitute critical input dependencies. Single-source vulnerability in noble gas supply destabilizes electron-beam melting economics. Distribution runs through equipment vendors with consignment powder inventory models transferring atomization risk to system suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over powder atomization and post-processing capacity determines margin capture. Players are pursuing captive spherical alloy production to escape feedstock cost volatility and qualification bottlenecks.
For Market Incumbents: Deepen integration into hot isostatic pressing and precision CNC finishing capacity to resolve aerospace-qualified surface finish queuing delays. Lock in long-term argon supply contracts with industrial gas suppliers to hedge against Ukrainian and Russian refining disruptions. Carbon-fiber PEEK injection molding substitution threatens polymer tooling margins; defend through conformal-cooled mold insert specialization above 150°C thermal thresholds.
For New Entrants and Emerging Players: Wire-fed titanium directed energy deposition for aviation engine casing repair offers a technology-first wedge into Singapore and Hamburg MRO networks. India's PLI scheme for Tamil Nadu and Karnataka captive facilities presents the most penetrable geography for defense-indigenization incentives. Pursue cloud-based part library partnerships with maritime and energy infrastructure operators as a service-first go-to-market angle.
For Investors and Strategic Acquirers: FDA 21 CFR Part 820 design history file clearance for gradient-density orthopedic implants is the leading indicator that medical additive manufacturing has crossed from prototype to production economics. Target mid-scale metal system producers with existing Fraunhofer institute partnerships and process-parameter databases for nickel superalloy applications. Watch for EASA damage-tolerance framework formalization as the signal that aviation production economics have stabilized.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Atomization Buildout | EOS and Trumpf service contracts with guaranteed certificate-of-analysis traceability transfer feedstock risk to equipment vendors. |
| Hybrid CNC-Deposition Cell Deployment | Singapore and Hamburg MRO providers compress corrosion-damaged component turnaround from weeks to days. |
| Closed-Loop Powder Handling Retrofit | ECHA's 2023 Annex XVII update forces German and Italian operators to install automated sieving for license retention. |
| Cloud-Based Part Library Partnership | Digital inventory convergence displaces physical spare part warehousing for maritime and energy infrastructure operators. |
| Fraunhofer Institute R&D Alliance | Munich and Aachen clusters accelerate process-parameter databases for EASA Part 21G certification timelines. |
Research Methodology
Multi-period observation of powder recycling rates, EASA certification timelines, and noble gas contract pricing anchored the trend analysis, supplemented by interviews with powder bed fusion system producers, aerospace procurement directors at Boeing and Airbus supply chains, medical device quality assurance leads, and Fraunhofer institute research coordinators. Secondary validation drew from FDA 21 CFR Part 820 filings, EASA Part 21G production organization registries, REACH Annex XVII substance classifications, and MIIT additive manufacturing roadmap disclosures. Bottom-up installed base enumeration triangulated against top-down capital expenditure estimates from aviation and medical device producers.
Input-output matrices mapped laser power density, layer thickness, and build volume to throughput economics across selective laser sintering, electron beam melting, and directed energy deposition modalities. Segmentation dimensions spanned technology type, material compatibility tier, end-use industry regulatory burden, and geographic production cluster adoption maturity. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from carbon-fiber PEEK injection molding and forged billet lead time compression. Forecast inputs included argon price volatility scenarios and EASA damage-tolerance framework implementation pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Ukrainian and Russian noble gas supply disruption or accelerated FDA orthopedic implant qualification protocols. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global 3D Pens Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
North America 3D Printing Market