
 Global 3D Printing in Medical Applications Market | 2026-2036
Global 3D Printing in Medical Applications Market Size, Share, and Industry Trends Forecast 2026-2036
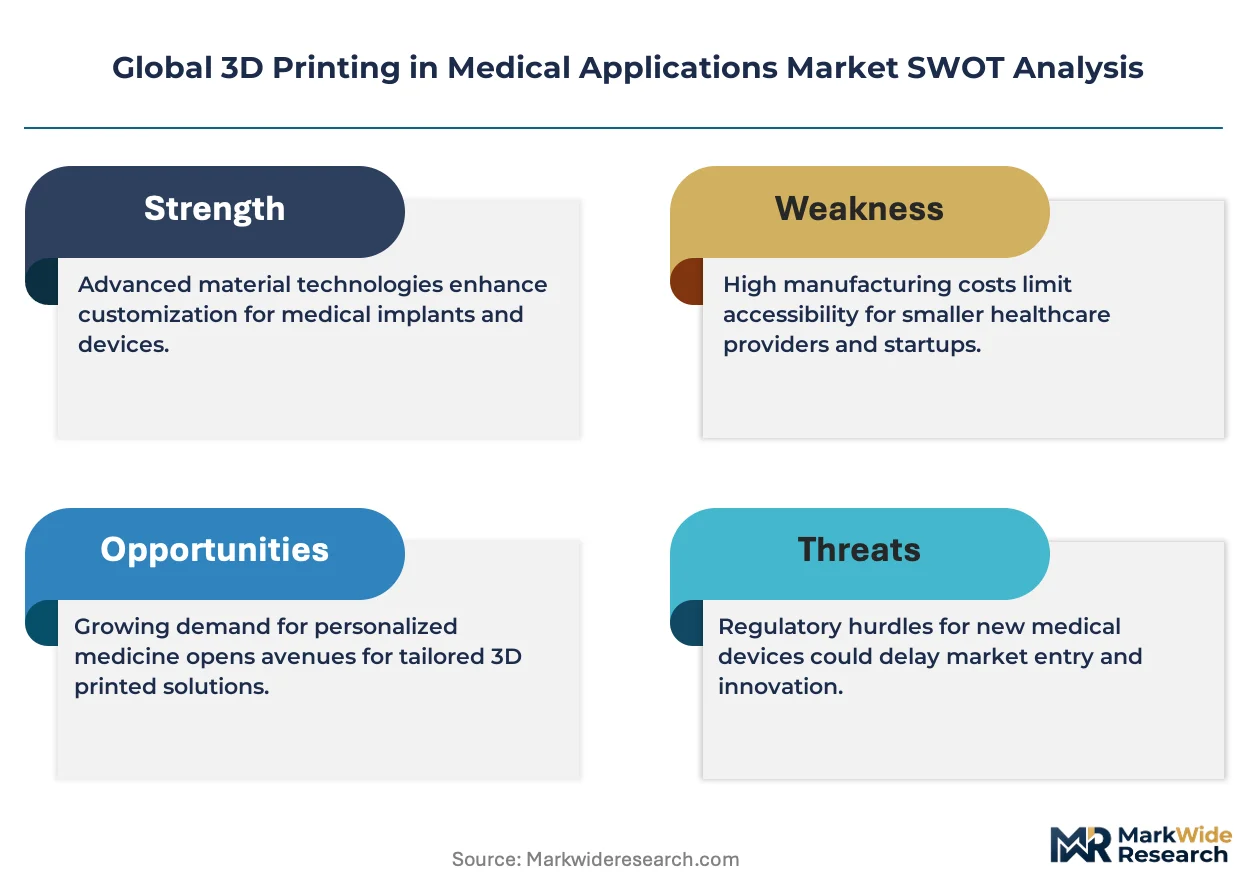
Global 3D Printing in Medical Applications Market Analysis
Multi-sourced material supply for titanium and biocompatible polymers is expanding as device manufacturers reduce reliance on single-feedstock vendors. Stratasys leverages polymer expertise across dental and orthopedic workflows. Materialise sustains software-to-print integration that anchors hospital adoption in Europe. EOS GmbH dominates metal powder-bed systems for cranial and spinal implant production.
3D printing in medical applications refers to additive manufacturing processes that build patient-specific devices, anatomical models, and tissue constructs from digital files using layer-by-layer deposition with resolutions reaching 16 microns in photopolymer systems. Its primary purpose is to eliminate tooling costs and compress lead times for customized therapeutic interventions. Bioprinting captures emerging margin pools as academic consortia advance vascularized tissue protocols, while surgical models occupy mature revenue channels with proven reimbursement pathways in hospital systems. Metals and ceramics lead implant-grade applications where fatigue resistance and osseointegration properties command premium positioning.
FDA enforces quality system regulations under 21 CFR Part 820 for 3D-printed device manufacturers, while EMA's Medical Device Regulation requires notified body oversight for custom-made implants entering European clinics. ISO 13485 certification shapes supplier qualification and OEM partnership access across both jurisdictions. Stakeholders must monitor evolving software validation standards as regulatory scope extends from hardware to design algorithms.
Market Dynamics
Patient-specific surgical planning is compressing traditional device development cycles as hospitals demand anatomical models within 48-hour windows, forcing manufacturers to reconfigure quality systems around digital workflows rather than physical tooling.
Growth Catalysts
- FDA 510(k) De Novo Pathways:Streamlined clearance for patient-matched implants accelerates commercialization timelines for spinal and cranial reconstructive devices.
- Titanium Powder Supply Diversification:Multi-source feedstock strategies reduce single-vendor dependency for orthopedic OEMs producing fatigue-critical load-bearing implants.
- Photopolymer Resolution Advances:16-micron layer precision in vat-polymerization systems enables vascular channel geometries previously requiring micro-machining.
Market Restraints
- Biocompatible Polymer Cost Volatility:Medical-grade PEEK and photopolymer resin prices fluctuate with semiconductor-grade chemical feedstock availability.
- Metal Powder Supply Concentration:Plasma-atomized titanium powder production clusters in Germany and China create geographic chokepoints for implant manufacturers.
- Osseointegration Performance Gaps:Porous lattice structures in cobalt-chrome alloys demonstrate inferior bone ingrowth versus wrought titanium in load-bearing applications.
Strategic Opportunities
- Brazil ANVISA Regulatory Harmonization:Emerging alignment with FDA quality system requirements opens Latin American surgical model markets to US and European exporters.
- Bioprinting Vascularized Tissue:Academic consortia advancing perfusable organoid constructs target transplantable tissue applications beyond static scaffold implants.
- Software-as-Medical-Device Convergence:AI-driven segmentation algorithms for anatomical modeling trigger new revenue streams alongside hardware sales.
Industry Challenges
- Computational Design Talent Scarcity:Lattice topology optimization and patient-specific finite element analysis require skill sets concentrated in aerospace and automotive sectors.
- ISO 13485 Certification Timelines:12-to-18-month notified body audit cycles delay market entry for novel material platforms.
- Post-Processing Bottlenecks:Support removal and surface finishing for metal implants constrain effective machine utilization rates below 40 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printing in Medical Applications Market |
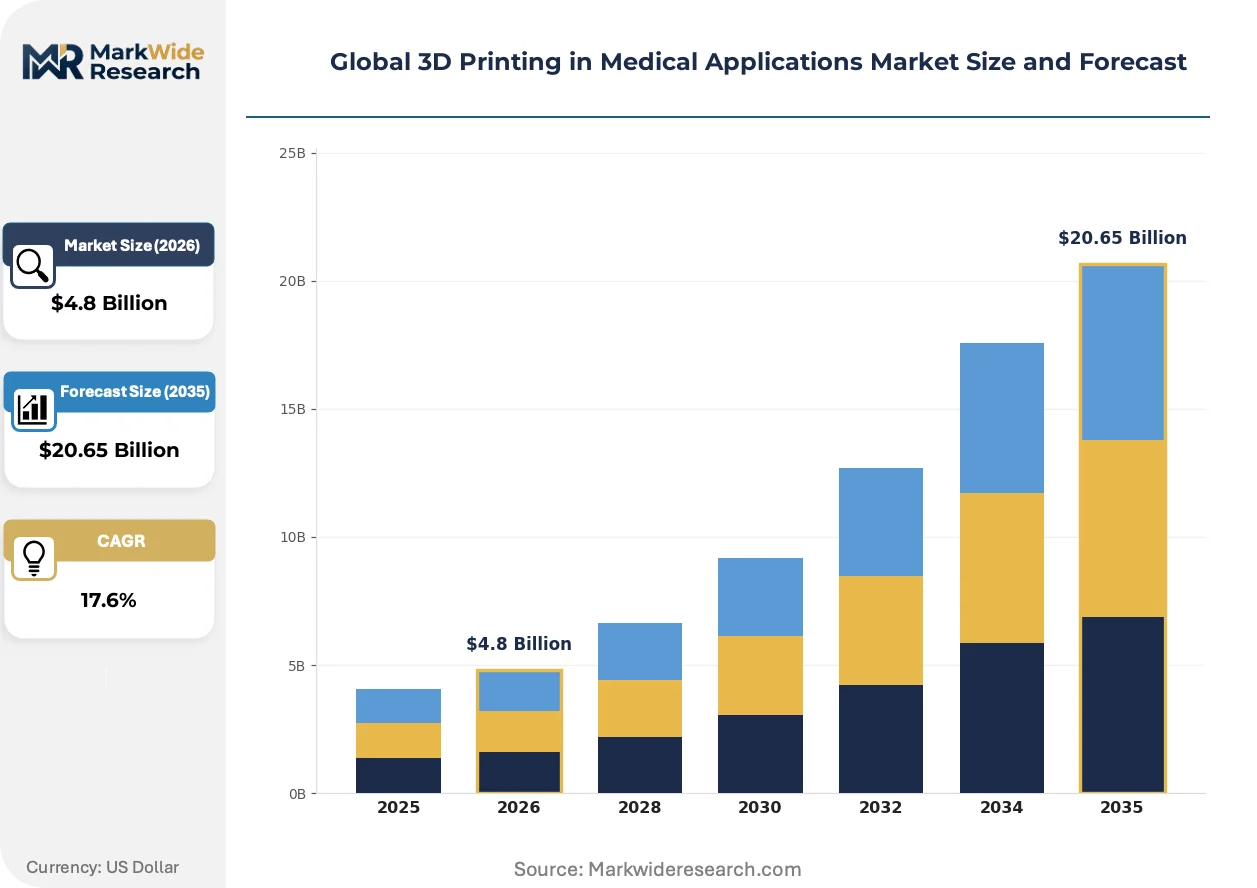
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprinting, Surgical Models, Prosthetics, Implants Material: Polymers, Ceramics, Metals, Hydrogels Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Hospitals, Research Institutions, Healthcare Providers, Contract Manufacturers |
| Companies Covered | 3D Systems, Stratasys, Materialise, Formlabs, EnvisionTEC, Organovo Holdings, Renishaw, EOS GmbH, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printing in Medical Applications Market Emerging Trajectories
Digital thread integration from diagnostic imaging to sterilized implant is collapsing traditional manufacturing handoffs. Three developments dominate competitive positioning.
Multi-laser powder-bed fusion is overtaking single-laser systems in cranial plate production. German and Belgian orthopedic device manufacturers deploy quad-laser architectures to reduce build times for titanium mesh implants from fourteen hours to under four. This speed compression enables same-week surgical scheduling for trauma cases.
EMA's Medical Device Regulation (MDR) Annex XVI expansion now captures patient-specific cutting guides as Class IIa devices. European notified bodies impose clinical evidence requirements previously reserved for permanent implants. Manufacturers respond by consolidating design history files across software, hardware, and sterilization validation.
Hospital procurement departments now bundle anatomical modeling services with surgical planning software subscriptions. US academic medical centers negotiate enterprise licenses covering radiology segmentation, 3D printing, and surgeon training. This unbundling displaces per-model transaction pricing in favor of annual capacity contracts.
Global 3D Printing in Medical Applications Market Segmentation
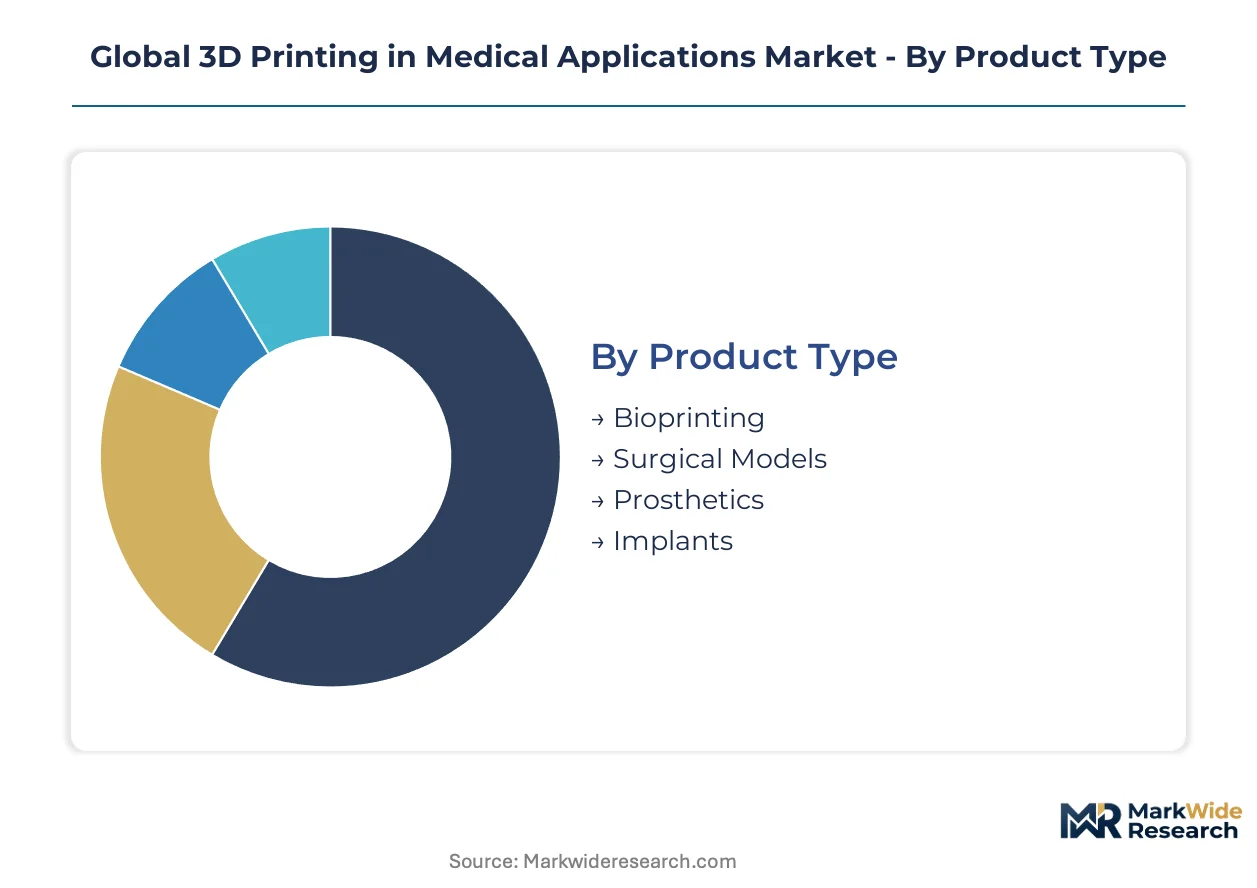
Segmentation in medical 3D printing reveals distinct capital requirements, regulatory pathways, and margin structures across product categories. Manufacturers configure equipment portfolios and quality systems around specific segment demands rather than pursuing horizontal coverage.
Product Type:
Implants and bioprinting platforms demand the heaviest upfront capital deployment, with cleanroom infrastructure and biological safety cabinets adding 40-60 percent to base equipment costs.
- Implants:Permanent load-bearing devices in titanium and cobalt-chrome alloys require validated powder-bed fusion systems with argon atmosphere control. German orthopedic OEMs concentrate cranial and spinal implant production in certified facilities near EOS GmbH headquarters to minimize supply chain risk for fatigue-critical components.
- Bioprinting:Extrusion-based and laser-assisted systems deposit living cells within temperature-controlled hydrogel matrices. Academic medical centers in the United States and Belgium anchor demand as consortia advance vascularized tissue protocols toward transplantable organoid applications.
- Surgical Models:Anatomical replicas from CT/MRI segmentation support preoperative planning with 48-hour turnaround requirements. Hospital procurement departments now bundle these services with enterprise software subscriptions.
- Prosthetics:Socket and limb components utilize lower-cost filament deposition for patient-matched geometries. Emerging market clinics drive volume through distributed manufacturing networks.
Most installed capacity flows through surgical models. Expansion is steepest in bioprinting.
Material:
Material selection determines post-processing complexity, sterilization compatibility, and reimbursement coding for finished devices.
- Metals:Plasma-atomized titanium powder dominates cranial plates and spinal cages due to fatigue resistance and osseointegration properties. Production clusters in Germany and China create geographic chokepoints for orthopedic OEMs seeking multi-source strategies.
- Polymers:Medical-grade PEEK and photopolymer resins enable radiolucent spinal implants and dental surgical guides. Stratasys leverages filament expertise across dental and orthopedic workflows with hospital-validated material libraries.
- Ceramics:Alumina and zirconia formulations serve maxillofacial and dental applications where abrasion resistance exceeds polymer limits. Japanese manufacturers concentrate hydroxyapatite composite development.
- Hydrogels:Cell-laden bioinks require sterile formulation and precise rheological control for vascular channel preservation. Academic suppliers dominate with customized compositions for specific tissue types.
Metal powders absorb the largest share of material procurement budgets. Hydrogels are climbing the fastest as bioprinting protocols mature.
Technology:
Technology platforms stratify by resolution capability, build speed, and qualified material range for regulatory submissions.
- Selective Laser Sintering:Powder-bed fusion with CO2 or fiber lasers produces fully dense metal implants with isotropic mechanical properties. Quad-laser architectures reduce titanium mesh build times from fourteen hours to under four, enabling same-week trauma scheduling.
- Stereolithography:Vat-polymerization systems achieve 16-micron layer precision for vascular channel geometries previously requiring micro-machining. Dental surgical guides and hearing aid shells dominate commercial utilization.
- Fused Deposition Modeling:Thermoplastic extrusion offers lowest equipment cost for surgical models and prosthetic prototypes. Limited to non-sterilized applications due to layer adhesion porosity.
- Digital Light Processing:Projector-based photopolymer curing accelerates dental workflow throughput with continuous printing modes. Materialise integrates DLP hardware with segmentation software for European hospital deployments.
Installed base concentrates in selective laser sintering. Digital light processing is expanding most quickly in dental applications.
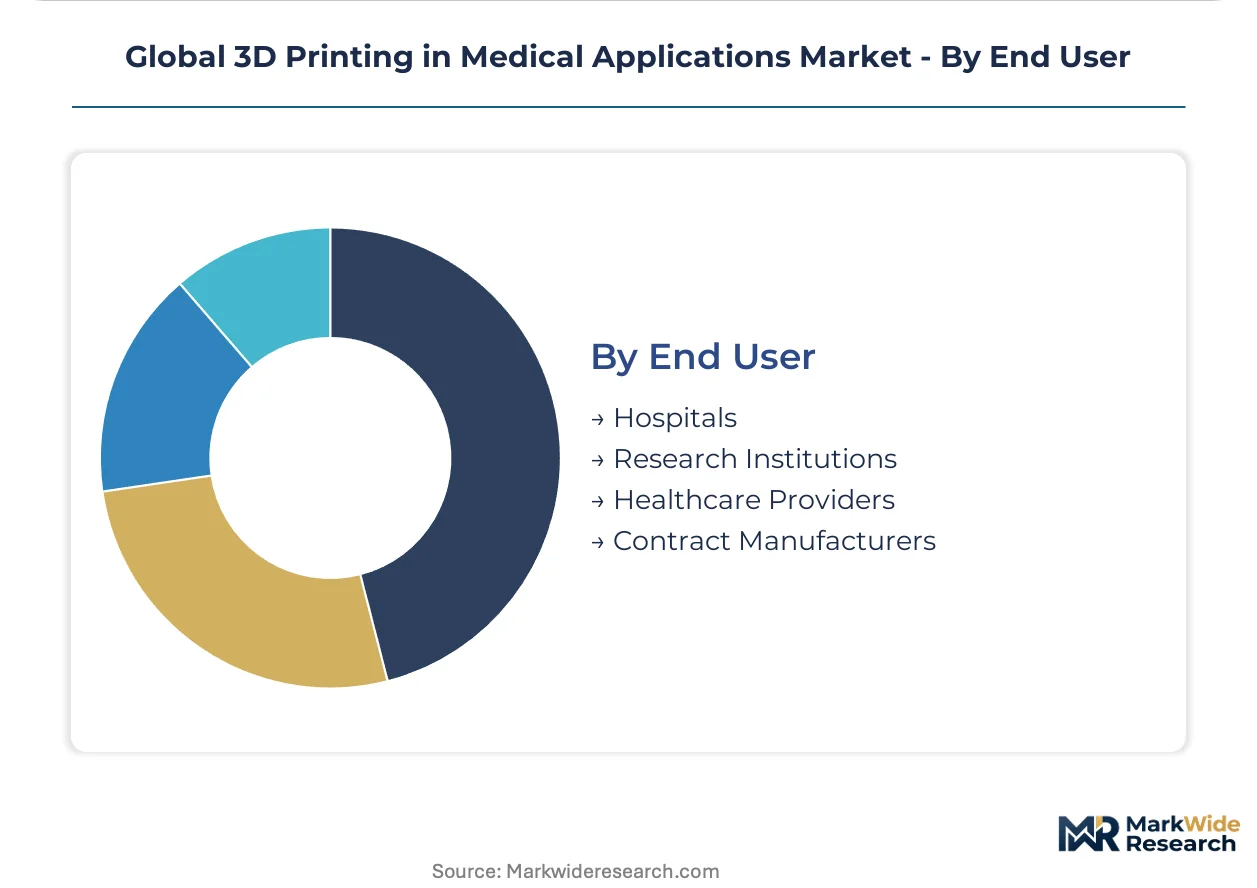
End User:
End-user categories differ in procurement authority, technical staffing, and regulatory filing responsibility.
- Hospitals:Academic medical centers in the United States and Germany deploy in-house printing for surgical models and patient-matched cutting guides. EMA MDR Annex XVI now classifies these guides as Class IIa devices, triggering clinical evidence requirements.
- Contract Manufacturers:ISO 13485-certified facilities in Belgium and Switzerland manage design history files and sterilization validation for implant OEMs. These providers consolidate multi-laser capacity to serve fragmented orthopedic device portfolios.
- Research Institutions:University consortia advance bioprinting protocols with non-commercial funding. Vascularized tissue applications remain preclinical with transplantable organoid timelines extending beyond current forecast windows.
- Healthcare Providers:Private clinic networks purchase anatomical modeling services through annual capacity contracts rather than per-case transactions.
Contract manufacturers absorb the majority of metal implant production volume. Hospital in-house capacity is gaining share fastest in surgical modeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters anchor global supply chains for medical-grade metal powder systems. FDA and EMA regulatory convergence is reshaping commercialization timelines across North American and European markets. Asian manufacturing centers are scaling polymer-based surgical modeling capacity for regional hospital networks.
United States
Academic medical centers in Boston and the San Francisco Bay Area deploy in-house printing for patient-matched cutting guides and anatomical models. FDA 510(k) pathways for patient-specific implants have compressed clearance timelines for spinal and cranial reconstructive devices. The Mayo Clinic in Rochester, Minnesota, operates one of the largest hospital-based 3D printing facilities for preoperative surgical planning.
Germany
EOS GmbH headquarters near Munich anchors a dense cluster of orthopedic OEMs producing fatigue-critical titanium implants. EMA Medical Device Regulation Annex XVI now classifies patient-specific surgical guides as Class IIa devices, triggering clinical evidence requirements. The Bavarian manufacturing corridor concentrates plasma-atomized titanium powder production and multi-laser powder-bed fusion system deployment.
Belgium
Materialise in Leuven sustains software-to-print integration that anchors hospital adoption across European markets. EMA notified body oversight for custom-made implants requires ISO 13485 certification and sterilization validation for entry into European clinics. The Flanders region hosts contract manufacturers consolidating design history files for fragmented orthopedic device portfolios.
China
NMPA regulatory harmonization with FDA quality system requirements is accelerating market entry for domestic implant manufacturers. The Yangtze River Delta manufacturing belt is scaling production of photopolymer surgical guides and dental models for hospital procurement departments. Shanghai-based academic consortia advance bioprinting protocols with government-funded vascularized tissue research programs.
Brazil
ANVISA regulatory alignment with FDA quality system requirements is opening Latin American surgical model markets to US and European exporters. São Paulo hospital networks are negotiating enterprise licenses covering radiology segmentation, 3D printing, and surgeon training. The Southeast region concentrates demand for anatomical modeling services supporting complex cardiovascular and orthopedic procedures.
Global 3D Printing in Medical Applications Market Vendor Landscape
Global majors compete with regional champions across hardware platforms and software integration layers. The vendor base stratifies into three tiers: diversified industrial conglomerates with medical divisions, pure-play additive manufacturing specialists, and software-centric workflow integrators. Dominant competitive moves include technology licensing agreements between equipment OEMs and materials suppliers, plus capacity consolidation among ISO 13485-certified contract manufacturers serving fragmented orthopedic device portfolios.
Among Germany-based metal powder-bed specialists, EOS GmbH exemplifies the precision manufacturing archetype anchored in fatigue-critical implant production. Materialise represents the software-to-print integration tier that hospital procurement departments favor for enterprise licensing. Stratasys occupies a position spanning polymer expertise across dental and orthopedic workflows with validated material libraries. 3D Systems sits within the diversified technology tier with historical presence across photopolymer and metal systems.
| Leading Market Players |
|---|
| 3D Systems |
| Stratasys |
| Materialise |
| Formlabs |
| EnvisionTEC |
| Organovo Holdings |
| Renishaw |
| EOS GmbH |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Plasma-atomized titanium powder moves from German and Chinese production clusters through orthopedic OEMs into fatigue-critical implant pricing tiers, with hospital procurement departments absorbing cost pass-throughs for patient-matched devices while contract manufacturers negotiate annual capacity contracts for surgical models.
Pricing Analysis
Input-cost pass-through from medical-grade PEEK and photopolymer resin volatility shapes tiered pricing across implant and surgical model segments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared titanium implants from CE-marked cutting guides and non-sterilized surgical models. Cost compression in standard-tier photopolymer guides is intensifying because semiconductor-grade chemical feedstock constraints tighten resin supply. Academic medical centers show least price sensitivity for bioprinting platforms, while emerging market clinics drive volume through economy-tier prosthetic socket contracts.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for titanium powder-bed systems, with distribution running through ISO 13485-certified contract manufacturers in Belgium and Switzerland for fragmented orthopedic device portfolios. Raw material supply draws from plasma-atomized titanium production in Germany and China, medical-grade PEEK resin from specialized chemical suppliers, and biocompatible photopolymers from dental-focused formulation houses. Single-source vulnerability concentrates in German titanium powder atomization capacity, where EOS GmbH anchors regional production clusters. Hospital procurement departments increasingly source anatomical modeling services through enterprise software subscriptions rather than per-case transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global 3D Printing in Medical Applications Market functions as a stable compounder, with patient-specific surgical planning workflows embedding additive manufacturing into standard hospital infrastructure.
For Market Incumbents: Anchor quality system investments around FDA 510(k) and EMA MDR Annex XVI convergence, which tightens clinical evidence requirements for patient-matched cutting guides previously exempt from implant-grade scrutiny. Deepen backward integration into plasma-atomized titanium powder supply to offset German production cluster concentration risk. Prioritize multi-laser capacity consolidation to compress build times for trauma-scheduled cranial mesh implants. For New Entrants and Emerging Players: Begin with bioprinting vascularized tissue protocols, where academic consortia funding sustains preclinical development timelines beyond incumbent commercialization horizons. Target Latin American surgical model markets through ANVISA regulatory harmonization with FDA quality systems. Deploy software-as-medical-device segmentation algorithms to capture AI-driven anatomical modeling revenue alongside hardware sales. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification timelines stretch 12-to-18 months and notified body audit backlogs delay novel material platform entry. Long-term viability favors contract manufacturers consolidating multi-laser capacity to serve fragmented orthopedic OEM portfolios. Watch bioprinting vascularized tissue protocols as the inflection signal, where transplantable organoid applications would expand addressable market beyond static scaffold implants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) De Novo Pathway | Streamlined clearance accelerates spinal and cranial reconstructive device commercialization timelines. |
| EMA MDR Annex XVI Compliance | CE marking for patient-specific cutting guides triggers clinical evidence requirements previously reserved for implants. |
| Hospital System Partnership | Enterprise software subscriptions bundle radiology segmentation with anatomical modeling capacity. |
| Software Companion Development | AI-driven segmentation algorithms create recurring revenue streams alongside hardware sales. |
| Reimbursement Strategy | Proven pathways for surgical models anchor mature revenue channels in academic medical centers. |
Methodological Framework
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs leads with secondary validation from FDA filings, EMA submissions, hospital procurement databases, and CMS Medicare data. Bottom-up equipment installation counts and top-down healthcare expenditure allocations triangulate market sizing across segments.
Granularity-level modeling disaggregates revenue across product type, material, technology, and end user dimensions, with additional segmentation by regional regulatory cluster and certification tier. CAGRs derive from fitted growth curves applied to base-year estimates across the projection horizon, incorporating surgical model reimbursement velocity, bioprinting protocol maturation timelines, and multi-laser powder-bed fusion adoption rates as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including preclinical bioprinting vascularized tissue applications without commercial timelines, commodity titanium powder price shocks from energy market volatility, and unforeseen regulatory scope expansion into software validation standards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Global 4D Printing in Healthcare Market