
 3D Printing in Automotive Additive Market | 2026-2036
3D Printing in Automotive Additive Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Automotive Additive Market Insights
European powder-bed equipment capacity is repositioning toward automotive-qualified metal alloys. EOS GmbH leverages its Munich engineering base to sustain qualification pipelines for aluminum and titanium automotive grades. GE Additive anchors its position through in-house production of aerospace-derived superalloys now migrating to high-performance engine brackets. Stratasys competes in the polymer tooling layer, where its FDM platforms occupy the jigs-and-fixtures workflows of North American assembly plants.
3D Printing in Automotive Additive refers to layer-by-layer fabrication of vehicle components from digital models, typically achieving tolerances of 50-200 microns in metal laser powder-bed systems and producing topology-optimized geometries unachievable through subtractive machining. Its primary purpose is to reduce part count, consolidate assemblies, and enable mass-customization at production volumes below traditional tooling break-even thresholds. Metal powder bed fusion, particularly DMLS, leads in structural load-bearing applications where fatigue resistance matches wrought material properties. Plastic extrusion via FDM dominates prototyping and interior trim tooling due to lower capital barriers and faster iteration cycles. Composite deposition remains nascent but differentiates in motorsport and luxury electric vehicle subframes where stiffness-to-weight ratios command premium positioning.
FDA material master files for titanium and cobalt-chrome powders indirectly shape automotive supply chains, as dual-use powder producers prioritize medical-qualified batches with traceability protocols OEMs increasingly demand. NHTSA's crashworthiness validation requirements for non-traditional manufacturing processes are forcing additive suppliers to build statistically significant test databases before production approval. EPA lifecycle emissions rules for vehicle lightweighting create regulatory pull for printed aluminum topology-optimized components that reduce fleet-average fuel consumption. Stakeholders must monitor how ISO/ASTM additive manufacturing standards evolve from qualification guidance to enforceable procurement mandates across tiered supply bases.
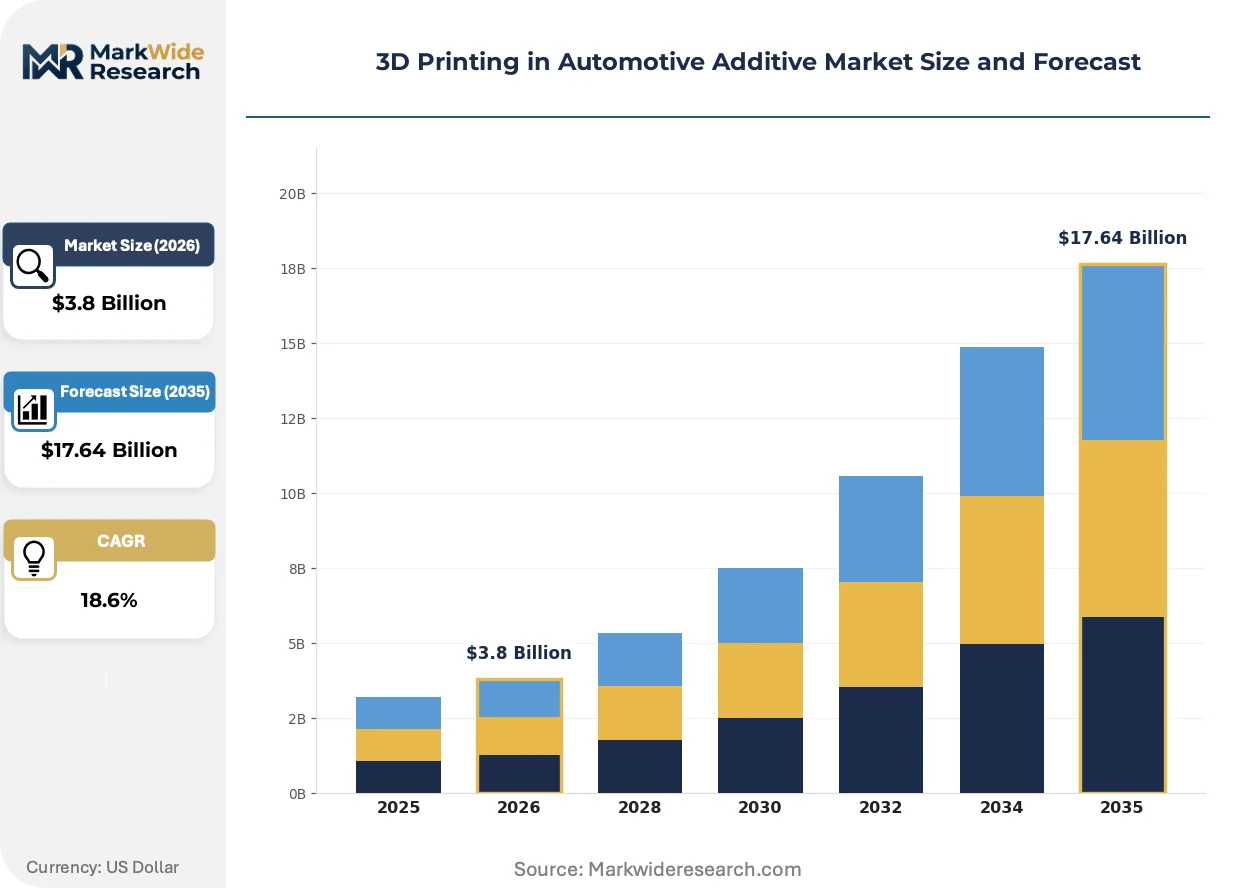
Market Dynamics
Automotive additive manufacturing is bifurcating between high-volume aluminum topology optimization for electric vehicle platforms and low-volume titanium consolidation for motorsport powertrains, with qualification protocols becoming the binding constraint on supplier expansion.
Growth Catalysts
- EPA Fleet Emissions Mandates:Stringent fuel economy benchmarks compel OEMs to adopt printed aluminum structural nodes that reduce vehicle mass without compromising NHTSA crashworthiness ratings.
- Baden-Württemberg Supplier Density:Germany's automotive cluster integrates metal powder-bed systems into just-in-sequence production lines, demonstrating scalable integration of additive workflows.
- Multi-Material Topology Software:Generative design platforms now automate lattice generation for brake calipers and suspension uprights, collapsing iteration cycles from weeks to days.
Market Restraints
- Gas Atomized Powder Concentration:Automotive-qualified aluminum and titanium powder production concentrates among a handful of European and North American suppliers, creating input vulnerability.
- NHTSA Additive Qualification Timelines:Crashworthiness validation for non-wrought manufacturing processes demands statistically significant test databases that extend approval cycles by 18-24 months.
- CNC Machining Cost Compression:Five-axis milling centers achieve competitive tolerances for sub-500 unit production runs, limiting additive's break-even threshold to complex geometries only.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for advanced automotive component manufacturing create subsidy pathways for metal additive capacity installation in Tamil Nadu and Gujarat.
- Battery Pack Structural Integration:Printed aluminum cooling channels and crash structures consolidate thermal management with chassis functions in skateboard EV platforms.
- ISO/ASTM Standards Maturation:Evolving qualification frameworks from guidance documents to enforceable procurement mandates will unlock tier-two supplier certification.
Industry Challenges
- Metallurgical Technician Scarcity:Powder-bed machine operation and build plate analysis require specialized skills that outpace vocational training program output.
- Post-Processing Bottlenecks:Hot isostatic pressing and precision machining of printed metal components create capacity constraints that offset additive's speed advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Automotive Additive Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping, Tooling, Production Parts, Custom Components Material: Plastic, Metal, Composite, Resin Process Technology: FDM, SLA, SLS, DMLS Application: OEMs, Aftermarket, Motocycle Parts, Spare Parts |
| Companies Covered | Stratasys, 3D Systems, EOS GmbH, HP Inc., Desktop Metal, GE Additive, Materialise, Renishaw, SLM Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Automotive Additive Market Trends and Innovations
Process automation and regulatory harmonization are compressing the gap between prototype validation and production qualification, with software-defined manufacturing workflows displacing operator-dependent quality variation.
Multi-laser powder-bed fusion is consolidating position as the dominant metal additive platform for structural automotive components. Tier-one OEMs in Stuttgart and Detroit are qualifying 400mm build-chamber systems for aluminum suspension brackets. This consolidation is compressing equipment vendor margins while accelerating build-speed benchmarks.
REACH substance restrictions on nickel powder classifications are forcing reformulation of Inconel feedstocks used in high-temperature exhaust components. European powder producers are migrating toward cobalt-free superalloy compositions. Motorsport exhaust manufacturers in the UK and Italy face immediate reformulation deadlines.
Direct digital manufacturing contracts are displacing traditional tooling-based procurement for service parts and low-volume specialty vehicles. BMW's Munich facility now prints final-order interior trim components on-demand. This pattern is most visible in German luxury EV programs where configuration variety exceeds 10,000 permutations.
3D Printing in Automotive Additive Market Segmentation
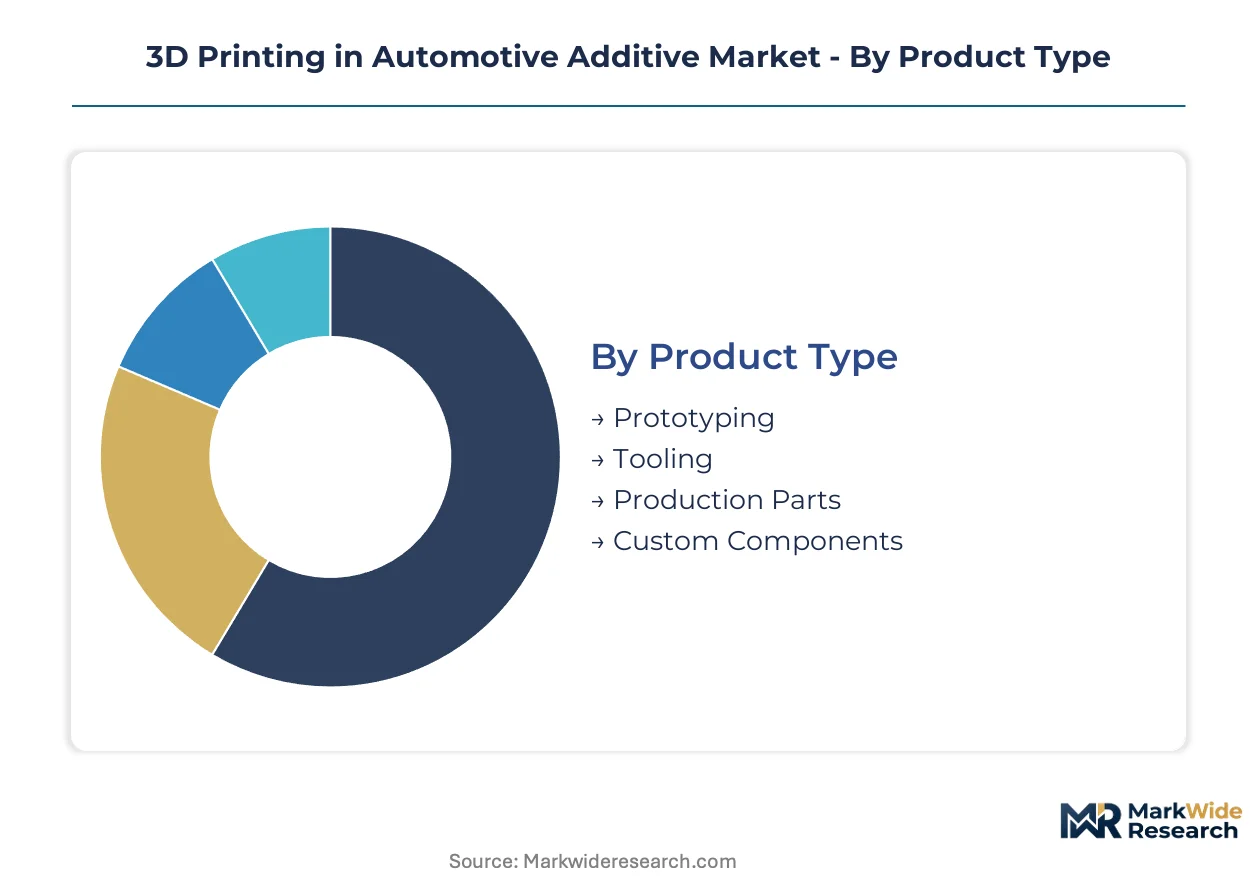
Automotive additive manufacturing segments diverge sharply by buyer sophistication and qualification burden. OEM procurement teams demand aerospace-grade traceability for production parts, while aftermarket distributors prioritize speed over certification depth.
Product Type:
Buyers in this category separate by production volume thresholds and regulatory exposure. Tier-one OEMs require full PPAP documentation for end-use components, whereas racing teams and custom shops accept first-article inspection only.
- Production Parts:Structural load-bearing components manufactured to NHTSA crashworthiness and EPA emissions standards. Demand concentrates in Stuttgart and Detroit for aluminum topology-optimized EV battery brackets where mass reduction directly impacts fleet compliance metrics.
- Tooling:Jigs, fixtures, and assembly aids printed via FDM for North American plants. Ford's Dearborn facility deploys printed drill guides that cut changeover times by 60% on F-150 mixed-model lines.
- Prototyping:Design validation models for interior fit-checks and wind tunnel testing. Iteration cycles compress from weeks to days.
- Custom Components:Low-volume specialty parts for luxury EV configurators. BMW Munich prints final-order trim on-demand.
Tooling leads volumes today; production parts are gaining share fastest.
Material:
Material selection tracks directly with structural requirements and post-processing capacity. Buyers with in-house HIP and CNC finishing favor metals; those without invest in reinforced polymers.
- Metal:Aluminum and titanium powders processed through DMLS for suspension uprights and engine brackets. Baden-Württemberg suppliers qualify Scalmalloy and Ti-6Al-4V grades for just-in-sequence delivery to Porsche and Mercedes-Benz assembly plants.
- Plastic:ABS, nylon, and reinforced thermoplastics via FDM for non-structural applications. Stratasys Fortus systems dominate North American prototyping floors due to lower capital barriers.
- Composite:Carbon fiber-reinforced deposition for motorsport subframes. Stiffness-to-weight ratios command premium positioning in Formula 1 and luxury EV programs.
- Resin:Photopolymer systems for high-detail interior mockups and lighting lens prototypes. Limited to non-structural uses due to thermal and mechanical constraints.
Plastic dominates unit volumes; metal commands revenue concentration.
Process Technology:
Technology adoption correlates with tolerance requirements and build chamber investment capacity. Sub-50-micron precision demands laser systems; speed-first applications favor extrusion.
- DMLS:Direct metal laser sintering produces fully dense aluminum and titanium components matching wrought fatigue properties. EOS M400 systems in Munich and Auburn Hills qualify automotive-grade powder lots with full traceability chains.
- FDM:Fused deposition modeling of thermoplastics for rapid tooling and prototyping. Desktop systems start below $10,000, democratizing access for tier-three suppliers.
- SLS:Selective laser sintering of nylon powders for functional prototypes and ducting components. No support structures enable complex geometries.
- SLA:Stereolithography delivers finest surface finishes for aesthetic prototypes and investment casting patterns. Limited by resin durability for functional testing.
FDM holds installed base leadership; DMLS expands most quickly.
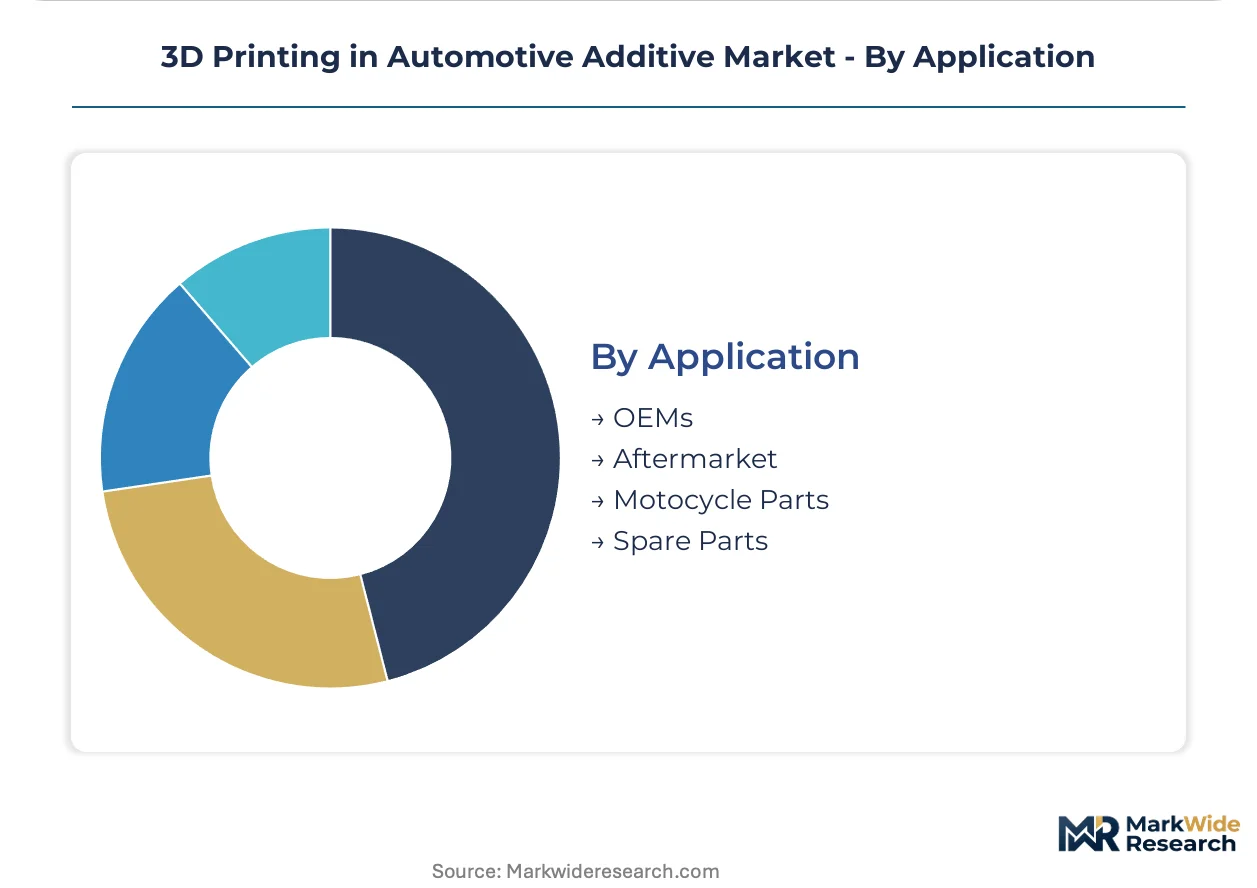
Application:
End-use buyers differ by procurement rigor and volume predictability. OEMs impose multi-year qualification protocols; aftermarket channels prioritize inventory velocity.
- OEMs:Tier-one manufacturers integrating additive into serial production. Volkswagen's Wolfsburg facility prints aluminum HVAC ducts and structural nodes for ID. series EVs under full PPAP controls.
- Aftermarket:Performance upgrade components and restoration parts sold through distributor networks. Lower documentation burdens accelerate supplier onboarding.
- Spare Parts:End-of-life inventory replacement for discontinued vehicle lines. Digital warehousing eliminates physical stockholding costs.
- Motocycle Parts:Custom exhaust brackets and bodywork for racing and premium street applications. Italian and UK manufacturers lead adoption.
OEMs anchor revenue today; spare parts show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where automotive additive capacity installs, as manufacturers migrate toward jurisdictions with streamlined qualification protocols and aligned emissions enforcement.
United States
EPA fleet emissions mandates and NHTSA crashworthiness protocols drive OEM adoption of printed aluminum structural nodes. Detroit's automotive cluster anchors metal powder-bed qualification pipelines for EV battery brackets. Auburn Hills suppliers integrate multi-laser systems into just-in-sequence workflows for Ford and General Motors assembly plants.
Germany
REACH substance restrictions on nickel powder classifications force reformulation of exhaust component feedstocks. Baden-Württemberg's supplier density demonstrates scalable additive integration, with Porsche and Mercedes-Benz assembly plants receiving DMLS-produced suspension uprights. Munich-based EOS GmbH sustains qualification pipelines for automotive-grade aluminum and titanium alloys.
China
MIIT dual carbon goals and GB standards for vehicle lightweighting create regulatory pull for topology-optimized printed components. Yangtze River Delta automotive clusters in Shanghai and Jiangsu province install metal additive capacity for domestic EV platforms. Local powder producers are qualifying Scalmalloy grades for structural battery pack applications.
India
PLI scheme production-linked incentives for advanced automotive component manufacturing subsidize metal additive capacity installation. Tamil Nadu and Gujarat automotive corridors attract powder-bed system deployments for domestic OEM supply chains. BIS standards evolution is compressing qualification timelines for aluminum automotive grades.
United Kingdom
Motorsport Valley concentration around Oxfordshire and Northamptonshire sustains titanium consolidation demand for Formula 1 powertrains. UK exhaust manufacturers face immediate REACH-driven reformulation deadlines for cobalt-free superalloy compositions. Silverstone Technology Cluster anchors composite deposition development for motorsport subframe applications.
3D Printing in Automotive Additive Market Competitive Landscape
German producers anchor the equipment tier; US specialists hold the polymer tooling layer. The market structures around three strategic archetypes: powder-bed system vendors with automotive qualification pipelines, polymer platform suppliers serving prototyping floors, and materials specialists controlling gas-atomized feedstock supply. Consolidation pressures concentrate among equipment vendors as multi-laser platforms commoditize build-speed performance. Strategic moves center on backward integration into powder production and geographic expansion toward subsidy-aligned jurisdictions.
Within the metal system tier, EOS GmbH and SLM Solutions exemplify European engineering-centric positioning. Stratasys occupies the polymer tooling archetype, with its FDM platforms serving North American assembly plant workflows. GE Additive represents the aerospace-derived superalloy specialist migrating toward high-performance automotive applications. These three anchors illustrate how competitive positioning fragments by material-metallurgy specialization rather than converging on unified platform strategies.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| EOS GmbH |
| HP Inc. |
| Desktop Metal |
| GE Additive |
| Materialise |
| Renishaw |
| SLM Solutions |
| Others |
Pricing and Supply Chain Analysis
Gas-atomized aluminum and titanium powder costs cascade through automotive additive supply chains from European producers to tier-one OEM procurement desks, with NHTSA qualification burdens compressing distributor margins while EPA emissions mandates sustain premium pricing for topology-optimized structural nodes.
Pricing Analysis
Distributor markups on automotive-qualified metal powders absorb NHTSA traceability documentation costs before reaching OEM direct-procurement contracts. Three-tier pricing structure across aerospace-grade, automotive-qualified, and industrial-grade certification levels separates Porsche-level PPAP requirements from aftermarket restoration channels. Cost compression in polymer tooling tiers intensifies as Stratasys FDM platforms commoditize entry-level prototyping. Racing teams and custom shops exhibit highest price sensitivity; tier-one EV manufacturers prioritize qualification depth over unit economics.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, but gas-atomized powder feedstocks for automotive additive manufacturing draw from Germany, the United States, and China. Scalmalloy and Ti-6Al-4V grades, hot isostatic pressing equipment, and multi-laser powder-bed systems constitute critical input dependencies. Single-source vulnerability concentrates in aerospace-derived superalloy formulations migrating to high-performance engine brackets. Distribution runs through Baden-Württemberg supplier networks for just-in-sequence delivery to Stuttgart assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive additive manufacturing rewards geographic arbitrage between India's PLI-subsidized capacity installation and Germany's REACH-constrained powder reformulation costs, with regulatory differential creating margin capture opportunities for repositioned production footprints.
For Market Incumbents: Anticipate REACH-driven cobalt-free superalloy migration by accelerating backward integration into powder production. EOS GmbH and SLM Solutions should defend qualification pipeline depth against emerging Chinese equipment vendors through BIS certification investment in Tamil Nadu. Multi-laser platform commoditization threatens equipment margins; captive supply of automotive-grade aluminum grades preserves pricing power. For New Entrants and Emerging Players: Tier-three aftermarket distributors represent the most penetrable channel partner type for FDM-based tooling entry. Target North American assembly plant jig-and-fixture workflows where Stratasys dominates but changeover-time sensitivity creates white-space. A direct-to-dealership spare parts digital warehousing model bypasses OEM qualification timelines entirely. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-laser powder-bed platforms commoditize build-speed performance and equipment vendor margins compress. Five-to-ten-year viability favors materials specialists controlling gas-atomized feedstock supply over pure-play system vendors. Watch ISO/ASTM standards evolution from guidance documents to enforceable procurement mandates as the inflection signal for tier-two supplier certification unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Captive supply of Scalmalloy grades insulates margins from European gas-atomization concentration. |
| Geographic Manufacturing Footprint Expansion | PLI-aligned capacity installation in Tamil Nadu captures subsidy pathways for domestic OEM supply chains. |
| Software-Defined Manufacturing Investment | Generative design platforms automate lattice generation for brake calipers at BMW Munich. |
| Long-term Supply Agreement | Just-in-sequence contracts with Porsche and Mercedes-Benz anchor Baden-Württemberg supplier revenue. |
| Green Manufacturing Transition | Cobalt-free superalloy compositions address REACH reformulation deadlines for UK exhaust manufacturers. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement managers, OEM platform engineers, powder metallurgy technicians, and aftermarket distributors grounded qualitative findings in operational reality. Secondary validation drew from EPA fleet emissions filings, NHTSA crashworthiness databases, IHS Markit vehicle production data, and ISO/ASTM additive manufacturing standards documentation. Bottom-up build-up of installed powder-bed capacity triangulated against top-down OEM procurement spend estimates.
Segment-level outputs across the projection horizon reflect modeled interactions between propulsion architecture, content per vehicle, and regional production cluster dynamics. CAGRs derived from curve-fitting historical qualification timeline compression against EPA emissions mandate phase-in schedules. Forecast inputs incorporated NHTSA additive process validation database build rates and REACH substance restriction implementation calendars.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ISO/ASTM standards maturation pace and India PLI scheme renewal decisions. Assumptions underlying projections reflect documented regulatory calendars and disclosed OEM platform launch timelines. A small set of triggers—MIIT dual carbon goal acceleration, BIS standards adoption speed, and multi-laser equipment vendor consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Selective Laser Sintering Market
3D Printing Technology
Food 3D Printing Market