
 North America 3D Printing Market | 2026-2036
North America 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3D Printing Market Insights
ASTM F3301 qualification for laser powder bed fusion is rotating the competitive landscape toward certified metal printing capabilities. Stratasys leverages its polymer expertise and extensive service bureau network across the United States and Mexico. Desktop Metal anchors its position through in-house production of binder jet systems targeting automotive tooling workflows. EOS competes primarily in industrial metal segments with precision equipment that dominates aerospace qualification programs.
3D printing encompasses additive manufacturing processes that build objects layer-by-layer from digital models using energy sources such as lasers, electron beams, or thermal extrusion to fuse materials with typical layer resolutions between 25 and 100 microns. FDM systems occupy the broadest installed base across education and prototyping environments due to accessible price points and material variety. Metal powder materials represent the fastest-growing segment as aerospace and healthcare end users shift from prototyping to qualified production applications. PolyJet technology sustains premium positioning in dental and medical modeling where multi-material capability and fine feature detail command higher margins.
The FDA regulates patient-specific implants and surgical guides under its 3D printing medical device guidance, while FAA certification requirements govern flight-critical additive components in commercial aviation. OSHA standards for metal powder handling and respiratory protection shape facility investments and operational compliance across manufacturing sites. NIST measurement science programs influence process qualification protocols that determine which suppliers qualify for defense and medical contracts. Stakeholders must monitor evolving FAA airworthiness criteria and FDA quality system expectations as these frameworks increasingly determine market access rather than merely product safety.
Market Dynamics
ASTM F3301 qualification requirements for laser powder bed fusion are restructuring competitive positioning toward certified metal printing capabilities, forcing equipment vendors and service bureaus to rebuild process validation protocols around aerospace and medical device specifications.
Growth Catalysts
- FDA Patient-Specific Device Guidance:Evolving regulatory pathways for 3D-printed implants and surgical guides accelerate healthcare adoption across orthopedic and dental verticals.
- Flight-Critical Aerospace Qualification:FAA airworthiness certification frameworks enable production of structural engine components and fuel nozzles for commercial aviation programs.
- Texas Manufacturing Corridor Concentration:Dense clusters of automotive and energy equipment producers drive demand for metal tooling and replacement part production workflows.
Market Restraints
- Titanium Powder Supply Concentration:Limited qualified suppliers of aerospace-grade spherical powders create input cost volatility and allocation risk for metal printing operations.
- Post-Processing Bottlenecks:Heat treatment, surface finishing, and inspection requirements extend total production cycle times and erode throughput economics versus conventional machining.
- Substitution by Hybrid Manufacturing:CNC machining centers with additive deposition heads capture mid-complexity geometries at lower capital intensity than dedicated powder bed systems.
Strategic Opportunities
- Canada Defense Industrial Base:Underpenetrated military maintenance and spare part production programs offer entry points for qualified North American service providers.
- Multi-Material PolyJet Expansion:Dental laboratories and maxillofacial surgical planning centers adopt color-capable modeling for patient communication and preoperative simulation.
- California Bay Area Biotech Convergence:Tissue engineering and pharmaceutical tooling applications merge additive manufacturing with microfluidic fabrication techniques.
Industry Challenges
- Process Technician Scarcity:Qualified operators capable of parameter optimization, powder handling safety, and quality documentation remain scarce across industrial metal printing facilities.
- Qualification Timeline Compression:Aerospace and medical device customers demand concurrent material, process, and part certification, stretching engineering resources and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3D Printing Market |
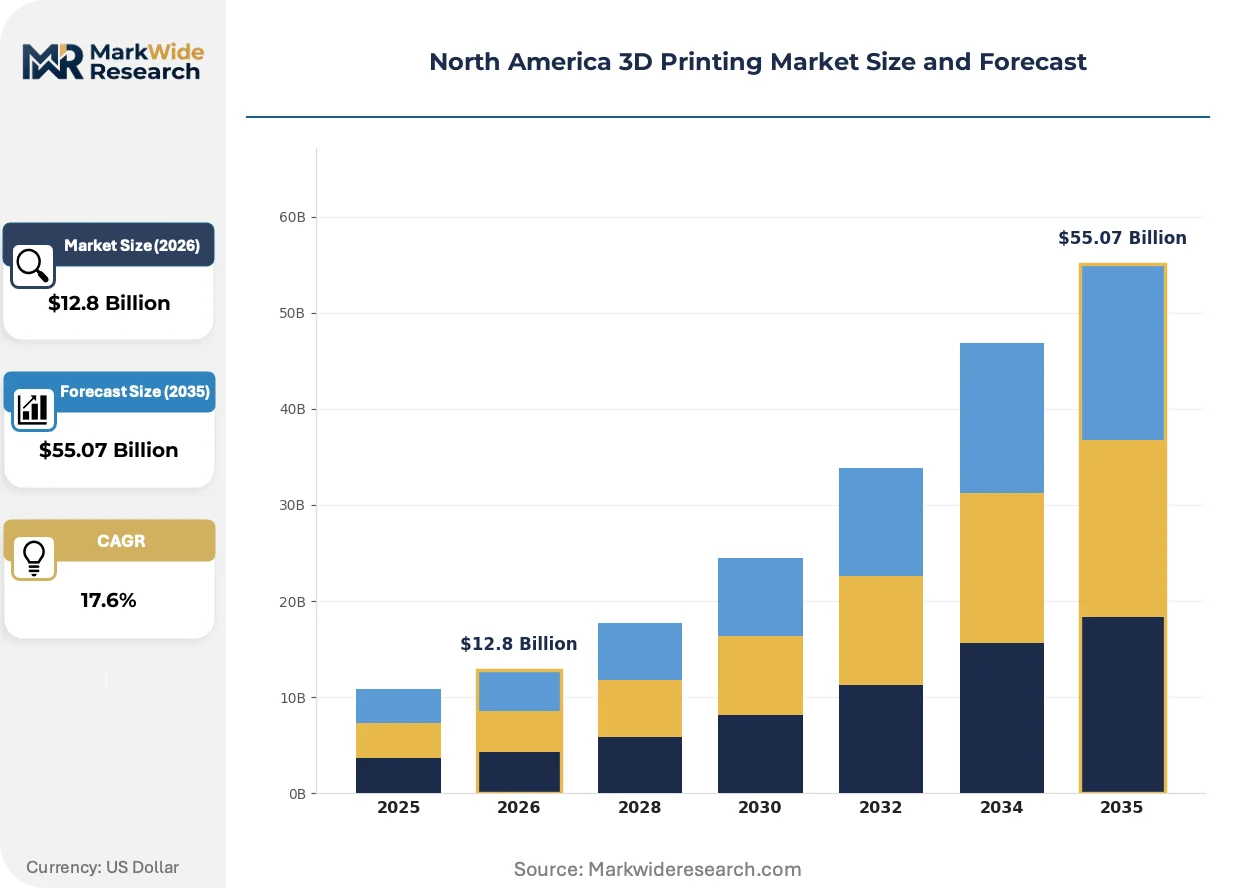
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $55.07 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FDM, SLA, SLS, PolyJet Material: Plastic, Metal, Ceramic, Composite End User: Aerospace, Healthcare, Automotive, Education Application: Prototyping, Tooling, Production, Customization |
| Companies Covered | Desktop Metal, Carbon, Stratasys, Protolabs, Formlabs, 3D Systems Corporation, Materialise, EOS, HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3D Printing Market Trends and Innovations
Process automation and in-situ monitoring systems are compressing the gap between prototype validation and qualified production, while regulatory frameworks mature to accommodate patient-specific and flight-critical applications.
Directed energy deposition systems with wire-fed metal delivery are miniaturizing for field repair and maritime maintenance applications. Shipyards and power generation operators deploy portable units for on-site shaft rebuilding and turbine blade restoration. This capability is miniaturizing the addressable market for conventional casting and forging suppliers serving heavy equipment aftermarket segments.
FAA airworthiness criteria for additive manufacturing are formalizing material pedigree and process control requirements for flight-critical aluminum and titanium components. Commercial aviation suppliers must demonstrate statistical process control across build chambers and thermal cycles. The narrow-body engine segment faces the steepest compliance burden as OEMs qualify printed fuel injectors and compressor stators.
Consolidated buying by hospital procurement networks is compressing vendor qualification cycles for surgical guides and anatomical models. Large health systems negotiate enterprise contracts spanning multiple facilities, displacing fragmented purchasing by individual surgeons and radiology departments. California's integrated delivery networks demonstrate the most aggressive supplier consolidation, favoring bureaus with FDA-registered quality systems and multi-site service coverage.
North America 3D Printing Market Segmentation
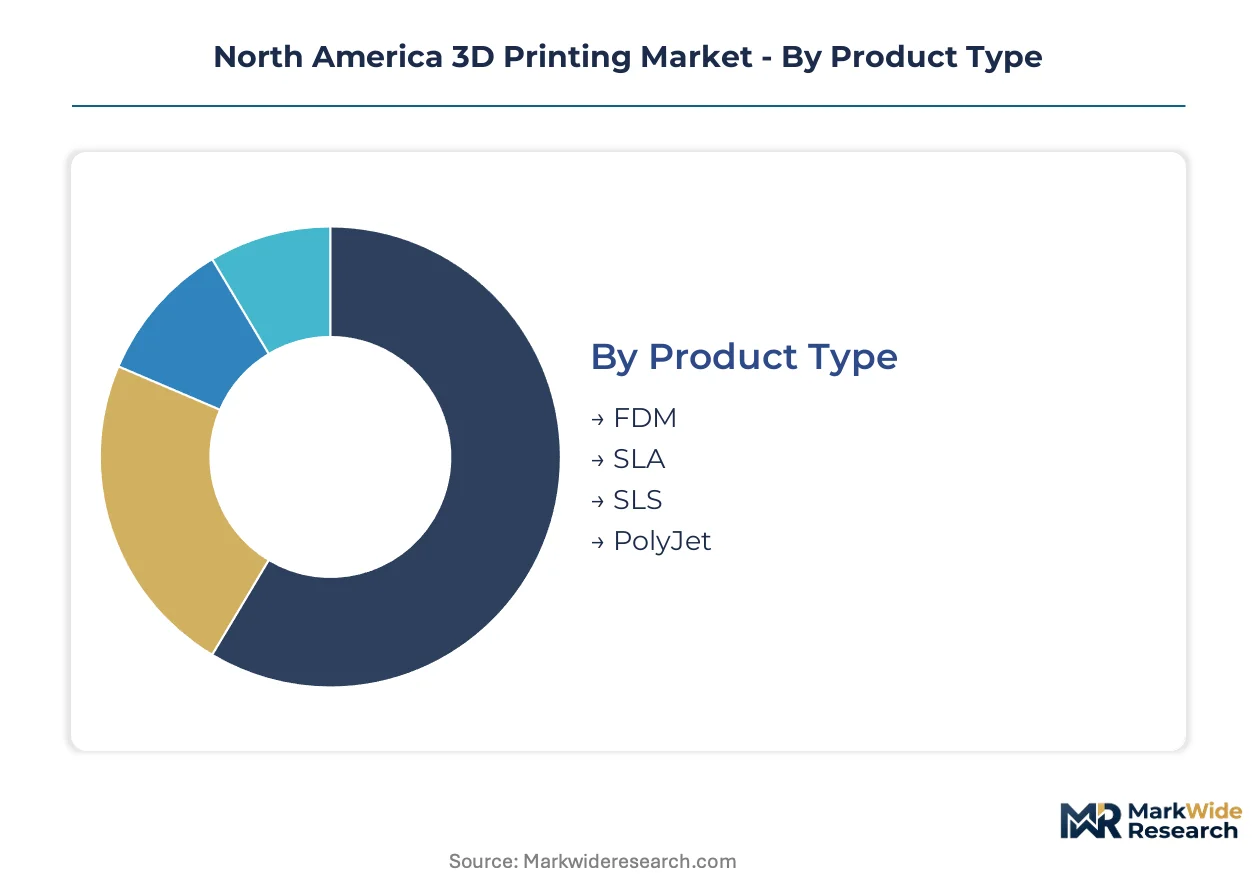
Segmentation in North American additive manufacturing reveals how technology selection maps directly to regulatory qualification requirements and production economics. Buyers choose systems based on material certification pathways, post-processing infrastructure, and end-use liability exposure rather than hardware specifications alone.
Product Type:
Substitution pressure from hybrid CNC-additive systems hits mid-range polymer technologies hardest, while certified metal platforms defend position through aerospace and medical lock-in.
- FDM:Fused deposition modeling extrudes thermoplastic filaments through heated nozzles, building parts layer-by-layer with build volumes ranging from desktop units to industrial-scale systems. Demand concentrates in Texas community colleges and California high school STEM programs where accessible price points and safe material handling dominate procurement criteria. FDM retains volume leadership; SLS holds the steepest expansion curve.
- SLA:Stereolithography cures liquid photopolymer resins with ultraviolet lasers, delivering surface finishes and dimensional tolerances required for dental aligner molds and investment casting patterns. Dental laboratories across Florida and New York State drive replacement cycles as multi-material capabilities displace older single-resin systems.
- SLS:Selective laser sintering fuses nylon and TPU powders without support structures, enabling complex geometries for functional prototypes and low-volume production end-use. Automotive suppliers in Michigan and Ohio deploy SLS for interior trim validation and ergonomic testing fixtures.
- PolyJet:PolyJet jetting deposits photocurable resins in multiple materials simultaneously, producing color-capable anatomical models and surgical planning guides with Shore hardness variation across single builds. Maxillofacial surgical centers in California's integrated delivery networks specify PolyJet for patient-specific preoperative visualization.
FDM retains volume leadership; SLS holds the steepest expansion curve.
Material:
Cost tier stratification separates qualified aerospace grades from commodity prototyping stocks, with powder metallurgy commanding premium positioning through scarcity of spherical titanium suppliers.
- Plastic:ABS, PLA, nylon, and photopolymer resins constitute the broadest material base, with bio-based PLA gaining traction in Colorado and Pacific Northwest educational institutions prioritizing sustainability procurement criteria. Plastic retains volume leadership; Metal holds the steepest expansion curve.
- Metal:Titanium, aluminum, stainless steel, and nickel superalloys require inert atmosphere processing and heat treatment protocols that limit qualified supplier pools. FAA airworthiness certification for laser powder bed fusion components drives specification tightening among Boeing and Airbus tier-one suppliers in Washington State and Kansas.
- Ceramic:Alumina, zirconia, and silicon nitride formulations serve high-temperature tooling and biomedical implant applications where biocompatibility and wear resistance outweigh brittleness constraints. Research hospitals in Massachusetts and Minnesota evaluate ceramic 3D printing for patient-specific dental crowns and orthopedic spacers.
- Composite:Carbon fiber-reinforced nylon and chopped fiber filaments deliver stiffness-to-weight ratios approaching continuous fiber layup at reduced capital intensity. Drone manufacturers and motorsports fabricators in North Carolina and Southern California adopt composite printing for non-structural aerodynamic components.
Plastic retains volume leadership; Metal holds the steepest expansion curve.
End User:
Application maturity diverges sharply: aerospace and healthcare operate under formal qualification regimes, while automotive and education purchase on capital efficiency metrics with shorter replacement cycles.
- Aerospace:Commercial aviation OEMs and defense contractors demand statistical process control documentation, material pedigree traceability, and destructive testing protocols for flight-critical printed components. GE Aviation's Alabama and Ohio facilities qualify printed fuel nozzles and compressor stators under FAA delegated authority.
- Healthcare:FDA-registered quality systems govern patient-specific implants, surgical guides, and anatomical models with biocompatibility testing and sterilization validation requirements. Hospital procurement networks in California and Texas consolidate vendor contracts, favoring bureaus with multi-site service coverage and ISO 13485 certification.
- Automotive:Tooling, jigs, and end-of-arm components dominate current adoption, with production part qualification progressing slowly due to liability exposure and cycle time economics. Tesla's Texas Gigafactory and legacy OEMs in Detroit deploy metal printing for stamping die inserts and assembly fixtures.
- Education:Universities, community colleges, and high school makerspaces prioritize equipment reliability, curriculum alignment, and safe material handling over production throughput. NSF-funded programs across the Midwest integrate additive manufacturing into mechanical engineering capstone sequences.
Education retains volume leadership; Healthcare holds the steepest expansion curve.
Application:
Geography shapes application mix: coastal technology corridors favor customization and production, while inland manufacturing belts concentrate prototyping and tooling workflows.
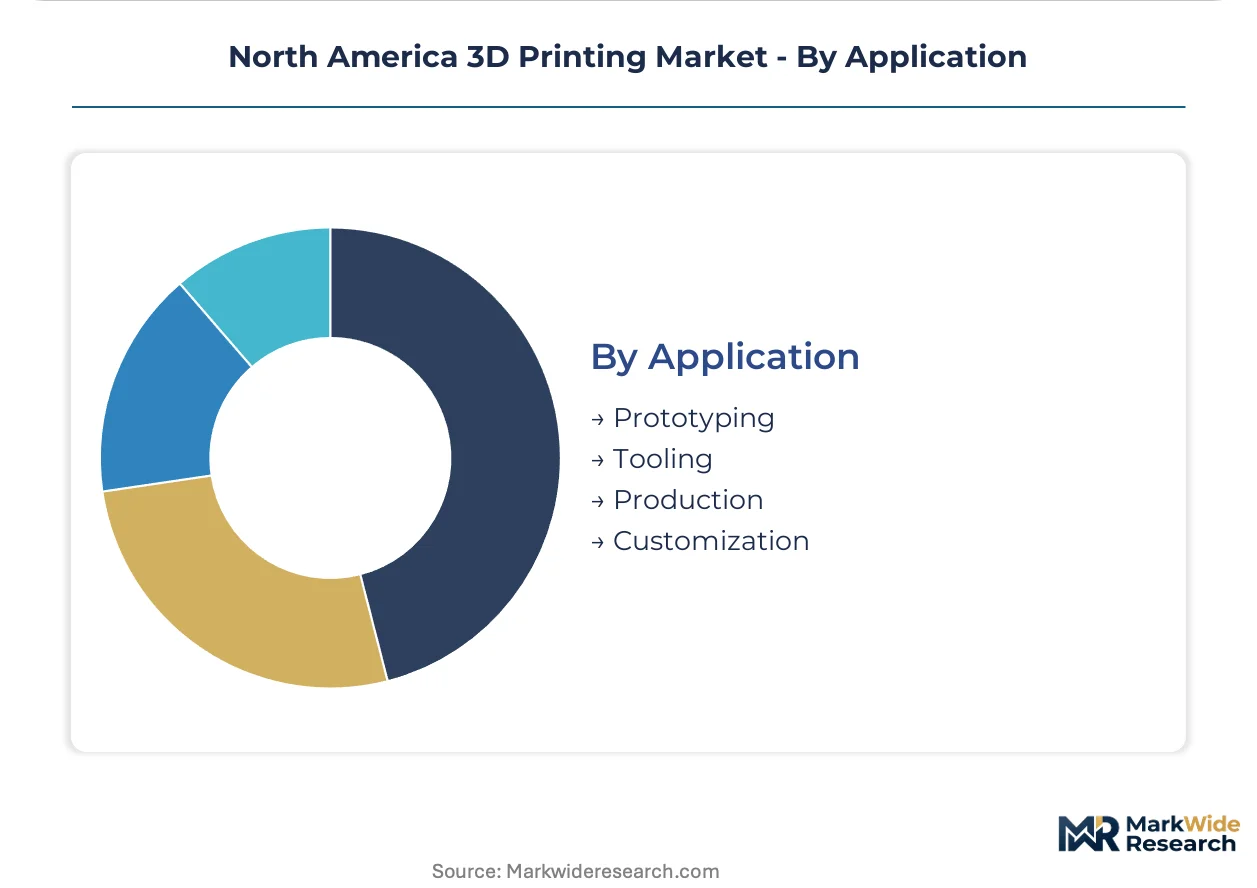
- Prototyping:Form, fit, and functional validation cycles compress product development timelines for consumer electronics and medical device startups. San Francisco Bay Area hardware accelerators and Austin venture studios maintain dense clusters of FDM and SLA capacity for iterative design refinement.
- Tooling:Conformal cooling channels, mold inserts, and assembly fixtures deliver lead time reductions and performance improvements over conventional machined tooling. Automotive stamping operations in Ohio and Indiana qualify printed die components for high-volume production runs.
- Production:Flight-critical engine components, patient-specific orthopedic implants, and satellite propulsion hardware transition from qualification to recurring revenue as regulatory frameworks mature. SpaceX's Texas and California facilities print SuperDraco engine chambers under FAA launch vehicle licensing.
- Customization:Patient-matched surgical guides, dental aligners, and prosthetic sockets leverage additive manufacturing's unit economics of one without tooling changeover costs. Atlanta and Chicago orthodontic practices adopt intraoral scanning-to-print workflows for same-day aligner fabrication.
Prototyping retains volume leadership; Production holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement incentives and state-level manufacturing tax credits are redistributing additive capacity across North American industrial corridors. The United States dominates installed base and qualification programs, while Canada and Mexico develop specialized roles in defense supply chains and nearshore production.
United States
Defense contracts and FAA airworthiness programs concentrate demand in Washington State aerospace clusters and Texas energy manufacturing corridors. The Department of Defense's additive manufacturing roadmap directs qualification funding toward metal printing for flight-critical components. California's Bay Area biotech convergence and Michigan automotive tooling hubs sustain dual demand vectors for medical device and industrial applications.
Canada
Underpenetrated defense industrial base programs offer entry points for qualified service providers serving Royal Canadian Navy and Air Force maintenance operations. Health Canada's evolving guidance on patient-specific devices aligns with FDA pathways, accelerating orthopedic implant adoption in Toronto and Montreal hospital networks. Quebec's aerospace supply chain in Montreal integrates printed tooling for Bombardier and Pratt & Whitney Canada programs.
Mexico
Automotive OEM nearshoring and medical device contract manufacturing drive demand in Baja California and Querétaro industrial parks. Mexico's federal manufacturing incentives support maquiladora adoption of polymer prototyping systems for consumer electronics and appliance tooling. Guadalajara's electronics cluster deploys additive manufacturing for rapid tooling in smartphone and medical device component production.
North America 3D Printing Market Competitive Landscape
Player mix skews toward diversified equipment vendors with established service bureau networks. Market structure concentrates around three tiers: integrated polymer-metal platforms, pure-play metal system specialists, and distributed manufacturing service providers. Dominant competitive moves include strategic partnerships between equipment vendors and aerospace qualification programs, plus geographic expansion of FDA-registered production facilities.
Among United States-based equipment vendors, Stratasys, Desktop Metal, and 3D Systems Corporation exemplify contrasting archetypes. Stratasys represents polymer platform breadth with extensive service coverage. Desktop Metal occupies the metal binder jet specialization vector targeting automotive tooling workflows. 3D Systems Corporation anchors diversified medical and industrial positioning. These three entities collectively illustrate how North American competitive positioning rotates around certification capabilities rather than hardware specifications alone.
| Leading Market Players |
|---|
| Desktop Metal |
| Carbon |
| Stratasys |
| Protolabs |
| Formlabs |
| 3D Systems Corporation |
| Materialise |
| EOS |
| HP Inc. |
| Others |
Pricing and Supply Chain Analysis
Wire-fed directed energy deposition displacing powder-bed systems for field repair applications redistributes supply geography toward portable equipment corridors while compressing pricing economics for conventional casting suppliers. This substitution dynamic simultaneously fragments titanium powder pricing power and elevates margins for qualified aerospace-grade spherical powder producers serving FAA certification programs.
Pricing Analysis
Certification level (FDA-grade, FAA airworthiness, ISO 13485) creates the primary spread across equipment and service tiers. Project-based pricing dominates qualified production workflows, with aerospace and medical device buyers paying premiums for material pedigree documentation and statistical process control. Cost compression in polymer prototyping tiers intensifies as hybrid CNC-additive systems capture mid-complexity geometries. Education and automotive tooling segments exhibit highest price sensitivity; aerospace OEMs and hospital procurement networks demonstrate lowest sensitivity due to liability exposure and qualification lock-in.
Supply Chain Analysis
Inventory lead times for aerospace-grade titanium powder extend production scheduling windows and amplify allocation risk during demand surges. Supply concentrates in the United States, Germany, and China for spherical powder production, with qualified suppliers drawing from Ukrainian and Russian sponge feedstock before geopolitical disruption. Powder metallurgy feedstock, inert gas processing equipment, and precision finishing services anchor cost structures. Single-source vulnerability pervades qualified powder suppliers holding FAA material specifications. Distribution runs through equipment vendor direct sales, certified service bureaus, and hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American additive manufacturing sits in early-cycle expansion as FAA airworthiness criteria formalize and FDA patient-specific pathways mature, with flight-critical and orthopedic applications crossing from qualification to recurring revenue.
For Market Incumbents: Consolidate position through captive titanium powder supply agreements and multi-site FDA-registered production facilities. Hybrid CNC-additive systems from DMG Mori and Mazak threaten dedicated powder-bed margins in automotive tooling. Defense contract qualification in Canada and Mexico offers channel control leverage against price erosion in saturated polymer prototyping tiers. For New Entrants and Emerging Players: FDA 510(k) fast-track for patient-specific surgical guides opens underpenetrated maxillofacial and orthopedic segments in California integrated delivery networks. Canada defense industrial base programs present accessible entry points with lower qualification barriers than FAA flight-critical tiers. Target hospital procurement networks with ISO 13485-certified service coverage and same-day digital workflow integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polymer service bureaus facing margin compression from hybrid manufacturing substitution. Five-to-ten year viability favors metal platform specialists with aerospace qualification lock-in and recurring production revenue. Watch FAA delegated authority expansion to additional tier-one suppliers as inflection signal for qualified production scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Aerospace Qualification Partnership | Stratasys and EOS secure Boeing tier-one supplier status under FAA delegated authority frameworks. |
| Backward Integration into Powder Supply | Desktop Metal acquires spherical titanium production capability to anchor automotive tooling cost structures. |
| Hospital System Enterprise Contract | Materialise negotiates multi-site California IDN coverage displacing fragmented surgeon-level purchasing. |
| Canada Defense Industrial Entry | Protolabs establishes Royal Canadian Navy maintenance program qualification for maritime shaft repair. |
| Multi-Material Dental Platform Launch | Formlabs releases color-capable PolyJet system for same-day aligner and surgical guide fabrication. |
Research Methodology
Desk research of FAA airworthiness directives, FDA 510(k) filings, and ASTM F3301 qualification protocols preceded structured interviews with aerospace procurement directors, hospital GPO contracts managers, and metal powder supply executives. Primary fieldwork across Washington State, Texas, and California manufacturing corridors triangulated against NIST measurement science publications and Department of Defense additive manufacturing roadmap disclosures. Bottom-up equipment shipment analysis and top-down end-use spending estimates were reconciled through iterative validation.
Variance decomposition across technology type, material grade, and end-use qualification tier shaped the analytical framework over the projection horizon. Modeled dimensions span product type (FDM, SLA, SLS, PolyJet, metal powder bed), material certification level, and application maturity (prototyping through flight-critical production). CAGRs were derived from segment-level adoption curves weighted by qualification timeline constraints. Forecast inputs incorporated FAA delegated authority expansion rates and FDA patient-specific device submission volumes.
Decision-makers should treat outputs as directional under sustained FAA certification timeline assumptions and stable titanium powder supply geography; material deviation in regulatory framework maturation or feedstock sourcing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
4D Printing Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
3D Printing Materials and Equipment Market